
 HIV Antivirals Market | 2026-2036
HIV Antivirals Market Size, Share, and Industry Trends Forecast 2026-2036
HIV Antivirals Market Foresight
Hospital outpatient care is consolidating as the dominant delivery setting for HIV antivirals, displacing traditional clinic-centric models. Gilead Sciences leverages its portfolio breadth across oral and long-acting formulations to sustain manufacturing scale advantages. ViiV Healthcare anchors its position through specialized focus on integrase inhibitor development and injectable innovation.
HIV antivirals comprise synthetic nucleoside and non-nucleoside analogs, protease inhibitors, and integrase strand transfer inhibitors formulated for oral, injectable, or topical delivery, with molecular targets selected to interrupt viral reverse transcription, protease cleavage, or genomic integration. These agents serve the primary commercial purpose of suppressing viral replication to undetectable levels, thereby preventing immunodeficiency progression and transmission. Integrase inhibitors command the strongest margin pool due to superior resistance profiles and fixed-dose combination versatility, while injectable administration routes represent the fastest-expanding segment as cabotegravir and rilpivirine long-acting formulations reduce dosing frequency from daily to monthly or quarterly intervals. Oral NRTIs remain the largest volume category but face gradual erosion as providers shift toward integrase-based first-line regimens with simpler side-effect profiles.
The FDA's antiretroviral guidance and the EMA's centralized marketing authorization procedures shape formulation standards and trial design requirements across developed markets, while WHO prequalification governs access pathways for low-income country procurement. The EU AI Act and GDPR impose emerging compliance obligations on digital adherence tools and patient data platforms that increasingly accompany drug delivery. Stakeholders must monitor how long-acting injectable uptake reshapes pharmacy benefit structures and whether biosimilar competition in oral NRTIs compresses pricing before patent cliffs accelerate.
Market Dynamics
Long-acting injectable regimens are restructuring HIV antiviral delivery economics, compressing pharmacy reimbursement cycles while expanding hospital outpatient capture rates through reduced dosing frequency.
Growth Catalysts
- FDA Streamlined Approval Pathways:Accelerated review mechanisms for antiretroviral therapies shorten development-to-commercialization timelines, incentivizing formulation innovation.
- Treatment-as-Prevention Programs:Expanded payer coverage for pre-exposure prophylaxis in the United States drives demand for preventive antiviral supply chains.
- Integrase Inhibitor Platforms:Superior resistance profiles and fixed-dose combination versatility pull prescribing behavior toward newer therapeutic classes.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of complex nucleoside analogs depends on specialized manufacturing clusters in India and China, creating supply vulnerability.
- Cold Chain Requirements:Long-acting injectable formulations require sustained temperature-controlled logistics, elevating distribution costs for rural and low-resource settings.
- Patent Thicket Complexity:Overlapping intellectual property on combination therapies extends exclusivity periods, delaying generic substitution in oral NRTI categories.
Strategic Opportunities
- Sub-Saharan Africa Procurement:WHO prequalification pathways for low-income country access create volume opportunities for manufacturers meeting centralized tender specifications.
- Digital Adherence Integration:EU AI Act and GDPR compliance frameworks enable patient data platforms that accompany drug delivery, opening service revenue streams.
- Topical Prevention Formulations:Microbicide development for receptive populations addresses underpenetrated prevention segments with distinct regulatory pathways.
Industry Challenges
- Specialized Formulation Talent:Long-acting depot technology requires expertise in polymer science and pharmacokinetic modeling that outstrips current workforce supply.
- EMA Centralized Authorization Timelines:Marketing authorization procedures for novel delivery mechanisms extend certification cycles, compressing effective patent life.
- Legacy Clinic Infrastructure:Traditional HIV care models resist transition to hospital outpatient settings, requiring retraining and facility investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HIV Antivirals Market |
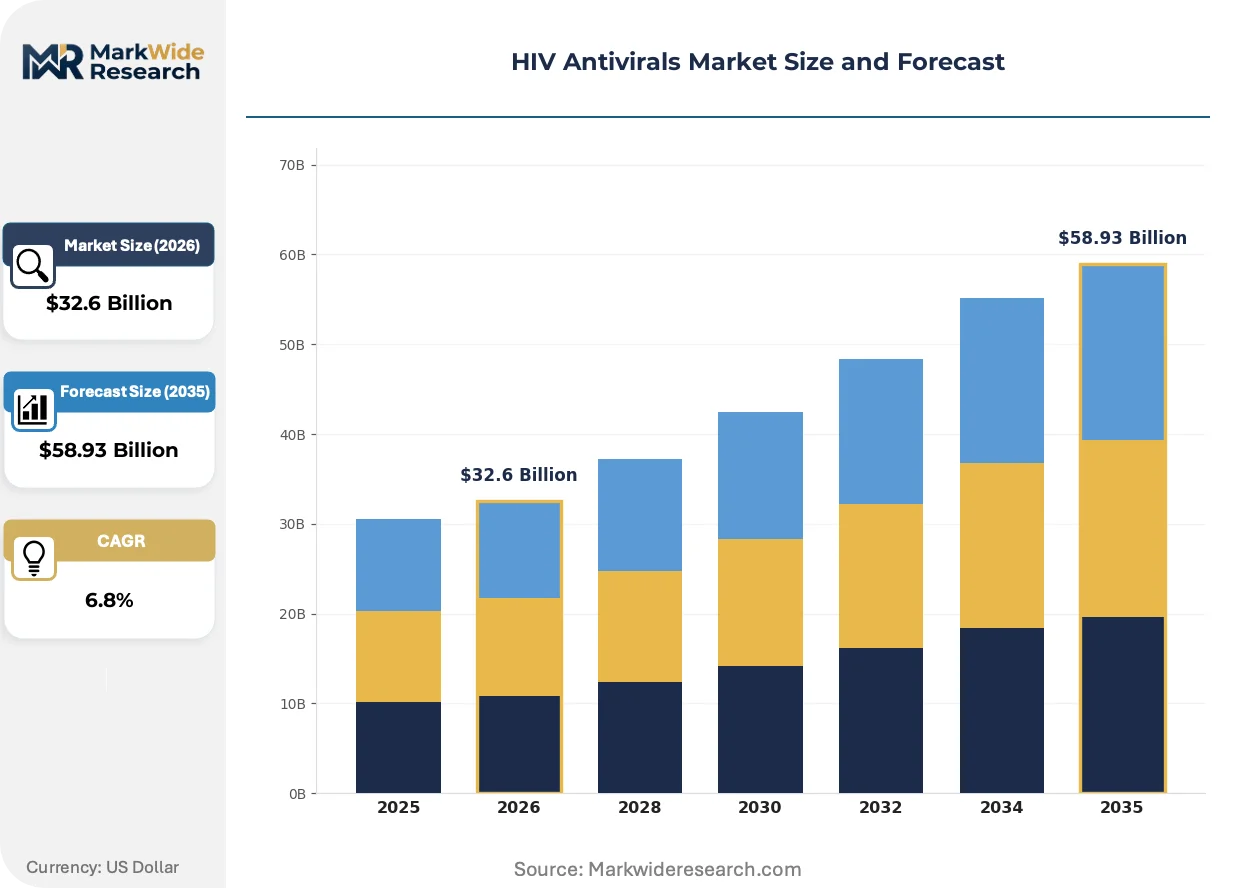
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $58.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NRTIs, NNRTIs, PIs, Integrase Inhibitors Administration Route: Oral, Injectable, Topical, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Patient Type: Adults, Pediatric, Pregnant Women, Geriatric |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Merck & Co., Johnson & Johnson, AbbVie, Bristol-Myers Squibb Company, Boehringer Ingelheim International GmbH, GSK plc, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HIV Antivirals Market Shifts & Advancements
Biopharmaceutical manufacturing and regulatory frameworks are converging to reshape how HIV antivirals reach patients, with formulation science and data governance emerging as decisive competitive variables.
Long-acting injectable technology is absorbing the market's innovation investment, with cabotegravir and rilpivirine depot formulations enabling monthly or quarterly administration that eliminates daily adherence barriers. Hospital outpatient departments are adopting these regimens fastest, displacing traditional clinic-based oral prescribing. The technology is absorbing pharmacy benefit structures as payers recalibrate reimbursement around administration events rather than prescription fills.
REACH and RoHS compliance requirements in the European Union are tightening excipient purity standards for antiretroviral manufacturing, forcing reformulation of legacy products. This regulatory pressure elevates costs for oral NRTI production while creating competitive advantage for manufacturers with advanced synthetic capabilities. Integrase inhibitor suppliers with EU manufacturing footprints are responding fastest, securing preferential tender positioning in European hospital systems.
Patient data platforms are accompanying antiviral delivery as adherence monitoring becomes a reimbursable care component. Pharmacy benefit managers are unbundling traditional dispensing margins to capture digital service fees, with the United States showing the most advanced channel transformation. This behavioral shift concentrates purchasing influence among integrated health systems capable of deploying combined pharmaceutical and data infrastructure.
HIV Antivirals Market Segmentation
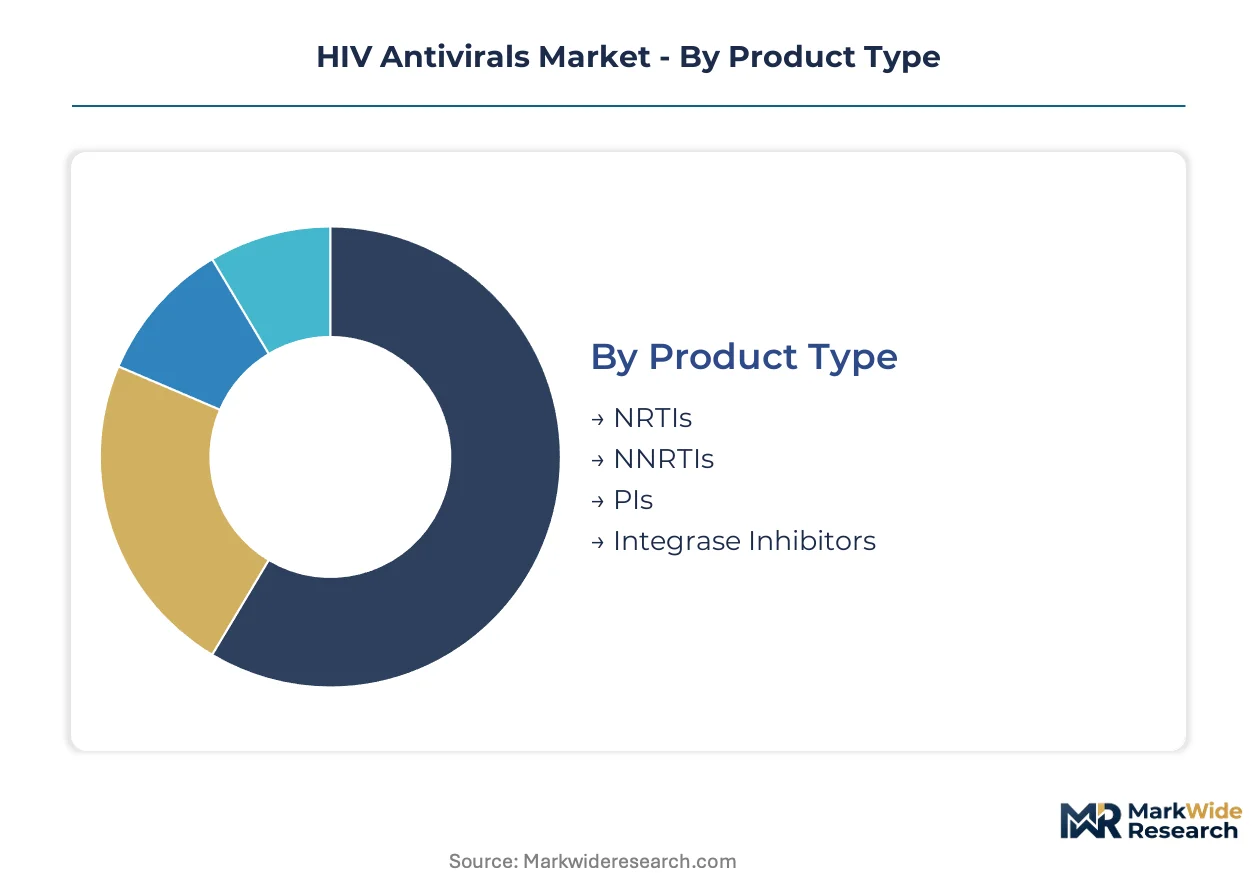
Segmentation in HIV antivirals reveals how formulation technology and delivery setting reshape prescribing economics. Product class and administration route determine margin structure, while end-user channel and patient type dictate access pathways and reimbursement design.
Product Type:
Prescribing behavior gravitates toward resistance profiles and combination versatility, with integrase inhibitors commanding premium positioning through superior viral suppression durability.
- Integrase Inhibitors:These agents block viral DNA integration into host genomes through strand transfer inhibition, enabling once-daily regimens with minimal metabolic side effects. Hospital outpatient departments in the United States favor these for treatment-naïve patients, driven by FDA streamlined approval pathways that accelerated fixed-dose combination launches.
- NRTIs:Nucleoside reverse transcriptase analogs terminate viral DNA chain elongation, forming the backbone of first-generation combination therapy. Volume concentrates in low-resource procurement through WHO prequalification, constrained by patent thicket complexity delaying generic substitution timelines.
- NNRTIs:Non-nucleoside reverse transcriptase inhibitors bind allosterically to viral polymerase, offering alternative resistance pathways for salvage therapy.
- PIs:Protease inhibitors cleave viral polyproteins through active-site competition, retaining niche utility in heavily pretreated populations with multi-class resistance.
Volume sits with NRTIs; growth tilts toward Integrase Inhibitors.
Administration Route:
Supply chain configuration and cold chain investment separate segments by distribution cost structure and patient adherence economics.
- Injectable:Long-acting depot formulations of cabotegravir and rilpivirine enable monthly or quarterly administration through polymer-matrix slow release. Hospital outpatient capture rates are expanding fastest in the United States as payers recalibrate reimbursement around administration events rather than prescription fills.
- Oral:Tablet and capsule formulations dominate current volume through established pharmacy benefit structures and ambient storage requirements. Clinics in Sub-Saharan Africa rely on oral NRTI combinations meeting WHO prequalification specifications, constrained by active pharmaceutical ingredient concentration in Indian and Chinese manufacturing clusters.
- Topical:Microbicide gels and rings deliver localized mucosal protection for receptive prevention populations.
- Inhalation:Aerosolized delivery remains investigational for pulmonary viral reservoir targeting.
Oral commands current volume; injectable climbs the fastest.
End User:
Facility infrastructure and reimbursement bundling determine channel economics, with integrated health systems consolidating purchasing influence.
- Hospitals:Outpatient departments absorb the fastest growth in long-acting injectable adoption, displacing traditional clinic-centric models through bundled reimbursement for administration services. United States health systems leverage pharmacy benefit manager partnerships to capture digital adherence monitoring fees alongside drug dispensing.
- Clinics:Legacy HIV care infrastructure resists transition to hospital settings, requiring retraining investment and facility modification. European clinic networks face REACH and RoHS compliance pressure on excipient purity standards, elevating reformulation costs for oral NRTI supply.
- Homecare:Self-administered oral regimens retain volume in stable, treatment-experienced populations.
- Pharmacies:Retail dispensing faces margin compression as administration shifts to institutional settings.
Volume sits with Clinics; growth tilts toward Hospitals.
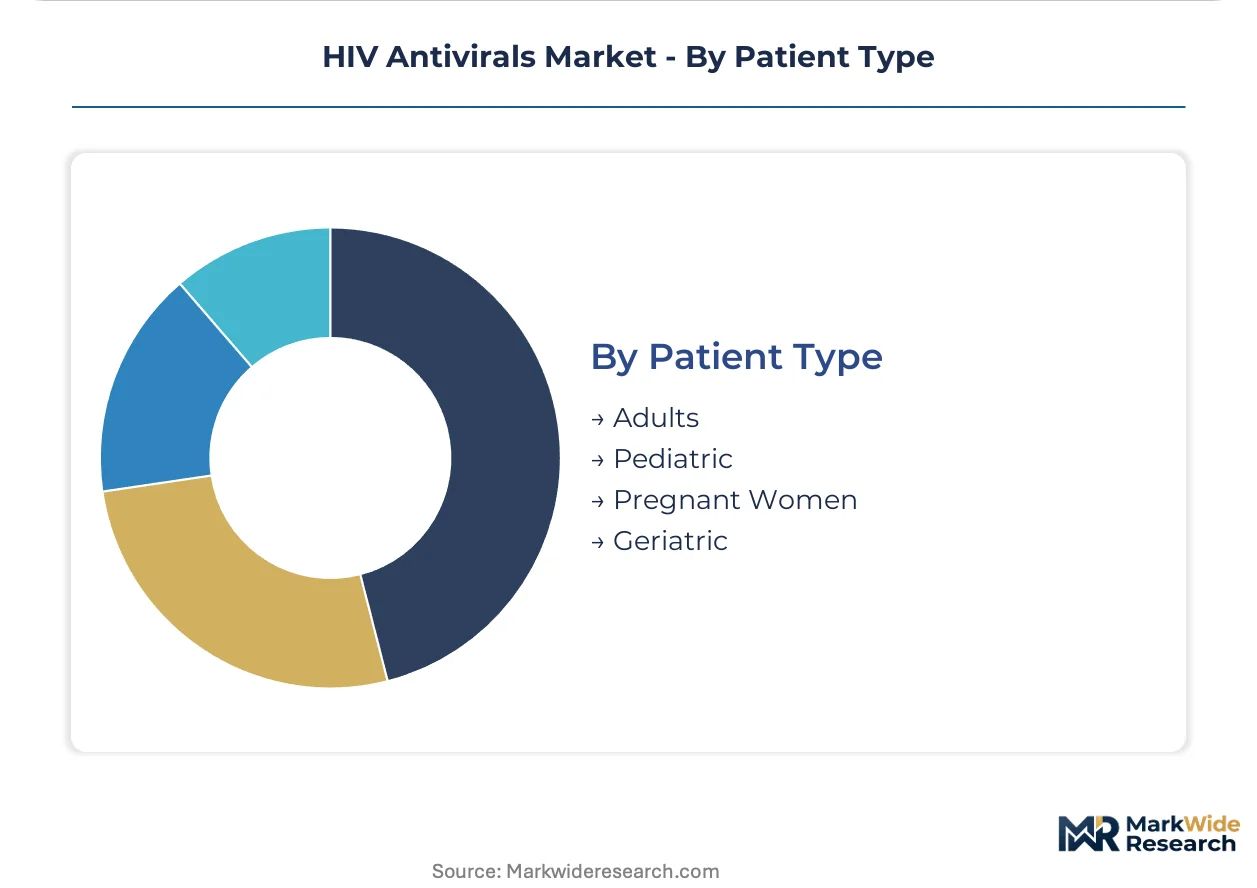
Patient Type:
Therapeutic indexing and safety profiling drive segment differentiation across life stages and physiological states.
- Adults:The core commercial population drives formulation innovation investment, with treatment-as-prevention programs expanding demand for pre-exposure prophylaxis supply chains. United States payer coverage broadening anchors volume concentration in this segment.
- Pediatric:Weight-based dosing requirements and palatability challenges necessitate distinct formulation development, with EMA centralized authorization timelines extending certification cycles for novel delivery mechanisms.
- Pregnant Women:Teratogenicity screening and placental transfer kinetics govern regimen selection for prevention of mother-to-child transmission.
- Geriatric:Polypharmacy interactions and renal function decline complicate dosing in aging HIV populations.
Volume sits with Adults; growth tilts toward Pediatric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and tax-advantaged manufacturing corridors in Ireland concentrate active pharmaceutical ingredient synthesis and finished-dose formulation for HIV antivirals. These zones attract investment through accelerated depreciation allowances and streamlined environmental clearances. Production gravity follows cost arbitrage in generic oral NRTIs and specialized capacity in long-acting injectables.
United States
FDA streamlined approval pathways for antiretroviral therapies compress development timelines, drawing formulation investment toward integrase inhibitor platforms. Payer coverage expansion for pre-exposure prophylaxis and treatment-as-prevention programs reshapes demand concentration in hospital outpatient settings. The Research Triangle Park corridor in North Carolina anchors clinical trial infrastructure and regulatory consulting clusters serving IND submissions.
Germany
EMA centralized marketing authorization procedures for novel delivery mechanisms extend certification cycles, compressing effective patent life for innovators. REACH and RoHS compliance requirements tighten excipient purity standards, elevating reformulation costs for legacy oral products. The Rhine-Main biopharma cluster around Frankfurt maintains specialized polymer science capabilities for long-acting depot formulation development.
India
WHO prequalification pathways for low-income country procurement create volume opportunities for manufacturers meeting centralized tender specifications. CDSCO manufacturing facility inspections govern export eligibility to regulated markets, with Hyderabad and Ahmedabad housing concentrated API synthesis clusters. The country's pharmaceutical special economic zones offer duty exemptions on imported equipment for antiretroviral production lines.
Switzerland
Swissmedic marketing authorization procedures align with EMA standards while offering parallel national pathways for early access programs. Basel anchors integrated health system headquarters with captive manufacturing capabilities and polymer science research institutes. The country's bilateral trade agreements with low-income countries facilitate preferential tariff treatment for exported antiretroviral finished doses.
Brazil
ANVISA sanitary surveillance requirements govern import licensing for patented antiretrovirals, with local production incentives through the Productive Development Partnerships program. São Paulo state concentrates hospital pharmacy procurement for the Unified Health System's HIV treatment distribution. The country's compulsory licensing framework creates pricing pressure on originator products while expanding generic substitution volumes.
HIV Antivirals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical companies commanding formulation innovation and regional generics houses absorbing oral NRTI volume. The vendor base concentrates around three strategic archetypes: large-cap innovators with polymer science capabilities, mid-tier specialists in fixed-dose combinations, and emerging-market manufacturers with API-to-finished-dose vertical integration. Competitive positioning hardens through M&A activity targeting long-acting depot technology assets and strategic partnerships for cold chain distribution in low-resource settings.
Within the large-cap innovator tier, Gilead Sciences and ViiV Healthcare exemplify portfolio breadth strategies spanning oral and injectable modalities, with the former representing manufacturing scale advantages and the latter anchoring specialized focus on integrase inhibitor development. Boehringer Ingelheim International GmbH occupies a position among European-based diversified pharmaceutical houses with historical antiretroviral franchises. These three entities collectively illustrate how regulatory relationship depth and polymer science investment separate premium positioning from commodity oral generic competition.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Merck & Co. |
| Johnson & Johnson |
| AbbVie |
| Bristol-Myers Squibb Company |
| Boehringer Ingelheim International GmbH |
| GSK plc |
| F. Hoffmann-La Roche Ltd |
| Others |
Supply & Pricing Matrix
Hospital outpatient procurement consolidation in the United States anchors pricing power for long-acting injectable regimens, compressing margins on oral NRTIs as integrated health systems extract volume discounts through bundled administration contracts.
Pricing Analysis
Lead-time-driven pricing separates hospital outpatient contracts from clinic spot procurement, with quarterly depot formulations commanding premium positioning against monthly alternatives. Three-tier pricing structure across innovator fixed-dose combinations, authorized generics, and commodity oral NRTIs stratifies by FDA approval tier and WHO prequalification status. Cost compression in oral NRTIs intensifies as Indian and Chinese API manufacturers expand capacity, while pediatric and salvage therapy segments show lowest price sensitivity due to limited therapeutic alternatives.
Supply Chain Analysis
WHO prequalification and FDA facility inspection status gate export eligibility for active pharmaceutical ingredient synthesis, concentrating production in Hyderabad and Ahmedabad clusters alongside specialized polymer science corridors in Basel and the Research Triangle Park. Nucleoside analog precursors and long-acting depot polymers draw from petrochemical feedstocks and specialized excipient suppliers, creating dependency on REACH-compliant European chemical houses. Single-source vulnerability runs through integrase inhibitor API manufacturing, while distribution feeds from captive manufacturing through hospital outpatient pharmacy networks and WHO centralized tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patent cliff acceleration in oral NRTIs is compressing viable economics for pure-play generic manufacturers, forcing asset divestitures and portfolio narrowing among sub-scale competitors.
For Market Incumbents: Lock in hospital outpatient formulary positioning through exclusive long-acting injectable supply agreements that bundle digital adherence monitoring services. Secure backward integration into polymer science capabilities via captive acquisition or joint development with specialized formulation houses, insulating against integrase inhibitor API supply disruption from Indian manufacturing clusters. For New Entrants and Emerging Players: Long-acting topical microbicide development offers the most penetrable white-space target, addressing underpenetrated prevention demand in Sub-Saharan African procurement channels. WHO prequalification pathway navigation provides the fastest go-to-market credentialing against originator pricing premiums in low-income country tenders. For Investors and Strategic Acquirers: The window for entry favors polymer science specialists with existing depot formulation expertise and regulatory submission track records across FDA and EMA pathways. Monitor long-acting injectable uptake rates in United States hospital outpatient settings as the inflection signal for pharmacy benefit structure permanence.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Injectable Manufacturing Scale-Up | Captures hospital outpatient volume concentration as dosing frequency shifts from daily to quarterly intervals. |
| Integrase Inhibitor Pipeline Diversification | Defends margin positioning against NRTI commoditization through resistance-profile superiority. |
| WHO Prequalification Pathway Investment | Unlocks Sub-Saharan African procurement volume through centralized tender eligibility. |
| Digital Adherence Platform Integration | Captures unbundled pharmacy benefit manager service fees alongside drug dispensing margins. |
| Cold Chain Distribution Partnership | Resolves rural and low-resource setting logistics constraints for temperature-sensitive depot formulations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. FDA approval databases, EMA centralized authorization records, ClinicalTrials.gov entries, and WHO prequalification listings supplied validation benchmarks. Bottom-up patient population modeling and top-down pharmaceutical expenditure reconciliation cross-checked volume and value estimates.
Data-stream reconciliation across treatment line, administration route, patient population, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate blending and patent expiry impact modeling. Forecast inputs incorporated long-acting injectable adoption curves in United States hospital systems and WHO tender volume specifications for low-income country access programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under compulsory licensing activation or API manufacturing cluster disruption scenarios. A model refresh is warranted upon material change in FDA streamlined approval pathway timelines or integrase inhibitor patent litigation resolutions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market