
 Global 3D Camera Market | 2026-2036
Global 3D Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Camera Market Analysis
ISO 13406 certification for machine vision components is unwinding the competitive field, favoring suppliers with validated optical pipelines. Sony Corporation leverages its CMOS sensor foundry dominance to control upstream supply for time-of-flight modules. Canon Inc. anchors professional cinema applications through proprietary dual-pixel autofocus architectures that extend into volumetric capture. Intel Corporation competes in embedded 3D vision with RealSense platforms that specialize in low-power depth sensing for robotics and logistics.
A 3D camera captures spatial depth information through multi-lens arrays or active illumination, typically resolving depth accuracy below one millimeter at ranges from ten centimeters to several meters for industrial metrology, autonomous navigation, and immersive content creation. Time-of-flight technology leads in mobile and automotive integration due to semiconductor miniaturization, while structured light dominates factory-floor inspection where sub-millimeter precision commands premium pricing. Stereo vision occupies the low-cost consumer tier, and laser scanning sustains margins in cultural heritage digitization and large-scale surveying where point-cloud density requirements exclude passive alternatives.
The FDA governs 3D imaging devices deployed in surgical navigation and dermatological screening in the United States, while the EU AI Act imposes conformity obligations on vision systems with automated decision-making capabilities in European markets. Japan's METI promotes JIS-standardized depth sensors through industrial automation subsidies, accelerating domestic adoption. Stakeholders must monitor how divergent electromagnetic emission limits across FCC, CE, and GB regimes fragment hardware certification burdens and reshape regional sourcing strategies.
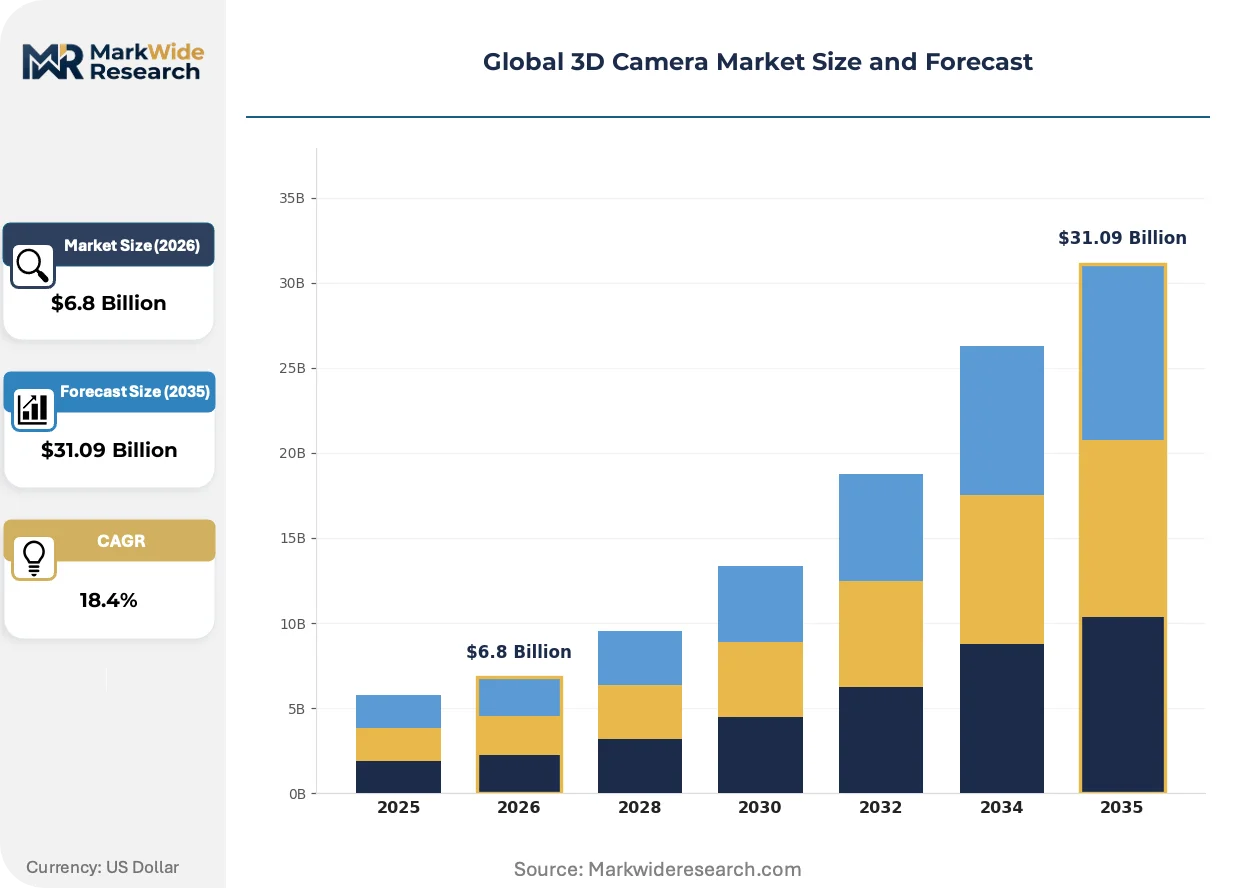
Market Dynamics
Time-of-flight semiconductor miniaturization is compressing module footprints below five cubic centimeters, collapsing the barrier between industrial metrology and consumer electronics while redrawing competitive boundaries across the entire depth-sensing value chain.
Growth Catalysts
- EU AI Act conformity pathways:Automated vision systems deployed in European manufacturing corridors now face mandatory algorithmic transparency documentation, accelerating replacement cycles for pre-2024 inspection hardware.
- Structured-light precision thresholds:Sub-millimeter factory-floor metrology requirements in Germany and Japan are expanding deployment of active-illumination arrays for automotive weld inspection and semiconductor packaging verification.
- China's manufacturing corridor concentration:Domestic OEMs in Shenzhen and Suzhou are integrating captive depth-sensing modules into automated assembly lines, creating localized demand clusters that bypass traditional import channels.
Market Restraints
- CMOS sensor supply concentration:Foundry capacity for specialized time-of-flight pixels remains captive to three East Asian semiconductor fabricators, exposing module assemblers to allocation volatility.
- GB electromagnetic emission ceilings:China's MIIT enforces stricter radiated-power limits than FCC or CE regimes, forcing hardware redesigns that fragment certification economies of scale.
- Stereo vision substitution in consumer tiers:Passive depth reconstruction using dual-lens smartphone arrays satisfies low-accuracy use cases without dedicated illumination hardware, compressing addressable volume at the price-sensitive base.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Subsidized capital expenditure for component assembly creates first-mover positioning for depth-module packaging operations serving South Asian industrial automation demand.
- Surgical navigation convergence:FDA-cleared time-of-flight devices are penetrating orthopedic implant alignment workflows, opening clinical reimbursement pathways previously reserved to CT-based navigation.
- Edge-AI coprocessor integration:Depth-sensing modules with on-chip neural inference are collapsing latency for autonomous mobile robots in logistics corridors, creating premium pricing tiers for real-time obstacle classification.
Industry Challenges
- ISO 13406 optical pipeline validation:Machine vision component certification requires documented traceability from lens coating through firmware calibration, extending qualification timelines for new supplier entrants.
- Multiphysics simulation talent scarcity:Design of active-illumination systems demands simultaneous optimization of thermal, optical, and electromagnetic behavior, with qualified engineers concentrated in German and Japanese industrial optics clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Camera Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DSLR, Mirrorless, Compact, Mobile Technology: Time-of-Flight, Stereo Vision, Structured Light, Laser Scanning Application: Gaming, Film Production, Virtual Reality, Industrial Inspection End User: Consumer Electronics, Manufacturing, Healthcare, Entertainment |
| Companies Covered | Sony Corporation, Canon Inc., Intel Corporation, Nikon Corporation, Panasonic Holdings Corporation, Samsung Electronics, Fujifilm Holdings Corporation, GoPro Inc., Faro Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Camera Market Emerging Trajectories
Active depth-sensing hardware is migrating from standalone peripherals to embedded subsystems, collapsing the traditional boundary between camera module and host device while redefining value capture across the supply chain.
Indirect time-of-flight pixel architectures are miniaturizing through backside-illuminated CMOS stacking, enabling sub-millimeter depth resolution in smartphone form factors. Automotive cabin-monitoring programs at German and Japanese OEMs are absorbing fifty-percent of foundry output for these specialized sensors. This compression is miniaturizing the addressable market for discrete industrial time-of-flight cameras below the two-hundred-dollar threshold.
Japan's METI is accelerating JIS-standardized depth sensor adoption through targeted industrial automation subsidies, mandating interoperability documentation for systems deployed in precision manufacturing. Domestic equipment builders must now certify calibration traceability to national measurement institutes. Small and mid-size factory operators in Nagoya and Osaka industrial belts are delaying procurement decisions pending clarity on subsidy eligibility windows.
Chinese contract manufacturers are consolidating depth-module sourcing through direct foundry relationships, bypassing traditional distributor channels that previously handled technical specification translation. Tier-one electronics assemblers in the Pearl River Delta now specify optical parameters directly with semiconductor fabricators. This disintermediation is compressing margin pools for European and Japanese component distributors serving Asian manufacturing demand.
Global 3D Camera Market Segmentation
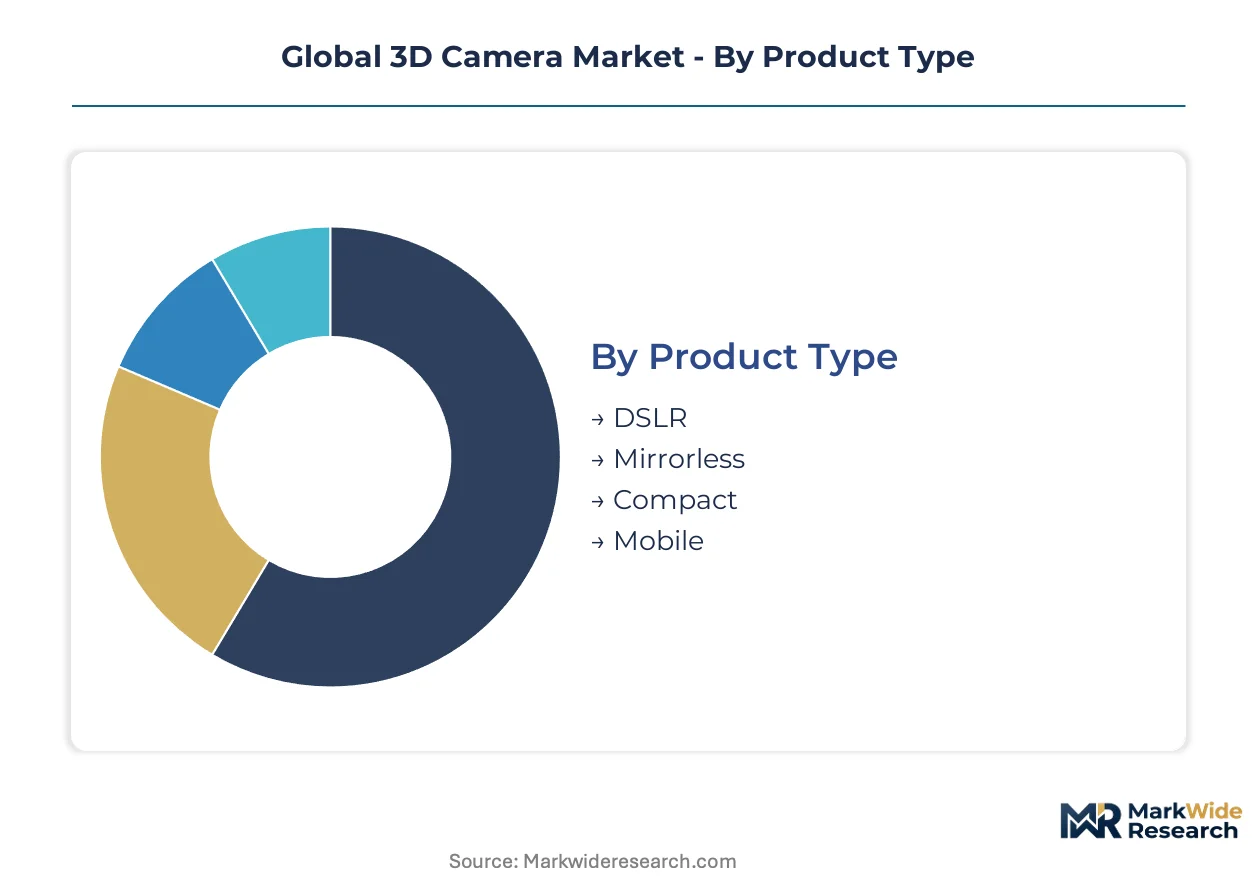
Technology differentiation and application-specific precision requirements fragment the 3D camera landscape into discrete performance tiers. Each segment carries distinct certification burdens and supply chain configurations that reshape competitive boundaries.
Product Type:
Mobile form factors face the most severe substitution pressure from computational depth reconstruction using standard dual-lens arrays.
- DSLR:Full-frame and APS-C sensor architectures with dedicated depth-sensing modules for professional volumetric capture workflows. Cinema production houses in Los Angeles and Mumbai deploy these systems for virtual production stages where real-time depth compositing replaces green-screen infrastructure.
- Mirrorless:Compact interchangeable-lens bodies with integrated time-of-flight or structured-light modules for hybrid photo-video creators. YouTube production studios and independent documentary filmmakers in Berlin and Tokyo favor these systems for portability without sacrificing depth resolution.
- Compact:Fixed-lens consumer devices with basic stereo depth capabilities for casual content creation.
- Mobile:Smartphone-embedded modules using indirect time-of-flight or dual-pixel phase detection for portrait effects and AR applications.
Mobile anchors the volume base while mirrorless gains share at the steepest rate.
Technology:
Cost tier stratification separates premium active-illumination systems from commodity passive alternatives.
- Time-of-Flight:Direct and indirect modulation schemes measuring photon travel time to resolve depth maps at frame rates exceeding 60fps. Automotive cabin-monitoring programs at German and Japanese OEMs absorb substantial foundry output for these specialized sensors, compressing availability for industrial applications.
- Structured Light:Projected pattern deformation analysis achieving sub-millimeter accuracy for factory-floor metrology. Semiconductor packaging verification lines in Dresden and Osaka mandate these systems for wire-bond inspection where defect tolerance falls below 50 microns.
- Stereo Vision:Passive triangulation using dual-camera arrays without active illumination for cost-sensitive consumer applications.
- Laser Scanning:Mechanical beam steering for high-density point-cloud generation in cultural heritage digitization and large-scale surveying.
Structured light commands the premium tier while time-of-flight scales fastest into automotive and mobile integration.
Application:
Customer type divergence separates enterprise procurement with extended validation cycles from consumer purchase patterns.
- Industrial Inspection:Automated quality assurance systems for weld verification, dimensional tolerance checking, and surface defect detection. Automotive suppliers in Stuttgart and Toyota City expand deployment of active-illumination arrays as EU AI Act conformity requirements accelerate hardware replacement cycles.
- Virtual Reality:Inside-out tracking and mixed-reality passthrough for headset-mounted spatial mapping. Meta and Apple hardware roadmaps drive consolidation around specific depth-sensing specifications that freeze out smaller module vendors.
- Gaming:Depth-based motion control and volumetric player scanning for immersive interaction.
- Film Production:Virtual set extension and real-time depth compositing for streaming content creation.
Industrial inspection generates the steadiest revenue stream while virtual reality application climbs the fastest.
End User:
Geographic concentration of manufacturing activity determines sourcing patterns and certification requirements.
- Manufacturing:Automated assembly line integration for robotic guidance and quality verification. Shenzhen and Suzhou corridor OEMs specify depth modules directly with semiconductor fabricators, bypassing traditional distributor channels.
- Healthcare:FDA-cleared surgical navigation and dermatological screening devices requiring electromagnetic emission compliance across FCC, CE, and GB regimes. Orthopedic implant alignment workflows in US hospital systems open clinical reimbursement pathways previously reserved to CT-based navigation.
- Consumer Electronics:Smartphone, tablet, and peripheral integration for photography and AR applications.
- Entertainment:Theme park attractions, live event volumetric capture, and streaming content production.
Manufacturing dominates current procurement volume while healthcare end use expands most quickly through regulatory clearance pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation buyers cluster in German automotive corridors, Chinese electronics manufacturing belts, and Japanese precision machinery hubs, with healthcare procurement expanding fastest in US hospital systems.
United States
FDA-cleared surgical navigation devices are penetrating orthopedic implant alignment workflows, creating clinical reimbursement pathways previously reserved to CT-based systems. FCC electromagnetic emission standards govern hardware certification for medical and industrial deployments. Boston and Minneapolis medical device clusters host validation laboratories accelerating time-to-market for depth-sensing surgical tools.
Germany
Automotive suppliers in Stuttgart expand active-illumination arrays for weld verification as EU AI Act conformity requirements accelerate hardware replacement cycles. CE marking and REACH compliance impose documented traceability obligations on vision system component sourcing. Dresden semiconductor packaging verification lines mandate structured-light systems for wire-bond inspection below 50-micron defect tolerance.
China
Shenzhen and Suzhou corridor OEMs specify depth modules directly with semiconductor fabricators, bypassing traditional distributor channels. MIIT enforces stricter GB electromagnetic emission ceilings than FCC or CE regimes, forcing hardware redesigns that fragment certification economies. Pearl River Delta contract manufacturers consolidate sourcing through direct foundry relationships, compressing margin pools for European and Japanese distributors.
Japan
METI accelerates JIS-standardized depth sensor adoption through targeted industrial automation subsidies, mandating interoperability documentation for precision manufacturing systems. Nagoya and Osaka industrial belt operators delay procurement decisions pending clarity on subsidy eligibility windows. Domestic equipment builders must now certify calibration traceability to national measurement institutes.
India
PLI scheme subsidies for electronics manufacturing create first-mover positioning for depth-module packaging operations serving South Asian industrial automation demand. BIS certification requirements for machine vision components extend qualification timelines for new supplier entrants. Karnataka and Tamil Nadu electronics manufacturing clusters attract component assembly investments targeting industrial robotics integration.
Global 3D Camera Market Vendor Landscape
Player mix skews toward diversified electronics conglomerates with captive semiconductor fabrication, tiered against specialized industrial metrology vendors and emerging contract manufacturers. The competitive field separates into three strategic archetypes: sensor foundry operators controlling upstream pixel supply, system integrators bundling depth modules with software platforms, and precision optics specialists serving sub-millimeter metrology niches. Dominant competitive moves include backward integration into specialized CMOS fabrication and geographic expansion through direct foundry relationships in Asian manufacturing corridors.
Among diversified electronics conglomerates, Sony Corporation exemplifies the sensor foundry archetype through its CMOS fabrication dominance, while Canon Inc. occupies a position in professional imaging systems. Intel Corporation sits within the embedded vision tier, representing the platform-integrator model for robotics and logistics applications.
| Leading Market Players |
|---|
| Sony Corporation |
| Canon Inc. |
| Intel Corporation |
| Nikon Corporation |
| Panasonic Holdings Corporation |
| Samsung Electronics |
| Fujifilm Holdings Corporation |
| GoPro Inc. |
| Faro Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for specialized time-of-flight CMOS sensors concentrate pricing power with East Asian foundry operators while forcing module assemblers into long-term offtake commitments that lock in cost structures. This inventory exposure cascades downstream, compressing margins for European and Japanese distributors caught between fixed contract terms and spot-market volatility in optical component procurement.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate upstream transactions between foundry operators and module assemblers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13406-certified industrial metrology systems from consumer-grade stereo vision modules. Pricing pressure stems from Chinese OEMs consolidating direct foundry relationships that bypass traditional distributor markups. Consumer electronics buyers exhibit highest price sensitivity, while healthcare procurement teams prioritize FDA clearance over unit cost.
Supply Chain Analysis
Tsushima Strait transit underwrites critical shipments of specialized CMOS sensors from South Korean and Japanese fabrication facilities to module assembly plants in China and Vietnam. The supply chain draws from germanium substrates for infrared illumination, precision glass optics from Germany, and rare-earth phosphors for structured-light projectors. Single-source vulnerability concentrates in backside-illuminated CMOS stacking capacity held by three East Asian fabricators. Distribution runs through direct foundry relationships in the Pearl River Delta, displacing European and Japanese component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory compliance tiers creates niche positioning opportunities as EU AI Act documentation requirements split the addressable market between validated and non-validated vision system suppliers.
For Market Incumbents: Secure captive foundry allocation through equity partnerships or prepayment structures to insulate against CMOS sensor allocation volatility. Invest in ISO 13406 certification pipelines to defend premium positioning against emerging contract manufacturers in India and Vietnam. Backward integration into lens coating and calibration firmware extends qualification timelines that freeze out new entrants. For New Entrants and Emerging Players: Differentiate on JIS-standardized interoperability documentation to capture delayed procurement decisions in Japan's Nagoya and Osaka industrial belts. Target India's PLI-subsidized electronics manufacturing clusters for depth-module packaging operations serving South Asian industrial automation demand. Lead with edge-AI coprocessor integration as the go-to-market angle for autonomous mobile robot deployments in logistics corridors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underutilized CMOS sensor fabrication lines and stranded industrial optics portfolios. Long-term viability hinges on regulatory compliance capabilities rather than pure technology differentiation. Monitor FDA 510(k) clearance velocity for time-of-flight surgical navigation devices as the inflection signal for clinical reimbursement pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CMOS Fabrication | Sony Corporation's captive sensor foundry secures allocation priority during supply crunches. |
| ISO 13406 Certification Investment | Documented optical pipeline validation extends qualification timelines that protect premium positioning. |
| Direct Foundry Relationship Establishment | Shenzhen OEMs bypass distributor markups by specifying parameters directly with semiconductor fabricators. |
| Edge-AI Coprocessor Integration | On-chip neural inference collapses latency for real-time obstacle classification in logistics robotics. |
| JIS Standardization Compliance | METI subsidy eligibility mandates interoperability documentation for precision manufacturing systems. |
Methodological Framework
A spread of perspectives from industrial automation procurement directors, machine vision system integrators, semiconductor foundry account managers, and regulatory compliance officers converged on the working assumptions. Primary interview insights combined with secondary validation from SEC 10-K filings, EU AI Act implementation guidance, JIS standard documentation, and customs trade data for optical component flows. Bottom-up module shipment estimates triangulated against top-down manufacturing automation capex forecasts.
Segmentation dimensions modeled span technology type, product form factor, application vertical, end-user industry, and geographic regulatory cluster across the analysis window. CAGRs derived from fitted growth curves applied to validated baseline volumes, with cross-checks against foundry capacity expansion announcements and OEM integration roadmaps. Forecast inputs incorporated EU AI Act hardware replacement cycle assumptions and METI subsidy eligibility window clarity.
Forecasts assume regulatory continuity in FDA, CE marking, and GB electromagnetic emission regimes; material policy shifts would require re-modeling supply chain certification burdens. Practitioners should keep alternative scenarios live as divergence between FCC, CE, and GB emission limits evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Electron Microscopy Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Pico Projector Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Webcam Market
Imaging
Image Intensifier Market
Imaging
Global Pathology Imaging Systems Market
Imaging
Digital Image Processing Market
Imaging
SWIR Camera Market
Imaging
Holotomographic Imaging Market
Imaging
Camcorder Market
Imaging
Vision Processing Unit Market
Imaging
Global Digital Photography Market
Imaging
Photography Equipment Market
Imaging
Brazil Surveillance Analog Camera Market