
 Digital Movie Cameras Market | 2026-2036
Digital Movie Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Movie Cameras Market Analysis
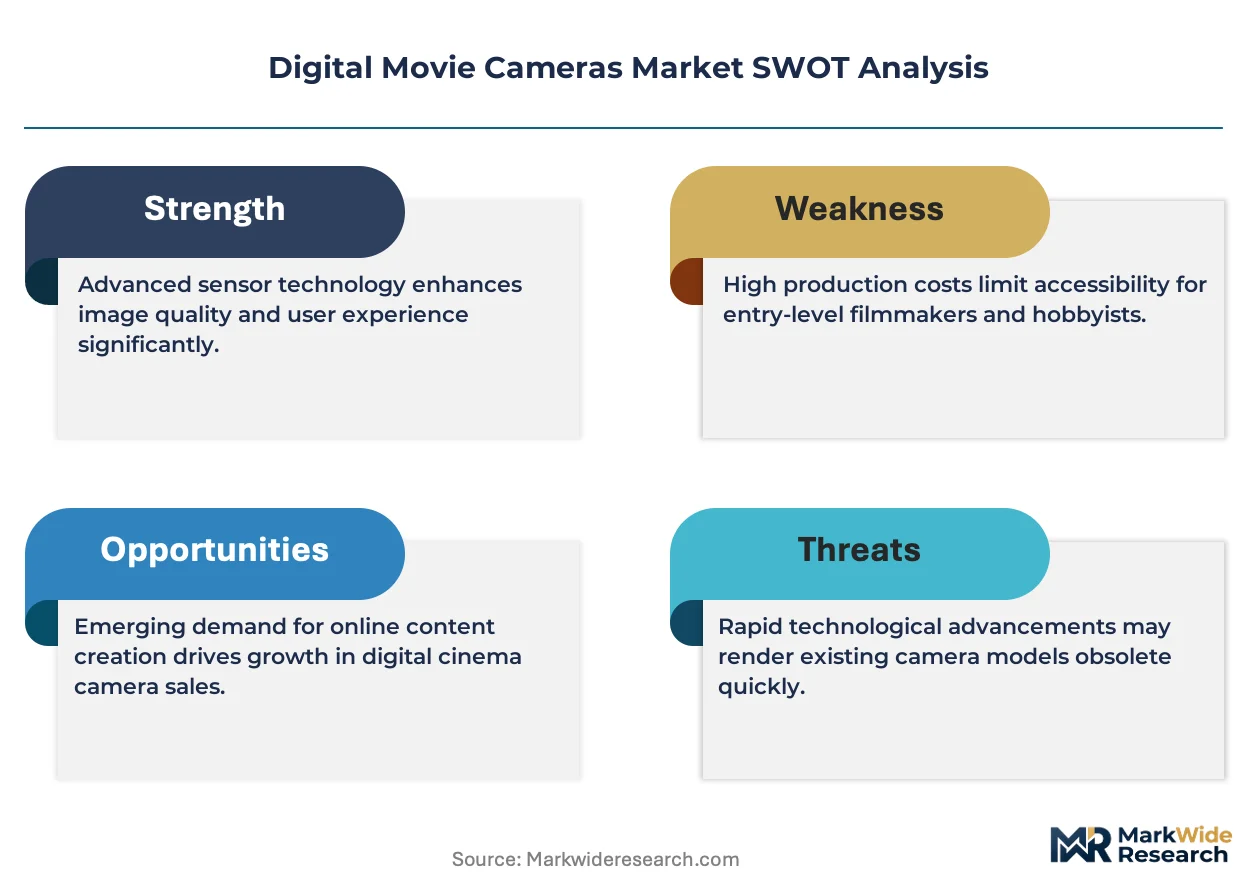
Modular sensor-and-body configurations is expanding buyer flexibility across rental houses and owner-operators. ARRI AG leverages its Munich engineering base to sustain dominance in large-format cinematography. RED Digital Cinema differentiates through proprietary RAW compression codecs. Blackmagic Design competes aggressively on price-performance for entry-level cinema workflows.
Digital movie cameras are professional electronic imaging systems that capture motion pictures using digital image sensors, typically employing Super 35 or full-frame formats with 14+ stops of dynamic range, designed for theatrical exhibition and broadcast distribution. Mirrorless systems are displacing traditional camcorders in documentary and commercial applications due to compact form factors and lens adaptability. 8K capture technology leads capital investment among rental fleet operators, while 4K remains the volume standard for corporate and training content production. Action camera segments occupy a narrow niche within narrative filmmaking, primarily serving stunt and POV sequences.
CE marking requirements under the EU Radio Equipment Directive shape product access for manufacturers selling into European production markets. The FCC's equipment authorization process governs electromagnetic compliance for cameras distributed in the United States. Japan's METI energy efficiency standards influence power management design in battery-operated cinema rigs. Stakeholders must monitor how sustainability disclosure mandates in Europe and Asia-Pacific alter component sourcing and product lifecycle obligations.
Market Dynamics
Streaming platforms are compressing production timelines and forcing rental houses to refresh sensor formats faster than traditional theatrical release cycles allowed. This acceleration is fragmenting procurement patterns between owner-operators and fleet-based rental providers.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandates material disclosure for electronic imaging devices, creating competitive differentiation for manufacturers with transparent supply chains.
- Independent production houses:These buyers are expanding professional-grade equipment procurement as direct-to-streaming distribution bypasses traditional studio gatekeepers.
- Large-format cinematography:Super 35 and full-frame sensor configurations are pulling demand from documentary and commercial segments into narrative production workflows.
Market Restraints
- Image sensor supply concentration:Advanced CMOS fabrication clusters in East Asia create vulnerability to geopolitical trade friction and capacity constraints.
- Battery chemistry cost volatility:Lithium-ion cell prices fluctuate with raw material markets, squeezing margins on portable cinema rigs.
- Compression codec licensing:Proprietary RAW formats lock rental houses into vendor-specific post-production pipelines, raising total cost of ownership.
Strategic Opportunities
- 8K capture infrastructure:Rental fleet operators in Germany and Japan are building premium tier inventory ahead of theatrical exhibition upgrades.
- Mirrorless form factor convergence:Compact systems are opening documentary and commercial applications previously served by dedicated camcorders.
- India's production incentive schemes:State-level film subsidies are attracting location shoots and driving localized equipment procurement.
Industry Challenges
- Digital imaging technician certification:The specialized skill set for HDR workflow and color science is scarce in secondary production markets.
- Legacy lens mount compatibility:Rental houses face inventory write-downs as PL-mount glass requires adapter solutions for mirrorless bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Movie Cameras Market |
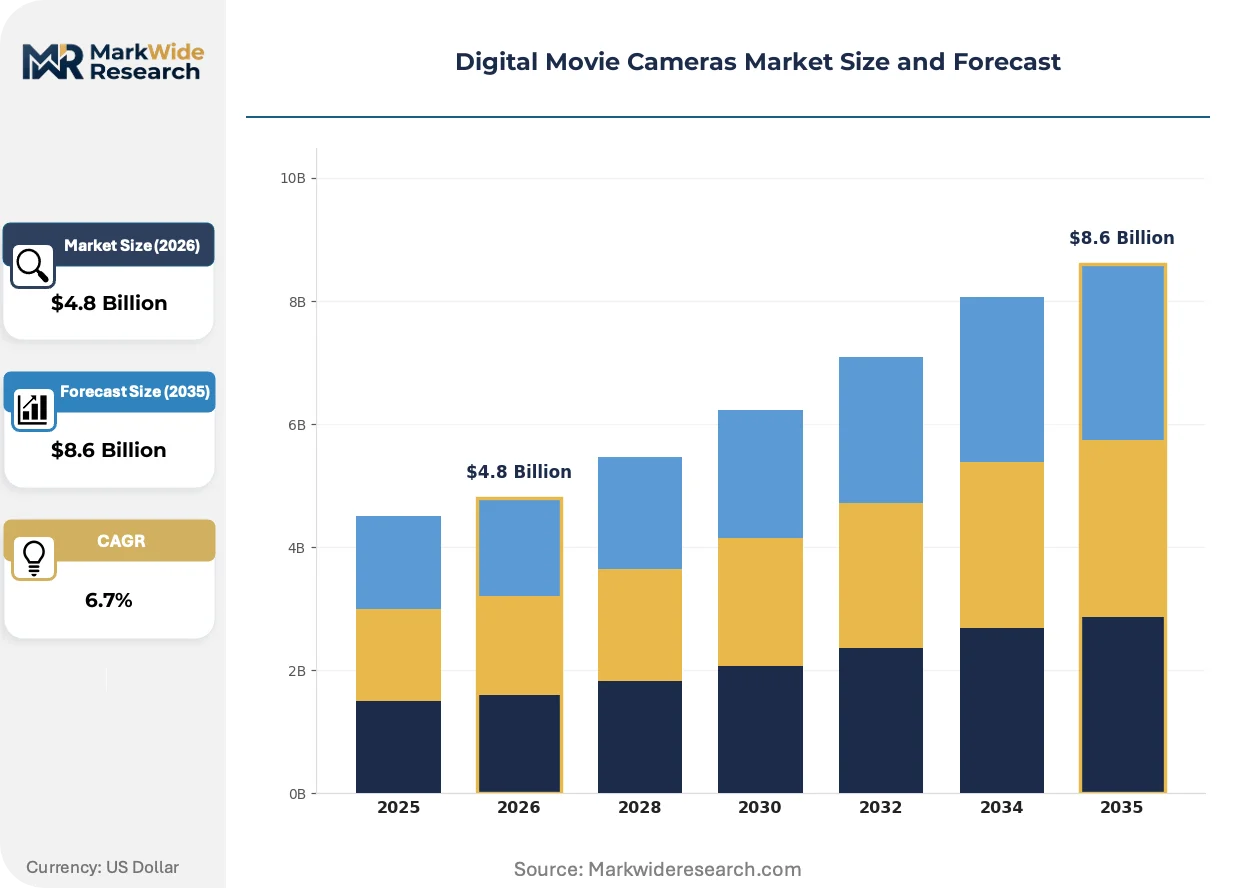
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DSLR, Mirrorless, Camcorder, Action Camera Technology: 4K, 8K, Digital, Analog End User: Filmmakers, YouTubers, Educators, Corporate Application: Documentary, Narrative, Commercial, Training |
| Companies Covered | Sony Group Corporation, Canon, Inc., Panasonic Holdings Corporation, ARRI AG, RED Digital Cinema, LLC, Blackmagic Design Pty. Ltd., Nikon Corporation, JVCKENWOOD Corporation, Vision Research, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Movie Cameras Market Emerging Trajectories
Computational imaging and cloud-native workflows are compressing the distance between capture and post-production. These shifts are redistributing value from hardware manufacturers toward software-integrated platform providers.
Computational photography pipelines are consolidating signal processing functions previously handled by discrete hardware modules. Major rental houses in Los Angeles and London are adopting these systems to reduce on-set equipment footprint. The technology is consolidating color grading and noise reduction into camera-native firmware, displacing external recorder boxes.
The EU's Ecodesign for Sustainable Products Regulation is mandating lifecycle disclosure for electronic imaging equipment sold into member states. Manufacturers must now document carbon intensity and material composition across supply chains. German engineering clusters are responding by redesigning thermal management systems to meet stricter efficiency benchmarks.
Short-term rental marketplaces are fragmenting traditional fleet procurement among owner-operators. Peer-to-peer equipment sharing platforms in California and Maharashtra are connecting underutilized camera bodies with independent productions. This behavioral shift is compressing rental house pricing power in mid-tier cinematography segments.
Digital Movie Cameras Market Segmentation
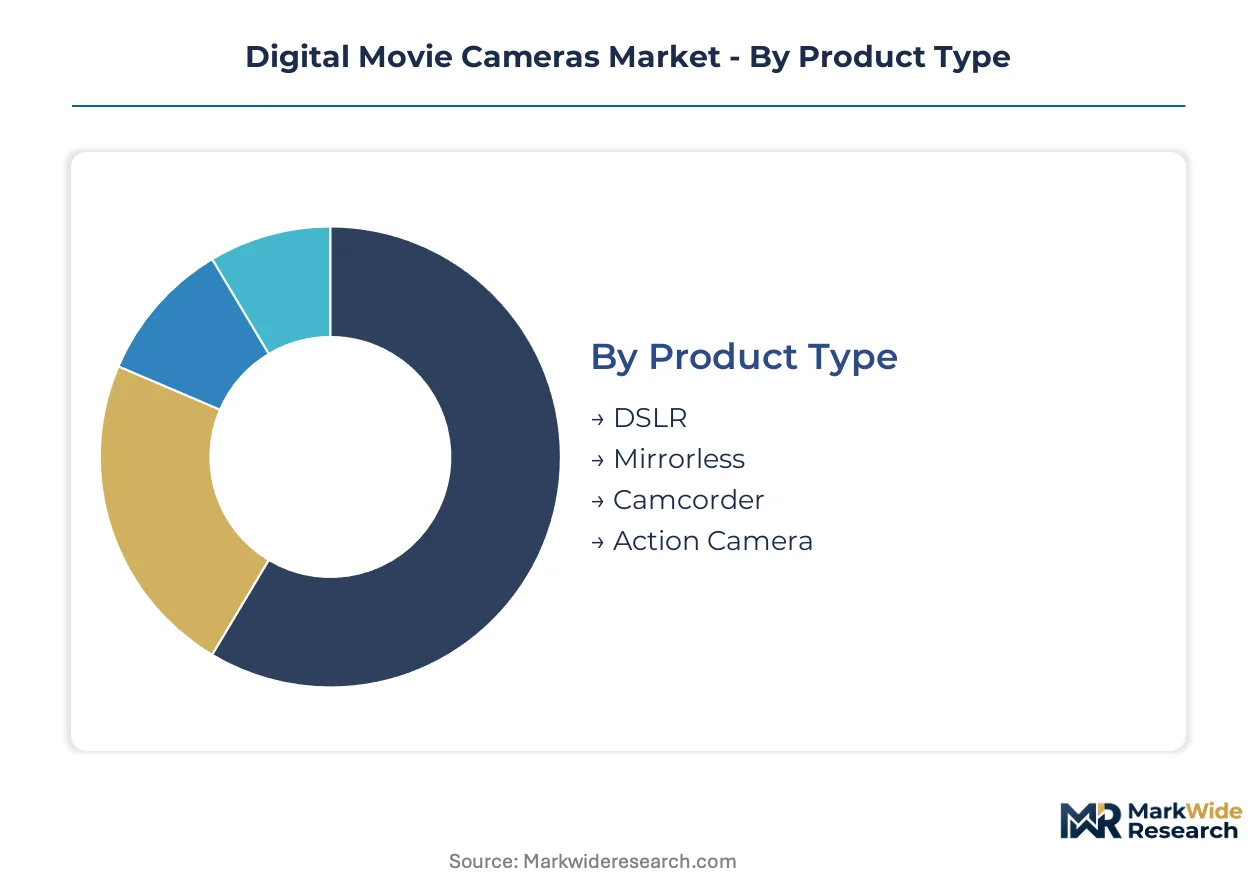
Segmentation in digital cinema equipment reveals how procurement patterns fragment between rental fleet operators and owner-operators. Format migration cycles and workflow specialization create distinct demand pockets that manufacturers must address through targeted sensor configurations and codec ecosystems.
Product Type:
Upgrade cycles vary dramatically by body configuration, with mirrorless systems forcing faster refresh rates than traditional camcorder architectures.
- Mirrorless:Compact full-frame bodies with interchangeable lens mounts dominate independent production workflows. Demand clusters in Los Angeles and Mumbai rental houses serving streaming platform originals, driven by lens adaptability and reduced gimbal payload requirements.
- DSLR:These bodies retain relevance in documentary and commercial segments where battery endurance and thermal stability outweigh resolution specifications. Owner-operators in secondary production markets favor these systems for their proven durability and lower insurance premiums.
- Camcorder:Integrated lens systems with fixed zoom ranges serve corporate training and live event capture where operator skill constraints limit interchangeable lens flexibility.
- Action Camera:Ruggedized compact units with extreme wide-angle optics occupy stunt and POV sequences in narrative production, with waterproof housings enabling underwater cinematography.
Volume placements concentrate in Mirrorless; the faster expansion belongs to Action Camera as immersive POV storytelling proliferates in streaming content.
Technology:
Resolution tiers stratify capital allocation between rental infrastructure and direct-to-streaming production budgets.
- 8K:Large-format sensors with 8192 horizontal resolution pixels anchor premium rental tiers in Germany and Japan. Fleet operators in Munich and Tokyo are building inventory ahead of theatrical exhibition upgrades, driven by future-proofing mandates from major studio clients.
- 4K:This resolution standard captures the majority of corporate training, educational content, and mid-budget documentary production. Procurement concentrates in owner-operator segments where storage and post-production infrastructure costs constrain specification ambitions.
- Digital:Broad category encompassing all non-film capture technologies, including compressed RAW and ProRes recording pipelines.
- Analog:Niche segment serving experimental filmmakers and archival restoration projects requiring film stock emulation.
Revenue concentration sits with 4K; steepest expansion trajectory belongs to 8K as exhibition infrastructure modernizes.
End User:
Customer type determines pricing tolerance and support service requirements across the procurement spectrum.
- Filmmakers:Narrative and documentary directors prioritize dynamic range and color science fidelity. German cinematographers specifically demand ARRI sensor architectures for theatrical exhibition compliance.
- YouTubers:Independent content creators drive volume in entry-tier mirrorless systems with autofocus reliability and direct streaming connectivity.
- Educators:University film programs and technical institutes favor cost-optimized 4K systems with standardized lens mounts for curriculum consistency.
- Corporate:Enterprise video departments prioritize automated workflows and IT integration over manual color grading flexibility.
Procurement volume clusters with Corporate; margin expansion follows Filmmaker segment premium tier adoption.
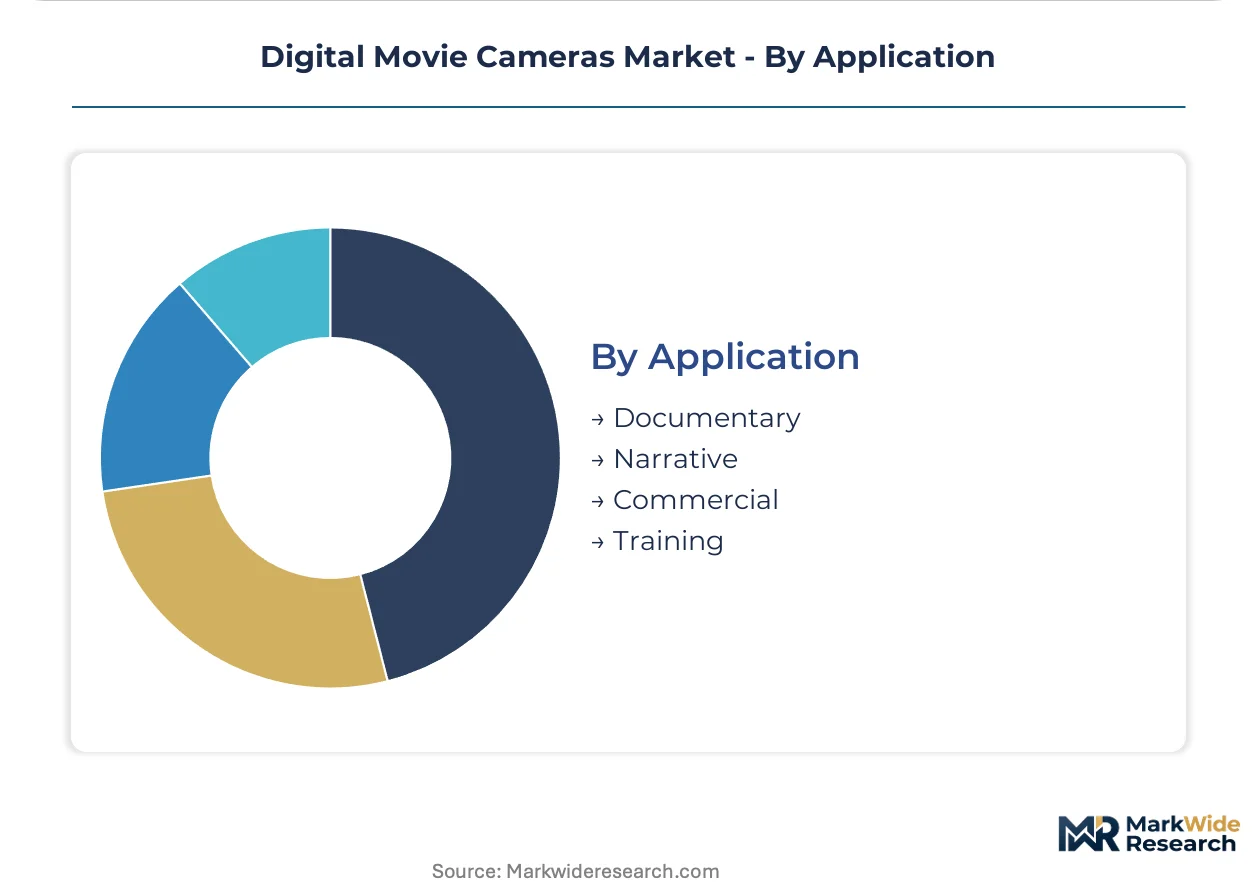
Application:
Use-case specialization drives sensor format and recording codec selection across production categories.
- Narrative:Theatrical feature production demands large-format sensors with 14+ stops dynamic range and RAW recording capabilities. German rental houses serving Netflix and Amazon co-productions specify full-frame configurations with PL lens compatibility.
- Documentary:Run-and-gun workflows favor compact mirrorless bodies with in-body stabilization and extended recording times. Demand concentrates in owner-operator segments covering conflict zones and environmental expeditions.
- Commercial:Advertising production cycles prioritize rapid turnaround and HDR delivery specifications, driving rental house investment in pre-calibrated color pipelines.
- Training:Corporate and educational video production accepts compressed 4K formats with automated exposure and focus systems to minimize specialized crew requirements.
Equipment utilization rates peak in Commercial; longest replacement cycles characterize Training applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's film production tax incentives anchor European equipment procurement concentration, while California's production rebates sustain North American rental house investment cycles.
United States
Streaming platform co-productions with major studios drive Los Angeles rental house fleet expansion. California Film Commission tax credits compress equipment depreciation schedules for narrative production. Burbank-based post-production facilities are integrating HDR calibration pipelines directly into camera rental packages.
Germany
Theatrical exhibition compliance standards pull demand toward large-format sensor configurations. EU Ecodesign for Sustainable Products Regulation mandates material disclosure for electronic imaging devices sold into member states. Munich engineering clusters sustain ARRI AG's dominance in premium cinematography equipment manufacturing.
Japan
Rental fleet operators in Tokyo are building 8K capture inventory ahead of theatrical infrastructure upgrades. METI energy efficiency standards influence power management design in battery-operated cinema rigs. Osaka-based precision optics manufacturers supply lens components for domestic and export markets.
India
State-level film subsidy schemes in Maharashtra attract location shoots and drive localized equipment procurement. BIS certification requirements shape electromagnetic compliance for cameras distributed domestically. Mumbai rental houses serving Bollywood and streaming platform originals are expanding mirrorless system inventories.
United Kingdom
Post-Brexit production tax relief maintains London's position as a European filming hub. CE marking requirements under the EU Radio Equipment Directive continue shaping product access for manufacturers. Pinewood Studios-adjacent rental providers are consolidating HDR workflow equipment for international co-productions.
Digital Movie Cameras Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across sensor format tiers. The vendor base stratifies between premium large-format manufacturers, mid-tier mirrorless providers, and entry-level workflow specialists. Three archetypes dominate: heritage optics conglomerates with cinema divisions, dedicated digital cinema pure-plays, and broadcast equipment diversifiers. Competitive moves concentrate on codec ecosystem lock-in and rental house partnership exclusivity.
Within the heritage optics tier, Canon Inc. and Nikon Corporation represent diversified imaging conglomerates with cinema product lines. ARRI AG anchors the premium large-format segment from its Munich engineering base. RED Digital Cinema exemplifies the pure-play digital cinema specialist archetype with proprietary compression technology.
| Leading Market Players |
|---|
| Sony Group Corporation |
| Canon, Inc. |
| Panasonic Holdings Corporation |
| ARRI AG |
| RED Digital Cinema, LLC |
| Blackmagic Design Pty. Ltd. |
| Nikon Corporation |
| JVCKENWOOD Corporation |
| Vision Research, Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into CMOS sensor fabrication anchors both supply security and pricing power for premium camera manufacturers. ARRI AG's captive Munich engineering base insulates its large-format systems from spot-market volatility while commanding rental house premiums.
Pricing Analysis
Short lead-time premiums for 8K sensor modules run 15-25% above standard fleet procurement schedules. Three-tier pricing structure across premium, standard, and economy levels stratifies by dynamic range certification and PL-mount compatibility. Price differentiation stems from proprietary RAW codec licensing and after-sales calibration service bundling. Corporate training segments exhibit highest price sensitivity; theatrical rental houses absorb premium tiering for future-proofing mandates.
Supply Chain Analysis
Precision optics workforce availability in Osaka and Munich constrains high-end lens module throughput. Advanced CMOS fabrication clusters in Japan, South Korea, and Taiwan feed sensor supply. Battery chemistry costs hinge on lithium carbonate spot markets. Single-source vulnerability concentrates in EUV lithography equipment for sub-7nm sensor designs. Distribution runs through Burbank and Munich rental house consignment networks with direct manufacturer technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced CMOS foundry capacity bottlenecks prop pricing across premium sensor tiers. Supply constraints in precision optics manufacturing sustain margin structures for integrated manufacturers.
For Market Incumbents: Anchor codec ecosystem lock-in through exclusive rental house partnerships. Defend against mirrorless convergence by certifying proprietary color science pipelines for streaming platform delivery specifications. Invest in thermal management R&D to preempt EU Ecodesign efficiency benchmarks. For New Entrants and Emerging Players: EU Ecodesign for Sustainable Products Regulation in Europe opens a window for transparent supply chain positioning against opaque competitors. Target India's state-level production incentive corridors with localized service partnerships. Pursue documentary filmmaker segments with compact 4K systems emphasizing in-body stabilization over RAW flexibility. For Investors and Strategic Acquirers: Exit pathways concentrate in pure-play digital cinema specialists with proprietary compression IP. Long-term viability favors vendors controlling both sensor architecture and post-production codec ecosystems. Watch theatrical exhibition infrastructure upgrade announcements as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Codec Ecosystem Expansion | Proprietary RAW licensing locks rental houses into vendor-specific post-production pipelines. |
| 8K Fleet Buildout | Munich and Tokyo rental operators are acquiring premium inventory ahead of theatrical upgrades. |
| Sustainable Design Certification | EU Ecodesign material disclosure mandates create competitive differentiation for transparent manufacturers. |
| Mirrorless Form Factor Convergence | Compact systems displace dedicated camcorders in documentary and commercial production workflows. |
| Regional Service Partnership | Mumbai rental houses expand mirrorless inventories to serve Bollywood streaming co-productions. |
Methodological Framework
Independent corroboration across rental house procurement managers, post-production facility engineers, and streaming platform technical directors underwrites the qualitative findings. Primary fieldwork encompassed cinematographers, camera rental fleet operators, and digital imaging technicians across Los Angeles, Munich, Mumbai, and Tokyo. Secondary validation drew from FCC equipment authorization filings, EU Ecodesign regulatory texts, METI efficiency standard disclosures, and customs trade data for imaging equipment. Bottom-up segment sizing triangulated against top-down industry revenue estimates.
Comparable-period anchoring calibrated the projection framework against historical theatrical release cycle patterns and streaming platform capex disclosures. The analytical framework modeled product type, resolution tier, end-user segment, and application workflow across the analysis window. CAGRs derived from segment-level demand elasticity and replacement cycle compression. Forecast inputs incorporated sensor format migration timelines and regional production incentive scheme announcements.
The model assumes a particular technology adoption path; alternative pathways for computational imaging consolidation would alter the outlook. Forecasts reflect assumptions regarding theatrical exhibition infrastructure investment continuity and streaming platform original content budgets. Material deviation in CMOS foundry capacity expansion or EU sustainability enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
North America Image Sensors Market
Imaging
Camera with Flip Screen Market
Imaging
Near Infra-Red Imaging Market
Imaging
AI Camera Market
Imaging
Wearable IP Camera Market
Imaging
Global Cell Imagers Market
Imaging
Acoustic Microscopy Market
Imaging
Pocket Video Camera Market
Imaging
Vintage Cameras Market
Imaging
Gige Camera Market
Imaging
Industrial X-Ray Inspection Equipment and Imaging Software Market
Imaging
TDI Camera Market
Imaging
Video Microscopes Market
Imaging
Thermal Imaging Systems Market
Imaging
Image Based Barcode Reader Market
Imaging
Europe Industrial Computed Tomography Market