
 Underwater Camera Market | 2026-2036
Underwater Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Camera Market Analysis
Cloud-based post-processing subscription tiers is realigning how underwater camera vendors monetize hardware sales. GoPro Inc. leverages its subscription ecosystem to sustain recurring revenue beyond initial device purchases. Sony Corporation anchors its position through sensor technology leadership in low-light submersible applications. Canon Inc. competes on optical heritage and professional cinematographer loyalty.
Underwater cameras are sealed imaging devices engineered to operate at hydrostatic pressures exceeding ambient atmospheric conditions, typically rated to depths of 10 meters to 100 meters depending on housing construction, with primary commercial purpose spanning marine biology documentation, recreational dive tourism, and offshore infrastructure inspection. Action cameras within the Product Type segment dominate unit volume through compact form factors suited to consumer snorkeling and extreme sports, while Mirrorless systems capture the professional cinematographer margin pool with interchangeable lens flexibility. Digital technology underpins the vast majority of current installations, though 360-Degree capture is gaining traction among research institutions requiring immersive spatial documentation.
IEC 60529 ingress protection ratings and ISO underwater equipment standards govern enclosure integrity and depth certification requirements, with national maritime safety regulators in coastal economies enforcing compliance for commercial diving operations. The US Federal Communications Commission and Japan's Ministry of Economy, Trade and Industry both impose electromagnetic emissions and energy efficiency standards on battery-powered submersible electronics. Stakeholders must monitor evolving battery chemistry regulations and depth-rating verification protocols as lithium-ion energy density improves and deeper commercial applications proliferate.
Market Dynamics
Cloud-based subscription models are unifying hardware monetization with recurring software revenue streams, forcing vendors to restructure customer lifetime value calculations around post-purchase engagement rather than single-transaction margins.
Growth Catalysts
- Marine Research Expansion:Australia's Great Barrier Reef tourism corridor and adjacent research zones are expanding procurement of submersible imaging systems for biodiversity documentation.
- ISO 6425 Certification Pressure:Tightening dive-watch standards and IP68 enclosure requirements are accelerating replacement cycles among commercial diving operations.
- Offshore Infrastructure Inspection:Energy sector maintenance protocols are mandating visual documentation of subsea assets, creating sustained demand for depth-rated camera systems.
Market Restraints
- Lithium-Ion Supply Concentration:Battery chemistry improvements face regulatory scrutiny as energy density advances, with maritime safety regulators enforcing stricter depth-rating verification protocols.
- Optical Component Cost Structure:Precision lens assemblies and pressure-resistant housing materials command premium input costs that compress margins at entry-tier price points.
- 360-Degree Substitution Pressure:Immersive spatial documentation systems are displacing traditional planar imaging in research institution procurement specifications.
Strategic Opportunities
- Japan's METI Efficiency Standards:Electromagnetic emissions and energy efficiency mandates for battery-powered submersible electronics are creating compliance-driven upgrade demand.
- Mirrorless Convergence:Interchangeable lens flexibility combined with low-light sensor advancement is unifying professional cinematographer and research institution requirements.
- Direct-to-Researcher Channels:Marine biology departments are bypassing traditional distribution intermediaries through institutional procurement platforms.
Industry Challenges
- IEC 60529 Certification Timelines:Ingress protection rating verification for new housing designs creates extended product development cycles that delay commercialization.
- Pressure-Engineering Talent Scarcity:Specialized optical and mechanical engineering expertise for hydrostatic environment design concentrates among a limited pool of experienced practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Camera Market |
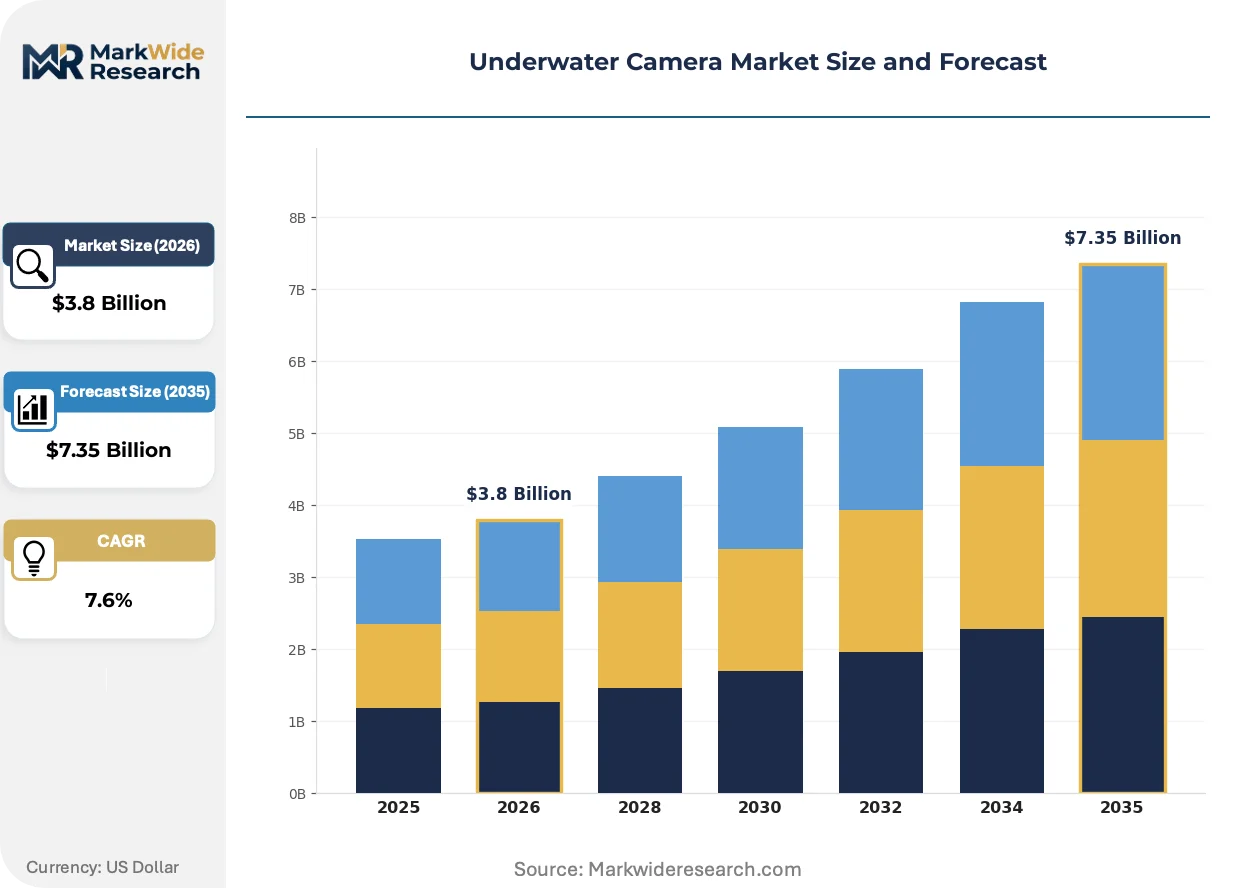
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Mirrorless, Action, DSLR Technology: Digital, Analog, 360-Degree, Video End User: Professionals, Hobbyists, Cinematographers, Researchers Distribution Channel: Online, Retail Stores, Specialty Shops, Wholesalers |
| Companies Covered | GoPro Inc., Sony Corporation, Canon Inc., Nikon Corporation, OM Digital Solutions Corporation, Panasonic Corporation, SeaLife Cameras, Fujifilm Holdings Corporation, Teledyne Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Camera Market Emerging Trajectories
Sensor technology advancement and regulatory harmonization are compressing the performance gap between consumer action cameras and professional cinematography systems, while procurement centralization is reshaping vendor-customer relationships.
Computational photography algorithms are unifying low-light performance with real-time depth compensation. Marine research institutions are adopting these systems for nocturnal species documentation. The technology is unifying previously separate lighting and capture hardware investments into single-device workflows.
Japan's METI has imposed electromagnetic emissions standards on submersible electronics that exceed baseline IEC requirements. Domestic manufacturers must redesign shielding architectures to maintain market access. Professional cinematography segments are absorbing compliance costs through premium pricing tiers.
Subscription-based post-processing tiers are displacing perpetual license models among recreational diving enthusiasts. GoPro's ecosystem approach demonstrates how hardware margins compress while service revenue expands. Australia's tourism operators are piloting bundled capture-and-edit packages for visitor experience monetization.
Underwater Camera Market Segmentation
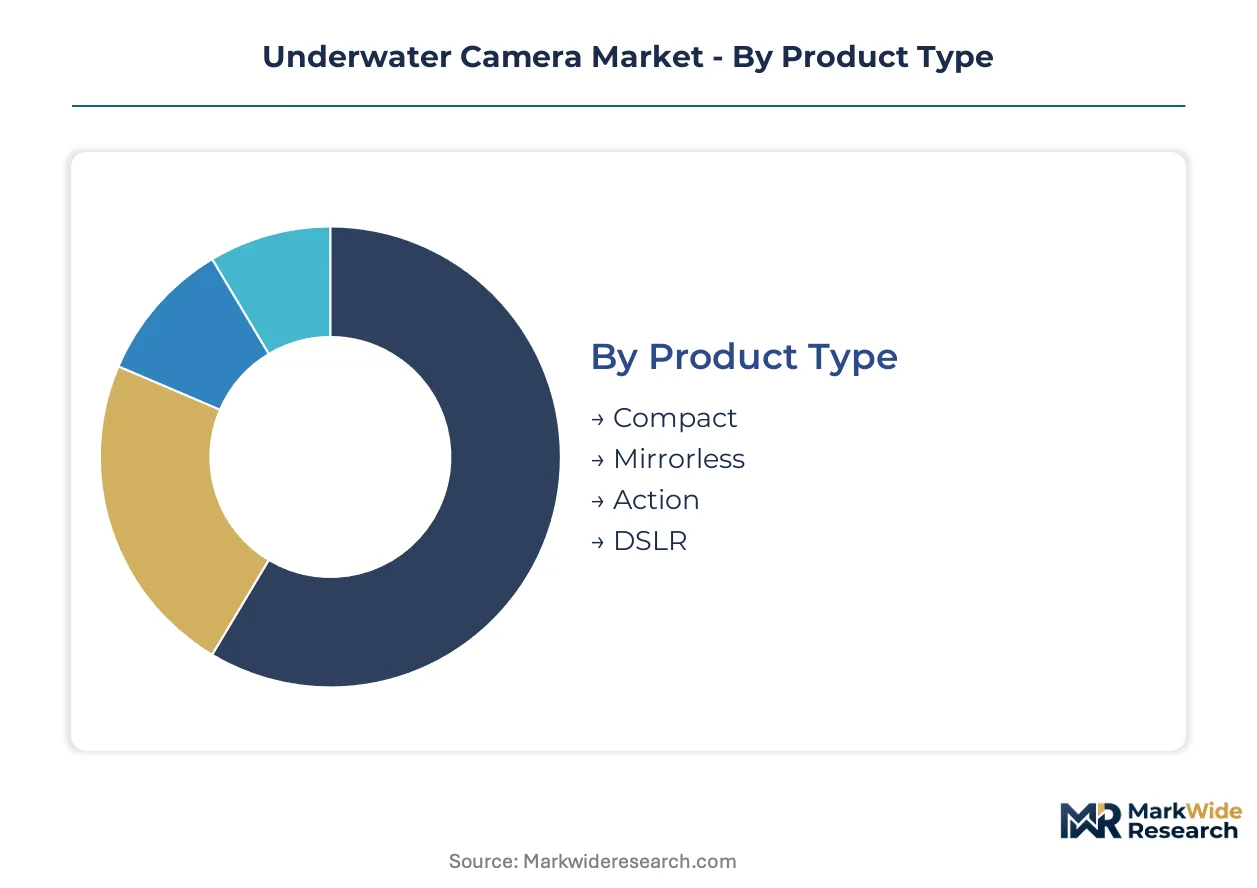
Underwater camera segmentation reveals divergent capital requirements across product architectures, with professional-grade systems demanding precision optical engineering while consumer formats prioritize scale manufacturing. Understanding these structural differences illuminates where margin pools concentrate and which technology trajectories warrant resource allocation.
Product Type:
Mirrorless and DSLR systems command the steepest upfront capital commitments due to interchangeable lens ecosystems and pressure-rated housing complexity, while compact and action formats leverage standardized component platforms.
- Compact:Fixed-lens designs with integrated waterproofing target recreational snorkelers and casual marine tourists. Australia's Great Barrier Reef tourism corridor concentrates procurement volumes for rental fleet operators seeking durability over optical sophistication.
- Mirrorless:Interchangeable lens architectures with large-format sensors deliver low-light performance for professional cinematographers. Research institutions in marine biology departments specify these systems for biodiversity documentation where lighting flexibility determines capture quality.
- Action:Ultra-compact form factors with integrated stabilization serve extreme sports and shallow recreational diving. Ruggedized construction tolerates repeated impact exposure in high-volume consumer applications.
- DSLR:Optical viewfinder systems with established lens mount ecosystems retain loyalty among professional underwater photographers. Legacy accessory compatibility preserves upgrade pathways for existing equipment owners.
Action cameras absorb the bulk of installed capacity; mirrorless systems are expanding most quickly as sensor technology narrows the performance gap with larger formats.
Technology:
Digital capture platforms dominate manufacturing scale, while emerging modalities reshape how spatial data gets collected and processed across end-use applications.
- Digital:CMOS and CCD sensor architectures with computational processing pipelines constitute the overwhelming majority of current installations. ISO 6425 compliance requirements and IP68 certification standards govern enclosure integrity for commercial diving operations.
- Analog:Film-based capture persists in niche artistic and archival applications where chemical processing delivers distinctive tonal characteristics. Limited commercial volume concentrates among specialty rental houses serving cinematographers.
- 360-Degree:Multi-sensor spherical capture systems generate immersive spatial documentation for research institutions. Australia's marine research zones are adopting these platforms for habitat mapping where planar imaging proves insufficient.
- Video:Dedicated moving-image formats with high frame-rate capabilities serve broadcast documentary production. Professional cinematographer specifications prioritize codec flexibility and color depth over still-capture resolution.
Digital platforms retain the dominant installed base; 360-degree systems are gaining share fastest as immersive documentation standards proliferate.
End User:
Professional and research segments extract premium pricing through specialized performance requirements, while hobbyist volumes drive manufacturing economies.
- Professionals:Commercial diving contractors and underwater photography studios require depth-rated systems with redundant sealing and serviceable components. Offshore infrastructure inspection mandates from energy sector operators sustain replacement cycles.
- Hobbyists:Recreational divers and snorkelers prioritize portability and intuitive operation over technical configurability. Subscription-based post-processing services are capturing recurring revenue from this segment.
- Cinematographers:Feature film and documentary production crews demand raw codec output and cinema-grade color science. Low-light sensor performance determines platform selection for nocturnal marine species documentation.
- Researchers:Marine biology and oceanography departments specify systems compatible with institutional procurement platforms and long-term archival standards. Direct-to-researcher distribution channels are displacing traditional intermediaries.
Professionals command the highest per-unit margins; researchers are expanding procurement fastest as marine research funding accelerates.
Distribution Channel:
Channel selection reflects customer technical sophistication and purchase urgency, with direct platforms capturing educated buyers while physical retail serves impulse and experiential decision-making.
- Online:Manufacturer-direct and marketplace platforms dominate replacement purchases and accessory replenishment. Subscription bundling and cloud-based post-processing tiers integrate hardware with recurring service revenue.
- Retail Stores:Big-box and electronics chains serve first-time buyers seeking hands-on evaluation. Seasonal tourism patterns in Australia's coastal economies concentrate foot traffic during peak diving months.
- Specialty Shops:Dive equipment retailers provide technical consultation and pressure-testing services for professional-grade systems. Staff expertise justifies premium positioning over mass-market alternatives.
- Wholesalers:Volume distributors supply rental fleet operators and tourism businesses with standardized equipment packages. Australia's Great Barrier Reef tourism corridor channels significant procurement through this tier.
Online channels capture the majority of transaction volume; specialty shops are growing fastest as technical differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Japan and China while consumption clusters in coastal tourism economies and marine research corridors. Australia and the United States absorb disproportionate procurement volumes through institutional research funding and recreational diving infrastructure. Regulatory divergence across maritime safety regimes fragments certification requirements.
United States
Offshore energy infrastructure inspection mandates from Gulf of Mexico operators sustain commercial diving equipment procurement. The FCC imposes electromagnetic emissions standards on battery-powered submersible electronics that exceed baseline international requirements. California's marine research institutions channel significant funding toward biodiversity documentation systems.
Japan
Sensor technology leadership and precision optical manufacturing anchor domestic production capacity. METI enforces energy efficiency mandates on submersible electronics that drive domestic redesign cycles. Tokyo-Osaka industrial corridors concentrate housing fabrication and pressure-engineering expertise for professional cinematography systems.
Australia
The Great Barrier Reef tourism corridor generates concentrated demand from rental fleet operators and marine biology departments. TGA maritime safety protocols govern commercial diving equipment certification for reef research operations. Queensland's coastal research zones are expanding procurement of immersive spatial documentation systems for habitat mapping.
China
Component manufacturing scale and battery supply chain integration support cost-competitive action camera production. MIIT oversees electromagnetic compatibility standards for consumer electronics exports. Shenzhen-Dongguan manufacturing clusters supply standardized housing platforms to international brands.
Germany
Industrial diving contractors serving North Sea offshore wind installations require depth-rated inspection systems. REACH chemical regulations constrain housing material formulations for EU market access. Hamburg's maritime engineering sector concentrates pressure-vessel design expertise for professional-grade enclosures.
Underwater Camera Market Vendor Landscape
Top-tier vendors anchor professional cinematography and research segments, while mid-tier specialists occupy recreational diving and action camera tiers. The vendor base stratifies across sensor technology ownership, optical heritage, and subscription ecosystem maturity. Three archetypes dominate: integrated electronics conglomerates with sensor fabrication capabilities, optical specialists with legacy lens mount ecosystems, and action-camera pure-plays with direct-to-consumer distribution. Competitive maneuvering centers on cloud-based post-processing subscription bundling and mirrorless system convergence toward research institution specifications.
Within the integrated electronics tier, Sony Corporation and Panasonic Corporation exemplify sensor-technology-led positioning through low-light submersible applications. Canon Inc. and Nikon Corporation occupy the optical heritage archetype with established professional cinematographer loyalty and interchangeable lens ecosystems. GoPro Inc. anchors the action-camera pure-play model with subscription ecosystem monetization beyond hardware transactions.
| Leading Market Players |
|---|
| GoPro Inc. |
| Sony Corporation |
| Canon Inc. |
| Nikon Corporation |
| OM Digital Solutions Corporation |
| Panasonic Corporation |
| SeaLife Cameras |
| Fujifilm Holdings Corporation |
| Teledyne Marine |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between IP68-rated commercial systems and consumer snorkeling equipment manifests in divergent margin structures and sourcing geographies. Premium-tier vendors absorb precision optical engineering costs through professional cinematographer loyalty, while commodity action camera producers leverage Shenzhen-Dongguan manufacturing clusters to compress unit economics.
Pricing Analysis
Margin tightening in entry-tier action cameras reflects lithium-ion battery supply concentration and standardized housing platform competition. Three-tier pricing structure across professional cinematography, research-grade mirrorless, and recreational action formats separates ISO 6425-certified commercial systems from IP68 consumer devices. Subscription bundling with cloud-based post-processing tiers captures recurring revenue from hobbyist segments least sensitive to upfront hardware costs. Professional cinematographers exhibit lowest price sensitivity due to raw codec and low-light performance requirements.
Supply Chain Analysis
Japan's METI energy efficiency mandates and domestic-content preferences are reshaping sensor fabrication sourcing toward Tokyo-Osaka industrial corridors. Precision CMOS sensors and pressure-resistant optical glass draw from Japanese and German supply bases, while lithium-ion cells and standardized housing plastics feed from Chinese manufacturing clusters. Single-source vulnerability concentrates in specialty pressure-engineering talent for hydrostatic housing design. Distribution runs through direct-to-researcher institutional procurement platforms and dive equipment specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational photography algorithms are displacing separate lighting and capture hardware investments, compressing equipment procurement cycles for marine research institutions and forcing legacy lighting accessory vendors toward obsolescence.
For Market Incumbents: Deepen sensor technology differentiation through low-light submersible performance leadership against mirrorless convergence threats. Invest in IEC 60529 certification pre-clearance to compress product development timelines. Secure backward integration into pressure-rated housing fabrication to defend margin position against optical component cost inflation. For New Entrants and Emerging Players: Australia's marine biology departments represent an underserved buyer archetype with expanding institutional procurement budgets for immersive spatial documentation. Direct-to-researcher distribution channels bypass established intermediaries. 360-degree capture platforms offer the most penetrable entry point where planar imaging incumbents retain legacy loyalty. For Investors and Strategic Acquirers: Re-rating potential sits with pressure-engineering specialists given offshore infrastructure inspection mandates from energy sector operators. Long-term viability favors vendors with subscription ecosystem maturity extending customer lifetime value beyond transactional hardware margins. Watch for 360-degree procurement specification displacement in research institution RFPs as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Mirrorless System Convergence | Unifies professional cinematographer and marine research specifications through interchangeable lens flexibility. |
| Subscription Ecosystem Expansion | GoPro's recurring revenue model demonstrates hardware margin compression offset by post-processing service tiers. |
| Direct-to-Researcher Channel Development | Bypasses traditional distribution intermediaries as Australia's marine biology departments centralize procurement. |
| 360-Degree Platform Investment | Addresses habitat mapping requirements where planar imaging proves insufficient for spatial documentation. |
| Pressure-Engineering Talent Acquisition | Secures scarce hydrostatic housing design expertise concentrated among limited experienced practitioners. |
Methodological Framework
Multi-period observation of sensor technology advancement and regulatory harmonization anchored the trend analysis, supplemented by interviews with marine biology department procurement officers, commercial diving contractors, underwater cinematography studios, and dive equipment specialty retailers. Secondary validation drew from IEC 60529 certification databases, ISO underwater equipment standards filings, METI electromagnetic emissions disclosures, and TGA maritime safety protocols. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Input-output matrices modeled unit shipments and value flows across product type, technology modality, end-user archetype, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectories weighted by procurement pattern shifts in Australia's Great Barrier Reef corridor and offshore energy inspection mandates. Forecast inputs incorporated lithium-ion energy density improvement curves and depth-rating verification protocol evolution.
Revisions become necessary when battery chemistry regulations tighten beyond current maritime safety frameworks or when 360-degree immersive documentation achieves dominant procurement specification status in research institutions. Forecasts reflect documented assumptions regarding sensor cost curves and certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Contact Image Sensor Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Borescope Market
Imaging
Machine Vision Camera Market
Imaging
Webcam Market
Imaging
Global CMOS Image Sensors Market
Imaging
Europe Machine Vision Systems Market
Imaging
Camera with Flip Screen Market
Imaging
X-Ray Market
Imaging
Global Mobile Image Sensor Market
Imaging
Machine Vision Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Hybrid Imaging Systems Market
Imaging
Global Whole Slide Imaging Market
Imaging
X-Ray Microscopes Market
Imaging
Global Waterproof Camera Market