
 X Ray Tubes Market | 2026-2036
X Ray Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
X Ray Tubes Market Intelligence
The transition from glass to metal-ceramic enclosures for X-ray tubes is reconfiguring manufacturing processes and product durability standards. This shift favors suppliers with advanced material science and vacuum technology capabilities. Varex Imaging Corporation specializes in high-performance components for a global OEM customer base. The Comet Group leverages its expertise in high-frequency technology to serve both medical and industrial inspection applications.
An X-ray tube is a vacuum device that converts electrical energy into X-rays by accelerating electrons from a heated cathode to strike a metal anode. These components are designed to operate at specific high voltages and produce a defined spectrum of radiation. While glass-based tubes still hold a significant share, metal-ceramic X-ray tubes are gaining prominence due to superior heat dissipation and longevity. Medical imaging constitutes the largest application segment, with non-destructive testing applications in aerospace and automotive sectors representing a key growth frontier.
Market access is governed by stringent regulatory frameworks for medical devices. In the United States, the FDA's 510(k) clearance process is critical, while in Europe, compliance with the Medical Device Regulation (MDR) and CE marking is mandatory. These regulations dictate performance standards and quality control for tubes used in diagnostic imaging. Future competitive advantage will depend on developing tubes with higher power density and longer operational lifespans to meet the demands of advanced imaging modalities.
Market Dynamics
The fundamental shift from glass to metal-ceramic enclosures is the central force shaping the X-ray tube market. This transition elevates manufacturing complexity, favoring suppliers with deep expertise in material science, brazing techniques, and ultra-high vacuum technology.
Growth Catalysts
- Digital Radiography Upgrades:The replacement cycle of analog X-ray systems with digital radiography (DR) and computed tomography (CT) scanners in hospitals worldwide accelerates demand for higher-performance tubes compatible with these platforms.
- Industrial NDT Expansion:Non-destructive testing applications in the aerospace and automotive sectors, used for inspecting composite materials and critical welds, represent a significant growth vector for high-power industrial X-ray tubes.
- Healthcare Infrastructure Investment:Government-led initiatives, particularly in China, to expand healthcare access and diagnostic capabilities are driving large-scale procurement of medical imaging equipment, creating sustained demand for X-ray components.
Market Restraints
- High Material Costs:The price volatility and supply concentration of critical raw materials, such as tungsten for filaments and anodes and specialized ceramics for insulators, create significant cost pressures for manufacturers.
- Stringent Regulatory Hurdles:Gaining market access requires navigating complex and lengthy approval processes, including the FDA's 510(k) clearance in the United States and CE marking under the MDR in Europe.
- Thermal Management Limits:The inherent challenge of dissipating waste heat from the anode limits the maximum power and duty cycle of X-ray tubes, acting as a technical barrier to achieving higher imaging speeds and resolution.
Strategic Opportunities
- Additive Manufacturing Inspection:The adoption of industrial CT scanning for quality assurance of 3D-printed metal and polymer parts creates a new application frontier for high-resolution, microfocus X-ray tubes.
- Predictive Maintenance Integration:Embedding sensors and leveraging AI analytics to monitor tube performance in real-time offers an opportunity to sell outcome-based service contracts focused on maximizing system uptime and predicting failures.
- Emerging Market Penetration:Expanding diagnostic imaging infrastructure in Southeast Asian and Latin American countries presents an opportunity for suppliers to provide durable, cost-effective tubes tailored for regional healthcare needs.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers and technicians with expertise in high-voltage physics, vacuum technology, and specialized material brazing constrains production scalability and new product development.
- High Capital Investment:Manufacturing advanced metal-ceramic tubes requires substantial capital expenditure on cleanroom facilities, vacuum furnaces, and sophisticated high-voltage testing equipment, creating high barriers to entry.
- Legacy System Compatibility:Ensuring that new, higher-performance tubes are backward-compatible with the vast installed base of existing OEM imaging systems presents a significant engineering and validation challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X Ray Tubes Market |
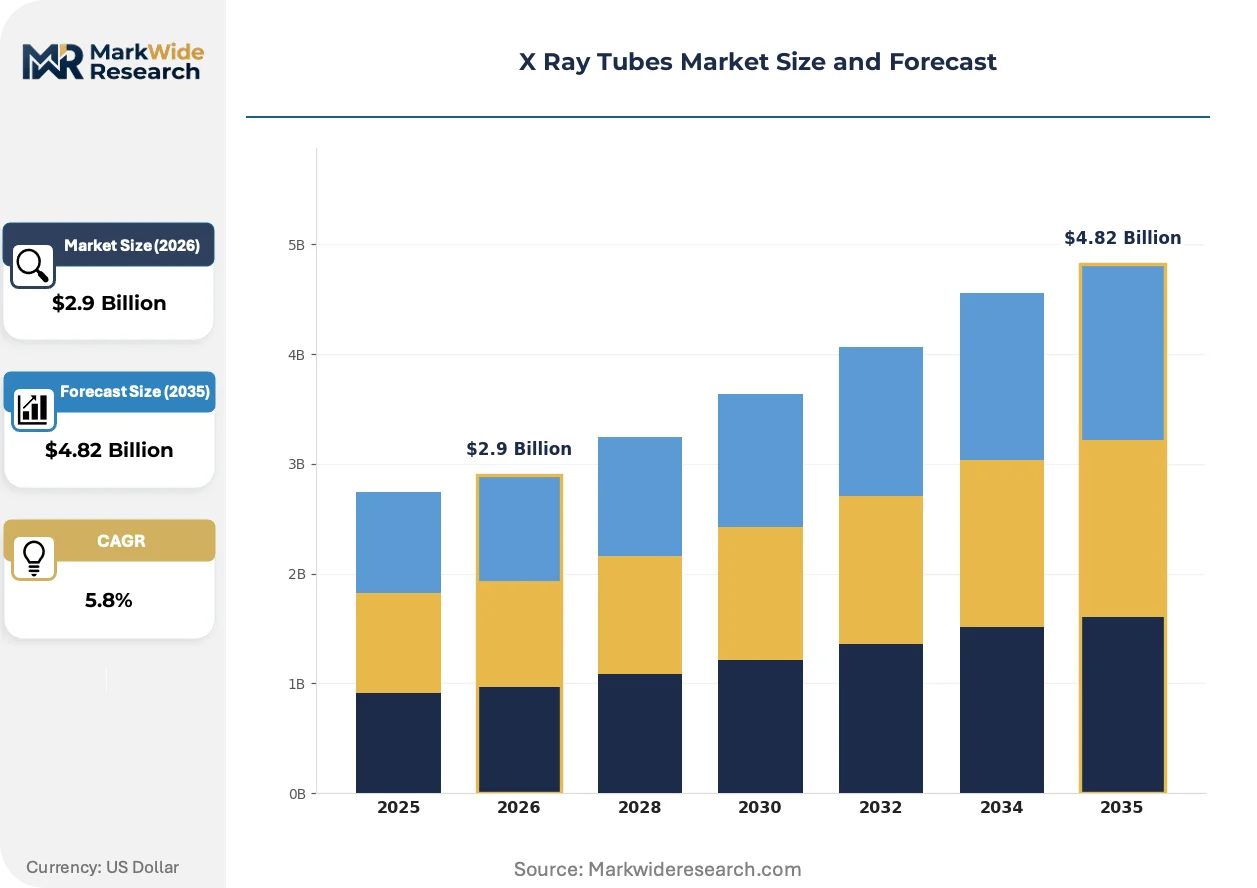
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.82 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass X Ray Tubes, Metal X Ray Tubes, Ceramic X Ray Tubes, High Voltage X Ray Tubes End User: Hospitals, Diagnostic Centers, Research Laboratories, Veterinary Clinics Application: Medical Imaging, Industrial Inspection, Security Scanning, Non-Destructive Testing Technology: Digital X Ray, Computed Radiography, Fluoroscopy, Cone Beam Computed Tomography |
| Companies Covered | Varex Imaging Corporation, Comet Group, Canon Electron Tubes & Devices Co. Ltd, Siemens AG, General Electric Company, Shimadzu Corporation, YXLON International, Hitachi Ltd., Koninklijke Philips NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X Ray Tubes Market Strategic Shifts & Innovations
Innovation in the X-ray tube market is driven by the need for higher power density, longer operational life, and greater control over the radiation output. These advancements are enabling new diagnostic and inspection capabilities across medical and industrial fields.
Next-generation field emission sources, or cold cathodes, provide precise, near-instantaneous control over X-ray generation. Medical equipment manufacturers are beginning to explore this technology for advanced computed tomography to enable faster scan times and dose reduction. This technology is digitizing the control of the X-ray pulse itself, creating pathways for novel techniques like dynamic and multi-energy imaging.
Europe's Medical Device Regulation (MDR) has intensified scrutiny on the entire medical device supply chain. The regulation mandates more extensive clinical evidence and robust post-market surveillance for components like X-ray tubes. Manufacturers selling into the European Union now face a higher compliance burden, impacting development timelines and documentation costs, especially for those supplying tubes for high-risk diagnostic applications.
A notable behavioral shift involves a move toward more integrated service and supply models for high-value imaging systems. This trend sees hospitals and large imaging centers favoring long-term service contracts that bundle tube replacement with maintenance and uptime guarantees. This model is most visible in the premium CT and angiography segments, where equipment availability is a critical operational metric.
X Ray Tubes Market Segmentation
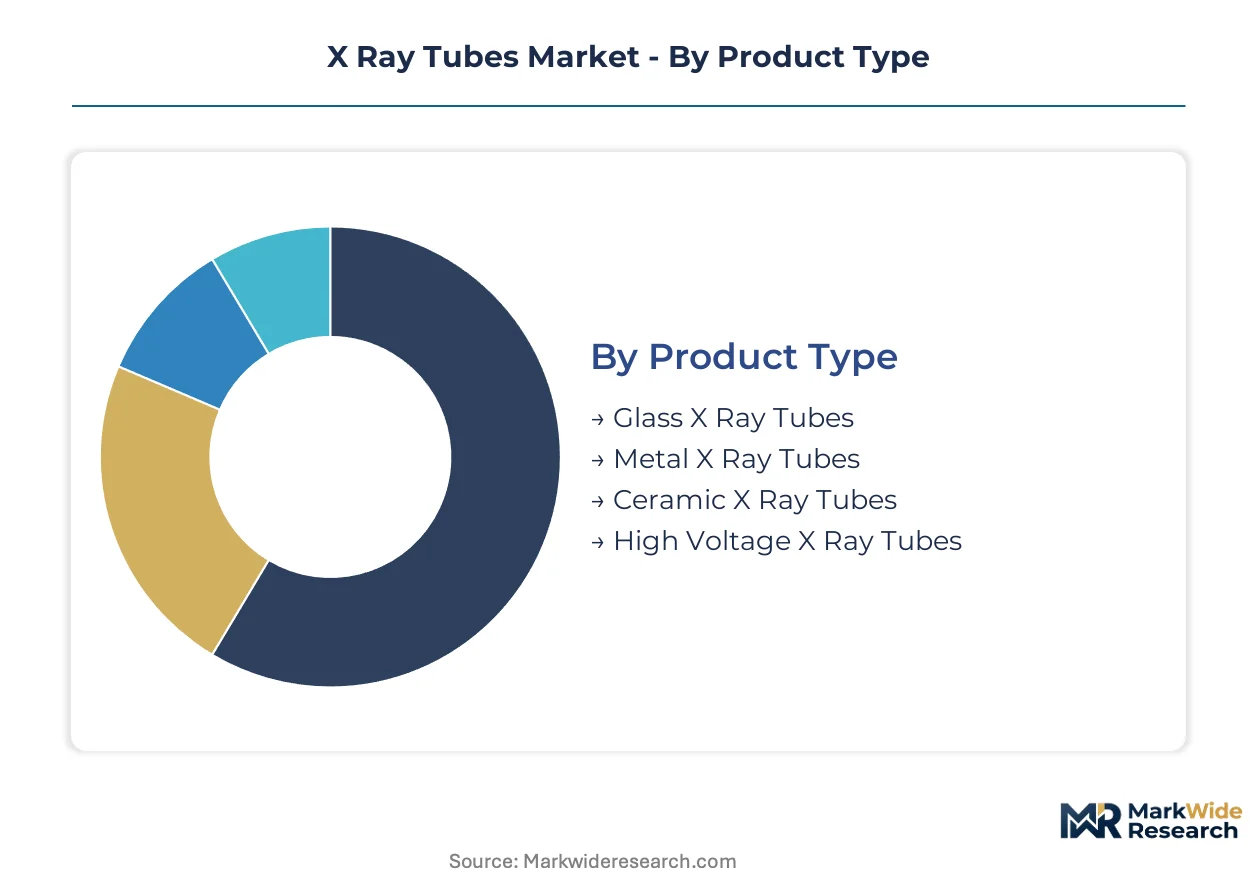
The X Ray Tubes Market exhibits distinct segmentation across several critical dimensions, reflecting varied technological capabilities, end-user requirements, and application specificities. Understanding these segments provides clarity on demand drivers and competitive dynamics within the X-ray tube industry.
Product Type:
The product type dimension differentiates X-ray tubes based on their construction materials and design principles, impacting performance and durability.
- Glass X Ray Tubes:These traditional tubes utilize a glass envelope to maintain vacuum, offering a cost-effective solution for many standard diagnostic applications. Demand for glass tubes remains consistent in regions with budget constraints, particularly in some emerging markets seeking basic diagnostic capabilities.
- Metal X Ray Tubes:Constructed with metal-ceramic envelopes, these tubes offer superior heat dissipation and mechanical robustness compared to glass variants. Medical imaging system manufacturers increasingly demand metal tubes for advanced CT scanners and angiography systems, where high power density and extended operational lifespans are essential.
- Ceramic X Ray Tubes:Ceramic tubes provide enhanced thermal stability and insulation properties, often employed in specialized industrial inspection settings requiring precise radiation control.
- High Voltage X Ray Tubes:These tubes are engineered to operate at extremely high voltages, typically used in industrial non-destructive testing for thick materials and cargo security scanning.
Glass X Ray Tubes commands the established base. The steepest expansion runs through Metal X Ray Tubes.
End User:
Customer type segmentation reveals the primary institutional consumers of X-ray tubes, each with unique purchasing patterns and technical requirements.
- Hospitals:These institutions represent a major end-user segment, acquiring X-ray tubes for a broad spectrum of medical imaging modalities, including radiography, fluoroscopy, and computed tomography. Hospital procurement often prioritizes reliability, image quality, and compatibility with existing digital imaging infrastructure.
- Diagnostic Centers:Specialized diagnostic centers focus on high-volume imaging procedures, driving demand for efficient, high-throughput X-ray tubes capable of rapid patient processing. These centers emphasize tube longevity and consistent performance to maximize operational uptime.
- Research Laboratories:Academic and industrial research laboratories utilize X-ray tubes for material science investigations, preclinical imaging, and novel diagnostic technique development.
- Veterinary Clinics:Animal healthcare facilities employ X-ray tubes for diagnostic imaging of pets and livestock, requiring robust and versatile systems.
Hospitals represent the primary demand channel for X-ray tubes. Diagnostic Centers show rapid expansion in imaging procedure volumes.
Application:
The application landscape categorizes X-ray tube usage across diverse industries, highlighting their functional versatility in both medical and industrial contexts.
- Medical Imaging:This segment constitutes the largest application area, encompassing diagnostic radiography, mammography, fluoroscopy, and computed tomography for human health assessment. Digital radiography upgrades in Europe and China significantly contribute to demand for high-performance medical imaging tubes.
- Industrial Inspection:X-ray tubes are critical for non-destructive testing (NDT) in manufacturing, aerospace, and automotive sectors, ensuring quality control of components and materials. The inspection of complex composite materials in aerospace manufacturing drives demand for specialized industrial X-ray tubes.
- Security Scanning:X-ray tubes are integral to security systems for baggage inspection at airports, cargo screening at ports, and threat detection in public spaces.
- Non-Destructive Testing:This application involves evaluating material properties and detecting flaws without causing damage, crucial for ensuring structural integrity in various industrial settings.
Medical Imaging drives substantial volume for X-ray tubes. Industrial Inspection applications are expanding quickly, particularly in quality assurance.
Technology:
Technology adoption patterns in X-ray imaging dictate the demand for specific tube characteristics, influencing design and performance innovations.
- Digital X Ray:Digital X-ray systems utilize flat-panel detectors to capture images electronically, replacing traditional film-based radiography and requiring tubes optimized for rapid pulsing and high image fidelity. The global shift from analog to digital radiography systems underpins this segment's growth.
- Computed Radiography:Computed radiography systems use phosphor plates to capture X-ray images, which are then scanned and digitized, offering a transitional technology between analog and full digital systems. Demand for these tubes persists in facilities transitioning to digital workflows.
- Fluoroscopy:Fluoroscopy employs continuous X-ray beams to produce real-time moving images, essential for guided surgical procedures and dynamic studies.
- Cone Beam Computed Tomography:This advanced imaging technique uses a cone-shaped X-ray beam to acquire 3D images with a single rotation, finding applications in dentistry and interventional radiology.
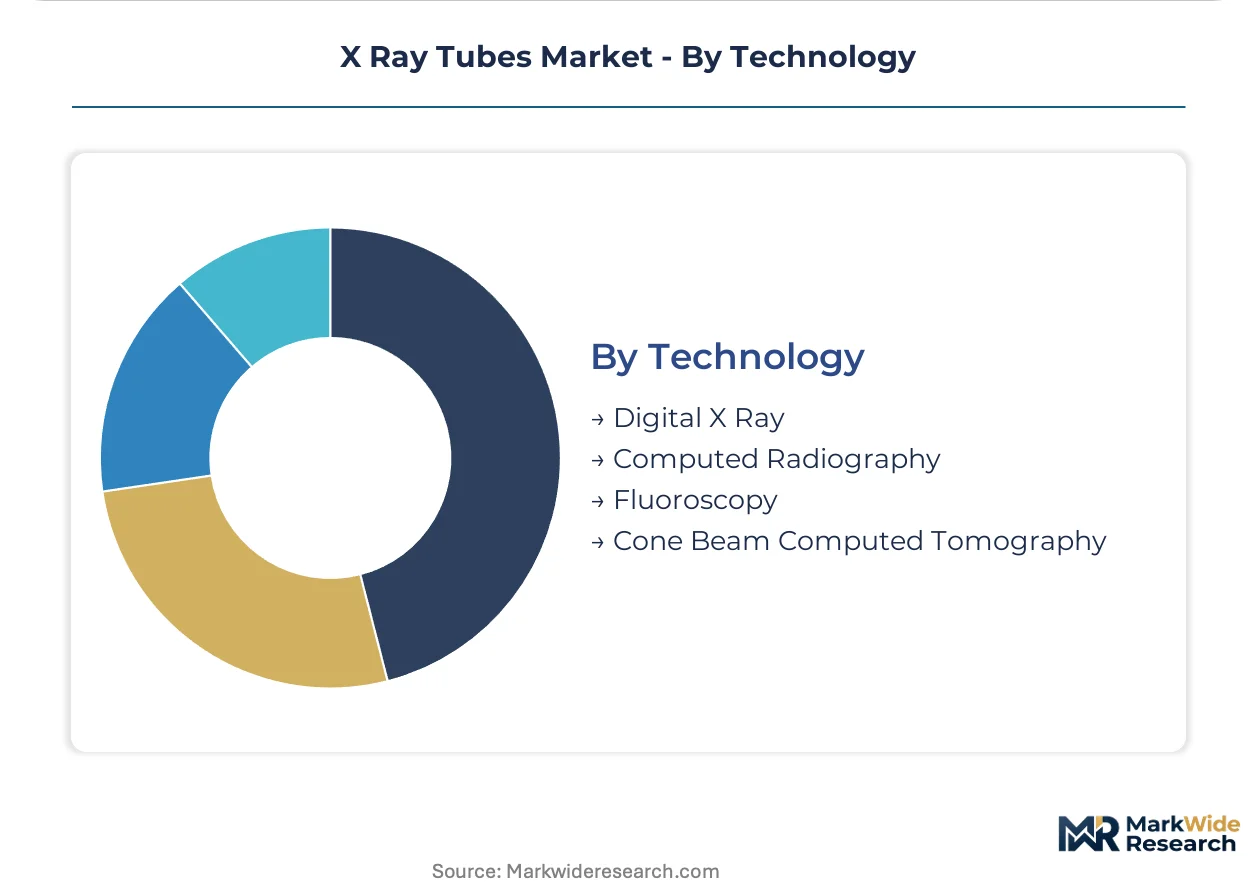
Digital X Ray technologies dominate modern installations. Cone Beam Computed Tomography shows significant innovation for specialized 3D imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences regional demand for X-ray tubes. Hospitals and diagnostic centers in developed economies drive demand for high-performance metal-ceramic tubes, while industrial applications in manufacturing hubs require specialized NDT solutions. Emerging markets prioritize cost-effectiveness and durability for expanding healthcare infrastructure.
United States
Digital radiography upgrades and advanced medical imaging modalities fuel demand for high-performance X-ray tubes. The FDA's 510(k) clearance process mandates rigorous performance and safety standards for medical devices. California and Massachusetts host significant medical device manufacturing clusters, contributing to component demand.
China
Government-led healthcare infrastructure investment drives substantial procurement of medical imaging equipment, increasing demand for X-ray components. The NMPA regulates medical devices, ensuring product quality and safety for the domestic market. The Yangtze River Delta region represents a major hub for medical equipment production and technology development.
Germany
Industrial non-destructive testing in the automotive and aerospace sectors drives demand for specialized high-power X-ray tubes. Compliance with the Medical Device Regulation (MDR) and CE marking is essential for medical X-ray tube suppliers. Bavaria and North Rhine-Westphalia are key regions for industrial technology and advanced manufacturing.
Japan
Advanced medical imaging technologies and stringent industrial quality assurance processes maintain strong demand for precision X-ray tubes. The PMDA regulates medical devices, ensuring high standards for diagnostic equipment. The Kanto region, including Tokyo, serves as a central point for medical device research and development.
India
Expanding diagnostic imaging infrastructure and a rising patient population increase the requirement for robust and cost-effective X-ray tubes. The CDSCO oversees medical device regulations, impacting market access for X-ray tube manufacturers. Karnataka and Maharashtra are emerging as significant clusters for medical equipment manufacturing and distribution.
X Ray Tubes Market Key Industry Players
Channel-controlling players compete with product-specialist players across the X-ray tube market. The market structure exhibits a tiered consolidation, with large diversified conglomerates alongside niche component manufacturers. Strategic partnerships and technology licensing represent dominant competitive moves among industry participants.
Varex Imaging Corporation exemplifies a specialized component manufacturer providing high-performance X-ray tubes to a global OEM customer base. Comet Group, a Swiss-based company, occupies a position combining expertise in high-frequency technology for both medical and industrial applications. Canon Electron Tubes & Devices Co. Ltd, a Japanese entity, represents a key player focused on electron tube technology for various imaging and industrial needs.
| Leading Market Players |
|---|
| Varex Imaging Corporation |
| Comet Group |
| Canon Electron Tubes & Devices Co. Ltd |
| Siemens AG |
| General Electric Company |
| Shimadzu Corporation |
| YXLON International |
| Hitachi Ltd. |
| Koninklijke Philips NV |
| Others |
Cost & Logistics Intelligence
Commodity price volatility for critical raw materials, such as tungsten and specialized ceramics, determines both pricing tier spreads and the strategic shape of the X-ray tube supply chain. This volatility impacts manufacturing costs and influences supplier stability.
Pricing Analysis
Cost-plus contracts, often structured with long-term agreements for OEMs, dominate pricing patterns for high-performance X-ray tubes. Price differentiation stems from specific performance specifications, such as power density and operational lifespan, alongside stringent regulatory compliance like FDA 510(k) clearance. Pricing pressure intensifies for standard glass tubes due to competition and raw material cost fluctuations. Basic diagnostic centers and emerging markets exhibit the highest price sensitivity, while advanced imaging centers and premium system OEMs prioritize performance over cost.
Supply Chain Analysis
Specialized contract manufacturing capacity for advanced metal-ceramic tubes concentrates in Germany and Japan, alongside a growing presence in China. The supply chain draws heavily on specific raw materials, including high-purity tungsten for filaments and anodes, and specialized ceramics for vacuum envelopes. Single-source vulnerability for these highly specialized components presents a structural supply chain risk. Distribution runs primarily direct to global OEM customers, with a smaller segment handled by specialized distributors for aftermarket service and niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a buyer-power-shift story, driven by the consolidation of large hospital networks and imaging group purchasing organizations. This shift influences procurement strategies and demands for integrated solutions.
For Market Incumbents:Entrench market leadership by investing heavily in advanced metal-ceramic material science and ultra-high vacuum technology. Deepen strategic OEM partnerships to co-develop next-generation tubes compatible with advanced imaging modalities, mitigating the threat from emerging cold cathode technologies. Focus R&D on achieving higher power density and extending operational lifespans to meet evolving clinical demands.
For New Entrants and Emerging Players:Build out capabilities in niche application segments like additive manufacturing inspection and predictive maintenance integration. Target emerging markets in Southeast Asia and Latin America, where underpenetration for diagnostic imaging creates demand for cost-effective and durable tube solutions. A go-to-market angle focused on outcome-based service contracts and localized technical support can differentiate offerings.
For Investors and Strategic Acquirers:EU MDR compliance reshapes the acquisition landscape, favoring companies with robust regulatory frameworks and proven quality systems over the long term. Seek acquisition targets that possess specialized expertise in field emission technology, advanced brazing, or ultra-high vacuum component manufacturing. The OEM adoption rates for next-generation tube technologies serve as a critical signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D | Enhances thermal management and extends tube lifespan, critical for high-performance CT systems. |
| OEM Partnership Expansion | Secures long-term supply agreements and integrates tube development with next-gen imaging platforms. |
| Digital Service Integration | Offers predictive maintenance solutions, maximizing system uptime for hospital networks. |
| Emerging Market Localisation | Tailors tube designs and support infrastructure for regional healthcare needs in India and China. |
| Cold Cathode Development | Enables precise X-ray pulse control, opening pathways for dose reduction in medical imaging. |
Research Approach
Initial hypotheses were tested against primary input from medical device engineers, hospital procurement managers, industrial NDT specialists, and regulatory affairs executives and refined through an iterative process. Secondary validation involved analysis of FDA 510(k) clearances, EU MDR guidance documents, national health infrastructure reports, and aerospace quality standards. This process employed both bottom-up market sizing and top-down validation for robust data integrity.
Demand-supply-balance models underpinned the quantitative framework, projecting market evolution across the analysis window. Segmentation dimensions including product type, end user, application, technology, and regional adoption were rigorously modeled. Compound annual growth rates were derived from historical trends and projected technological shifts. Key forecast inputs included healthcare spending projections and industrial NDT investment cycles.
Sensitivities concentrate around raw material price volatility, new regulatory mandates, and unforeseen technological breakthroughs that could revise forecasts. Forecasts reflect assumptions regarding economic stability and continued investment in healthcare infrastructure. Quarterly review of healthcare infrastructure spending and OEM product roadmaps is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
On-Chip Color Filters Market
Imaging
Handheld Imaging Systems Market
Imaging
Wearable IP Camera Market
Imaging
Weatherproof Camera Market
Imaging
X-Ray Systems Market
Imaging
Holotomographic Imaging Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Handheld Imaging Devices Market
Imaging
SDI Camera Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Photoconductor Drums Market
Imaging
Global 3D Imaging Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Instant Digital Cameras Market
Imaging
Asia Pacific IP Camera Market
Imaging
AI-Based Fever Detection Camera Market