
 Global High-Speed Digital Camera Market | 2026-2036
Global High-Speed Digital Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Global High-Speed Digital Camera Market Analysis
CMOS image sensors are restructuring cost structures across the high-speed digital camera landscape by displacing legacy CCD architectures in frame rates above 10,000 fps. Vision Research leverages in-house sensor fabrication to sustain pricing power in the ultra-high-speed tier. Photron Limited anchors its position through dedicated service centers in Asia-Pacific manufacturing corridors. Mikrotron GmbH differentiates via compact form factors purpose-built for industrial inline inspection.
High-speed digital cameras are electro-optical instruments engineered to capture sequential images at frame rates exceeding 240 fps, with specialized variants reaching millions of frames per second through intensified or streak architectures; CMOS backside-illumination and global shutter designs now enable sub-100 nanosecond exposure times for transient event analysis. Mirrorless architectures are gaining ground in scientific and industrial deployments where reduced mechanical vibration and continuous autofocus tracking matter. The 4K resolution tier captures disproportionate margin pools as broadcast and cinema clients demand chroma sampling fidelity that Full HD cannot deliver. Slow motion functionality remains the dominant feature specification across sports and film production end users, though low-light performance is emerging as a decisive criterion for defense and astronomy applications.
FCC equipment authorization governs electromagnetic emissions for systems deployed in US aerospace testing environments, while CE marking under the EU's Radio Equipment Directive shapes market access for European scientific instrument vendors. Japan's METI enforces energy efficiency benchmarks through Top Runner standards that constrain standby power in laboratory imaging suites. Stakeholders must monitor divergence between regional sensor export controls and harmonized IEC imaging standards as supply chain fragmentation accelerates.
Market Dynamics
CMOS backside-illumination architectures are collapsing cost-per-frame thresholds while EU energy efficiency mandates under the Green Deal reshape procurement specifications across member states. This technological-regulatory intersection is compressing legacy CCD upgrade cycles and redrawing competitive boundaries.
Growth Catalysts
- Semiconductor fabrication demand:East Asian chip foundries in Taiwan, South Korea, and Japan require sub-microsecond capture precision for wafer inspection and defect analysis. Tooling refresh cycles have shortened to 18-24 months.
- EU AI Act compliance:Automated visual inspection systems for automotive manufacturing must now meet algorithmic transparency requirements, driving replacement of legacy imaging hardware with traceable high-speed architectures.
- Ballistics research expansion:German, Japanese, and American defense laboratories are scaling high-frame-rate procurement for hypersonic projectile visualization and combustion dynamics studies.
Market Restraints
- Sensor supply concentration:Advanced CMOS fabrication capacity concentrates in Taiwan and South Korea, exposing procurement timelines to geopolitical transit risks and export control variability.
- Specialized optical component costs:Custom-designed objective lenses and intensifier tubes face price volatility due to rare-earth element dependencies and precision glass supply constraints.
- Technical bandwidth limitations:Data throughput bottlenecks in coaxial and fiber-optic transmission infrastructure constrain real-time streaming above 100,000 fps in field-deployable configurations.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for electronics manufacturing are attracting high-speed camera vendors to establish local calibration and service presence ahead of demand maturation.
- Autonomous vehicle validation:Lidar-to-camera sensor fusion testing requires synchronized multi-camera arrays at 10,000+ fps, creating specification pull from automotive safety labs in Germany and Michigan.
- Computational imaging convergence:Integration of edge AI inference with high-speed capture enables real-time anomaly detection without downstream server dependency, opening predictive maintenance applications.
Industry Challenges
- Specialized firmware engineering scarcity:Talent capable of optimizing FPGA-based image processing pipelines for nanosecond-precision triggering commands premium compensation and extended recruitment timelines.
- Multi-jurisdiction certification complexity:Simultaneous FCC equipment authorization, CE marking under the Radio Equipment Directive, and METI Top Runner compliance extends product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High-Speed Digital Camera Market |
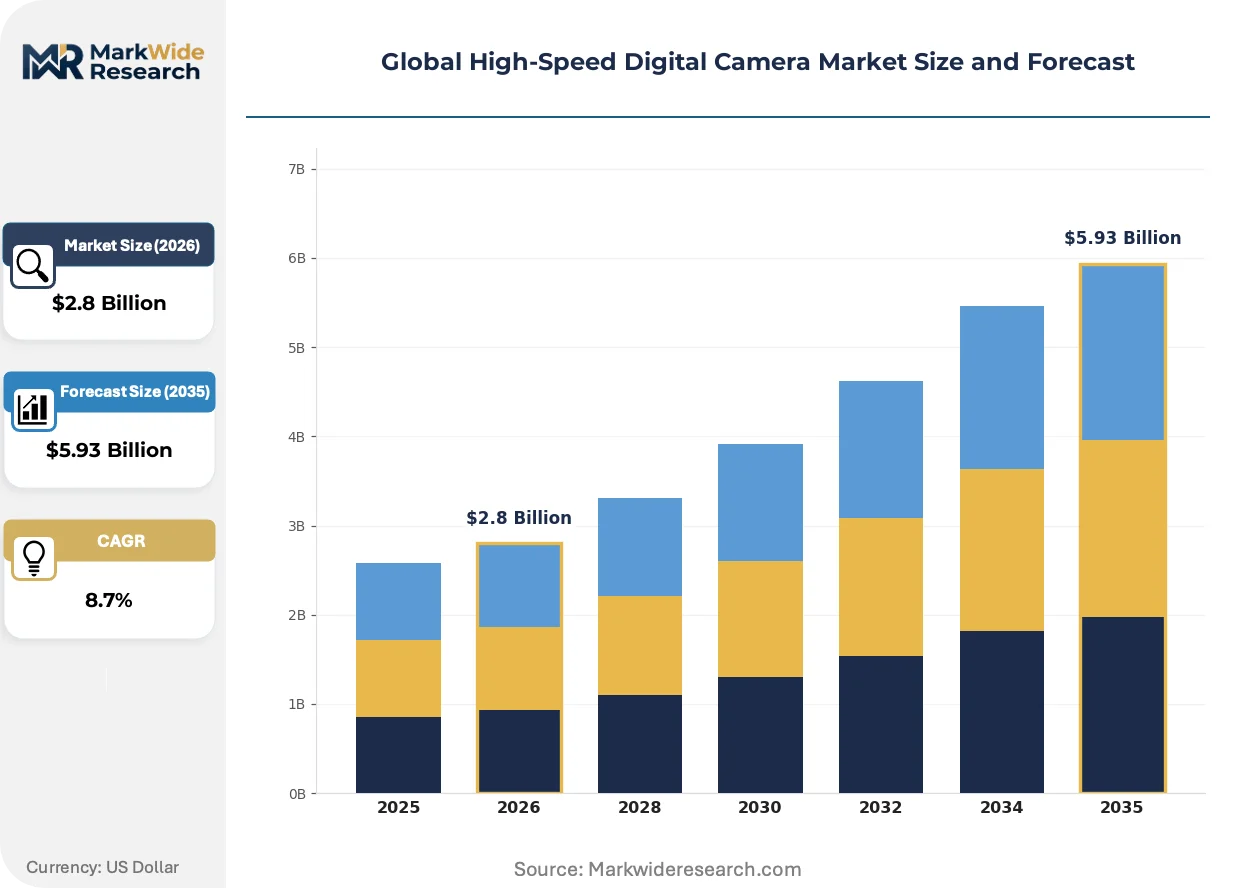
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DSLR, Mirrorless, Compact, Action Camera End User: Sports, Film Production, Scientific Research, Industrial Testing Resolution: Full HD, 4K, 8K, 12MP Feature: Slow Motion, High Frame Rate, Low Light Performance, Live Streaming |
| Companies Covered | AOS Technologies AG, Mikrotron GmbH, Photron Limited, DEL Imaging Systems, Optronis GmbH, Vision Research, Fastec Imaging Corporation, Teledyne Technologies, NAC Image Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High-Speed Digital Camera Market Emerging Trajectories
Sensor architecture evolution and regulatory harmonization pressures are converging to redefine performance benchmarks and commercialization pathways across scientific and industrial deployment contexts.
Backside-illuminated CMOS sensors with global shutter designs are overtaking frontside-illuminated alternatives in scientific instrumentation. Physics laboratories and materials science facilities in Switzerland and the United States have standardized procurement around these architectures for 2024-2025 equipment refreshes. The transition is compressing acceptable signal-to-noise ratio thresholds by half while extending viable exposure latitude into single-digit lux conditions.
Japan's METI Top Runner standards now mandate standby power ceilings for laboratory imaging suites that constrain idle-state energy draw. Equipment vendors serving Japanese research institutions must redesign power management subsystems or forfeit eligibility for public procurement tenders. This regulatory pressure is propagating efficiency specifications into product lines destined for European and North American markets through platform standardization.
Automotive crash-test centers are consolidating vendor relationships around integrated service contracts that bundle hardware, calibration, and predictive maintenance. Tier-1 suppliers in Stuttgart and Detroit have displaced transactional purchasing with multi-year performance agreements tied to uptime guarantees. This behavioral shift concentrates procurement authority among facilities directors rather than decentralized engineering teams.
Global High-Speed Digital Camera Market Segmentation
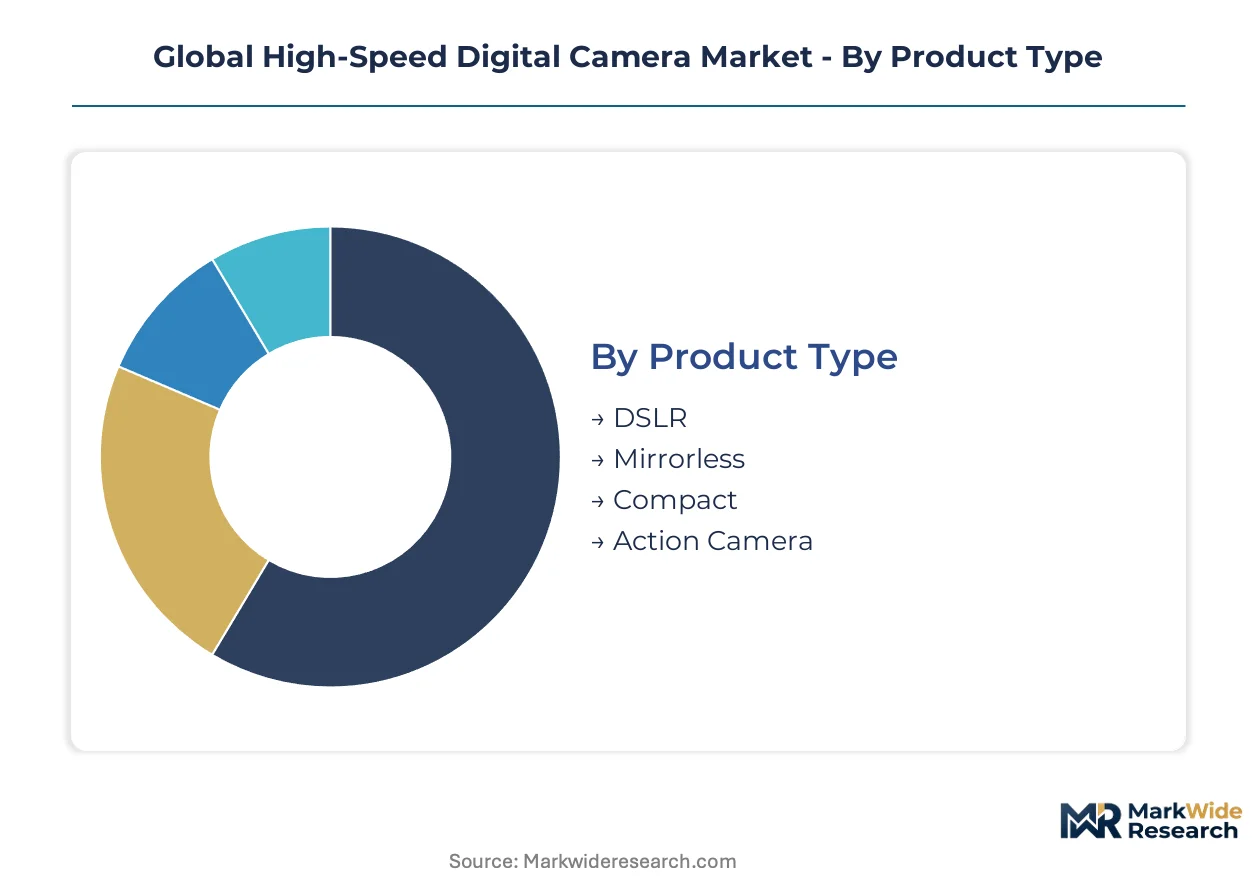
High-speed digital camera procurement patterns diverge sharply between standalone scientific instruments and embedded industrial vision systems. Understanding these integration-depth distinctions enables vendors to align sensor architectures, firmware capabilities, and service models with actual deployment contexts.
Product Type:
Standalone camera bodies dominate laboratory and field research deployments, while compact and action variants increasingly embed directly into automated production lines and vehicle platforms.
- DSLR:Optical viewfinder architectures with mechanical mirror assemblies deliver sub-50 microsecond trigger latency for ballistics and combustion studies. German defense laboratories and Japanese automotive crash-test centers specify these for hypersonic projectile visualization where electronic viewfinder lag is unacceptable.
- Mirrorless:Elimination of mechanical vibration enables continuous autofocus tracking at 10,000+ fps for fluid dynamics and materials characterization. Swiss materials science facilities and Michigan automotive safety labs have standardized procurement around these architectures for 2024-2025 equipment refreshes.
- Compact:Fixed-lens designs with integrated power management suit inline semiconductor wafer inspection in Taiwanese and South Korean fabrication facilities.
- Action Camera:Ruggedized enclosures with native waterproofing deploy in outdoor ballistics ranges and environmental testing chambers across Arizona and New Mexico.
Mirrorless architectures lead volumes today; compact form factors for industrial embedding are gaining share fastest.
End User:
Cost tier stratification separates capital-intensive scientific procurement from volume-driven industrial and content production segments.
- Sports:Broadcast clients demand 4K chroma sampling fidelity at 240-1000 fps for replay systems. Stadium infrastructure upgrades in Qatar and Saudi Arabia are driving specification pulls for slow-motion functionality.
- Film Production:Cinema clients prioritize 4K and 8K resolution tiers with RAW output for color grading latitude. Los Angeles and London production houses anchor demand for frame rates above 120 fps.
- Scientific Research:Physics and materials science facilities require sub-100 nanosecond exposure times through intensified or streak architectures. Berkeley and Zurich laboratories specify backside-illuminated CMOS with global shutter designs.
- Industrial Testing:Semiconductor fabs and automotive validation centers need sub-microsecond capture precision with predictive maintenance integration. Stuttgart and Detroit safety labs consolidate around multi-year performance agreements.
Scientific Research commands premium pricing today; Industrial Testing is climbing the fastest as manufacturing automation accelerates.
Resolution:
Application-specific bandwidth constraints and display ecosystem compatibility shape resolution procurement patterns across deployment contexts.
- Full HD:1920x1080 formats dominate legacy industrial vision systems where data throughput bottlenecks constrain real-time streaming above 100,000 fps. Older automotive crash-test installations in Germany retain these specifications.
- 4K:3840x2160 captures disproportionate margin pools as broadcast and cinema clients demand chroma sampling fidelity unavailable at lower resolutions. Tokyo and Burbank production facilities anchor volume concentration.
- 8K:7680x4320 enables crop flexibility and downstream reframing for scientific visualization where single-capture events preclude retakes. NASA and CERN facilities specify these for combustion and particle tracking studies.
- 12MP:Stills-optimized architectures with burst modes suit hybrid scientific documentation workflows in field biology and astronomy applications across Chile and Hawaii observatories.
4K leads installed base today; 8K is expanding most quickly in scientific and premium broadcast segments.
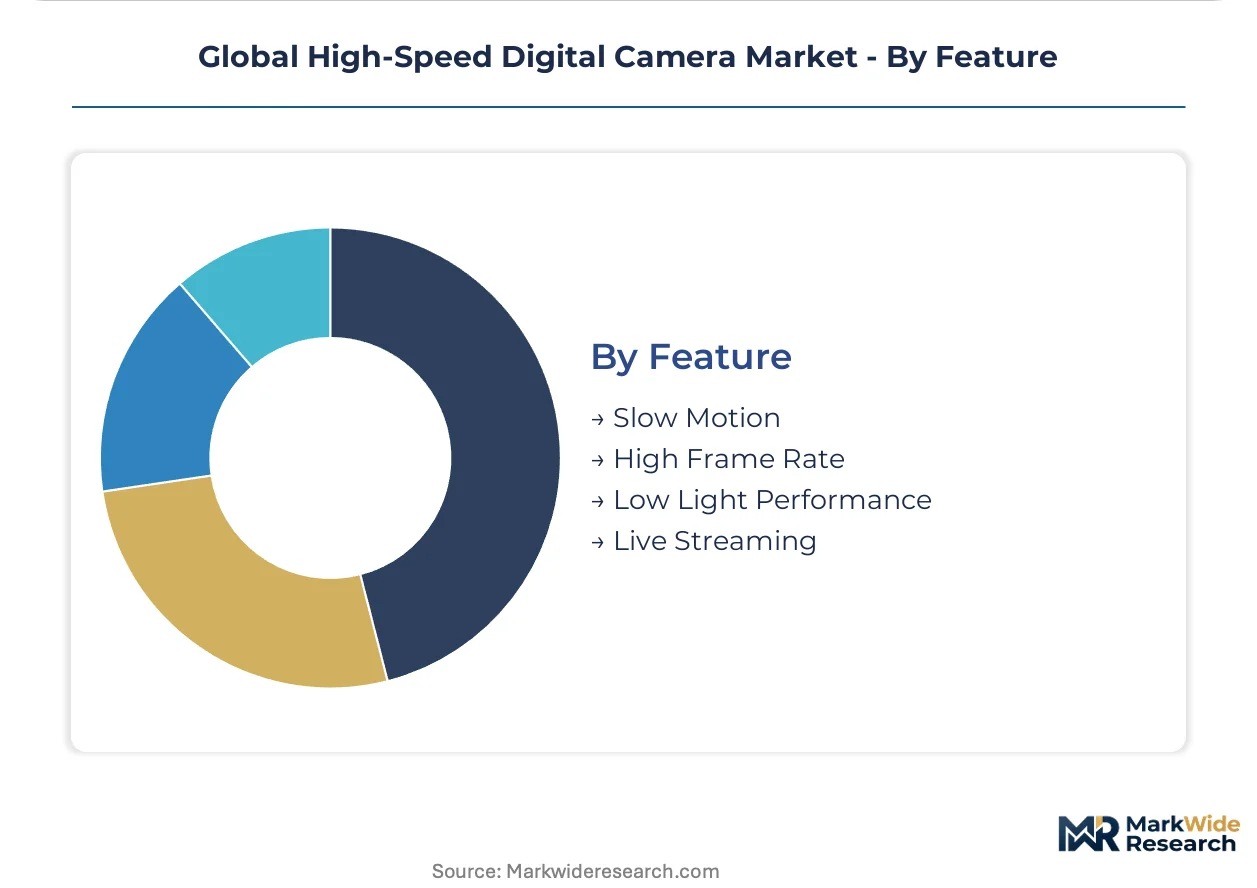
Feature:
Customer type differentiation separates entertainment-oriented functionality from performance specifications demanded by defense and research institutions.
- Slow Motion:Frame rate multiplication remains the dominant specification across sports and film production end users. Broadcast infrastructure in Qatar and Saudi Arabia prioritizes 1000+ fps replay capability.
- High Frame Rate:Sustained capture above 10,000 fps with global shutter enables transient event analysis in ballistics and fluid dynamics. German and Japanese defense laboratories anchor procurement concentration.
- Low Light Performance:Single-digit lux sensitivity with extended exposure latitude addresses defense and astronomy applications. Hawaii and Chile observatories specify these for adaptive optics and atmospheric monitoring.
- Live Streaming:Real-time transmission without downstream server dependency supports edge AI inference for predictive maintenance. Taiwanese semiconductor fabs integrate these for inline defect detection.
Slow Motion dominates feature prioritization today; Low Light Performance is gaining specification weight fastest in defense and scientific procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters anchor procurement concentration for high-speed digital cameras, with semiconductor fabrication and automotive validation driving specification intensity across Taiwan, South Korea, and Japan.
United States
Berkeley and Los Alamos defense laboratories scale high-frame-rate procurement for hypersonic projectile visualization and combustion dynamics studies. FCC equipment authorization governs electromagnetic emissions for aerospace testing environments. Michigan automotive safety labs consolidate around multi-year performance agreements with integrated service contracts.
Germany
Stuttgart crash-test centers and Munich-area semiconductor equipment vendors demand sub-microsecond capture precision for wafer inspection and defect analysis. CE marking under the EU's Radio Equipment Directive shapes market access for scientific instrument vendors. Bavarian materials science facilities have standardized procurement around backside-illuminated CMOS architectures for 2024-2025 equipment refreshes.
Japan
Tokyo and Osaka production houses anchor volume concentration for 4K and 8K resolution tiers with RAW output requirements. METI enforces energy efficiency benchmarks through Top Runner standards that constrain standby power in laboratory imaging suites. Nagoya-area automotive validation centers require synchronized multi-camera arrays at 10,000+ fps for sensor fusion testing.
South Korea
Suwon and Pyeongtaek semiconductor foundries drive tooling refresh cycles shortened to 18-24 months for sub-microsecond capture precision. The country's national industrial regulator mandates alignment with harmonized IEC imaging standards for export-oriented equipment. Busan manufacturing corridors attract dedicated service center investments from high-speed camera vendors.
Taiwan
Hsinchu Science Park fabrication facilities require inline defect detection systems with edge AI inference integration for predictive maintenance. Bureau of Standards, Metrology and Inspection (BSMI) certification requirements shape procurement specifications for domestic electronics manufacturing. Tainan and Taichung industrial clusters concentrate demand for compact form factors purpose-built for automated production lines.
Global High-Speed Digital Camera Market Vendor Landscape
Global majors compete with regional champions across sensor architecture specialization and service network density. The vendor base stratifies into three tiers: in-house sensor fabricators commanding ultra-high-speed pricing power, dedicated industrial vision specialists with Asia-Pacific service footprints, and compact-form-factor engineers targeting inline inspection deployments. Dominant competitive moves include captive supply of CMOS backside-illumination designs and backward integration into FPGA-based image processing firmware.
Within the premium-tier vector, Vision Research and Photron Limited exemplify contrasting geographic anchoring strategies, while Mikrotron GmbH occupies a position representing German precision-engineering specialization in compact industrial deployments. AOS Technologies AG and Optronis GmbH sit within the European specialist tier alongside NAC Image Technology's Japanese heritage positioning. Fastec Imaging Corporation and DEL Imaging Systems represent North American mid-scale fabrication, with Teledyne Technologies anchoring the diversified technology conglomerate archetype through platform breadth rather than imaging-specific focus.
| Leading Market Players |
|---|
| AOS Technologies AG |
| Mikrotron GmbH |
| Photron Limited |
| DEL Imaging Systems |
| Optronis GmbH |
| Vision Research |
| Fastec Imaging Corporation |
| Teledyne Technologies |
| NAC Image Technology |
| Others |
Supply Flow & Price Mechanics
FPGA firmware engineering talent concentrated in Munich and Stuttgart feeds into pricing-tier spreads across German industrial vision deployments, with labor-cost differentials between Bavarian engineering clusters and Taiwanese manufacturing corridors compressing margin structures at the mid-market tier.
Pricing Analysis
Input-cost pass-through from rare-earth element dependencies in intensifier tubes and precision glass supply constraints drives three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—CE marking under the EU Radio Equipment Directive commands premium positioning—and volume scale for semiconductor fab tooling contracts. Cost compression in the standard tier is intensifying because CMOS backside-illumination architectures collapse cost-per-frame thresholds. Automotive crash-test centers in Stuttgart and Detroit exhibit lowest price sensitivity due to multi-year performance agreements, while broadcast clients in emerging stadium infrastructure segments negotiate hardest on unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by Japanese defense laboratories and German automotive safety labs force qualification of multiple CMOS sensor suppliers across Taiwan, South Korea, and Japan. Raw material dependencies center on gallium arsenide substrates for high-speed photodiodes, rare-earth elements for optical glass, and copper-clad laminates for FPGA carrier boards. Single-source vulnerability concentrates in advanced CMOS fabrication capacity, exposing procurement timelines to geopolitical transit risks. Distribution runs through authorized service centers in Asia-Pacific manufacturing corridors, with calibration and predictive maintenance bundled into integrated performance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
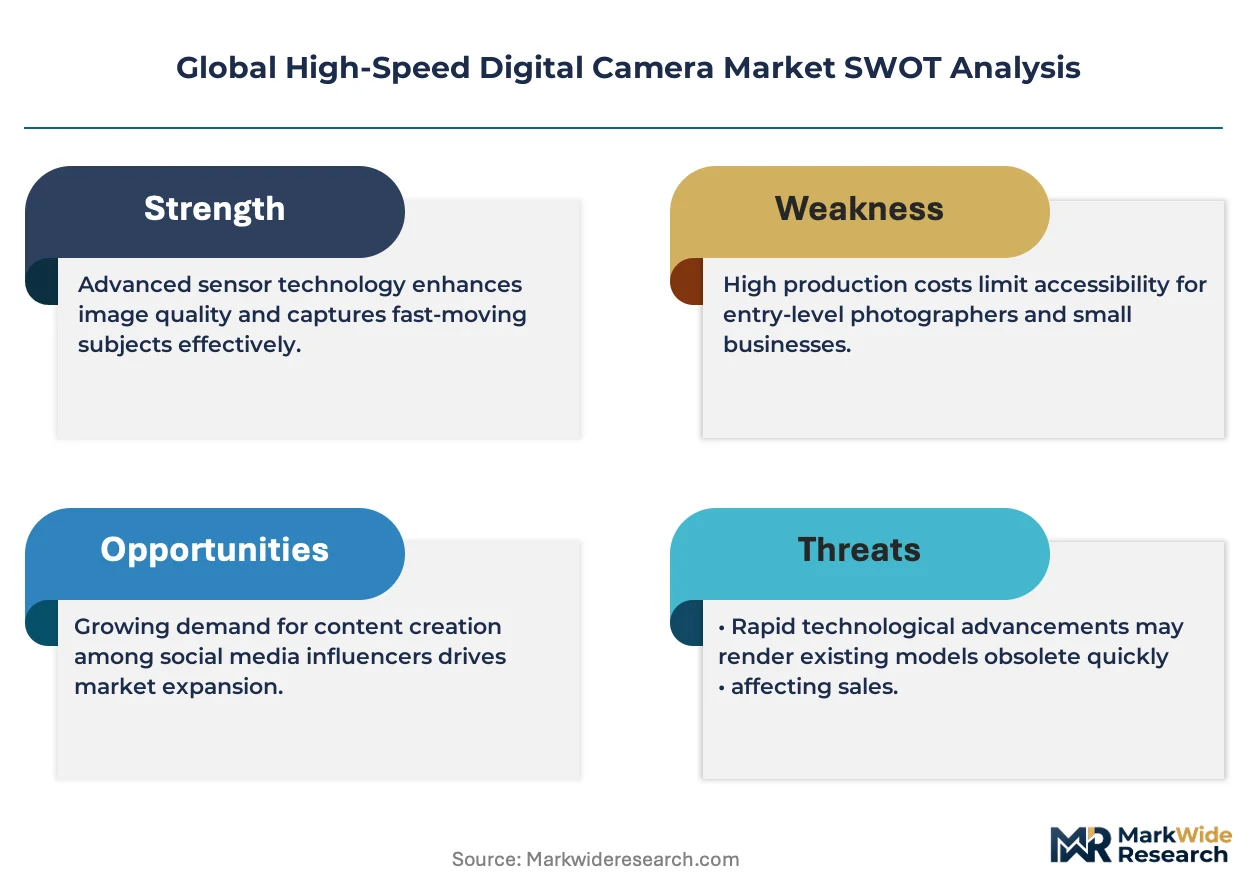
This market functions as a geographic-arbitrage play: METI Top Runner standby power mandates in Japan propagate efficiency specifications into European and North American product lines through platform standardization, compressing R&D cost duplication.
For Market Incumbents: Acquire captive CMOS backside-illumination fabrication capacity to defend pricing power against Vision Research's in-house sensor architecture. Consolidate service network density in Busan and Hsinchu manufacturing corridors to lock in multi-year performance agreements before emerging industrial vision specialists establish calibration presence. Counter the threat of computational imaging convergence by embedding edge AI inference modules directly into firmware pipelines.
For New Entrants and Emerging Players: Tier-2 semiconductor foundries in India represent the most penetrable buyer archetype ahead of PLI scheme demand maturation, with local calibration and service presence creating first-mover advantage. Target autonomous vehicle validation labs in Michigan and Germany with synchronized multi-camera array specifications at 10,000+ fps. Pursue a hardware-as-a-service go-to-market angle bundling predictive maintenance to bypass capital-constrained procurement committees.
For Investors and Strategic Acquirers: Valuations sit cheapest among compact-form-factor specialists with Asia-Pacific service footprints but limited sensor fabrication backward integration. Long-term viability over a five-to-ten-year window favors vendors controlling FPGA-based image processing firmware rather than pure hardware assemblers. Watch for inflection when EU AI Act algorithmic transparency requirements trigger replacement cycles in automotive automated visual inspection systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive CMOS Sensor Fabrication | Vision Research sustains ultra-high-speed pricing power through in-house backside-illumination production. |
| Asia-Pacific Service Center Expansion | Photron Limited anchors market position through dedicated calibration facilities in Busan manufacturing corridors. |
| Edge AI Firmware Integration | Real-time anomaly detection without downstream server dependency opens predictive maintenance in Taiwanese semiconductor fabs. |
| Multi-Jurisdiction Certification Pre-Qualification | Simultaneous FCC, CE marking, and METI compliance compresses rival launch schedules by 8-14 months. |
| Integrated Performance Contract Bundling | Stuttgart and Detroit safety labs displace transactional purchasing with uptime-guaranteed multi-year agreements. |
Methodological Framework
Direct dialogue with high-speed camera product managers, semiconductor fab tooling procurement leads, automotive safety lab facilities directors, and FPGA firmware engineering specialists grounded qualitative findings in deployment-specific constraints. Secondary validation drew from FCC equipment authorization filings, METI Top Runner compliance disclosures, EU CE marking registries, and SEC 10-K filings from diversified technology conglomerates with imaging divisions. Bottom-up and top-down triangulation reconciled unit shipment estimates from fabrication facility tooling refresh cycles with aggregate market sizing derived from scientific instrumentation procurement databases.
Bottom-up modeling segmented volume and value outputs across product type, resolution tier, end-user vertical, and regional regulatory cluster throughout the forecast period. CAGRs were derived from weighted averages of segment-specific growth trajectories, with semiconductor fabrication demand intensity and EU AI Act compliance-driven replacement cycles serving as primary forecast inputs. Top-down cross-checks against aggregate scientific instrumentation spending patterns ensured methodological consistency.
Underlying measurement precision varies by segment; scientific research procurement with standardized tender documentation carries tighter precision than decentralized industrial vision deployments. Forecasts reflect assumptions around CMOS sensor supply continuity, harmonized IEC imaging standard propagation, and sustained defense laboratory funding for ballistics visualization. Deviation in Taiwan Strait transit stability or export control variability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Digitizer Market
Imaging
Vision Processing Unit Market
Imaging
Chemiluminescence Imaging Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Industrial Camera Market
Imaging
SDI Camera Market
Imaging
Holotomographic Imaging Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Weatherproof Camera Market
Imaging
Silent Scan Technology Market
Imaging
Vintage Cameras Market
Imaging
Global Computed Radiography Market
Imaging
CCD Image Sensors Market
Imaging
Handheld Backscatter X-Ray Devices Market