
 Handheld Imager Market | 2026-2036
Handheld Imager Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Imager Market Analysis
Market Context
The premium thermal resolution tier is rotating toward 640×480 and higher sensor arrays as industrial buyers reject entry-level 320×240 units for predictive maintenance workflows. Teledyne FLIR leverages captive wafer fabrication to sustain margin control across infrared detector supply. Robert Bosch GmbH anchors European industrial distribution through its measurement tools division. Leonardo SpA competes in defense-grade thermal monoculars with ITAR-calibrated supply chains.
Technical Definition and Segment Structure
A handheld imager denotes a portable electro-optical device integrating focal plane array sensors, onboard signal processing, and battery-powered operation for real-time image capture outside fixed installations. CMOS imagers lead document scanning and barcode capture due to low power draw and direct digital output, while thermal imagers command the highest unit economics in industrial inspection and security surveillance applications. Infrared technology dominates security and industrial end uses, whereas visible light sensors saturate medical diagnostics and academic research segments where color fidelity governs diagnostic validity.
Regulatory Frame and Outlook
The FDA governs medical handheld imagers through 510(k) premarket notification pathways for diagnostic applications, while the FCC regulates radio-frequency emissions from wireless-enabled units deployed in security and logistics. The EU AI Act imposes conformity assessment obligations on biometric identification imagers, restricting market access for non-compliant hardware. Stakeholders must monitor evolving classification thresholds under the EU MDR for thermal imagers claiming clinical diagnostic utility.
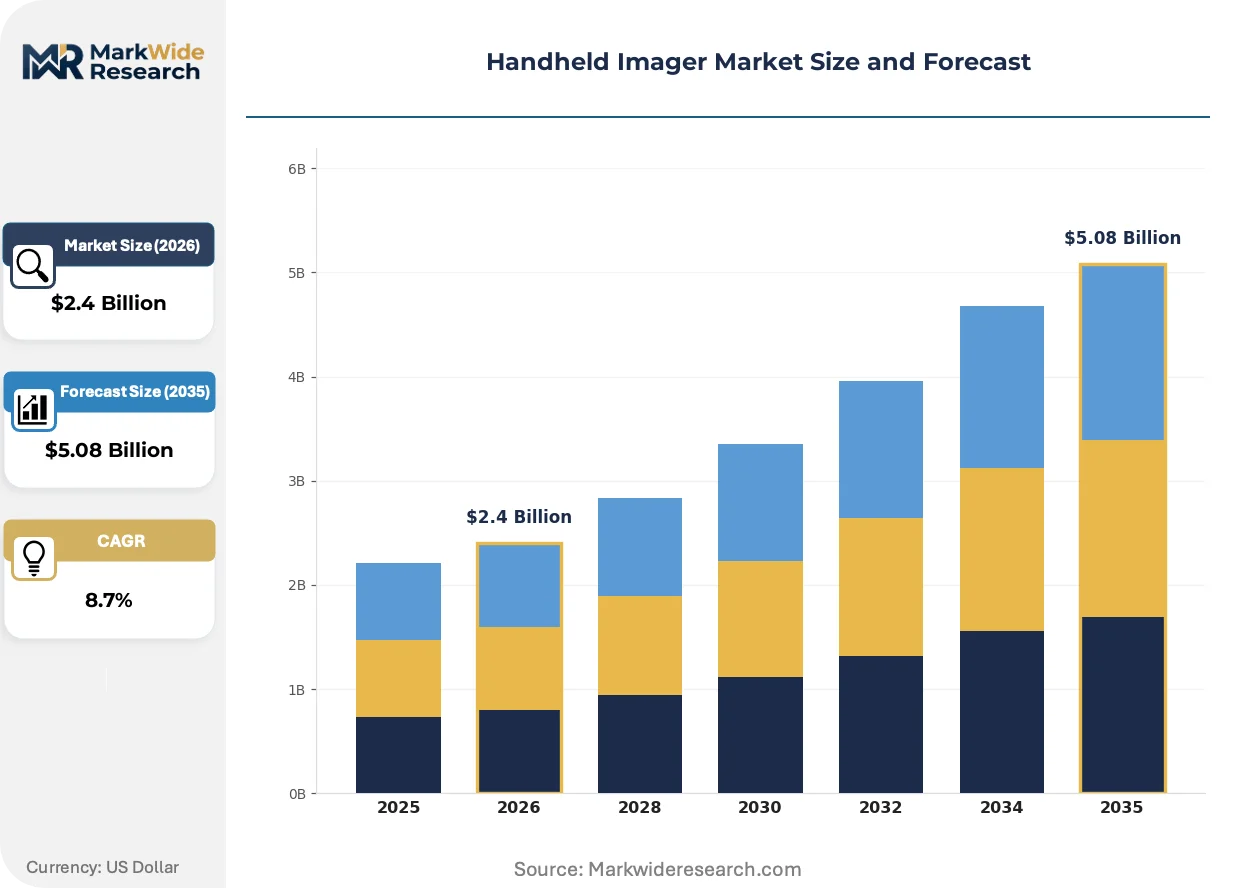
Market Dynamics
The handheld imager market is undergoing sensor resolution polarization as industrial buyers abandon entry-tier thermal arrays for 640×480 and higher specifications, compressing mid-tier vendor margins while rewarding captive wafer producers.
Growth Catalysts
- EU AI Act compliance mandates:Biometric-enabled handheld devices face mandatory conformity assessments, creating replacement demand for certified hardware across European security agencies.
- Predictive maintenance digitization:Manufacturing facilities are deploying thermal imagers for electrical and mechanical fault detection, displacing scheduled inspection routines with condition-based monitoring.
- Law enforcement thermal adoption:Night-vision procurement for surveillance and search operations is accelerating in Germany, France, and Italy as agencies modernize field equipment.
Market Restraints
- Indium antimonide supply concentration:High-performance infrared detector materials depend on limited raw material sources, exposing manufacturers to price volatility and geopolitical sourcing risk.
- ITAR-calibrated supply chain lockout:Defense-grade thermal monoculars require US State Department export licensing, excluding non-US allies from premium defense procurement channels.
- Smartphone thermal attachment substitution:Low-cost plug-in thermal cameras for consumer handsets are capturing price-sensitive inspection segments previously served by dedicated devices.
Strategic Opportunities
- Clinical diagnostic thermal imaging:Thermal imagers claiming fever screening or vascular assessment utility can pursue FDA 510(k) pathways to access hospital and clinic procurement budgets.
- Wireless-enabled logistics scanners:CMOS imagers with embedded cellular connectivity are penetrating last-mile delivery verification workflows previously dominated by tethered barcode systems.
- EU Green Deal industrial retrofit mandates:Building energy audit requirements in Germany and France are stimulating demand for thermal inspection services and associated hardware.
Industry Challenges
- Multispectral algorithm development:Fusing thermal and visible-light data streams requires scarce machine-vision engineering talent, slowing product development cycles for integrated platforms.
- EU MDR classification uncertainty:Thermal imagers with diagnostic claims face evolving medical device regulatory thresholds, extending time-to-market for clinical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Imager Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Imagers, CCD Imagers, CMOS Imagers, Thermal Imagers Application: Medical Diagnostics, Industrial Inspection, Document Scanning, Security Surveillance Technology: Infrared, Visible Light, X-ray, Ultraviolet End User: Healthcare Professionals, Manufacturing Engineers, Law Enforcement, Academic Researchers |
| Companies Covered | Fluke Corporation, Teledyne FLIR LLC, Robert Bosch GmbH, BAE Systems PLC, Leonardo DRS, Inc., Zebra Technologies Corp., General Dynamics Corporation, Leonardo SpA, Opgal Optronic Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Imager Market Emerging Trajectories
Thermal sensor technology is polarizing around resolution tiers while regulatory frameworks fragment compliance requirements across medical, security, and industrial deployment contexts.
Uncooled vanadium oxide microbolometer arrays are bifurcating the industrial inspection segment. Predictive maintenance teams at German automotive and chemical plants are specifying 640×480 resolution as minimum viable, forcing vendors to abandon 320×240 product lines or retreat to consumer markets. This resolution escalation is compressing mid-tier supplier margins while concentrating volume with captive wafer fabricators.
EU AI Act biometric identification restrictions are reshaping security hardware deployment. Handheld imagers with facial recognition capabilities now require notified body conformity assessment before EU market entry, adding certification cost and timeline risk. German federal police procurement tenders are prioritizing pre-certified devices, disadvantaging suppliers without established EU regulatory infrastructure.
Inspection service unbundling is altering industrial buyer relationships. German manufacturing facilities are separating thermal imager hardware acquisition from predictive maintenance software subscriptions, forcing equipment vendors to defend position through sensor performance rather than bundled analytics. This disaggregation is visible in Rhine-Ruhr industrial cluster procurement patterns, where buyers source imagers from measurement specialists and analytics from industrial IoT platforms.
Handheld Imager Market Segmentation
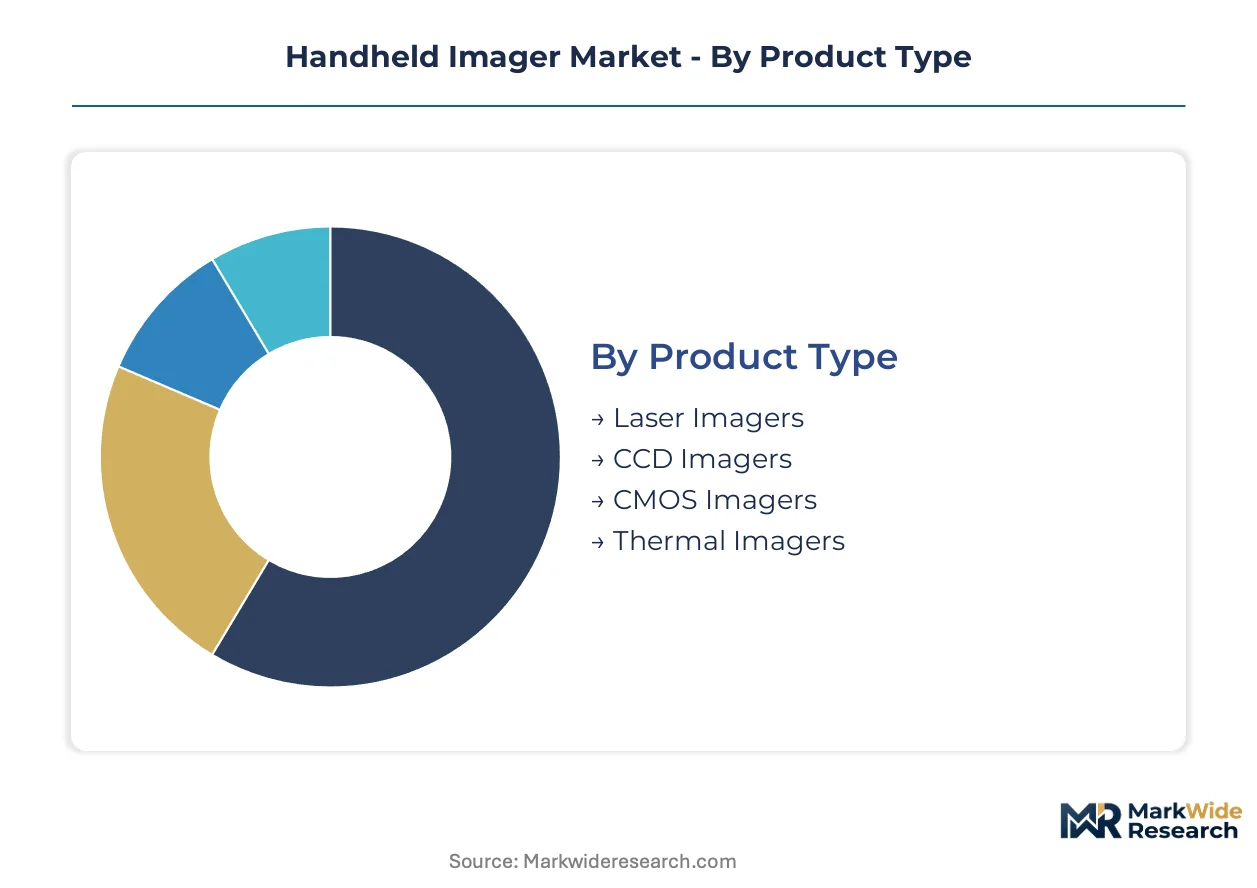
Resolution tiers and regulatory compliance requirements fragment the handheld imager market into distinct procurement channels. Each segment carries specific certification burdens and margin structures that reshape vendor positioning across medical, industrial, and security deployment contexts.
Product Type:
Margin pools concentrate in thermal and CMOS architectures where sensor fabrication scale and software integration create defendable positions.
- Thermal Imagers:Uncooled vanadium oxide microbolometer arrays with 640×480 resolution minimum now dominate industrial predictive maintenance contracts. German automotive and chemical facilities specify these units for electrical fault detection, displacing scheduled inspection routines with continuous thermal monitoring.
- CMOS Imagers:Low-power complementary metal-oxide-semiconductor sensors with direct digital output enable wireless-enabled logistics scanners. Last-mile delivery verification workflows in France and Italy are adopting cellular-connected units previously served by tethered barcode systems.
- CCD Imagers:Charge-coupled device sensors retain niche medical and scientific applications where quantum efficiency and noise characteristics outweigh power constraints.
- Laser Imagers:Time-of-flight and structured light configurations serve precision measurement tasks in construction surveying and dimensional quality control.
Thermal imagers hold installed capacity in industrial security procurement. CMOS imagers are rotating up the share rankings in logistics automation.
Application:
End-use concentration varies sharply by certification pathway, with medical and security applications imposing the steepest compliance costs.
- Industrial Inspection:Predictive maintenance digitization drives specification escalation toward higher-resolution thermal arrays. German facilities under EU Green Deal energy audit mandates source imagers for building envelope and electrical system assessment.
- Security Surveillance:Night-vision procurement accelerates among law enforcement agencies in Germany, France, and Italy. EU AI Act conformity assessment requirements now restrict biometric-enabled device deployment to pre-certified hardware.
- Medical Diagnostics:Fever screening and vascular assessment applications face FDA 510(k) and EU MDR classification uncertainty, extending time-to-market for clinical thermal platforms.
- Document Scanning:Portable digitization for field insurance adjusters and mobile notary services demands compact CMOS architectures with automatic document detection.
Industrial inspection holds installed capacity in manufacturing procurement budgets. Security surveillance is rotating up the share rankings with EU defense modernization tenders.
Technology:
Sensor physics determines addressable market scope, with infrared commanding premium unit economics in non-visible spectrum applications.
- Infrared:Thermal radiation detection spans near-infrared active illumination through long-wave infrared passive imaging. Security and industrial end uses dominate volume, with uncooled microbolometers displacing cooled indium antimonide in all but defense-grade applications.
- Visible Light:Silicon photodiode arrays in CMOS and CCD architectures saturate medical diagnostics and academic research where color fidelity governs diagnostic validity. Bayer filter patterns and RAW output capabilities differentiate professional-grade units.
- Ultraviolet:UV-A and UV-C imaging serves forensic evidence detection and semiconductor wafer inspection where fluorescence excitation reveals surface contamination.
- X-ray:Portable digital radiography systems with CMOS or TFT flat-panel detectors penetrate non-destructive testing and security screening where penetration depth exceeds optical methods.
Infrared technology holds installed capacity in thermal imaging procurement. Visible light sensors are rotating up the share rankings with clinical diagnostic platform integration.
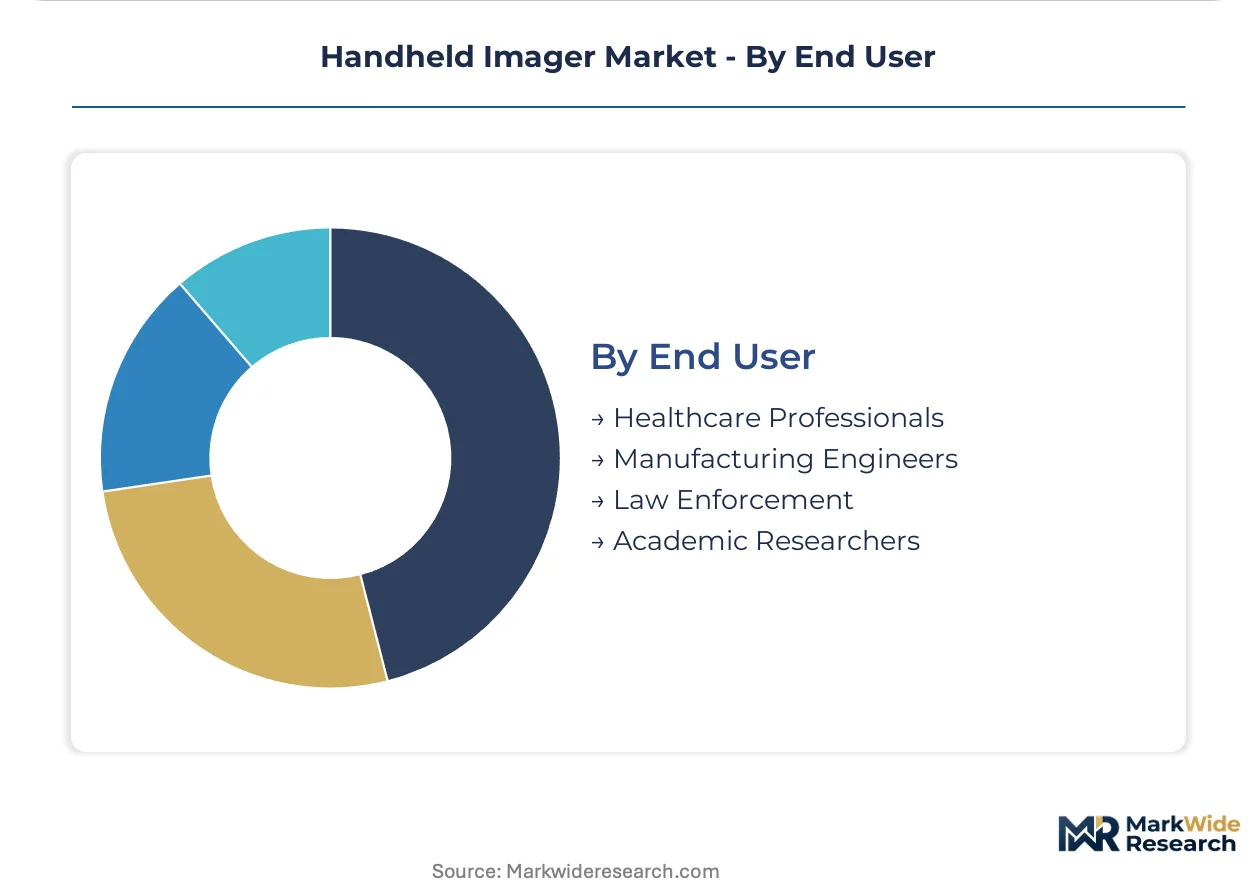
End User:
Professional credential requirements and procurement authorization levels segment demand by buyer sophistication and contract scale.
- Manufacturing Engineers:Condition-based monitoring programs specify thermal imagers with analytics integration. Rhine-Ruhr industrial cluster procurement separates hardware acquisition from predictive maintenance software subscriptions.
- Law Enforcement:Federal police tenders in Germany prioritize EU AI Act pre-certified biometric devices. ITAR-calibrated supply chains exclude non-US allies from certain defense-grade thermal monocular procurement channels.
- Healthcare Professionals:Hospital procurement committees evaluate thermal imagers for fever screening and vascular assessment against FDA 510(k) clearance status and clinical validation literature.
- Academic Researchers:Visible-light and hyperspectral configurations support laboratory protocols where spectral resolution and quantitative radiometry outweigh ruggedization requirements.
Manufacturing engineers hold installed capacity in industrial measurement procurement. Law enforcement agencies are rotating up the share rankings with security modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication for infrared detectors concentrates in the United States, Germany, and Japan, creating geographic dependency for thermal imager supply chains. Component assembly and system integration distribute across multiple manufacturing clusters. Regulatory fragmentation across FDA, EU AI Act, and ITAR jurisdictions shapes market access patterns.
United States
Defense procurement drives demand for cooled indium antimonide detectors in night-vision applications. The FDA governs medical handheld imagers through 510(k) premarket notification pathways. Boston-area defense contractors supply ITAR-restricted thermal monoculars to federal law enforcement agencies.
Germany
EU Green Deal energy audit mandates stimulate thermal inspection hardware acquisition for building envelope assessment. The EU AI Act imposes conformity assessment obligations on biometric-enabled devices, restricting non-certified hardware from federal police tenders. Rhine-Ruhr industrial cluster procurement separates imager hardware from predictive maintenance software subscriptions.
France
Law enforcement agencies modernize field equipment with night-vision thermal systems for surveillance operations. CE marking and EU AI Act compliance requirements filter market access for biometric identification devices. Paris-region security integrators specify pre-certified handheld imagers for municipal police contracts.
Japan
Automotive and electronics manufacturing facilities deploy thermal imagers for predictive maintenance of electrical systems. METI industrial efficiency programs encourage condition-based monitoring adoption. Nagoya-area automotive plants specify 640×480 resolution minimums for production line thermal inspection.
China
Domestic uncooled microbolometer production scales for industrial and security applications. NMPA medical device regulations govern clinical thermal imager market entry. Yangtze River Delta manufacturing clusters source locally fabricated thermal sensors for building inspection and electrical fault detection workflows.
Handheld Imager Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the handheld imager market. Captive wafer fabricators command margin control in thermal sensor supply while mid-tier assemblers face compression from resolution escalation demands. The vendor base stratifies into defense-grade specialists with ITAR-calibrated supply chains, industrial measurement tool conglomerates with distribution scale, and component-focused sensor technology developers. Competitive moves concentrate on backward integration into detector fabrication and regulatory pre-certification investments for EU market access.
Within the defense-grade specialist tier, BAE Systems PLC and Leonardo SpA exemplify ITAR-constrained positioning for thermal monocular procurement channels. Among industrial measurement specialists, Fluke Corporation and Robert Bosch GmbH occupy positions anchored by distribution infrastructure and predictive maintenance service relationships. Teledyne FLIR LLC sits within the captive fabrication archetype, controlling infrared detector supply through in-house wafer production.
| Leading Market Players |
|---|
| Fluke Corporation |
| Teledyne FLIR LLC |
| Robert Bosch GmbH |
| BAE Systems PLC |
| Leonardo DRS, Inc. |
| Zebra Technologies Corp. |
| General Dynamics Corporation |
| Leonardo SpA |
| Opgal Optronic Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Uncooled vanadium oxide microbolometer arrays are displacing cooled indium antimonide detectors across industrial inspection segments, simultaneously shifting fabrication gravity toward the United States and China while compressing unit cost structures for mid-tier thermal imager vendors.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for biometric-enabled handheld devices entering European security procurement channels. Three-tier pricing stratifies across ITAR-restricted defense-grade thermal monoculars, EU AI Act pre-certified law enforcement units, and uncertified commercial inspection hardware. Price differentiation hinges on certification grade and captive wafer fabrication status. Cost compression in the mid-tier industrial segment is intensifying because manufacturing facilities are unbundling hardware acquisition from predictive maintenance software subscriptions. Price-sensitive buyers in building energy audit services prioritize resolution-per-dollar metrics, while defense procurement committees exhibit minimal price elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate infrared detector procurement as manufacturers buffer against indium antimonide supply volatility. Wafer fabrication concentrates in the United States, Germany, and Japan, with component assembly distributing across Mexico and Vietnam. Raw material dependencies include germanium substrates, indium antimonide crystals, and vanadium oxide thin-film deposition targets. Single-source vulnerability in cooled detector materials exposes vendors to geopolitical sourcing risk. Distribution runs through industrial measurement tool conglomerates for predictive maintenance segments and defense contractors for ITAR-restricted channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The handheld imager market sits in a cyclical recovery phase driven by EU defense modernization budgets and Green Deal energy audit mandates. Procurement authorization cycles favor vendors with pre-certified regulatory infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into uncooled microbolometer wafer fabrication and accelerated EU AI Act conformity assessment investments. Smartphone thermal attachment substitution threatens entry-tier product lines. Captive detector supply and notified body relationships represent the critical levers for margin defense. For New Entrants and Emerging Players: Differentiate on clinical diagnostic thermal imaging applications pursuing FDA 510(k) pathways where incumbent certification coverage remains sparse. The most penetrable white space sits in wireless-enabled logistics scanners for last-mile delivery verification in France and Italy. A direct hospital procurement engagement model bypasses established industrial distribution channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors captive fabrication specialists over assembly-dependent mid-tier vendors. Long-term viability over the next decade rests on regulatory pre-certification moats and sensor technology IP. The signal to watch is EU MDR classification threshold revisions for clinical thermal platforms, which would trigger accelerated M&A in diagnostic imaging capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | Notified body certification unlocks German federal police procurement tenders. |
| Backward Integration into Detector Fabrication | Captive wafer production insulates margins from indium antimonide price volatility. |
| Clinical Diagnostic Platform Development | FDA 510(k) clearance accesses hospital procurement budgets for fever screening applications. |
| Predictive Maintenance Software Unbundling | Hardware-only positioning defends sensor performance differentiation against industrial IoT platforms. |
| ITAR-Calibrated Supply Chain Investment | US State Department licensing enables defense-grade thermal monocular procurement channels. |
Methodological Framework
Operator-level perspectives from maintenance directors at German automotive plants, federal police procurement officers, hospital biomedical engineers, and thermal inspection service providers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU notified body certification databases, and customs trade data for infrared detector components. Bottom-up unit shipment estimates and top-down market value triangulation cross-verified segmentation outputs.
Sensitivity analysis tested forecast robustness across resolution tier adoption curves and regulatory compliance timeline scenarios. The analytical framework modeled product type, application, technology, and end user dimensions across the projection horizon. CAGRs derived from segment-level growth rate blending with macroeconomic intensity factors. Industry-specific inputs included EU Green Deal building retrofit targets and law enforcement equipment modernization budget authorizations.
Material uncertainties — indium antimonide supply disruptions, EU MDR classification threshold revisions, and ITAR licensing policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued uncooled microbolometer cost reduction and stable transatlantic defense procurement relationships. Revision becomes warranted when EU AI Act enforcement intensity crosses thresholds that exclude non-compliant hardware from security tenders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global in Ceiling Camera Market
Imaging
Digital Camera Market
Imaging
Camera Stabilizer Market
Imaging
Photo Kiosk Market
Imaging
Document Imaging Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Hyperspectral Cameras Market
Imaging
Infrared Imaging Software Market
Imaging
Machine Vision System Market
Imaging
Global Computed Radiography Market
Imaging
IR Camera Market
Imaging
Holographic Imaging Market
Imaging
Instant Digital Cameras Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Global 3D Camera Market
Imaging
Holotomographic Imaging Market