
 Handheld Retinal Scanners Market | 2026-2036
Handheld Retinal Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Retinal Scanners Market Foresight
Buyer concentration in ophthalmology is shifting from fragmented private practices toward consolidated hospital systems and multi-site clinic chains. Volk Optical leverages its legacy in diagnostic lenses to sustain relationships with academic medical centers. HEINE Optotechnik competes through precision-engineered optical instruments that dominate European hospital procurement channels. Optomed Plc anchors its position in mobile health with portable fundus cameras designed for decentralized screening programs.
Handheld retinal scanners are compact, non-mydriatic imaging devices that capture high-resolution images of the retina through infrared illumination or optical coherence tomography, enabling point-of-care diagnosis of diabetic retinopathy and glaucoma without pupil dilation. Wireless scanners lead product type demand as clinical workflows prioritize seamless electronic health record integration and teleophthalmology connectivity. Optical coherence tomography technology captures the fastest-growing segment as clinicians demand cross-sectional retinal tissue analysis previously limited to tabletop systems. Diabetic retinopathy screening applications concentrate margin pools where pay-for-performance models reward early detection in primary care settings.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and market access for manufacturers targeting the United States and European Union. Japan's PMDA enforces stringent optical performance standards that filter out lower-resolution devices from its reimbursement-eligible product list. India's CDSCO has streamlined import licensing for retinal diagnostic devices under its Medical Device Rules, opening channels for manufacturers serving its expanding diabetes screening infrastructure. Stakeholders must monitor evolving reimbursement codes for remote diagnostic interpretation and the interoperability standards that determine which devices integrate with national telehealth platforms.
Market Dynamics
Teleophthalmology reimbursement expansion is compressing diagnostic workflows into primary care settings, forcing manufacturers to prioritize wireless interoperability and cloud-native architecture over standalone device performance.
Growth Catalysts
- Diabetes screening mandates:Medicare's remote diagnostic interpretation codes now reimburse point-of-care retinal imaging performed by non-ophthalmologists, accelerating deployment in federally qualified health centers across the United States.
- EU MDR streamlined pathways:Class IIa ophthalmic device conformity assessments under the Medical Device Regulation now average 12-18 months, down from prior uncertainty, enabling faster European market entry for validated manufacturers.
- Infrared illumination advances:Non-mydriatic imaging through 820-850nm wavelengths eliminates pharmacologic dilation delays, making same-day diabetic retinopathy screening viable in high-throughput clinics.
Market Restraints
- CMOS sensor supply concentration:High-resolution medical-grade image sensors for fundus cameras source primarily from Sony and Samsung fabrication facilities in South Korea and Japan, creating single-source vulnerability for mid-tier manufacturers.
- PMDA optical performance thresholds:Japan's Pharmaceuticals and Medical Devices Agency mandates 45-degree field-of-view minimums and 15-micron resolution standards that filter lower-specification devices from national reimbursement eligibility.
- Tabletop OCT substitution:Hospital systems with capital budgets continue favoring stationary spectral-domain optical coherence tomography systems for comprehensive glaucoma staging, limiting handheld penetration in tertiary care.
Strategic Opportunities
- India's CDSCO import streamlining:Medical Device Rules amendments have collapsed import licensing timelines for retinal diagnostic equipment, opening procurement channels for manufacturers serving state-level diabetes screening programs.
- AI diagnostic convergence:Integration of automated diabetic retinopathy grading algorithms with handheld capture hardware creates bundled screening solutions eligible for value-based care contracts in United States accountable care organizations.
- Pharmacy-based screening channels:Retail health clinics in Germany and the United Kingdom are piloting fundus camera installations for cardiovascular risk stratification, expanding addressable endpoints beyond traditional eye care settings.
Industry Challenges
- DICOM interoperability certification:Electronic health record integration requires HL7 FHIR and DICOM conformance testing that extends product development cycles by 8-14 months for manufacturers lacking prior radiology device experience.
- Telehealth platform fragmentation:Proprietary cloud architectures from Epic, Cerner, and regional teleophthalmology vendors force redundant software development to maintain connectivity across hospital system procurement silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Retinal Scanners Market |
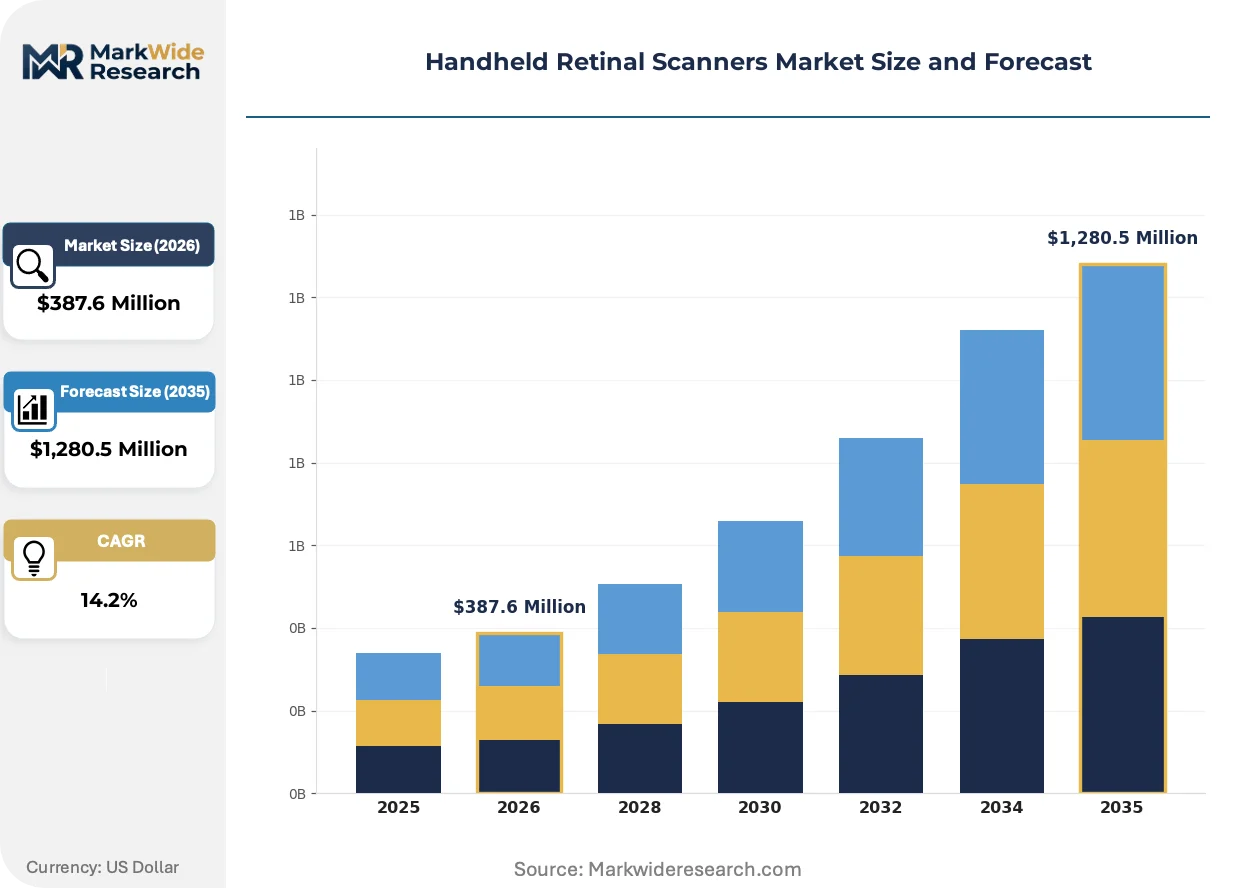
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Scanners, Wireless Scanners, Digital Scanners, Optical Scanners End User: Ophthalmologists, Optometrists, Clinics, Hospitals Technology: Infrared Imaging, Optical Coherence Tomography, Fundus Photography, Spectral Domain Imaging Application: Diabetic Retinopathy Screening, Glaucoma Detection, Macular Degeneration Diagnosis, Vision Assessment |
| Companies Covered | Volk Optical, ROWIAK GmbH, KIRCHNER & WILHELM GmbH, HEINE Optotechnik, Welch Allyn, Optomed Plc, Remidio Innovative Solutions, AI Optics, Forus Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Retinal Scanners Market Shifts & Advancements
Artificial intelligence integration and wireless connectivity standards are compressing the gap between image capture and clinical decision, enabling diagnostic workflows that bypass traditional ophthalmology referral bottlenecks.
Optical coherence tomography miniaturization is automating cross-sectional retinal analysis previously confined to hospital-based tabletop systems. Community health centers in the United States are deploying handheld spectral-domain devices for glaucoma progression monitoring between specialist visits. This capability compression is automating the displacement of optical biometry referrals from tertiary centers to primary care settings.
Japan's PMDA has tightened electromagnetic compatibility standards for wireless ophthalmic devices, requiring manufacturers to demonstrate 2.4GHz and 5GHz band resilience in clinical environments. The regulation forces hardware redesigns for devices originally architected for European CE marking alone. Products targeting simultaneous United States and Japan clearance now prioritize dual-band antenna configurations from initial design phases.
Hospital procurement committees now bundle handheld retinal scanners with enterprise telehealth platforms rather than acquiring standalone devices. United States health systems are consolidating vendor relationships under single-source agreements that mandate API-level integration with Epic or Cerner ecosystems. This specification tightening favors manufacturers with established health IT partnerships over pure-play device specialists.
Handheld Retinal Scanners Market Segmentation
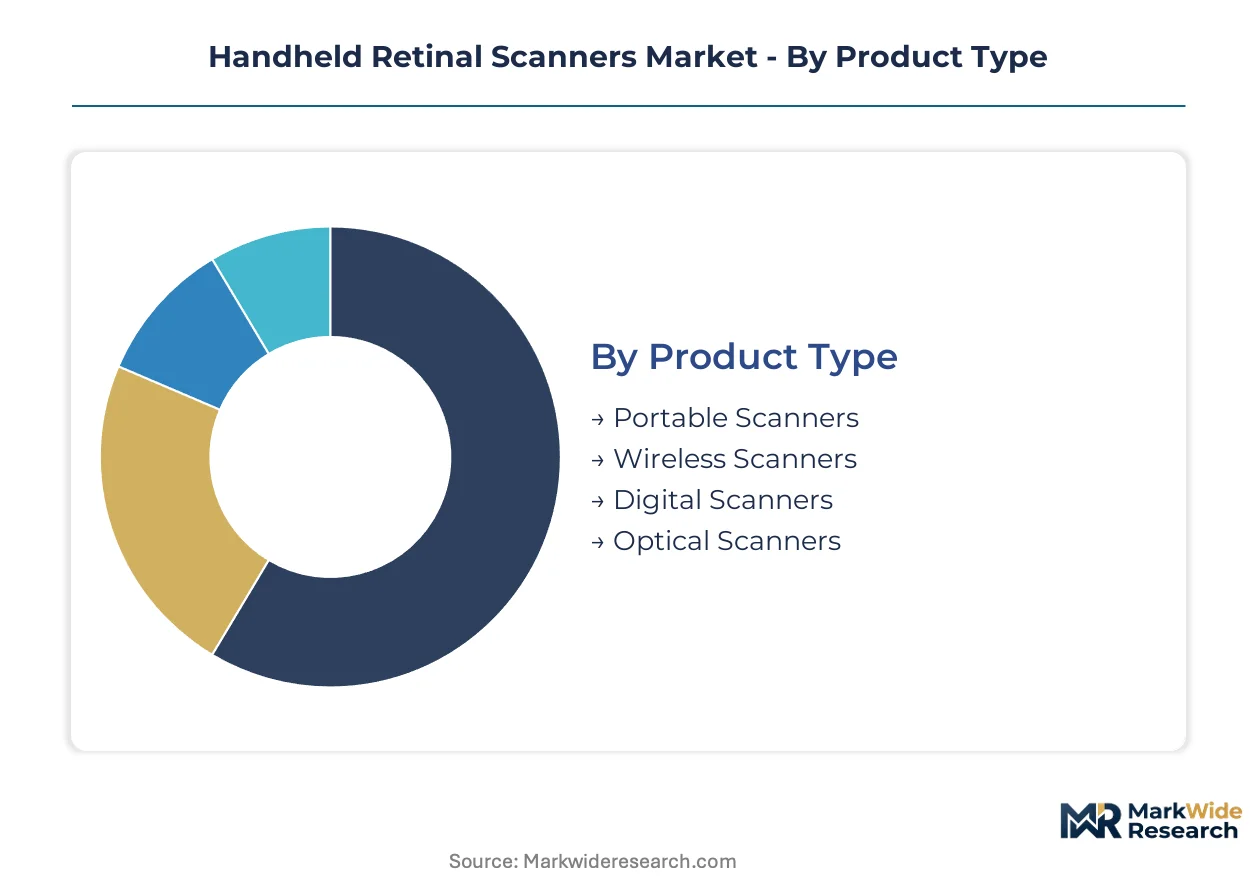
Segmentation in handheld retinal scanners reveals how procurement priorities diverge across care settings and clinical workflows. Buyers prioritize different specifications depending on whether devices deploy in high-throughput screening programs or specialized diagnostic environments.
Product Type:
Procurement committees weight portability against connectivity requirements when selecting device formats for specific deployment contexts.
- Wireless Scanners:Bluetooth and Wi-Fi-enabled devices transmit images directly to cloud-based teleophthalmology platforms. Hospital systems in the United States specify these for integration with Epic and Cerner electronic health record ecosystems.
- Portable Scanners:Battery-operated units with tethered data transfer suit mobile screening vans and rural outreach programs. State-level diabetes programs in India procure these for district-level deployment where network connectivity remains intermittent.
- Digital Scanners:USB-connected devices with onboard image processing appeal to cost-conscious clinic chains standardizing on single-vendor imaging suites.
- Optical Scanners:Lens-based systems without electronic capture components serve training institutions and backup diagnostic roles in resource-limited settings.
Wireless scanners lead volumes today; portable scanners are gaining share fastest in emerging market screening programs.
End User:
Credential requirements and reimbursement eligibility shape which user categories drive procurement specifications.
- Hospitals:Integrated delivery networks demand FDA-cleared devices with DICOM conformance and automated quality assurance algorithms. Tertiary centers in Germany specify these for glaucoma progression monitoring between specialist referrals.
- Clinics:Federally qualified health centers in the United States prioritize non-mydriatic operation and single-button capture for staff without ophthalmic training. Medicare remote diagnostic interpretation codes now reimburse these deployments.
- Ophthalmologists:Solo and group practices seek handheld spectral-domain devices for patient education and supplementary imaging between comprehensive examinations.
- Optometrists:Primary eye care providers in the United Kingdom pilot fundus cameras for cardiovascular risk stratification, expanding beyond traditional refractive services.
Hospitals dominate current procurement volumes; clinics are expanding fastest under value-based screening contracts.
Technology:
Imaging modality selection determines diagnostic depth and capital intensity for different clinical applications.
- Optical Coherence Tomography:Miniaturized spectral-domain systems capture cross-sectional retinal tissue analysis previously confined to tabletop platforms. Community health centers in the United States deploy these for glaucoma monitoring between specialist visits.
- Infrared Imaging:Non-mydriatic capture through 820-850nm wavelengths eliminates pharmacologic dilation delays. High-throughput diabetic retinopathy screening programs in Japan specify these for same-day workflow completion.
- Fundus Photography:Standard color imaging through white-light or green-filter illumination serves baseline documentation and telemedicine transmission requirements.
- Spectral Domain Imaging:High-speed line-scanning variants of OCT technology enable motion-corrected capture in non-compliant patients and pediatric populations.
Fundus photography maintains the largest installed base; optical coherence tomography is climbing the fastest as miniaturization costs decline.
Application:
Reimbursement structures and disease prevalence determine which screening applications concentrate device deployment.
- Diabetic Retinopathy Screening:Point-of-care imaging for early detection commands priority in pay-for-performance models. Accountable care organizations in the United States bundle automated grading algorithms with capture hardware for value-based contracts.
- Glaucoma Detection:Handheld spectral-domain devices monitor optic nerve head and retinal nerve fiber layer changes between comprehensive examinations. Hospital networks in Germany deploy these for progression tracking in community settings.
- Macular Degeneration Diagnosis:Age-related pathology screening drives demand in aging populations across Japan and Western Europe.
- Vision Assessment:General ophthalmic evaluation applications support primary care integration and wellness screening beyond specialist referral pathways.
Diabetic retinopathy screening leads current deployment; glaucoma detection is expanding most quickly with OCT miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ophthalmology specialists cluster in urban medical centers across aging economies, concentrating device procurement in hospital networks with integrated telehealth infrastructure. Regulatory clearance pathways in major markets filter device specifications before reimbursement eligibility.
United States
Medicare's remote diagnostic interpretation codes now reimburse point-of-care retinal imaging performed by non-ophthalmologists, accelerating deployment in federally qualified health centers. FDA 510(k) clearance requirements shape product development timelines for manufacturers targeting hospital procurement committees. The Cleveland Clinic and Mayo Clinic anchor demand in integrated delivery networks that mandate DICOM conformance and automated quality assurance algorithms.
Germany
Specialty eye care chains and academic medical centers drive procurement of precision-engineered optical instruments under streamlined EU MDR Class IIa conformity assessments. The country's national pharmaceutical regulator enforces optical performance standards that validate devices for statutory health insurance reimbursement. Tertiary centers in Berlin and Munich specify handheld spectral-domain devices for glaucoma progression monitoring between specialist referrals.
Japan
PMDA optical performance thresholds mandate 45-degree field-of-view minimums and 15-micron resolution standards that filter lower-specification devices from national reimbursement eligibility. METI electromagnetic compatibility standards for wireless ophthalmic devices require 2.4GHz and 5GHz band resilience in clinical environments. Tokyo and Osaka medical districts concentrate procurement of non-mydriatic imaging systems for same-day diabetic retinopathy screening workflows.
India
State-level diabetes screening programs expand procurement of battery-operated portable units for district-level deployment where network connectivity remains intermittent. CDSCO import licensing streamlining under Medical Device Rules amendments collapses timelines for retinal diagnostic equipment. Maharashtra and Karnataka anchor manufacturing and distribution channels serving government health infrastructure expansion.
Handheld Retinal Scanners Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels that increasingly favor enterprise telehealth integration over standalone device performance. The vendor base stratifies into three tiers: legacy optical instrument manufacturers with hospital relationships, mobile health technology specialists with cloud-native architectures, and emerging AI-diagnostic convergence players bundling automated grading algorithms. Dominant competitive moves include strategic partnerships with electronic health record platforms and geographic expansion into streamlined regulatory jurisdictions.
Among legacy optical specialists, Volk Optical and HEINE Optotechnik occupy positions anchored by decades of diagnostic lens relationships with academic medical centers. Optomed Plc exemplifies the mobile health archetype, with its Finland-based corporate structure reflecting European engineering concentration in portable medical devices. These three entities represent the spectrum from precision optical heritage to cloud-connected screening platforms that procurement committees now evaluate as integrated ecosystem components rather than discrete hardware acquisitions.
| Leading Market Players |
|---|
| Volk Optical |
| ROWIAK GmbH |
| KIRCHNER & WILHELM GmbH |
| HEINE Optotechnik |
| Welch Allyn |
| Optomed Plc |
| Remidio Innovative Solutions |
| AI Optics |
| Forus Health |
| Others |
Supply & Pricing Matrix
Optical engineering talent concentration in southern Germany and the Boston corridor drives labor-cost differentials that separate premium handheld retinal scanners from economy-tier alternatives. Manufacturing wage spreads of 40-60% between these engineering hubs and contract assembly zones in Mexico and Eastern Europe translate directly into three-tier pricing architectures across the market.
Pricing Analysis
Bundled enterprise telehealth contracts versus unbundled device-only procurement splits the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and DICOM interoperability certification. Pricing pressure stems from hospital procurement committees consolidating vendor relationships under single-source agreements. Federally qualified health centers exhibit highest price sensitivity, while integrated delivery networks prioritize ecosystem integration over unit cost.
Supply Chain Analysis
Workforce availability for precision optical assembly constrains manufacturing scale-up in Japan and Germany more severely than in South Korea or Taiwan. High-resolution CMOS sensors source primarily from Sony and Samsung fabrication facilities in South Korea and Japan, while infrared illumination modules concentrate in German optical component suppliers. Single-source vulnerability around medical-grade image sensors creates supply chain risk. Distribution runs through specialized medical device distributors and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between streamlined CDSCO import pathways in India and stringent PMDA optical performance thresholds in Japan, with regulatory compliance cost differentials exceeding 30% between these jurisdictions.
For Market Incumbents: To counter AI-diagnostic convergence players bundling automated grading algorithms, legacy optical specialists must deepen health IT partnerships with Epic and Cerner ecosystems while expanding backward integration into CMOS sensor sourcing to reduce single-supplier exposure. For New Entrants and Emerging Players: Cloud-native teleophthalmology platforms represent the most penetrable white-space target, particularly for state-level diabetes screening programs in India where intermittent network connectivity favors portable scanners with tethered data transfer over fully wireless architectures. For Investors and Strategic Acquirers: Hospital system procurement committees are the most active acquirer in this space through captive venture arms and innovation funds. Acquisition targets should demonstrate established DICOM conformance and automated quality assurance algorithms. Watch for Medicare reimbursement code expansion for remote diagnostic interpretation as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for Class II ophthalmic devices targeting United States hospital procurement committees. |
| CE Marking Under EU MDR | Enables streamlined 12-18 month conformity assessments for European specialty eye care chain deployments. |
| Hospital System Partnership | Secures single-source agreements mandating API-level integration with Epic or Cerner electronic health record ecosystems. |
| Software Companion Development | Creates bundled screening solutions eligible for value-based care contracts in United States accountable care organizations. |
| Reimbursement Strategy | Aligns device specifications with Medicare remote diagnostic interpretation codes for non-ophthalmologist deployment. |
Research Methodology
Coverage spans the United States, Germany, Japan, and India, with primary inputs from each combining structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at ophthalmic device manufacturers. Secondary validation draws from FDA 510(k) filings, EU MDR conformity assessment databases, PMDA reimbursement eligibility lists, and CMS Medicare claims data. Bottom-up unit economics triangulate against top-down market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, technology, end user, and application segments throughout the forecast period. CAGRs derive from modeled adoption curves in diabetic retinopathy screening programs and glaucoma detection workflows, calibrated against diabetes prevalence trajectories and teleophthalmology reimbursement expansion timelines.
The model holds under stable regulatory clearance timelines and continued Medicare reimbursement for remote diagnostic interpretation; deviation in FDA enforcement priorities or CMS coding changes would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Digital Image Processing Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
On-Chip Color Filters Market
Imaging
Global Thermal Imager Market
Imaging
Micro Computed Tomography Market
Imaging
North America Image Sensors Market
Imaging
Camcorder Market
Imaging
Chemical Imaging Systems Market
Imaging
Instant Digital Cameras Market
Imaging
Thermal Imaging Systems Market
Imaging
Hybrid Imaging Systems Market
Imaging
SWIR Camera Market
Imaging
IR Camera Market
Imaging
Printed Image Sensors Market
Imaging
Embedded Smart Cameras Market
Imaging
LCD Digital Microscope Market