
 Europe Optical Imaging Market | 2026-2036
Europe Optical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Optical Imaging Market Foresight
Modular system configurations is rebalancing how European hospitals evaluate capital optical imaging purchases, shifting preference toward upgradeable platforms over fixed-function devices. Carl Zeiss Meditec AG anchors the ophthalmology segment through its integrated diagnostic-to-surgical workflow systems. Heidelberg Engineering Inc. specializes in confocal scanning laser ophthalmoscopy for glaucoma progression monitoring. Canon Inc. competes across retinal imaging and digital radiography with unified software ecosystems.
Europe optical imaging encompasses non-invasive techniques that capture photon-based contrast from biological tissues, typically operating across ultraviolet to near-infrared wavelengths with spatial resolutions reaching sub-micron scales for cellular visualization. The primary commercial purpose centers on disease diagnosis and therapeutic monitoring in clinical settings, alongside fundamental cell research in academic laboratories. Optical coherence tomography dominates hospital procurement budgets due to its established reimbursement codes across EU member states. Fluorescence microscopes sustain margin pools in research laboratories where multiphoton variants command premium positioning for deep-tissue imaging. Image processing technology represents the fastest-expanding segment as AI-assisted diagnostic algorithms gain CE marking under the EU AI Act framework.
The EU Medical Device Regulation and EMA guidance on software-as-medical-device classification are reshaping product registration pathways for AI-enhanced optical imaging platforms. REACH compliance requirements influence fluorophore chemistry sourcing decisions for European fluorescence microscope manufacturers. Stakeholders must monitor how notified body capacity constraints under MDR transition timelines affect new product market access across member states.
Market Dynamics
EU Medical Device Regulation timelines are compressing product launch windows across European optical imaging, forcing manufacturers to front-load clinical validation spending before notified body reviews.
Growth Catalysts
- MDR compliance mandates:Stricter performance verification requirements under the EU Medical Device Regulation are accelerating hospital replacement cycles for legacy ophthalmic equipment.
- Retinal disease burden:Aging demographics across Germany, France, and Italy are expanding diagnostic imaging volumes for age-related macular degeneration screening.
- AI-assisted algorithms:CE marking pathways under the EU AI Act framework are unlocking reimbursement for automated diagnostic interpretation tools.
Market Restraints
- Notified body capacity constraints:Bottlenecks in MDR-designated certification bodies are extending product registration timelines by 12-18 months for new market entrants.
- Fluorophore supply concentration:REACH compliance requirements for specialty chemical sourcing limit European fluorescence microscope manufacturers to three qualified suppliers.
- Fixed reimbursement codes:Established EU member state pricing for optical coherence tomography procedures caps revenue expansion despite technology upgrades.
Strategic Opportunities
- Eastern European hospital networks:Poland and Romania are expanding ophthalmology department capital budgets with EU structural fund allocations for healthcare infrastructure.
- Multiphoton microscopy convergence:Integration with advanced cell research workflows at Heidelberg and Leiden university medical centers commands premium positioning for deep-tissue imaging.
- Software-as-medical-device classification:EMA guidance on AI-enhanced diagnostic platforms creates first-mover advantages for vendors with integrated algorithm-hardware bundles.
Industry Challenges
- Photonics engineering talent scarcity:Specialized optical design expertise concentrates in Stuttgart and Eindhoven clusters, constraining R&D expansion for mid-tier manufacturers.
- Legacy system integration friction:Hospital IT departments face compatibility barriers when connecting new imaging platforms to existing PACS infrastructure across heterogeneous vendor environments.
- Clinical validation cost escalation:MDR-mandated post-market surveillance studies require sustained investment that disproportionately burdens smaller equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Optical Imaging Market |
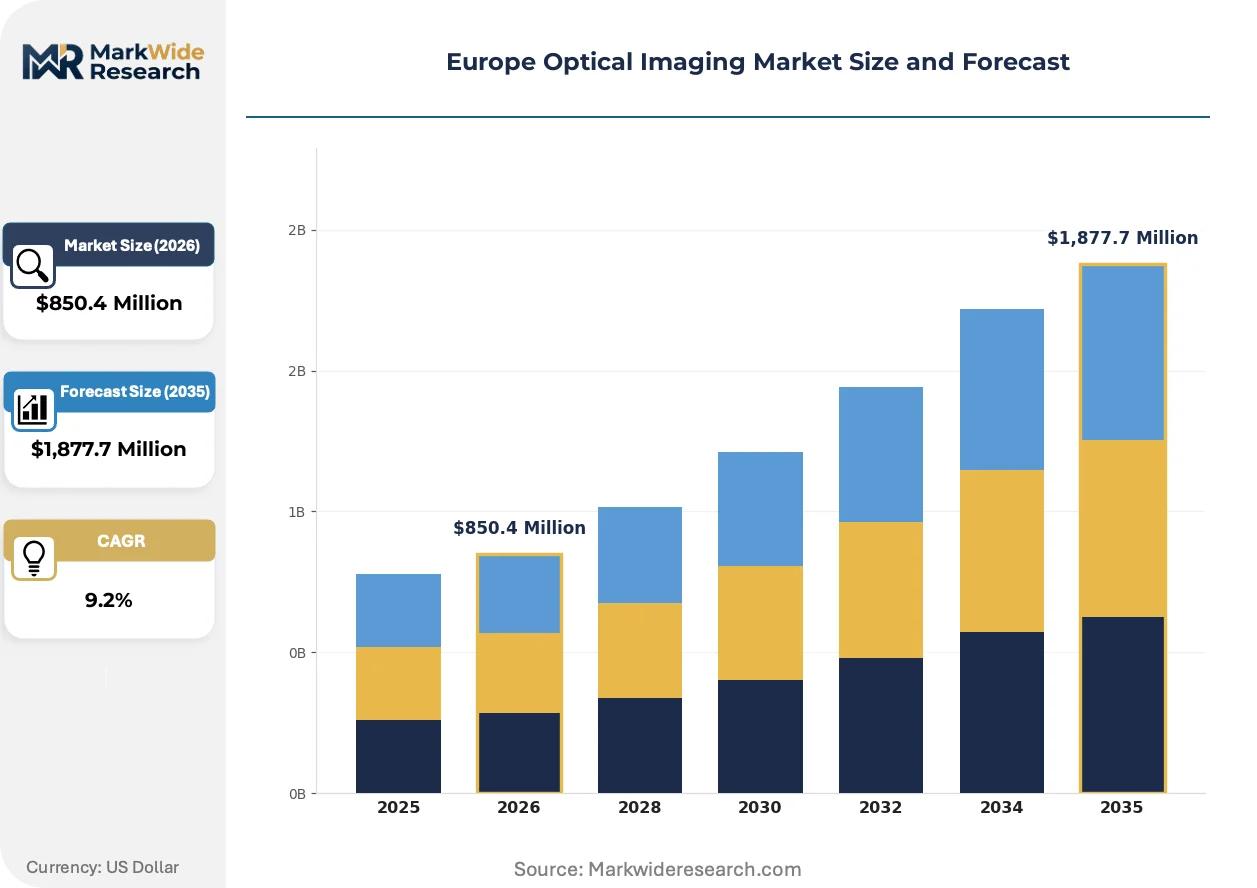
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,877.7 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescence Microscopes, Confocal Microscopes, Optical Coherence Tomography, Multiphoton Microscopes Technology: Imaging Modalities, Image Processing, Image Acquisition, Signal Enhancement End User: Hospitals, Research Laboratories, Diagnostic Centers, Academic Institutes Application: Cell Research, Disease Diagnosis, Clinical Trials, Preclinical Studies |
| Companies Covered | Headwall Photonics Inc., Canon Inc., Carl Zeiss Meditec AG, Agfa-Gevaert NV, PerkinElmer, Inc., Heidelberg Engineering Inc., ASE Optics, Inc., Bioptigen Inc., Topcon Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Optical Imaging Market Shifts & Advancements
Computational imaging architectures are displacing hardware-centric designs across European optical systems, compressing physical component counts while expanding diagnostic parameter extraction.
Adaptive optics retinal imaging is rewriting clinical workflow economics by enabling cellular-resolution visualization of photoreceptor layers without invasive contrast agents. University medical centers in Munich and Rotterdam are deploying these systems for early-stage glaucoma progression tracking. The technology is compressing the diagnostic value chain by merging structural and functional assessment into single-session protocols.
The EU AI Act's risk classification framework for medical device software is forcing manufacturers to restructure algorithm development pipelines around documented clinical validation datasets. High-risk diagnostic applications now require conformity assessments from notified bodies with expanded technical documentation. Ophthalmic imaging platforms with embedded machine learning modules face the steepest compliance cost escalation.
Hospital procurement committees are unbundling service contracts from equipment purchases, separating preventive maintenance from software update subscriptions. German university hospitals pioneered this shift, with regional purchasing consortia in Baden-Württemberg and Bavaria now mandating itemized pricing disclosure. The model is spreading to French public hospital networks seeking operational expenditure transparency.
Europe Optical Imaging Market Segmentation
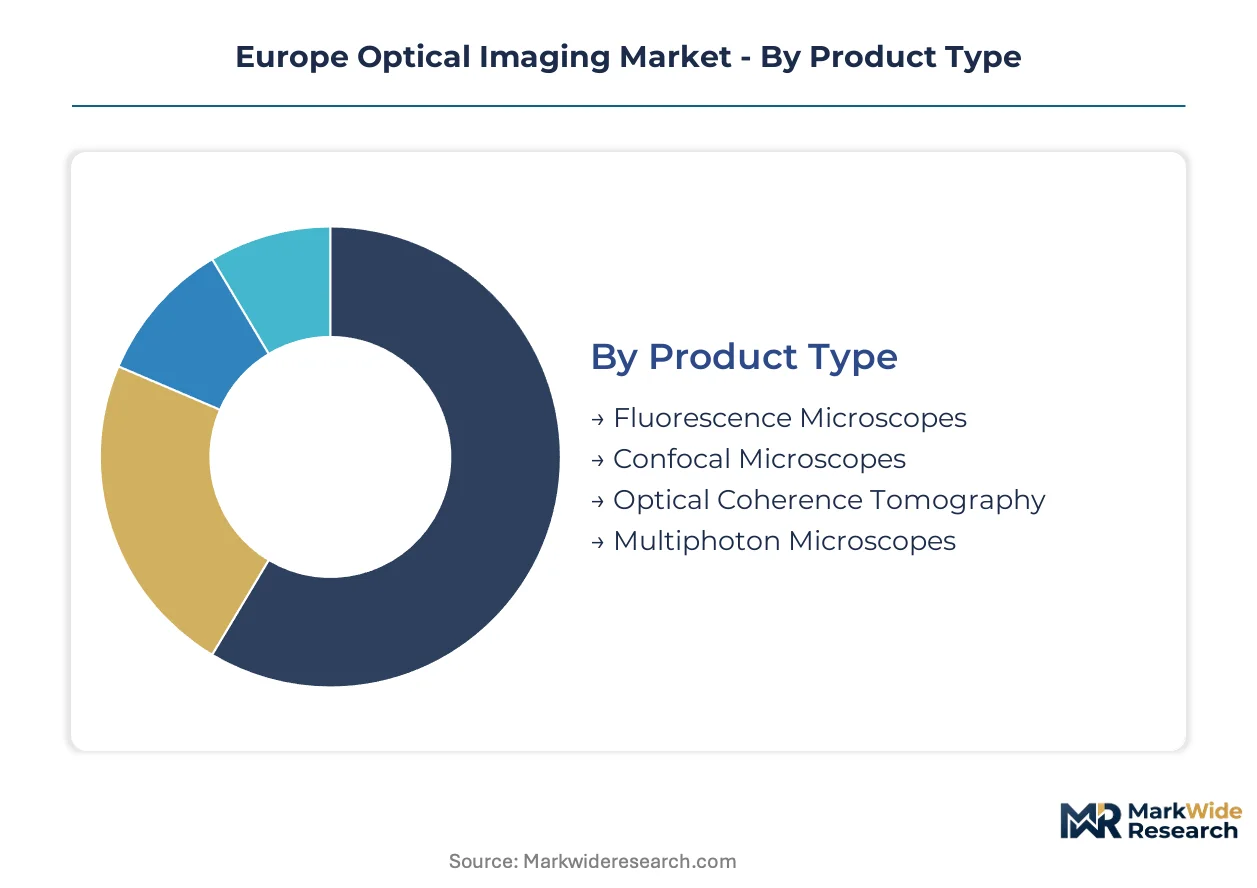
Segmentation in the Europe Optical Imaging Market reveals how capital allocation, regulatory pathways, and end-use requirements fragment purchasing behavior across the value chain. Equipment buyers in Germany and France weight upgradeability and software integration more heavily than price points alone.
Product Type:
Capital intensity varies sharply across optical imaging platforms, with hospital-grade systems demanding multimillion-euro procurement budgets while research-grade instruments operate at lower fixed-cost thresholds.
- Optical Coherence Tomography:Interferometric imaging systems generate cross-sectional tissue visualizations at micrometer resolution using near-infrared light sources. German university medical centers in Munich and Heidelberg anchor regional purchasing volume for retinal disease diagnosis, driven by established reimbursement codes under national health insurance frameworks.
- Fluorescence Microscopes:Widefield and confocal variants utilize excitation-emission spectral separation to visualize labeled cellular structures. Research laboratories at Leiden University Medical Center and the Francis Crick Institute in London concentrate demand for multicolor imaging workflows, constrained by REACH compliance requirements for specialty fluorophore sourcing.
- Confocal Microscopes:Pinhole-based optical sectioning eliminates out-of-focus light for three-dimensional reconstruction of thick specimens.
- Multiphoton Microscopes:Nonlinear excitation enables deep-tissue penetration with reduced phototoxicity for intact organoid imaging.
Optical coherence tomography absorbs the bulk of installed capacity; multiphoton microscopes are expanding most quickly among advanced research facilities.
Technology:
Software-enabled capabilities now command premium positioning over hardware specifications as AI-assisted diagnostic algorithms gain CE marking under EU AI Act frameworks.
- Image Processing:Computational algorithms extract quantitative biomarkers from raw imaging data, enabling automated pathology scoring and treatment response monitoring. EMA guidance on software-as-medical-device classification is accelerating vendor investment in documented clinical validation datasets for high-risk diagnostic applications.
- Imaging Modalities:Hardware configurations span spectral, time-domain, and en-face acquisition schemes optimized for specific tissue contrast mechanisms. Hospital procurement committees in Baden-Württemberg prioritize modular platforms permitting field-upgradable detection channels.
- Image Acquisition:Sensor and scanning subsystem integration determines spatial resolution and acquisition speed trade-offs.
- Signal Enhancement:Adaptive optics and computational denoising methods recover contrast from photon-limited biological samples.
Image processing claims the steepest margin expansion trajectory; imaging modalities retain the largest installed base across European clinical sites.
End User:
Purchasing authority and budget cycles diverge substantially between publicly funded hospital networks and grant-dependent academic research institutions.
- Hospitals:Clinical diagnostic departments operate under fixed reimbursement schedules that cap equipment replacement frequency despite MDR-mandated performance verification upgrades. France's public hospital networks (AP-HP) and Germany's university medical centers (Charité Berlin, Klinikum rechts der Isar) dominate capital procurement volume for ophthalmology and pathology workflows.
- Research Laboratories:Principal investigator grant funding drives instrument selection toward publication-impact metrics and multi-user accessibility. Netherlands-based European Molecular Biology Laboratory and Swiss Federal Institute of Technology concentrate demand for super-resolution and live-cell imaging platforms.
- Diagnostic Centers:Private imaging chains operate on throughput-optimized service models with shorter depreciation schedules.
- Academic Institutes:Core facility management structures pool equipment access across departmental boundaries.
Hospitals deploy the greatest cumulative imaging capacity; research laboratories are gaining share fastest through EU Horizon Europe infrastructure allocations.
Application:
Regulatory classification and commercial monetization models diverge between exploratory research use cases and clinically validated diagnostic indications.
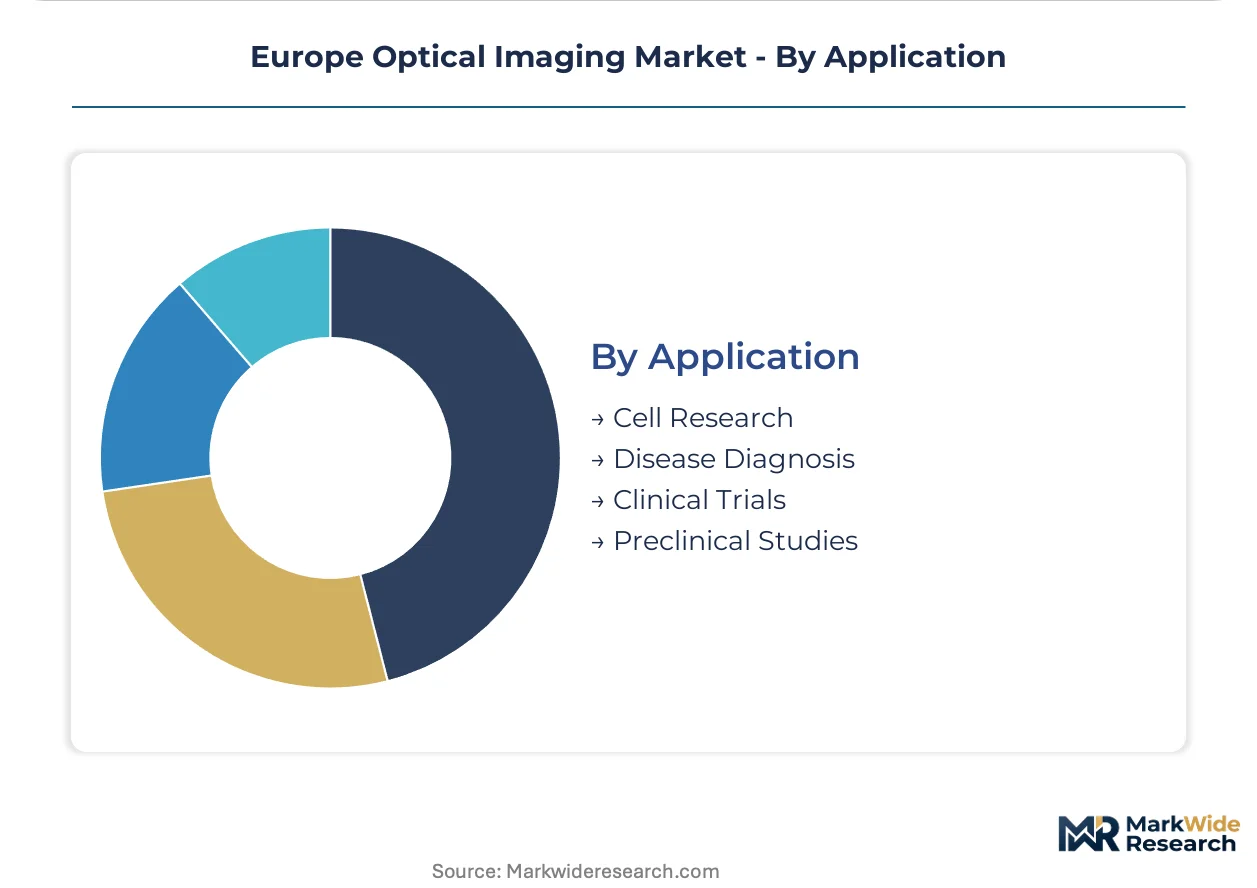
- Disease Diagnosis:CE-marked optical imaging systems support screening and monitoring workflows for age-related macular degeneration, glaucoma, and diabetic retinopathy. Italian ophthalmology departments in Milan and Rome are expanding screening program capacity in response to aging demographic burdens.
- Cell Research:Fundamental biology applications prioritize spatial resolution and live-cell compatibility over regulatory compliance speed. Heidelberg and Cambridge university clusters anchor European demand for advanced microscopy in developmental biology and neuroscience.
- Clinical Trials:Biomarker validation studies require standardized imaging protocols across multicenter investigator networks.
- Preclinical Studies:Small-animal imaging platforms bridge translational gaps between in vitro assays and human trials.
Disease diagnosis commands the largest revenue pool; cell research exhibits the most rapid technology refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European optical imaging production concentrates in southern Germany and the Netherlands, while consumption spreads across university medical centers from Milan to Stockholm. The region's regulatory fragmentation under national health insurance frameworks creates divergent procurement timelines despite harmonized CE marking requirements.
Germany
University medical centers in Munich and Heidelberg drive retinal imaging procurement volumes for age-related macular degeneration screening. The EU Medical Device Regulation's stricter performance verification mandates accelerate hospital replacement cycles for legacy ophthalmic equipment. Stuttgart anchors photonics engineering talent clusters that constrain R&D expansion for mid-tier manufacturers seeking specialized optical design expertise.
France
Public hospital networks in Paris and regional university hospitals expand ophthalmology department capital budgets for diagnostic imaging workflows. ANSM oversight of software-as-medical-device classification reshapes product registration pathways for AI-enhanced platforms. The Île-de-France region concentrates demand for integrated diagnostic-to-surgical workflow systems among AP-HP facilities.
United Kingdom
Research laboratories at the Francis Crick Institute and Oxford university clusters sustain margin pools for multiphoton microscopy in developmental biology applications. MHRA alignment with EU AI Act risk classification frameworks influences algorithm development pipelines for high-risk diagnostic applications. London anchors European demand for super-resolution imaging platforms through core facility management structures.
Italy
Ophthalmology departments in Milan and Rome expand screening program capacity in response to aging demographic burdens for glaucoma and diabetic retinopathy. National health service reimbursement codes for optical coherence tomography procedures cap revenue expansion despite technology upgrades. Northern Italian industrial districts concentrate fluorescence microscope component sourcing constrained by REACH compliance requirements.
Netherlands
Leiden University Medical Center and the European Molecular Biology Laboratory concentrate demand for multicolor imaging workflows in fundamental cell research. EMA guidance on AI-assisted diagnostic algorithms accelerates vendor investment in documented clinical validation datasets. The Eindhoven photonics cluster enables deep-tissue imaging platform development for intact organoid visualization.
Europe Optical Imaging Market Competitive Landscape
The competitive structure tilts toward integrated diagnostic platform specialists with established notified body relationships under MDR transition timelines. Tiered positioning separates premium-tier vendors with captive algorithm-hardware bundles from mid-market equipment suppliers competing on modular upgradeability. Strategic moves center on software-as-medical-device conformity assessments and geographic expansion into Eastern European hospital networks.
Within the integrated ophthalmology systems tier, Carl Zeiss Meditec AG and Heidelberg Engineering Inc. exemplify archetypes anchored in German engineering clusters. Canon Inc. occupies a position spanning retinal imaging and broader medical device portfolios. These three represent the spectrum from pure-play optical specialists to diversified health technology conglomerates competing across unified software ecosystems.
| Leading Market Players |
|---|
| Headwall Photonics Inc. |
| Canon Inc. |
| Carl Zeiss Meditec AG |
| Agfa-Gevaert NV |
| PerkinElmer, Inc. |
| Heidelberg Engineering Inc. |
| ASE Optics, Inc. |
| Bioptigen Inc. |
| Topcon Corporation |
| Others |
Supply & Pricing Matrix
REACH compliance mandates for specialty fluorophore chemistry gate qualified supply access and premium-tier pricing eligibility for European fluorescence microscope manufacturers serving university medical centers and research laboratories.
Pricing Analysis
Margin tightening in mid-tier equipment reflects MDR-mandated clinical validation cost escalation that disproportionately burdens smaller manufacturers lacking notified body relationships. Three-tier pricing structure across premium, standard, and economy levels separates integrated algorithm-hardware bundles from modular upgradeable platforms and fixed-function legacy systems. Certification tier under EU AI Act risk classification drives price differentiation, with high-risk diagnostic applications commanding conformity assessment premiums. Cost-down pressure on standard-tier equipment accelerates because hospital procurement committees in Germany and France now unbundle service contracts from capital purchases, demanding itemized pricing transparency.
Supply Chain Analysis
Freight cost volatility from Asian component sourcing strains working capital for European optical imaging assembly operations concentrated in southern Germany and the Netherlands. Photonics manufacturing draws from German precision optics clusters, Dutch semiconductor packaging facilities, and Japanese laser diode suppliers for near-infrared light sources. Specialized fluorophore chemistry hinges on three REACH-qualified suppliers, creating single-source vulnerability for multicolor imaging workflows. Distribution runs through university medical center purchasing consortia in Baden-Württemberg and Bavaria, with regional hospital networks consolidating procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MDR transition timelines and notified body capacity constraints are forcing consolidation as capital-starved mid-tier manufacturers exit before conformity assessment completion.
For Market Incumbents:Acquire algorithm development teams with documented clinical validation datasets to secure EU AI Act high-risk classification conformity assessments. Deepen backward integration into photonics engineering talent pools in Stuttgart and Eindhoven clusters to constrain R&D expansion for emerging competitors. Lock hospital system partnerships through integrated diagnostic-to-surgical workflow systems that embed switching costs against modular challengers.
For New Entrants and Emerging Players:Enter via Eastern European hospital networks in Poland and Romania where EU structural fund allocations for healthcare infrastructure expand capital budgets without entrenched vendor relationships. Target research laboratory segments at Leiden University Medical Center and the Francis Crick Institute where grant-dependent purchasing prioritizes publication-impact metrics over brand heritage. Pursue software-as-medical-device classification pathways for AI-assisted diagnostic algorithms that bypass hardware-intensive notified body reviews.
For Investors and Strategic Acquirers:First notified body MDR designation for AI-enhanced ophthalmic platforms is the leading indicator that algorithm-hardware bundles will capture premium positioning in hospital procurement cycles. Mid-cap equipment manufacturers with captive fluorophore supply agreements and established CE marking track records represent the most defensible acquisition targets. Watch for consolidation announcements in German university medical center purchasing consortia as signal of regional procurement authority concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR designation unlocks market access across EU member state hospital networks. |
| Hospital System Partnership | Baden-Württemberg and Bavaria consortia consolidate procurement authority for ophthalmology workflows. |
| Software Companion Development | AI Act high-risk classification requires documented clinical validation datasets for diagnostic algorithms. |
| Reimbursement Strategy | Established national health insurance codes for OCT procedures cap revenue expansion despite upgrades. |
| Geographic Expansion | Poland and Romania EU structural fund allocations expand ophthalmology department capital budgets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe Optical Imaging Market analysis, supplemented by primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and photonics R&D directors at German and Dutch manufacturing clusters. EMA guidance documents, MDR transition timelines from notified bodies, and EU AI Act risk classification frameworks provided regulatory validation. Bottom-up equipment shipment data from university medical centers and research laboratories triangulated against top-down market sizing from national health expenditure databases.
Cross-referencing shipment volumes, installed base depreciation schedules, and replacement cycle indicators reconciled data streams across the projection horizon. Segmentation modeling incorporated product type, technology tier, end-user category, and application with geographic clustering by national health insurance framework. CAGRs derived from weighted average of historical replacement patterns and MDR-mandated upgrade acceleration. Forecast inputs included aging demographic projections for retinal disease burden and EU Horizon Europe infrastructure allocations for research microscopy.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended notified body review timelines or fluorophore supply disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
South Korea Optical Detector Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Optical Spectrum Analyzer (OSA) Market
Optical Components
North America Laser Diode Market
Optical Components
Bio-Optics Market
Optical Components
North America Tunable Laser Market
Optical Components
Pancake Optical Module Market
Optical Components
Photosensitive Glass Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Global Optical Imaging System Market
Optical Components
Optical Transmitter Market
Optical Components
Passive Optical Component Market