
 US Laboratory Informatics Market | 2026-2036
US Laboratory Informatics Market Size, Share, and Industry Trends Forecast 2026-2036
US Laboratory Informatics Market Intelligence
Cloud-native architecture is rebalancing total cost of ownership against legacy on-premise installations across pharmaceutical and clinical settings. Thermo Fisher Scientific Inc. leverages its instrument-software integration to anchor enterprise accounts in high-throughput environments. LabVantage Solutions Inc. competes through modular deployment options that reduce implementation timelines for mid-size biotechnology firms. STARLIMS Corporation differentiates via deep specialization in quality control workflows for regulated manufacturing labs.
US Laboratory Informatics encompasses software platforms that capture, manage, and analyze scientific data across laboratory operations, typically integrating instrument control, sample tracking, and audit trail functionality with SQL or Oracle database backends. These systems serve primarily to ensure data integrity, accelerate experimental cycles, and maintain compliance with FDA, EPA, and USDA documentation standards in regulated industries. Laboratory Information Management Systems dominate installed base revenue due to their workflow orchestration depth across pharmaceutical quality control and clinical diagnostics. Cloud-Based deployment shows the fastest expansion trajectory as biotech startups prioritize capital efficiency and elastic compute scaling over fixed infrastructure investments. Electronic Lab Notebooks represent a concentrated margin pool where intellectual property capture requirements in early-stage drug discovery justify premium pricing.
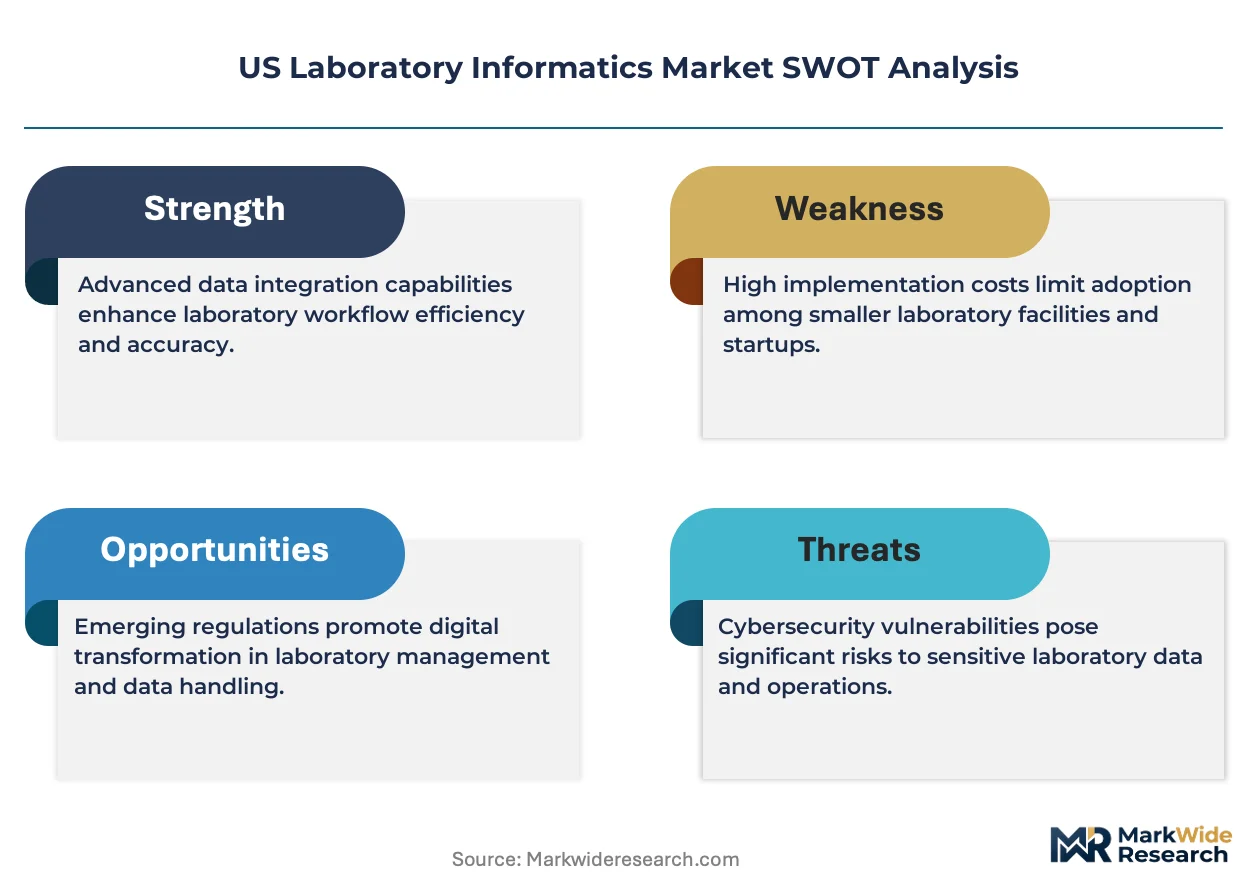
FDA 21 CFR Part 11, HIPAA privacy safeguards for clinical laboratory data, and EPA Good Automated Laboratory Practices collectively mandate audit trails, electronic signatures, and data immutability that elevate software validation costs while creating switching barriers for incumbent vendors. OSHA laboratory safety reporting requirements further embed informatics into operational compliance workflows across academic and industrial facilities. Stakeholders must monitor how AI-enabled data parsing triggers new FDA software-as-medical-device classification determinations that could reshape vendor liability and validation obligations.
Market Dynamics
Cloud-native architecture is displacing legacy on-premise installations as pharmaceutical quality control labs prioritize elastic compute scaling over fixed infrastructure commitments. This structural shift compresses implementation timelines while elevating vendor switching costs through integrated instrument-software ecosystems.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signatures mandates drive validation-compliant software procurement across regulated manufacturing facilities, embedding audit trail functionality as a non-negotiable procurement criterion.
- Biotech startup density:Boston's Kendall Square and San Francisco's Mission Bay clusters generate concentrated demand for capital-efficient SaaS deployments that eliminate upfront server investments.
- AI-enabled data parsing:Machine learning algorithms accelerate experimental cycle times in early-stage drug discovery, creating pull-through demand for platforms capturing structured and unstructured scientific data.
Market Restraints
- Validation cost structure:FDA software validation requirements for electronic records systems impose documentation burdens that extend sales cycles and elevate total cost of ownership for mid-size contract research organizations.
- Legacy system entrenchment:Oracle and SQL database backends in existing installations create data migration friction that protects incumbent vendors and delays replacement decisions.
- Talent scarcity:Shortage of professionals combining laboratory science expertise with informatics architecture skills constrains implementation velocity for complex multi-site deployments.
Strategic Opportunities
- Quality control specialization:Regulated manufacturing labs seek purpose-built workflows for batch release testing and stability studies, creating white space distinct from generalized research platforms.
- HIPAA-compliant clinical extensions:Privacy safeguard requirements for laboratory data in hospital networks open adjacent revenue pools beyond traditional pharmaceutical accounts.
- Mid-size biotechnology segment:Firms with 50-500 employees represent an underserved tier between enterprise pharma and academic labs, prioritizing modular deployment options over monolithic suites.
Industry Challenges
- Integration complexity:Connecting cloud-native platforms to heterogeneous instrument fleets and legacy laboratory information management systems demands specialized professional services that strain vendor delivery capacity.
- Software-as-medical-device classification uncertainty:FDA determinations on AI-enabled data parsing tools create liability exposure and validation obligation ambiguity that delays product roadmap commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Laboratory Informatics Market |
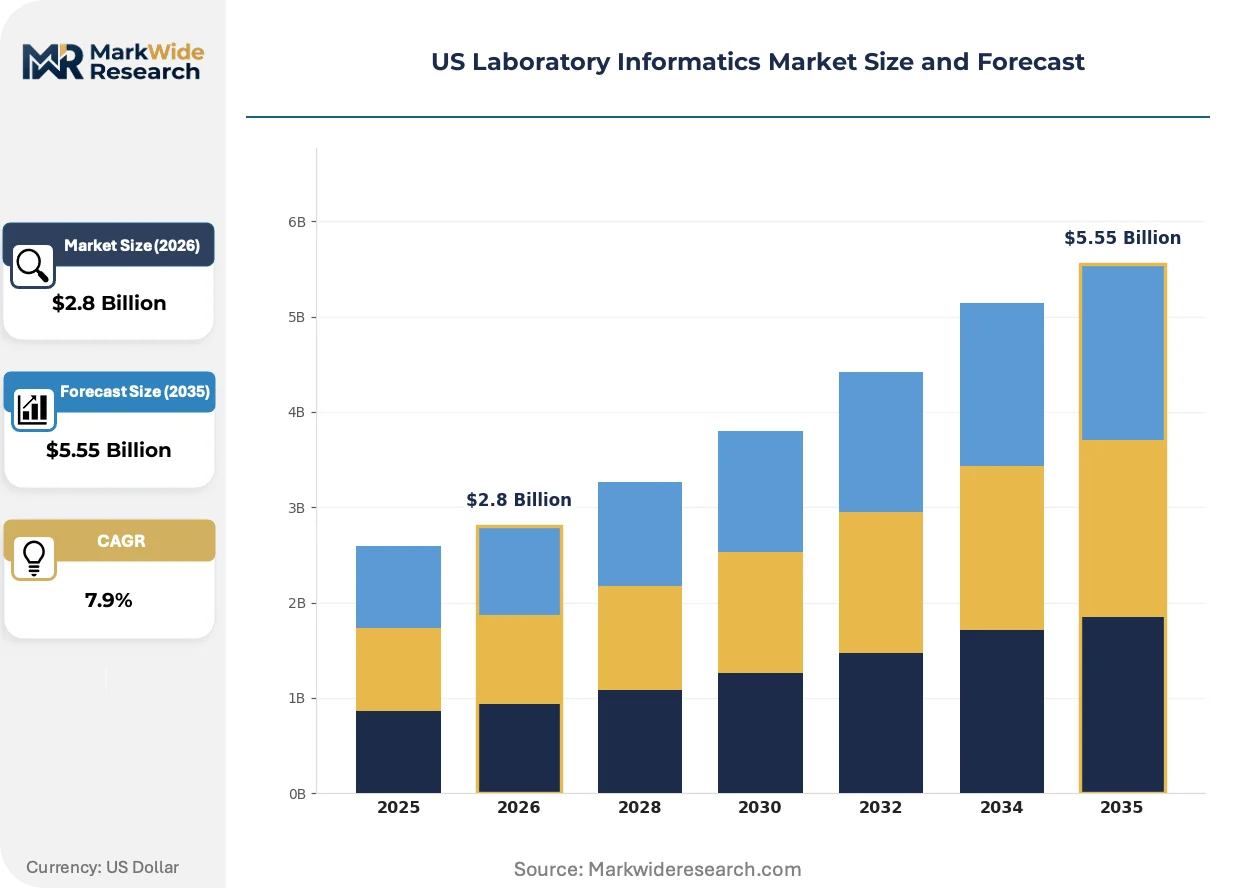
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
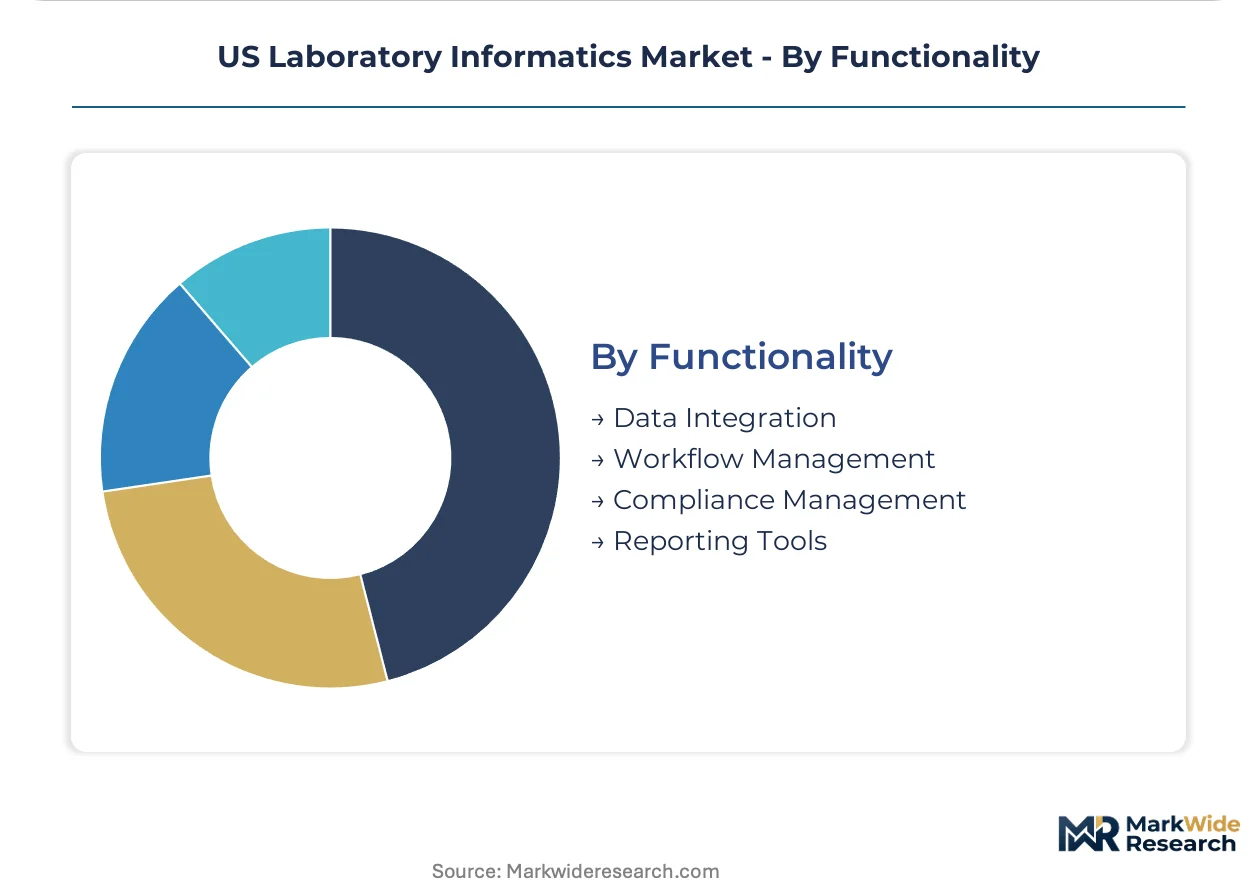
| Segmentation | Product Type: Laboratory Information Management Systems, Electronic Lab Notebooks, Scientific Data Management Systems, Chromatography Data Systems End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutions, Clinical Laboratories Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Functionality: Data Integration, Workflow Management, Compliance Management, Reporting Tools |
| Companies Covered | Abbott, STARLIMS Corporation, Thermo Fisher Scientific Inc., LabLynx Inc., Revvity, LabVantage Solutions Inc., Agilent Technologies Inc., Confience, LabWare Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Laboratory Informatics Market Strategic Shifts & Innovations
Artificial intelligence is embedding into scientific data workflows, compressing the gap between raw instrument output and actionable experimental insights while triggering new regulatory classification debates.
Laboratory information management systems are converging with electronic lab notebook functionality as vendors consolidate data capture layers. Pharmaceutical quality control departments adopt these unified platforms to eliminate redundant data entry between research and manufacturing phases. This consolidation is converging with cloud infrastructure investments to reduce total cost of ownership by eliminating on-premise server maintenance.
OSHA laboratory safety reporting requirements are mandating tighter integration between informatics platforms and environmental health systems. Industrial and academic facilities must now correlate sample tracking data with chemical exposure logs and waste disposal records. California and Massachusetts research clusters show the most advanced compliance implementations, driven by state-level occupational safety enforcement intensity.
Capital efficiency priorities among venture-backed biotechs are accelerating subscription pricing acceptance over perpetual license models. These firms defer infrastructure investments to preserve runway, favoring vendors offering consumption-based scaling. The Northeast corridor exhibits this behavioral shift most prominently, where Boston-area startups influence procurement norms that propagate to satellite facilities.
US Laboratory Informatics Market Segmentation
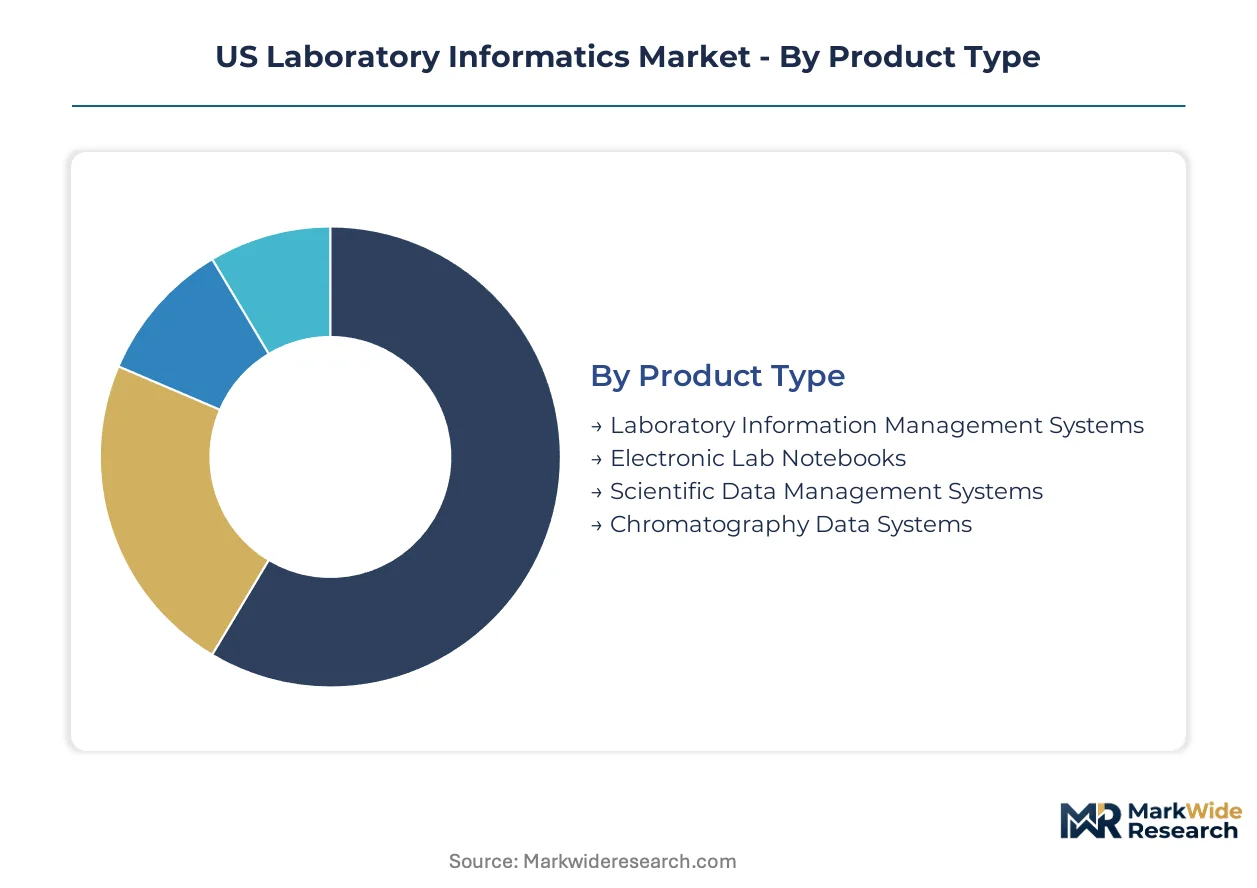
US Laboratory Informatics vendors structure product portfolios around regulatory compliance intensity and capital deployment preferences. Segmentation reveals how FDA validation requirements and cloud infrastructure economics reshape procurement patterns across pharmaceutical, biotech, and clinical settings.
Product Type:
Capital intensity varies sharply across product categories, with enterprise-grade systems demanding substantial upfront validation investment while modular tools lower entry barriers for emerging biotechs.
- Laboratory Information Management Systems:These platforms orchestrate sample tracking, instrument integration, and audit trail management through SQL or Oracle database architectures. Pharmaceutical quality control labs in New Jersey and Massachusetts drive concentrated procurement, with FDA 21 CFR Part 11 compliance mandates elevating total cost of ownership through extensive validation documentation.
- Electronic Lab Notebooks:Intellectual property capture tools structured for unstructured scientific data entry, experiment versioning, and collaborative research workflows. Boston's Kendall Square biotech cluster generates disproportionate demand, as venture-backed startups prioritize IP documentation for due diligence and partnership negotiations.
- Scientific Data Management Systems:Enterprise repositories normalizing heterogeneous instrument outputs into queryable analytical datasets.
- Chromatography Data Systems:Specialized platforms governing separation science workflows in regulated manufacturing environments.
Laboratory Information Management Systems absorb the bulk of installed capacity; Electronic Lab Notebooks are expanding most quickly.
End User:
Customer type determines pricing architecture, with enterprise pharmaceutical accounts funding perpetual licenses and mid-tier biotechnology firms driving subscription model adoption.
- Pharmaceutical Companies:Large-scale manufacturers operating validated quality control laboratories for batch release testing and stability studies. These organizations command the deepest workflow customization requirements and longest sales cycles, with procurement concentrated among headquarters operations in New Jersey and Illinois.
- Biotechnology Firms:Emerging and mid-cap drug developers prioritizing capital efficiency and rapid implementation timelines. San Francisco's Mission Bay cluster exhibits the strongest SaaS preference, deferring infrastructure investment to preserve venture runway.
- Academic Research Institutions:Universities and medical schools managing multi-investigator shared resource facilities with fragmented funding sources.
- Clinical Laboratories:Hospital-affiliated and independent diagnostic providers navigating HIPAA privacy safeguards for patient data management.
Pharmaceutical Companies anchor vendor revenue stability; Biotechnology Firms are climbing the fastest as cloud-native procurement norms propagate.
Deployment:
Infrastructure commitment level segments the market between capital-heavy on-premise installations and operational-expense-focused cloud arrangements.
- Cloud-Based:Elastic compute environments eliminating server procurement and maintenance overhead. Biotech startups across the Northeast corridor favor this model, with consumption-based scaling aligning informatics costs with experimental throughput fluctuations.
- SaaS:Vendor-managed software delivery with embedded compliance updates and security patching. Mid-size contract research organizations in North Carolina's Research Triangle prioritize this deployment to accelerate validation timelines.
- On-Premise:Self-hosted installations retaining full data sovereignty and customization control.
- Hybrid:Mixed architectures preserving sensitive manufacturing data on-site while leveraging cloud analytics for research collaboration.
On-Premise retains dominance in validated manufacturing settings; Cloud-Based is gaining share fastest among venture-funded life science operations.
Functionality:
Feature depth correlates with regulatory exposure, with compliance-intensive modules commanding premium pricing against operational efficiency tools.
- Compliance Management:Audit trail generation, electronic signature enforcement, and data immutability controls mandated by FDA electronic records requirements. Pharmaceutical quality control departments treat this functionality as non-negotiable, embedding it into vendor selection scorecards regardless of base platform cost.
- Workflow Management:Sample routing, protocol enforcement, and resource scheduling across multi-step experimental processes. Academic core facilities in California leverage these tools to maximize instrument utilization rates and justify fee-for-service pricing.
- Data Integration:API architectures and middleware connecting heterogeneous instrument fleets to central repositories.
- Reporting Tools:Configurable dashboards and regulatory submission document generation for EPA, USDA, and OSHA filing requirements.
Compliance Management commands the steepest pricing premiums; Workflow Management is expanding most quickly as operational efficiency pressures intensify across constrained research budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Laboratory Informatics demand concentrates along the Northeast corridor, where pharmaceutical headquarters and biotech clusters generate disproportionate procurement volume. State-level enforcement intensity and research funding density create sharp sub-regional variation in adoption velocity and compliance implementation.
Greater Boston
Kendall Square biotech density drives SaaS-first procurement preferences among venture-backed startups. Massachusetts state occupational safety regulations mandate tighter informatics integration with environmental health systems. Cambridge and Watertown facilities exhibit the most advanced OSHA compliance implementations nationwide.
New Jersey Corridor
Pharmaceutical headquarters operations command the deepest workflow customization requirements and longest validation cycles. FDA 21 CFR Part 11 enforcement concentrates procurement decisions among enterprise-grade platform vendors. Princeton and Rahway manufacturing complexes anchor quality control informatics spending.
San Francisco Bay Area
Mission Bay and South San Francisco biotech clusters prioritize capital-efficient cloud deployments to preserve venture runway. California's laboratory safety reporting requirements exceed federal OSHA baselines. Oakland and Emeryville contract research organizations accelerate subscription model acceptance.
North Carolina Research Triangle
Mid-size contract research organizations drive demand for rapid-validation SaaS implementations. State economic development incentives attract pharmaceutical manufacturing expansion. Durham and Raleigh facilities favor modular deployment options over monolithic enterprise suites.
San Diego Biotech Beach
Torrey Pines and Sorrento Valley clusters generate concentrated demand for electronic lab notebook functionality. California intellectual property documentation standards shape vendor selection criteria. La Jolla research institutes prioritize IP capture tools for partnership negotiations.
US Laboratory Informatics Market Key Industry Players
Branded specialists and instrument-software integrators split share differently across segments, with enterprise pharmaceutical accounts favoring validated platform ecosystems while mid-tier biotechs drive SaaS fragmentation. The vendor base organizes around three strategic archetypes: instrument-native platform providers, modular deployment specialists, and quality control workflow purists. M&A activity concentrates on cloud-native capability acquisition, while strategic partnerships target instrument fleet integration depth.
Among instrument-integrated platform providers, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. occupy positions where hardware-software bundling creates switching cost advantages. LabVantage Solutions Inc. sits within the modular deployment tier, exemplifying vendors that compress implementation timelines for capital-constrained biotechnology firms. STARLIMS Corporation anchors the quality control specialization segment, representing vendors that differentiate through regulated manufacturing workflow depth rather than research-oriented feature breadth.
| Leading Market Players |
|---|
| Abbott |
| STARLIMS Corporation |
| Thermo Fisher Scientific Inc. |
| LabLynx Inc. |
| Revvity |
| LabVantage Solutions Inc. |
| Agilent Technologies Inc. |
| Confience |
| LabWare Inc. |
| Others |
Cost & Logistics Intelligence
Enterprise-to-mid-market bifurcation separates perpetual license premiums from SaaS subscription compression across US laboratory informatics procurement. FDA validation documentation costs anchor pricing at the top tier, while venture-backed biotechs drive subscription elasticity downward through consumption-based scaling demands.
Pricing Analysis
Volume concentration in enterprise pharmaceutical accounts sustains margin pools against SaaS compression at the mid-market tier. Pricing stratifies across validated quality control suites, modular research platforms, and entry-level electronic lab notebooks, with FDA 21 CFR Part 11 certification tiers commanding substantial premiums. Pricing pressure stems from cloud-native entrants undercutting legacy perpetual licenses with faster implementation timelines. Mid-size biotechnology firms exhibit highest price sensitivity, deferring upfront investment to preserve runway; enterprise quality control labs show lowest sensitivity, treating validation depth as non-negotiable.
Supply Chain Analysis
Reverse logistics flows for instrument-software bundles reshape vendor economics through refurbishment programs and trade-in credits for legacy database migrations. Software development concentrates in the United States, Ireland, and India, with regulatory consulting services anchored domestically near FDA headquarters. Component dependencies include Oracle and SQL database licenses, cloud infrastructure from hyperscalers, and specialized compliance documentation services. Supply chain risk centers on single-source vulnerability for validated instrument drivers controlling chromatography and mass spectrometry hardware. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and channel partners for mid-market biotechnology penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US laboratory informatics operates as a supply-constrained market where validation talent scarcity props pricing power for incumbent vendors. Certified compliance architects represent the critical bottleneck constraining implementation velocity.
For Market Incumbents: Lock in switching costs through deeper instrument-native integration, embedding software validation into hardware procurement workflows. Expand professional services capacity in Boston and New Jersey corridors to capture implementation backlog. Defend against modular SaaS challengers by accelerating cloud migration roadmaps for existing Oracle and SQL database installations.
For New Entrants and Emerging Players: Mid-size contract research organizations in North Carolina's Research Triangle represent the most penetrable buyer archetype, underserved between enterprise pharma and academic tiers. Target rapid-validation SaaS deployments with pre-configured FDA 21 CFR Part 11 templates. Pursue partnership routes with regional instrument distributors lacking captive software offerings.
For Investors and Strategic Acquirers: Re-rating potential sits with quality control workflow specialists given FDA software-as-medical-device classification uncertainty creating distressed valuations. Long-term viability favors vendors with validated manufacturing install bases over research-oriented platforms facing AI-enabled disruption. Monitor FDA guidance publication timelines as the critical inflection signal for liability exposure clarity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Reduces total cost of ownership for biotech startups prioritizing capital efficiency over fixed infrastructure. |
| Instrument-Software Integration Deepening | Creates switching cost advantages through validated driver ecosystems controlling chromatography and mass spectrometry fleets. |
| Quality Control Workflow Specialization | Captures regulated manufacturing spend concentrated in New Jersey and Massachusetts pharmaceutical headquarters. |
| HIPAA-Compliant Clinical Extension | Opens adjacent revenue pools in hospital networks beyond traditional pharmaceutical accounts. |
| AI-Enabled Data Parsing Development | Accelerates experimental cycles while triggering FDA software-as-medical-device classification determinations. |
Research Approach
Document review covered FDA 21 CFR Part 11 guidance documents, EPA Good Automated Laboratory Practices, and OSHA laboratory safety reporting requirements, complemented by interviews with laboratory informatics vendors, pharmaceutical quality control directors, biotechnology IT procurement officers, and regulatory affairs consultants. Secondary sources included SEC filings from publicly traded instrument manufacturers, clinical laboratory accreditation databases, and cloud infrastructure spending disclosures from hyperscalers. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models and end-user categories.
Market size and growth trajectory outputs reflect segmentation modeling across product type, end user, deployment architecture, and functionality depth, with cross-validation against instrument installation base estimates and software subscription revenue disclosures. CAGRs derived from trend extrapolation of cloud adoption curves, regulatory enforcement intensity, and biotech funding cycle patterns. Key forecast inputs included venture capital deployment into life sciences, FDA inspection citation trends for electronic records violations, and cloud infrastructure pricing trajectories.
Revisions become necessary when FDA software-as-medical-device classification determinations, biotech funding collapse, or hyperscaler pricing disruption materialize outside modeled assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and cloud security certification acceptance. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare Information Exchange Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
Indonesia Connected Healthcare Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
Global Health IT Security Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
Middle East and Africa Healthcare Archiving and Ediscovery Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Healthcare Application Programming Interfaces Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Healthcare Operational Analytics Market