
 Artificial Intelligence in Epidemiology Market | 2026-2036
Artificial Intelligence in Epidemiology Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Epidemiology Market Analysis
Subscription-based SaaS licensing and pay-per-analytics models is rewriting capital requirements for new entrants, lowering barriers for mid-size health IT vendors. Microsoft Corporation leverages its cloud infrastructure to anchor enterprise-scale epidemiology deployments across government contracts. Epic Systems Corporation specializes in EHR-integrated surveillance workflows that dominate hospital network procurement. Siemens Healthineers sustains imaging-AI synergies that extend into outbreak detection protocols.
Artificial intelligence in epidemiology denotes computational systems that apply machine learning algorithms, natural language processing pipelines, and neural network architectures to infectious disease data for pattern recognition, transmission modeling, and intervention optimization. These systems process structured clinical records, unstructured case reports, and genomic sequencing outputs to generate actionable public health intelligence. Machine learning and deep learning technologies capture the dominant share of deployed solutions, while natural language processing exhibits the fastest expansion as health agencies automate literature and social media monitoring for early outbreak signals. Predictive modeling applications command premium pricing due to their direct impact on resource allocation decisions during health emergencies.
The FDA oversees algorithm validation and clinical evidence standards for AI-driven diagnostic and surveillance tools in the United States, while the EMA and national regulators across Europe enforce CE marking and MDR compliance for epidemiology software classified as medical devices. HIPAA and GDPR frameworks impose strict constraints on cross-border patient data flows, shaping cloud architecture choices and vendor geographic deployment strategies. Stakeholders must monitor evolving interoperability mandates and data localization requirements that will determine which platform architectures achieve sustainable market access.
Market Dynamics
FDA validation requirements for AI/ML-based medical devices are compressing vendor certification timelines while simultaneously filtering out undercapitalized entrants, reshaping competitive density in predictive epidemiology platforms.
Growth Catalysts
- FDA Algorithm Validation Guidance:The FDA's evolving clinical evidence standards for AI-driven surveillance tools are accelerating enterprise procurement cycles among hospital networks seeking regulatory certainty.
- Cloud Infrastructure Maturation:Microsoft Azure and AWS GovCloud deployments are virtualizing compute requirements for real-time outbreak modeling, reducing capital barriers for mid-size public health agencies.
- Genomic Sequencing Integration:Pathogen surveillance programs are embedding machine learning pipelines directly into CDC and state laboratory workflows, creating persistent demand for variant-tracking algorithms.
Market Restraints
- HIPAA-GDPR Data Friction:Cross-border patient record transfers face strict de-identification requirements that fragment cloud architecture choices and inflate compliance engineering costs.
- Specialized Talent Scarcity:The intersection of epidemiological domain expertise and production-grade ML engineering remains concentrated in Boston, London, and Singapore hiring pools.
- Validation Timeline Compression:FDA 510(k) pathways for AI/ML-based Software as a Medical Device now demand prospective clinical studies that extend commercialization cycles by 18-24 months.
Strategic Opportunities
- Social Media Signal Mining:Natural language processing pipelines applied to Twitter and Reddit data streams are creating early-warning systems for foodborne illness clusters ahead of formal case reporting.
- EMA MDR Harmonization:The European Medical Device Regulation's risk-classification framework for epidemiology software is opening CE-marked pathways for predictive analytics vendors with existing FDA clearances.
- Wastewater Surveillance Expansion:University research consortia and municipal utilities are deploying AI-powered pathogen concentration models that bypass traditional clinical testing infrastructure entirely.
Industry Challenges
- EHR Interoperability Fragmentation:Epic, Cerner, and Meditech data schemas require custom API integration for each health system deployment, inflating implementation timelines and professional services dependency.
- Algorithmic Bias Auditing:CDC and state health departments now mandate demographic parity testing for outbreak risk scores, adding validation layers that most vendors lack internal capacity to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Epidemiology Market |
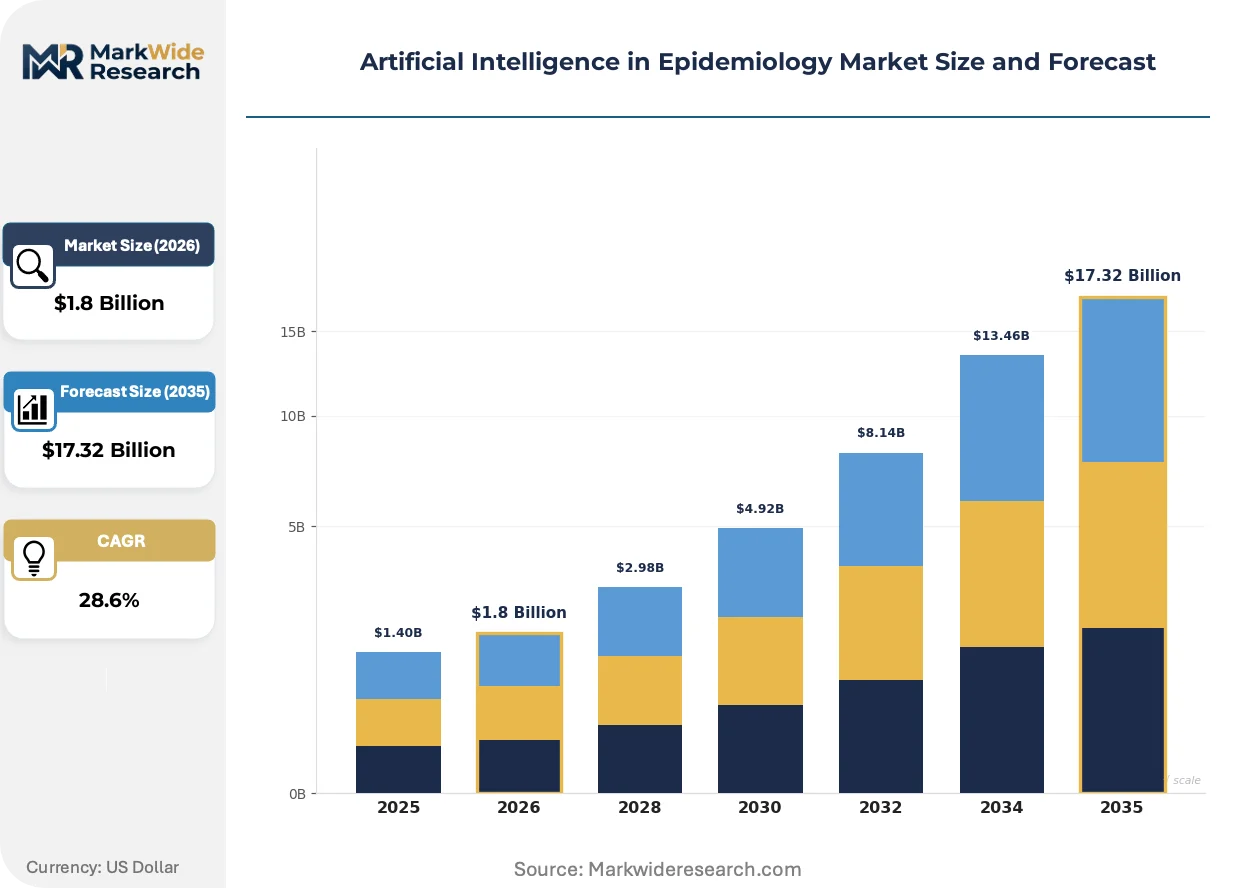
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Disease Surveillance, Predictive Modeling, Data Analysis, Patient Monitoring Technology: Machine Learning, Natural Language Processing, Neural Networks, Deep Learning End User: Public Health Agencies, Research Institutions, Hospitals, Pharmaceutical Companies Solution: Data Integration, Risk Assessment, Forecasting Tools, Reporting Systems |
| Companies Covered | Alphabet Inc, Microsoft Corporation, Cerner Corporation, Siemens Healthineers, Komodo Health, Cognizant, Epic Systems Corporation, Intel Corporation, eClinical Works Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Epidemiology Market Emerging Trajectories
Computational epidemiology is pivoting from retrospective outbreak analysis to preemptive intervention orchestration, driven by real-time data fusion architectures and shifting procurement accountability from IT departments to clinical operations leadership.
Digital twin technology is virtualizing population-level disease transmission dynamics, enabling health agencies to simulate intervention scenarios before resource deployment. State-level public health laboratories in California, New York, and Texas are piloting these systems for influenza and RSV forecasting. The technology is compressing the feedback loop between surveillance signal detection and policy response from weeks to hours.
The EU AI Act's risk-tier classification system is redefining compliance architecture for epidemiology software vendors seeking European market access. High-risk system designations now mandate conformity assessments, quality management systems, and post-market monitoring protocols that mirror pharmaceutical traceability requirements. Vendors with existing MDR certifications are adapting faster than pure-play AI entrants lacking established regulatory affairs infrastructure.
Hospital procurement committees are consolidating epidemiology analytics spend under value-based care contracts rather than standalone IT line items. Integrated delivery networks in the United States now bundle outbreak detection capabilities with population health management platforms, displacing point-solution vendors. This concentration is most visible in the Southeast and Midwest, where Catholic health systems and regional cooperatives dominate purchasing decisions.
Artificial Intelligence in Epidemiology Market Segmentation
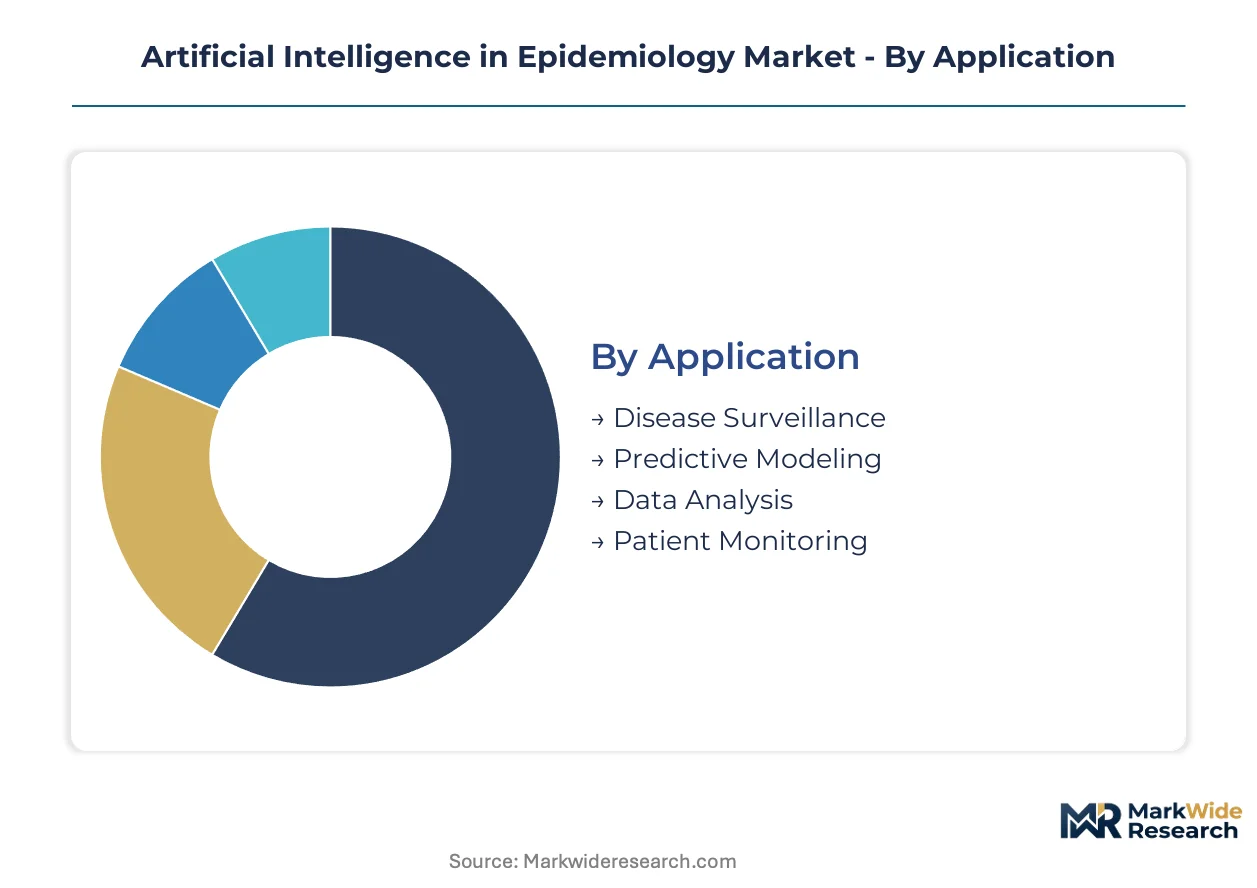
Segmentation reveals how AI epidemiology solutions align with distinct operational workflows and procurement budgets across health systems. Each dimension exposes different competitive dynamics and vendor specialization patterns.
Application:
The use-case spectrum spans reactive surveillance through preemptive intervention orchestration, with each application commanding different technical specifications and pricing tiers.
- Disease Surveillance:Real-time case detection systems ingest EHR feeds, laboratory information management outputs, and syndromic data streams for outbreak identification. Public health agencies in the United States prioritize FDA-cleared surveillance platforms for hospital network procurement, driven by federal pandemic preparedness infrastructure investments.
- Predictive Modeling:Transmission dynamics algorithms simulate pathogen spread across populations to optimize resource pre-positioning. State-level laboratories in California, New York, and Texas deploy these tools for influenza and RSV forecasting, with procurement committees bundling capabilities under value-based care contracts rather than standalone IT purchases.
- Data Analysis:Pattern recognition engines process structured clinical records and unstructured case reports for epidemiological intelligence.
- Patient Monitoring:Individual-level risk stratification tools track infection progression and treatment response within hospital workflows.
The dominant share belongs to Disease Surveillance, while Predictive Modeling is closing the gap fastest.
Technology:
Cost tier differentiation separates production-grade deployments from experimental implementations, with infrastructure requirements scaling sharply across the technology stack.
- Machine Learning:Supervised and unsupervised algorithms form the backbone of deployed epidemiology solutions, processing structured datasets for classification and clustering tasks. Health agencies favor ML pipelines for their interpretability and regulatory auditability compared to black-box alternatives.
- Deep Learning:Multi-layer neural architectures extract complex patterns from high-dimensional genomic and imaging data for variant tracking and outbreak signature detection. CDC and state laboratory workflows embed these systems for pathogen surveillance, creating persistent demand despite higher computational costs.
- Natural Language Processing:Text mining pipelines automate literature surveillance and social media signal extraction for early outbreak detection.
- Neural Networks:Connectionist architectures support specialized tasks including genomic sequence classification and epidemiological time-series forecasting.
Machine Learning and Deep Learning together anchor procurement volumes, though Natural Language Processing is expanding most quickly as agencies automate signal detection.
End User:
Customer type determines deployment scale, with procurement authority shifting from IT departments to clinical operations leadership across integrated delivery networks.
- Public Health Agencies:Federal, state, and municipal health departments operate the largest-scale deployments, with the CDC and state laboratories driving standardization requirements. These entities mandate demographic parity testing for outbreak risk scores, adding validation layers that shape vendor development roadmaps.
- Hospitals:Acute care systems and integrated delivery networks procure EHR-integrated surveillance workflows, with Epic Systems dominating procurement in the Southeast and Midwest where Catholic health systems and regional cooperatives concentrate purchasing decisions.
- Research Institutions:University consortia pilot wastewater surveillance and digital twin technologies before commercial transfer.
- Pharmaceutical Companies:Drug developers apply epidemiological AI for trial site selection and disease burden estimation in target populations.
Public Health Agencies command the largest contract values, while Hospitals are gaining procurement velocity fastest through value-based care integration.
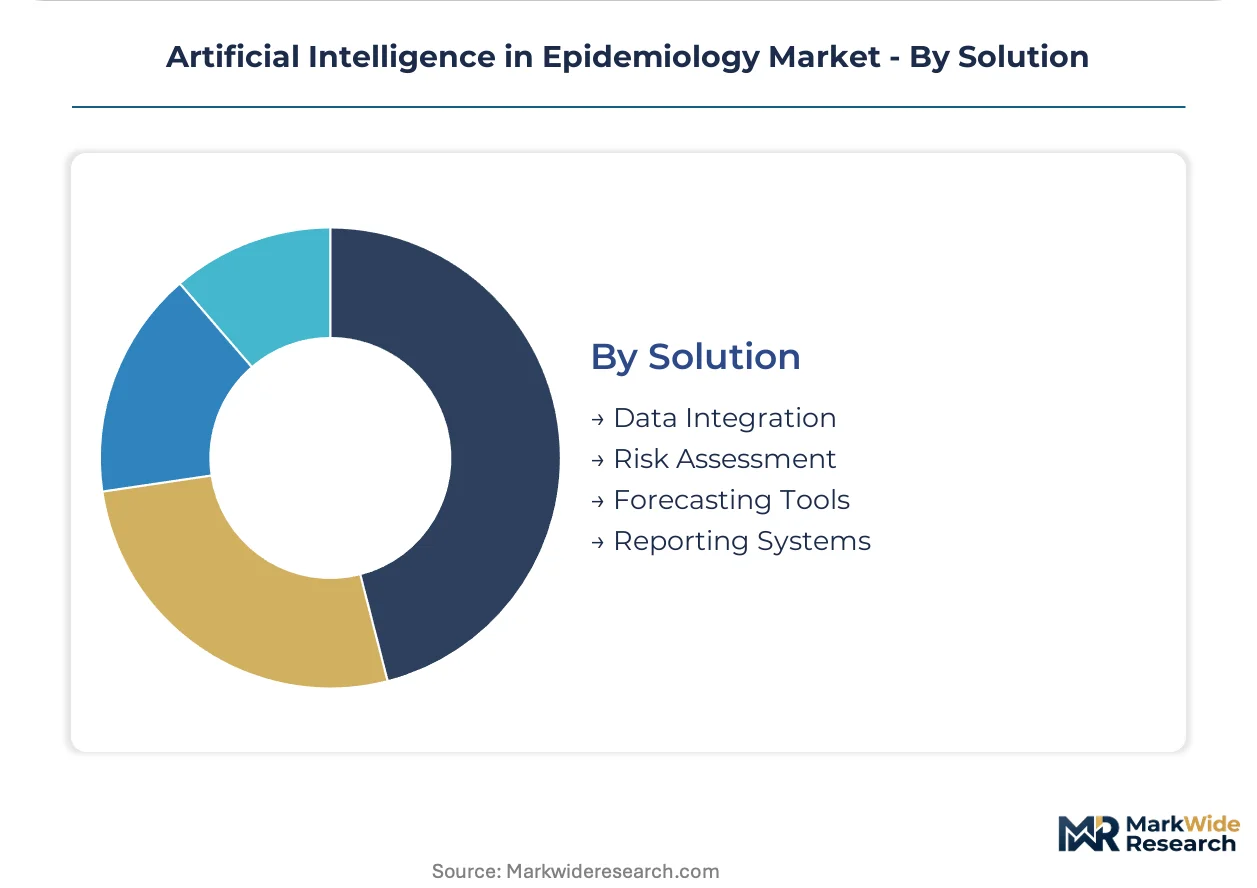
Solution:
Maturity gradients separate established infrastructure categories from emerging capability layers, with implementation timelines stretching longest for cross-cutting integration platforms.
- Data Integration:Interoperability middleware harmonizes Epic, Cerner, and Meditech schemas for unified epidemiological datasets. Custom API requirements for each health system deployment inflate professional services dependency and extend implementation timelines.
- Forecasting Tools:Predictive analytics modules project case counts, hospitalization peaks, and resource requirements for operational planning. These solutions carry premium pricing due to direct impact on emergency resource allocation decisions.
- Risk Assessment:Algorithmic scoring systems stratify population and individual-level infection probability for targeted intervention.
- Reporting Systems:Automated visualization and alert generation tools streamline regulatory compliance and stakeholder communication.
Data Integration holds the foundational position, though Forecasting Tools are climbing the fastest as procurement accountability shifts to clinical operations leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal pandemic preparedness infrastructure investments in the United States are accelerating AI epidemiology procurement cycles, while the EU AI Act's risk-tier classification system is redefining compliance architecture for vendors seeking European market access.
United States
The CDC and state laboratories in California, New York, and Texas drive persistent demand for variant-tracking algorithms and predictive modeling tools. FDA validation requirements for AI/ML-based Software as a Medical Device now mandate prospective clinical studies that extend commercialization timelines. Epic Systems dominates EHR-integrated surveillance procurement across Catholic health systems and regional cooperatives in the Southeast and Midwest.
United Kingdom
London-based research consortia pilot digital twin technologies and wastewater surveillance systems before commercial transfer to municipal utilities. The Medicines and Healthcare products Regulatory Agency enforces algorithm validation standards that align with emerging FDA guidance, creating dual-certification pathways for vendors. Greater Manchester and Oxfordshire clusters concentrate machine learning engineering talent for production-grade epidemiology deployments.
Germany
Siemens Healthineers anchors imaging-AI synergies that extend into outbreak detection protocols for hospital networks across Bavaria and Baden-Württemberg. The EU Medical Device Regulation's risk-classification framework opens CE-marked pathways for predictive analytics vendors with existing FDA clearances. Berlin-Brandenburg research institutions specialize in genomic sequencing integration for pathogen surveillance programs.
China
National health authorities deploy machine learning pipelines for real-time disease tracking across provincial laboratory networks in the Yangtze River Delta and Pearl River Delta regions. The National Medical Products Administration oversees algorithm validation for AI-driven diagnostic tools, accelerating enterprise procurement among hospital networks seeking regulatory certainty. Beijing-Tianjin-Hebei corridor concentrates deep learning research for high-dimensional genomic data analysis.
Singapore
The Ministry of Health anchors Southeast Asian demand for EHR-integrated surveillance workflows and social media signal mining systems. Strict data localization requirements under national privacy frameworks shape cloud architecture choices for vendors seeking sustainable market access. Biopolis research cluster specializes in natural language processing pipelines for early outbreak detection across regional health agencies.
Artificial Intelligence in Epidemiology Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where cloud infrastructure vendors and EHR-integrated workflow specialists command premium positioning. The vendor base separates into three strategic archetypes: hyperscale cloud platforms anchoring government contracts, health IT incumbents dominating hospital network procurement, and point-solution AI vendors pursuing social media and wastewater surveillance niches. Dominant competitive moves include strategic partnerships between cloud providers and public health agencies, plus portfolio diversification into predictive analytics modules.
Within the health IT incumbent tier, Epic Systems Corporation and Cerner Corporation exemplify EHR-integrated surveillance specialists, while Microsoft Corporation anchors the hyperscale cloud platform archetype for enterprise-scale epidemiology deployments. These three entities occupy positions that reflect the market's concentration around federal contract vehicles and value-based care procurement consolidation.
| Leading Market Players |
|---|
| Alphabet Inc |
| Microsoft Corporation |
| Cerner Corporation |
| Siemens Healthineers |
| Komodo Health |
| Cognizant |
| Epic Systems Corporation |
| Intel Corporation |
| eClinical Works Inc |
| Others |
Supply Flow & Price Mechanics
Cloud compute concentration in the United States within Microsoft Azure and AWS GovCloud deployments anchors margin pools downstream at the SaaS application layer, where epidemiology software vendors extract premium pricing for FDA-cleared predictive modules.
Pricing Analysis
Certification level creates the primary spread between vendor tiers. Three-tier pricing structure across FDA-cleared premium, CE-marked standard, and uncertified economy levels dominates procurement. Subscription-based SaaS licensing with per-analytics consumption models anchors the dominant pricing structure. Price differentiation stems from validation depth and cloud infrastructure scale. Cost compression in economy tiers is intensifying because hospital procurement committees now bundle epidemiology spend under value-based care contracts. Public health agencies exhibit lowest price sensitivity due to federal pandemic preparedness infrastructure investments.
Supply Chain Analysis
Single-source vulnerability in specialized GPU hardware sourced from Taiwan and South Korea dominates supply chain risk assessment for deep learning training clusters. Geographic supply concentration centers on the United States for cloud infrastructure, India for NLP engineering talent, and Germany for imaging-AI hardware integration. Raw material dependencies draw from semiconductor lithography equipment, high-bandwidth memory modules, and genomic sequencing reagents. Regulatory restriction risk intensifies through HIPAA-GDPR data localization mandates that fragment cross-border deployment architectures. Distribution runs through direct enterprise sales to public health agencies and health IT channel partners for hospital network penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 510(k) validation pathways creates formidable defensive moats for established vendors, as prospective clinical study requirements extend commercialization timelines beyond the capital endurance of undercapitalized entrants.
For Market Incumbents: Harden certification portfolios through prospective clinical study investment for AI/ML-based Software as a Medical Device submissions, neutralizing emerging entrant threats from pure-play AI vendors lacking regulatory affairs infrastructure. Deepen vertical integration into cloud infrastructure partnerships with Azure and AWS GovCloud to lock in government contract vehicles. Prioritize demographic parity testing capabilities to meet CDC algorithmic bias auditing mandates. For New Entrants and Emerging Players: Establish a beachhead in wastewater surveillance and social media signal mining niches where EHR-integrated incumbents lack established presence. Municipal utilities and university research consortia represent the most penetrable buyer archetype. Pursue white-label partnerships with cloud infrastructure providers to bypass direct FDA validation requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed health IT vendors possessing FDA-cleared surveillance platforms but lacking predictive analytics modules. Long-term viability hinges on regulatory entrenchment depth rather than algorithmic novelty. Watch for EU AI Act high-risk system designations as an inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Prospective clinical studies compress vendor certification timelines while filtering undercapitalized competitors. |
| Cloud Infrastructure Partnership | Azure and AWS GovCloud deployments anchor enterprise-scale epidemiology contracts across federal agencies. |
| EHR Integration Deepening | Epic Systems workflows dominate Catholic health system procurement in Southeast and Midwest regions. |
| CE Marking Pathway Expansion | EU MDR harmonization opens European market access for vendors with existing FDA clearances. |
| Wastewater Surveillance Pilot | Municipal utilities bypass traditional clinical testing infrastructure entirely for pathogen detection. |
Methodological Framework
The analysis maps machine learning deployment pipelines, deep learning training clusters, and NLP signal detection systems, each validated through epidemiologists, biomedical engineers, hospital purchasing committees, and public health IT directors. Primary interview data triangulates against FDA 510(k) filing databases, EMA MDR submission records, CDC procurement contract disclosures, and GPO pricing benchmarks. Bottom-up segmentation modeling reconciles with top-down federal pandemic preparedness infrastructure investment flows.
Fixed assumptions across the analysis window hold cloud infrastructure maturation and FDA validation guidance evolution at observed trajectory levels, while varying genomic sequencing integration depth and social media signal mining adoption rates. Segmentation dimensions include technology stack tier, application workflow type, end-user procurement authority, and solution maturity gradient. CAGRs derive from logistic diffusion modeling of regulatory clearance velocity and health system procurement cycle compression. Forecast inputs incorporate state laboratory workflow automation rates and value-based care contract bundling penetration.
Stress conditions across FDA timeline extension, HIPAA-GDPR enforcement intensification, and specialized talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumption sets and acknowledge algorithmic bias auditing mandate expansion as a specific revision trigger. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Health Information Exchange (HIE) Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Healthcare Laboratory Informatics Market
Health Informatics
Allergy Care Market
Health Informatics
Healthcare API Market
Health Informatics
Vocal Biomarkers Market
Health Informatics
Laboratory Informatics Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Healthcare Natural Language Processing Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Global Radiology Information Systems Market
Health Informatics
IHE XDS.B Market
Health Informatics
Healthcare Operational Analytics Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
Global Health IT Security Market