
 Global Laboratory Information System Market | 2026-2036
Global Laboratory Information System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Information System Market Foresight
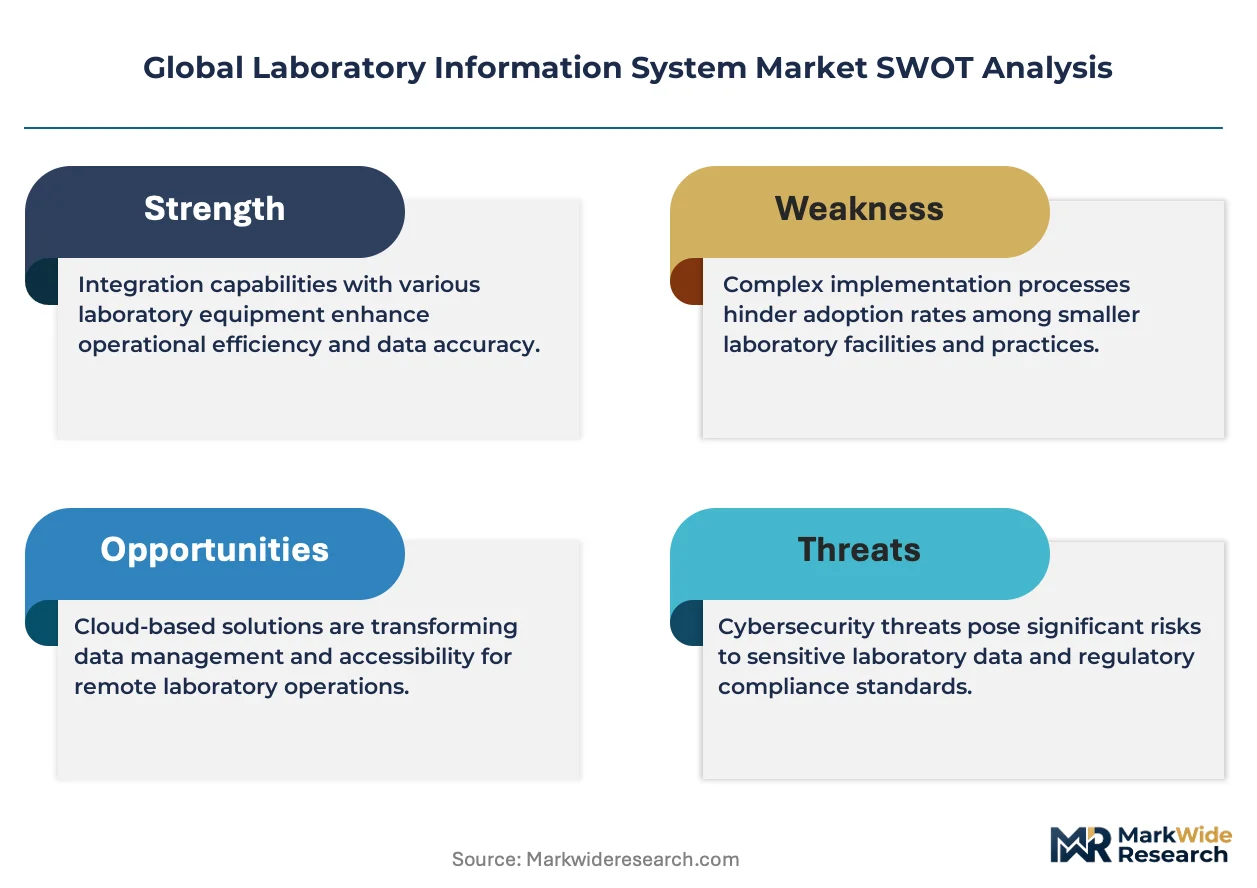
The capital-intensity divergence between cloud-native platforms and legacy on-premise installations is redrawing competitive boundaries in laboratory informatics. Thermo Fisher Scientific leverages its instrument-to-software integration to dominate high-throughput clinical environments. LabWare sustains its position through deep configurability in regulated pharmaceutical quality labs. STARLIMS Corporation anchors its presence in forensic and government contract channels where audit trails carry premium value.
A laboratory information system comprises software infrastructure that manages sample workflows, analytical data, and regulatory documentation across clinical and research environments; these platforms integrate instrument interfacing, barcode tracking, and automated reporting to ensure chain-of-custody integrity and compliance traceability. Cloud-based deployments now capture the fastest expansion as laboratories prioritize remote accessibility and reduced IT overhead, while on-premise installations retain dominance in government agencies and facilities with strict data-localization mandates. The clinical diagnostics application segment leads in absolute spending, though research laboratories show accelerating uptake as multi-site genomics studies demand centralized data harmonization.
FDA oversight of clinical decision-support algorithms and HIPAA security requirements directly shape product roadmaps for vendors serving US healthcare systems, while EMA's MDR and GDPR compliance obligations constrain European deployment architectures and data-residency specifications. ISO 15189 accreditation standards further dictate quality-management module requirements for laboratories seeking international recognition. Stakeholders must weigh interoperability investments against regulatory fragmentation as regional compliance divergences deepen.
Market Dynamics
Cloud-native LIS architectures are compressing deployment timelines from eighteen months to under six weeks, forcing legacy vendors to rewrite core platforms or cede mid-market clinical laboratories to SaaS-native entrants.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature mandates in US pharmaceutical quality labs accelerate validated LIS replacements, particularly among generic drug manufacturers expanding analytical capacity.
- Genomics data harmonization:Multi-site precision medicine studies require centralized LIS platforms with API-first architectures, pulling research institutions toward cloud deployments.
- Japan's diagnostic infrastructure modernization:METI funding for regional hospital consolidation drives standardized LIS procurement across prefectural laboratory networks.
Market Restraints
- Specialized bioinformatics talent scarcity:Laboratory IT departments face twelve-to-eighteen-month hiring cycles for LIS administrators with both clinical workflow and cybersecurity expertise.
- Data-localization mandates:German and French healthcare authorities enforce sovereign cloud requirements that fragment vendor scale economies and complicate multi-national rollouts.
- Legacy instrument interfacing:Proprietary communication protocols from 1990s-era analyzers resist HL7 FHIR conversion, trapping facilities in maintenance-heavy on-premise configurations.
Strategic Opportunities
- India's PLI scheme for diagnostics:Domestic manufacturing incentives attract LIS vendors to localize cloud infrastructure and capture price-sensitive pathology chain expansions.
- AI-assisted pathology workflows:Integration of whole-slide imaging with predictive analytics creates new module categories for digital pathology-first LIS platforms.
- Subscription-based instrument-software bundles:Reagent rental models in clinical chemistry are extending to include embedded LIS licensing, reshaping vendor-customer relationships.
Industry Challenges
- ISO 15189 accreditation timelines:Quality-management module validation for international laboratory standards requires six-to-nine-month implementation cycles that delay revenue recognition.
- Interoperability testing burden:Each new instrument interface demands site-specific validation protocols, inflating professional services costs and compressing gross margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Information System Market |
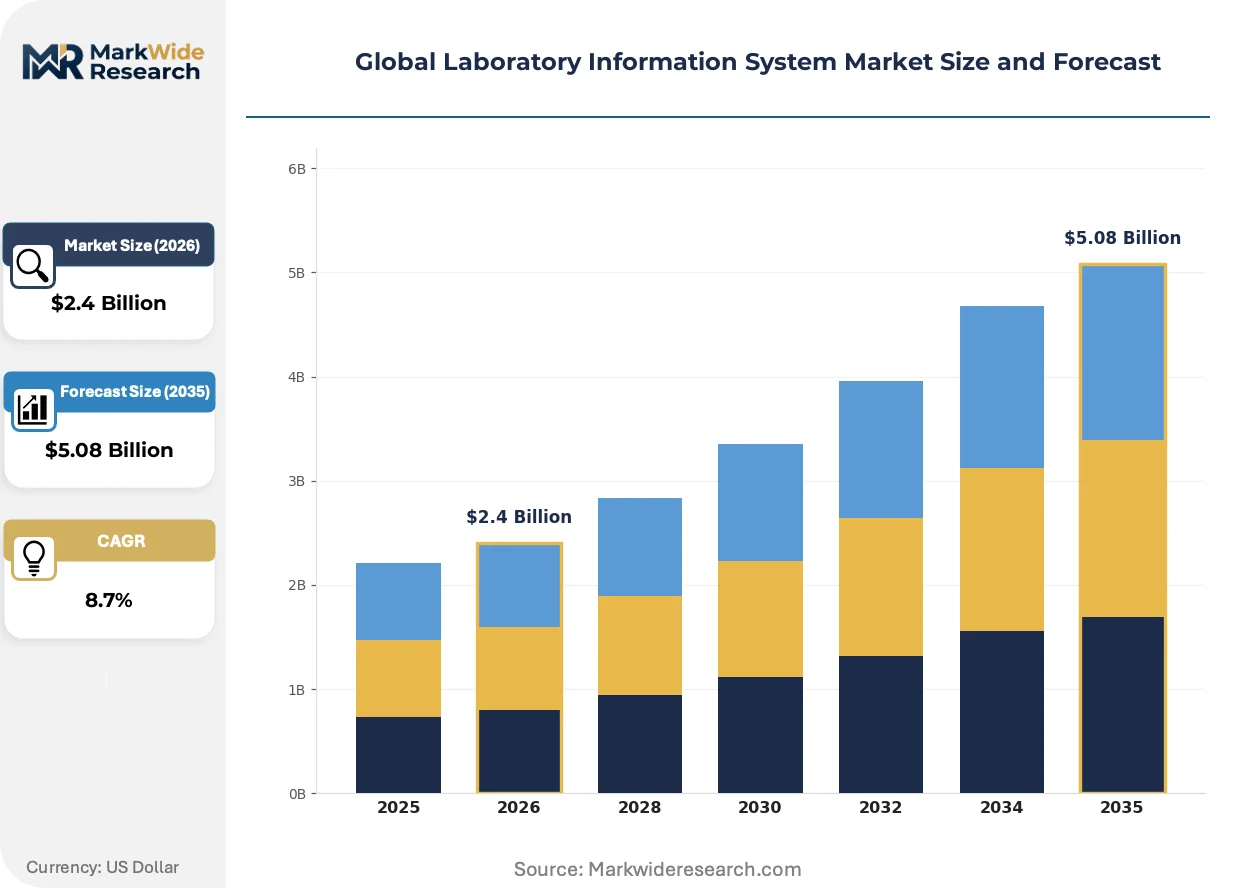
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Web-Hosted, Hybrid Deployment: Public Cloud, Private Cloud, Community Cloud, Multi-Cloud Application: Clinical Diagnostics, Research Laboratories, Forensic Analysis, Environmental Testing, Quality Management End User: Hospitals, Pharmaceutical Firms, Academic Institutions, Government Agencies |
| Companies Covered | Thermo Fisher Scientific, Siemens, LabVantage Solutions Inc., LabWare, Autoscribe Informatics, PerkinElmer Inc., Abbott Laboratories, STARLIMS Corporation, LabLynx, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Information System Market Shifts & Advancements
Artificial intelligence integration is splitting LIS product roadmaps between embedded analytics engines and standalone decision-support modules, with vendor strategies diverging sharply on data ownership and liability allocation.
Containerized microservices architecture is bifurcating the vendor landscape. SaaS-native platforms deploy feature updates weekly through automated pipelines, while monolithic legacy systems require quarterly release cycles that frustrate laboratory directors. Academic medical centers with dedicated devops teams favor API-extensible platforms; community hospitals prioritize pre-configured specialty templates that minimize customization.
EMA's MDR traceability requirements are mandating end-to-end sample lineage documentation across in-vitro diagnostic workflows. Device manufacturers must now demonstrate LIS integration capabilities during conformity assessments, shifting procurement evaluation criteria toward interoperability certifications. European contract research organizations report eighteen-month backlogs for MDR-compliant LIS validations.
Consolidated procurement by multi-site diagnostic chains is displacing single-laboratory purchasing autonomy. National pathology networks in the United Kingdom and Australia now mandate centralized LIS standards, forcing independent laboratories to adopt parent-company platforms or exit network contracts. Vendor sales cycles have elongated as economic buyers shift from laboratory directors to health system procurement committees.
Global Laboratory Information System Market Segmentation
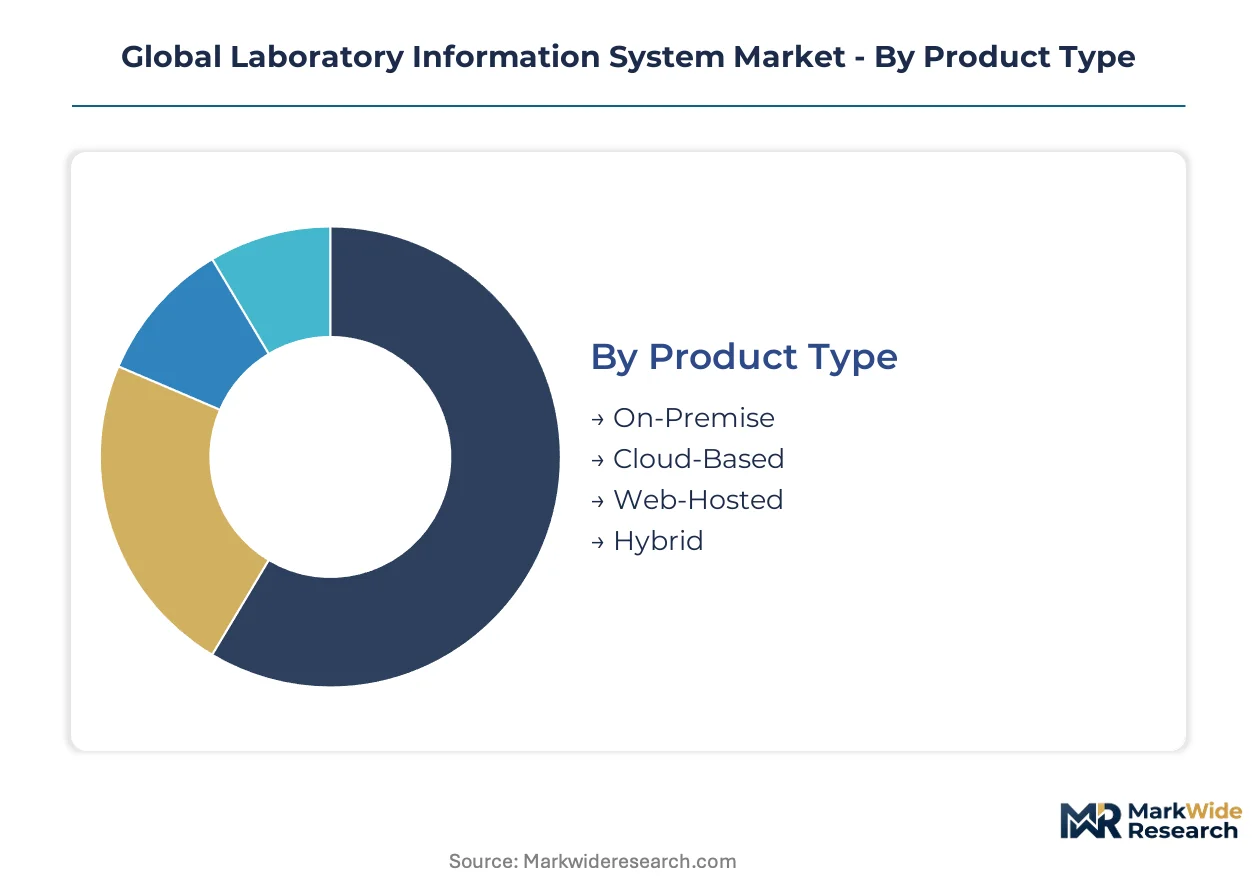
Laboratory information systems fragment across deployment architectures and compliance postures, with procurement decisions increasingly driven by data residency mandates and interoperability requirements. Understanding these segment boundaries reveals where vendor R&D investments concentrate and where margin structures diverge most sharply.
Product Type:
FDA 21 CFR Part 11 validation requirements and GDPR data-localization clauses create divergent compliance burdens across deployment modes, directly shaping total cost of ownership calculations.
- On-Premise:Infrastructure resides within facility-controlled server environments with direct hardware management. Government agencies in Germany and Japan mandate these configurations for forensic and public health laboratories where sovereign data control overrides operational efficiency considerations.
- Cloud-Based:Fully managed SaaS platforms eliminate capital expenditure for server hardware while shifting liability models. Multi-site hospital networks in the United States accelerate procurement here as HIPAA business associate agreements mature and remote accessibility becomes non-negotiable for distributed pathology review.
- Web-Hosted:Browser-accessible applications with vendor-managed hosting but client-dedicated instances. Academic medical centers in Australia favor this middle path for research collaborations requiring custom integration without full infrastructure burden.
- Hybrid:Split architectures maintaining sensitive workloads on-premise while leveraging cloud elasticity for analytics and reporting. Pharmaceutical quality labs adopt this model to ring-fence proprietary assay data while enabling centralized regulatory submission preparation.
Established volume favors On-Premise; emerging adoption favors Cloud-Based.
Deployment:
Cost tier differentiation separates enterprise-grade private infrastructure from commodity public offerings, with community models capturing cooperative purchasing efficiencies among regional laboratory networks.
- Public Cloud:Shared infrastructure with metered consumption pricing and automatic scaling. Community hospitals and independent pathology chains in India deploy here to minimize upfront investment while accessing enterprise-grade security certifications.
- Private Cloud:Single-tenant environments with dedicated resource isolation and custom security policies. Large pharmaceutical manufacturers in Switzerland and the United States require these configurations for GxP-validated manufacturing support systems.
- Community Cloud:Collaborative infrastructure serving multiple organizations with shared compliance frameworks. National laboratory networks in the United Kingdom standardize on this model to achieve procurement scale without surrendering operational autonomy to commercial hyperscalers.
- Multi-Cloud:Orchestrated workloads across heterogeneous provider environments to mitigate vendor lock-in. Research consortia conducting international genomics studies adopt this architecture to satisfy conflicting data residency requirements across jurisdictions.
Private Cloud commands premium pricing; Public Cloud shows steepest expansion trajectory.
Application:
Customer type concentration varies dramatically by workflow complexity, with regulated diagnostic environments demanding validated modules that research settings often bypass.
- Clinical Diagnostics:Patient-facing test processing with direct EHR integration and diagnostic reporting. Hospital laboratories in the United States, Germany, and Japan drive absolute spending here as diagnostic infrastructure modernization programs accelerate replacement cycles.
- Research Laboratories:Investigational sample management with flexible protocol configuration and multi-site data harmonization. Academic institutions conducting precision medicine initiatives favor platforms with API-first architectures enabling custom analytics pipeline integration.
- Forensic Analysis:Chain-of-custody documentation with courtroom-admissible audit trails and tamper-evident records. Government crime laboratories prioritize these specialized modules where procedural integrity carries legal liability implications.
- Environmental Testing:Field sample logistics with geospatial tracking and regulatory threshold monitoring. Commercial laboratories serving industrial clients in France and the Netherlands configure these workflows for compliance with EU environmental directives.
- Quality Management:Manufacturing support with batch release documentation and deviation tracking. Pharmaceutical and medical device manufacturers require these modules for ISO 15189 and FDA cGMP compliance.
Clinical Diagnostics absorbs majority procurement volume; Research Laboratories gain share fastest.
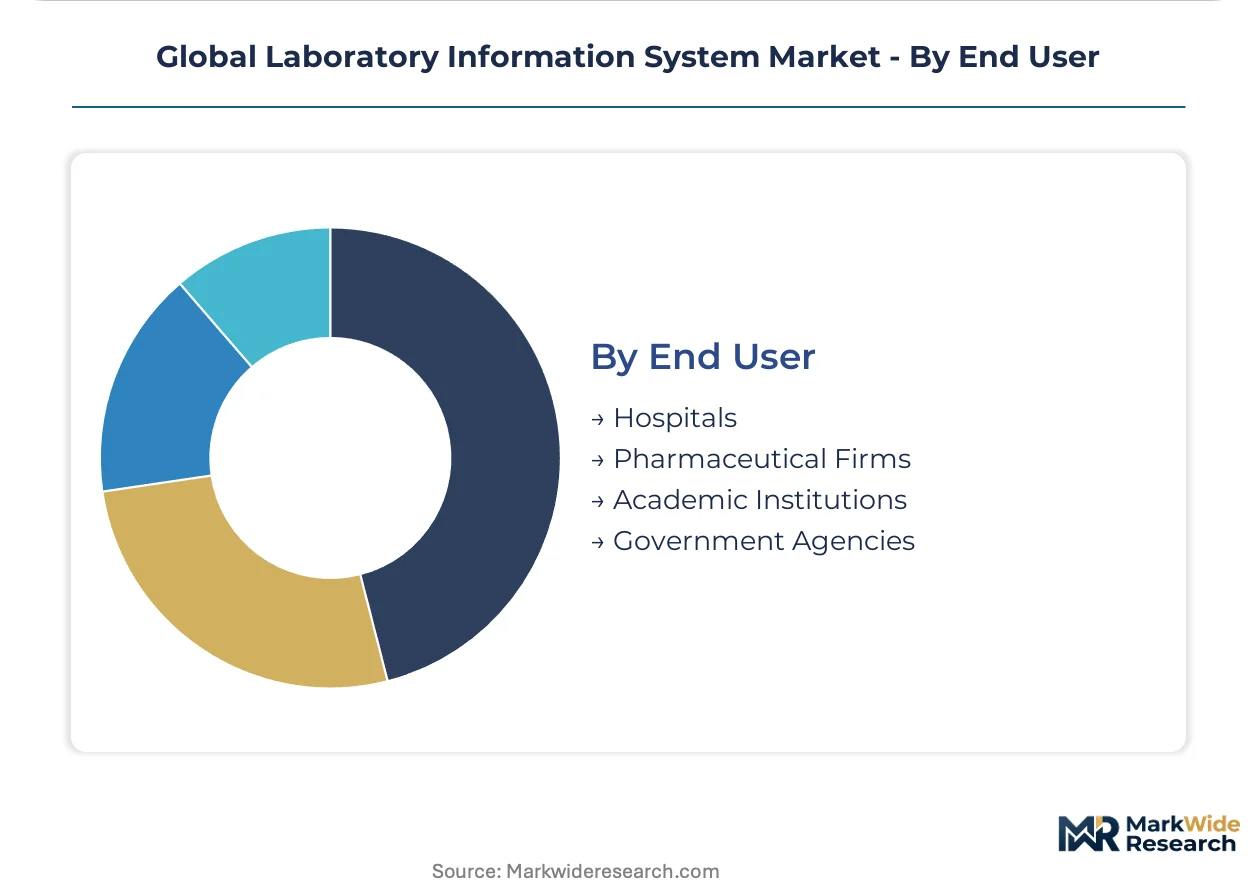
End User:
Maturity differentiation separates institutions with dedicated informatics teams from resource-constrained organizations requiring pre-configured specialty templates.
- Hospitals:Integrated health system laboratories requiring seamless EHR connectivity and enterprise-wide standardization. Multi-site networks in Australia and the United Kingdom mandate centralized platform selections, compressing vendor choice autonomy at individual facilities.
- Pharmaceutical Firms:R&D and manufacturing quality operations with GxP validation requirements and global data harmonization needs. Companies expanding generic drug manufacturing capacity in India accelerate validated LIS procurement to meet FDA inspection readiness standards.
- Academic Institutions:Research-focused deployments with grant-funded customization tolerance and devops-capable technical staff. Universities with dedicated bioinformatics cores favor extensible platforms over pre-packaged clinical solutions.
- Government Agencies:Public health surveillance and forensic operations with sovereign data mandates and extended procurement cycles. National laboratories in Japan leverage METI funding for standardized regional hospital network consolidation.
Hospitals dominate current installed base; Pharmaceutical Firms show strongest upgrade momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic infrastructure modernization follows divergent paths across major economies. The United States prioritizes HIPAA-compliant cloud migration for distributed hospital networks, while Germany enforces sovereign data localization that fragments vendor scale. Japan channels METI funding toward prefectural laboratory consolidation, and India's domestic manufacturing incentives attract localized cloud infrastructure investment.
United States
FDA 21 CFR Part 11 mandates and multi-site health system consolidation accelerate cloud-native LIS procurement. Hospital networks across Texas, Florida, and the Midwest demand seamless EHR integration for distributed pathology review. Academic medical centers in Boston and the San Francisco Bay Area favor API-extensible platforms for precision medicine research.
Germany
Data-localization requirements from health authorities and ANSM/CNIL-aligned sovereign cloud mandates reshape procurement architectures. Pharmaceutical quality labs in Bavaria and Baden-Württemberg maintain on-premise configurations for GxP-validated manufacturing support. Regional hospital networks in North Rhine-Westphalia navigate EMA MDR traceability obligations for in-vitro diagnostic workflows.
Japan
METI funding for regional hospital consolidation drives standardized LIS procurement across prefectural laboratory networks. Public health surveillance operations in Tokyo and Osaka require sovereign data control for forensic and epidemiological applications. Diagnostic infrastructure modernization concentrates in Kanto and Kansai metropolitan clusters.
India
PLI scheme incentives for domestic diagnostics manufacturing attract LIS vendors to localize cloud infrastructure. Price-sensitive pathology chains in Maharashtra and Gujarat accelerate procurement as generic drug manufacturers expand analytical capacity. CDSCO inspection readiness standards push validated system adoption among pharmaceutical quality operations.
United Kingdom
National pathology network consolidation mandates centralized LIS standards across NHS trusts. Community cloud deployments serve regional laboratory cooperatives in England and Scotland without surrendering autonomy to commercial hyperscalers. Academic institutions in Cambridge and Oxford favor web-hosted configurations for multi-site genomics research collaborations.
Global Laboratory Information System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in laboratory informatics. Instrument-to-software bundling and deep configurability for regulated environments define the upper tier, while mid-market SaaS entrants capture cloud-first clinical laboratories. Strategic archetypes include integrated life sciences conglomerates, configurable enterprise software specialists, and forensic-focused compliance vendors. Competitive moves concentrate on API-first architecture development and subscription-based instrument-software bundling.
Within the integrated instrumentation tier, Thermo Fisher Scientific and PerkinElmer Inc. occupy positions that exemplify hardware-software convergence strategies. LabWare and STARLIMS Corporation represent the configurability-specialist archetype for regulated pharmaceutical and forensic environments respectively. Siemens and Abbott Laboratories anchor the diagnostic systems conglomerate segment with embedded LIS licensing extending from reagent rental models.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Siemens |
| LabVantage Solutions Inc. |
| LabWare |
| Autoscribe Informatics |
| PerkinElmer Inc. |
| Abbott Laboratories |
| STARLIMS Corporation |
| LabLynx, Inc. |
| Others |
Supply & Pricing Matrix
Long-term SaaS subscription contracts with embedded instrument-software bundling lock in both supply access and price visibility for multi-site hospital networks, compressing procurement cycles while stabilizing vendor revenue streams across the United States, Germany, and Japan.
Pricing Analysis
Professional services and validated module customization drive lifetime value beyond initial licensing. Three-tier pricing structure across enterprise, mid-market, and community-laboratory levels reflects deployment complexity and regulatory certification depth. Pricing pressure stems from SaaS-native entrants undercutting legacy on-premise maintenance contracts. Community hospitals exhibit highest price sensitivity; pharmaceutical quality labs with GxP mandates show lowest.
Supply Chain Analysis
Specialized HL7 FHIR middleware development concentrates in the United States, India, and Ireland. Cloud infrastructure provisioning draws from hyperscaler data centers in Frankfurt, Singapore, and Virginia. Single-source vulnerability in legacy instrument protocol adapters threatens interoperability timelines. Distribution runs through direct vendor sales teams and health system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laboratory information system market sits in early-cycle expansion as cloud-native architectures displace eighteen-month on-premise deployments, creating whitespace for SaaS entrants to capture mid-market clinical laboratories before legacy vendors complete platform rewrites.
For Market Incumbents: Fortify API-first architecture investments to defend against SaaS-native competitors compressing deployment timelines to six weeks. Deepen backward integration into instrument protocol adapters to reduce third-party dependency. Prioritize ISO 15189 pre-validated modules to accelerate customer accreditation cycles and differentiate from configurable-but-unvalidated alternatives. For New Entrants and Emerging Players: Lead with AI-assisted pathology workflow modules targeting community hospital networks in India's Maharashtra and Gujarat states where CDSCO inspection readiness standards create urgent replacement demand. Emphasize subscription-based pricing with rapid deployment guarantees. Capture forensic laboratory segments where audit-trail specialization commands premium positioning against generalist platforms. For Investors and Strategic Acquirers: Capital is best deployed toward SaaS-native platforms with containerized microservices architecture and established HIPAA business associate agreements. The five-to-ten-year viability window favors vendors with demonstrated multi-cloud orchestration capabilities for international genomics consortia. Watch for inflection signals in Japan's METI-funded prefectural consolidation contracts as indicators of sovereign-cloud procurement standardization.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Enables weekly feature updates through automated pipelines, matching SaaS-native competitor velocity. |
| Instrument-Software Bundle Licensing | Extends reagent rental models to embed LIS licensing, reshaping vendor-customer relationships in clinical chemistry. |
| ISO 15189 Pre-Validation Investment | Compresses six-to-nine-month implementation cycles, accelerating revenue recognition for quality-management modules. |
| Multi-Cloud Orchestration Capability | Satisfies conflicting data residency requirements across German, French, and Japanese sovereign cloud mandates. |
| AI-Assisted Pathology Module Launch | Captures digital pathology-first procurement as whole-slide imaging integrates with predictive analytics workflows. |
Research Methodology
Cross-validation between primary interviews with laboratory informatics directors, hospital procurement committee members, LIS implementation specialists, and regulatory compliance officers anchors the qualitative findings against secondary sources including FDA 510(k) filings, EMA MDR technical documentation, hospital GPO contract databases, and hyperscaler healthcare cloud certification disclosures. Bottom-up triangulation from individual laboratory deployment data and top-down validation from vendor revenue segmentation ensure methodological rigor.
Sensitivity analysis across deployment architecture, application type, and end-user institution size dimensions shapes the analytical framework over the projection horizon. CAGRs derive from installed base erosion rates for on-premise systems and net-new adoption curves for cloud-native platforms. Modeled inputs include METI funding allocation trajectories for Japanese prefectural consolidation and India's PLI scheme incentive disbursement timelines for domestic diagnostics manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained HIPAA business associate agreement maturation and EMA MDR traceability requirement enforcement would require recalibration. Practitioners should keep alternative scenarios live as sovereign data localization mandates in Germany and France evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
Healthcare Laboratory Informatics Market
Health Informatics
IHE XDS.B Market
Health Informatics
Indonesia Connected Healthcare Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
AI in Healthcare Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Healthcare API Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Global Non Clinical Information System Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
Cat Allergy in Humans Market