
 Healthcare Information Exchange Market | 2026-2036
Healthcare Information Exchange Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Information Exchange Market Outlook
Hospital consolidation is repositioning procurement priorities for health information exchange platforms. Epic Systems Corporation leverages its dominant installed base across large academic medical centers to sustain long-term contracts. Cerner Corporation anchors its competitive stance through deep integration with federal health systems. Allscripts Healthcare Solutions specializes in ambulatory-focused interoperability tools that compete for mid-market share.
Healthcare information exchange encompasses the electronic movement of clinical, administrative, and financial data across disparate systems using standardized protocols such as HL7 FHIR and Direct Secure Messaging. Its primary purpose enables care coordination, reduces redundant testing, and supports population health analytics by breaking data silos between unaffiliated providers. Cloud-based solutions command the fastest expansion trajectory as health systems abandon on-premise infrastructure for scalable API architectures. Clinical data exchange retains the deepest margin pools due to real-time workflow integration requirements and persistent vendor stickiness. Blockchain remains nascent but attracts pilot funding from government agencies seeking immutable audit trails for Medicaid claims verification.
The Office of the National Coordinator for Health IT enforces information blocking rules under the 21st Century Cures Act, compelling vendors to enable patient-directed data access or face civil monetary penalties. HIPAA security standards shape product development roadmaps by mandating encryption, audit logging, and business associate agreements across all network transactions. CMS interoperability mandates for Medicare Advantage plans further tighten compliance timelines. Stakeholders must monitor emerging state-level health data utility regulations that could fragment national platform strategies.
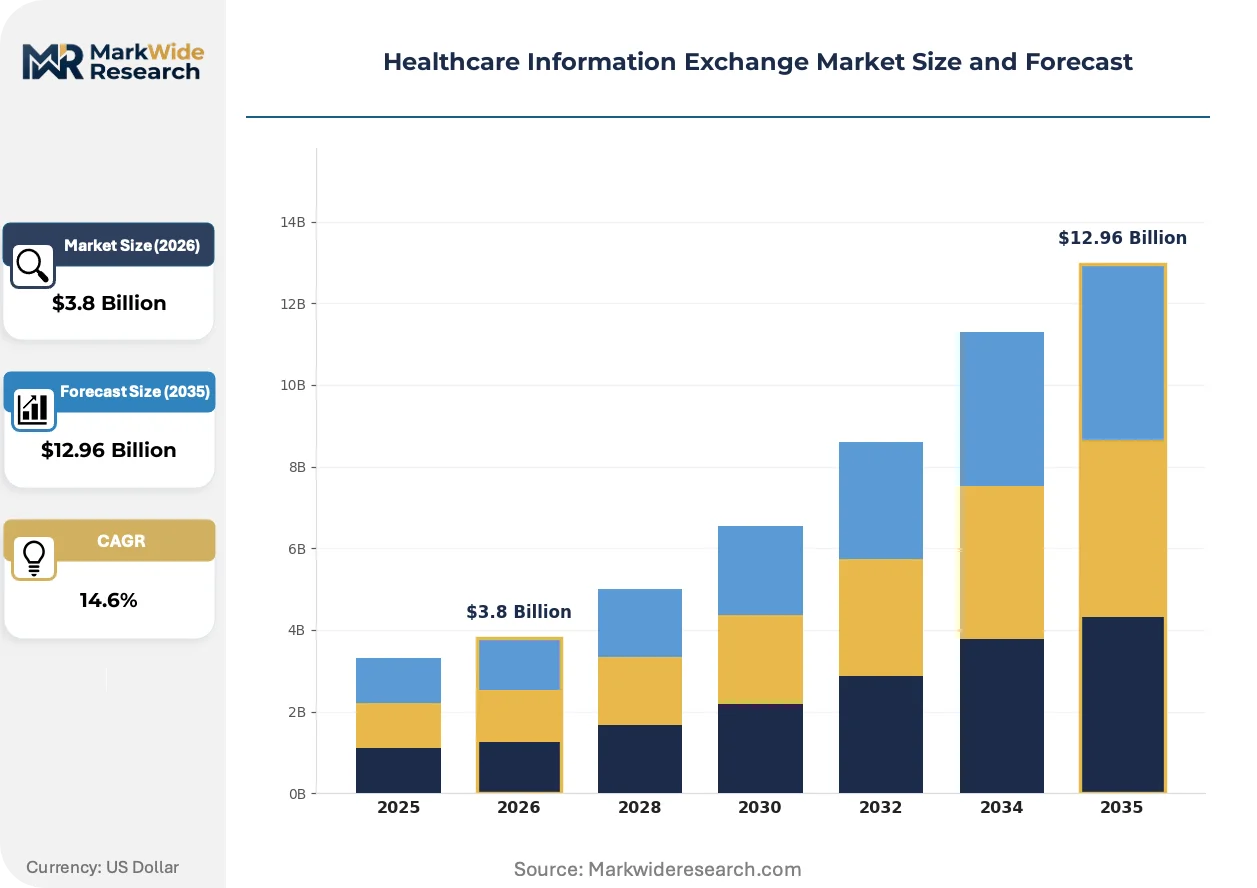
Market Dynamics
Cloud-native API architectures are compressing replacement cycles for on-premise health data infrastructure, forcing incumbent vendors to re-platform or cede mid-market share to specialized interoperability providers.
Growth Catalysts
- 21st Century Cures Act enforcement:The US Office of the National Coordinator for Health IT imposes civil monetary penalties for information blocking, compelling vendors to open patient-directed data access APIs.
- Hospital network consolidation:Integrated delivery systems spanning multiple states require unified clinical data lakes, driving procurement of scalable health information networks.
- HL7 FHIR standardization:Widespread adoption of Fast Healthcare Interoperability Resources protocols enables real-time clinical data exchange between previously incompatible EHR systems.
Market Restraints
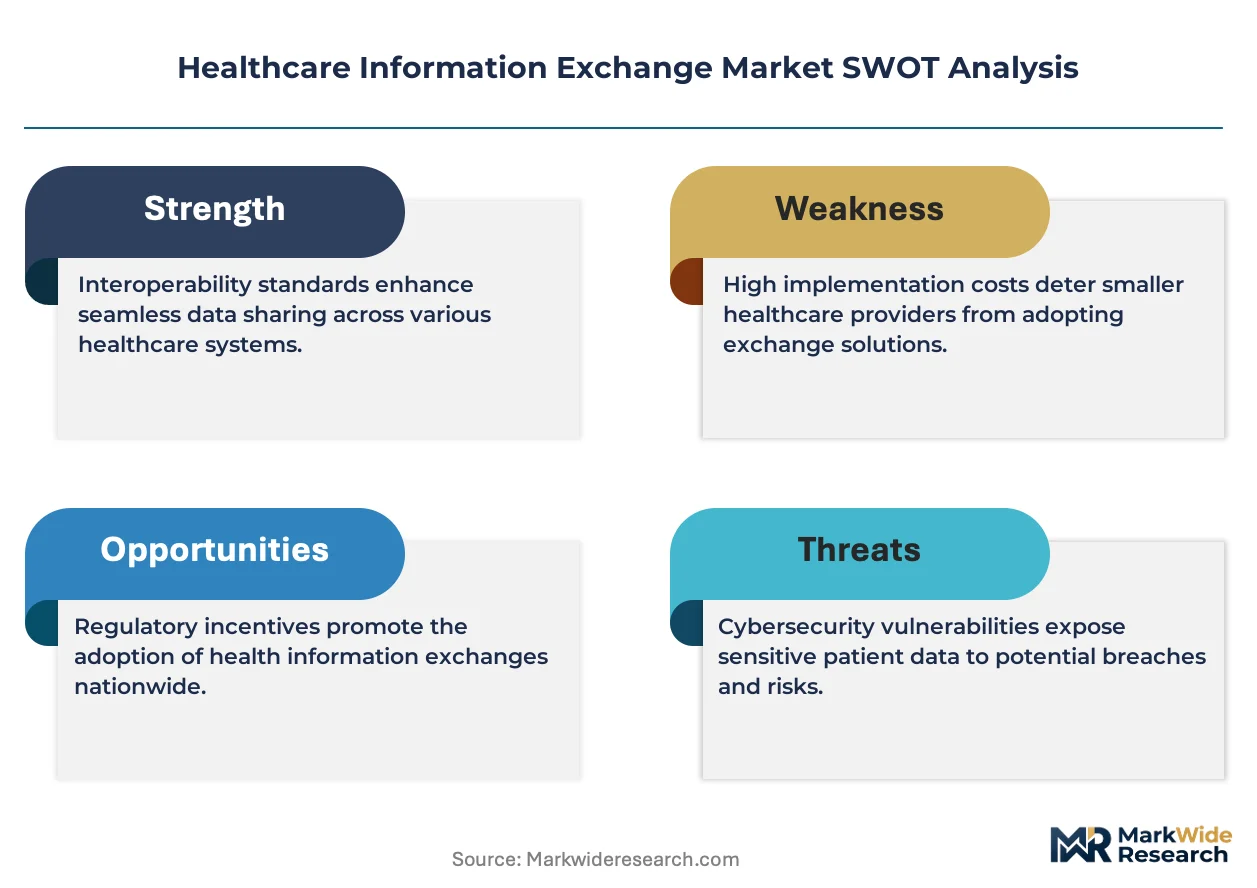
- Legacy system technical debt:Decades-old on-premise EHR installations lack modern API layers, requiring expensive middleware or full replacement to achieve interoperability.
- HIPAA compliance complexity:Encryption, audit logging, and business associate agreement requirements across every network transaction inflate implementation timelines and legal review costs.
- Cloud concentration risk:Dominant hyperscale providers (AWS, Azure, Google Cloud) control critical infrastructure for health information networks, creating single-point-of-failure vulnerabilities.
Strategic Opportunities
- Medicaid claims verification pilots:US state agencies are funding blockchain-based immutable audit trails to reduce fraud in multi-payer eligibility verification.
- Medicare Advantage data mandates:CMS interoperability requirements for MA plans create compliance-driven demand for payer-agnostic clinical data aggregation platforms.
- Population health analytics convergence:Integration of social determinants of health data with clinical records enables risk stratification tools for accountable care organizations.
Industry Challenges
- FHIR implementation skill scarcity:Health IT workforces lack depth in modern API architecture, forcing vendors to compete for limited integration engineer talent.
- Multi-state regulatory fragmentation:Emerging state-level health data utility regulations in California, New York, and Texas complicate national platform deployment strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Information Exchange Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Public Health, Clinical Data Exchange, Laboratory Information Management System, Health Information Network End User: Hospitals, Clinics, Laboratories, Government Agencies Technology: Interoperability Standards, API Integration, Cloud-based Solutions, Blockchain Application: Patient Data Management, Referral Management, Population Health, Revenue Cycle Management |
| Companies Covered | Epic Systems Corporation, Oracle Corporation, InterSystems Corporation, Cerner Corporation, Allscripts Healthcare Solutions, Optum, Veradigm LLC, NextGen Healthcare, Orion Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Information Exchange Market Strategic Shifts
Real-time clinical data streaming is displacing batch-oriented exchange models, compressing care coordination latency from days to seconds and enabling point-of-care decision support.
Fast Healthcare Interoperability Resources Release 4 is rewriting how clinical documents traverse organizational boundaries. Large academic medical centers in the US and university hospitals in Germany are deploying FHIR-native apps for medication reconciliation and care transition alerts. This standard is compressing integration timelines from 18-month custom interfaces to weeks of configuration.
The EU AI Act's risk classification framework for health software is reshaping vendor product roadmaps. High-risk clinical decision support tools must meet conformity assessment requirements before CE marking, extending time-to-market for algorithmic diagnostics. European health networks are prioritizing explainable AI architectures to satisfy documentation mandates.
Subscription-based interoperability platforms are displacing perpetual license models for health information exchange. US-based integrated delivery networks and Canadian provincial health authorities now prefer per-member-per-month pricing that aligns vendor incentives with network uptime and data quality metrics. This shift concentrates procurement power with finance departments rather than traditional IT gatekeepers.
Healthcare Information Exchange Market Segmentation
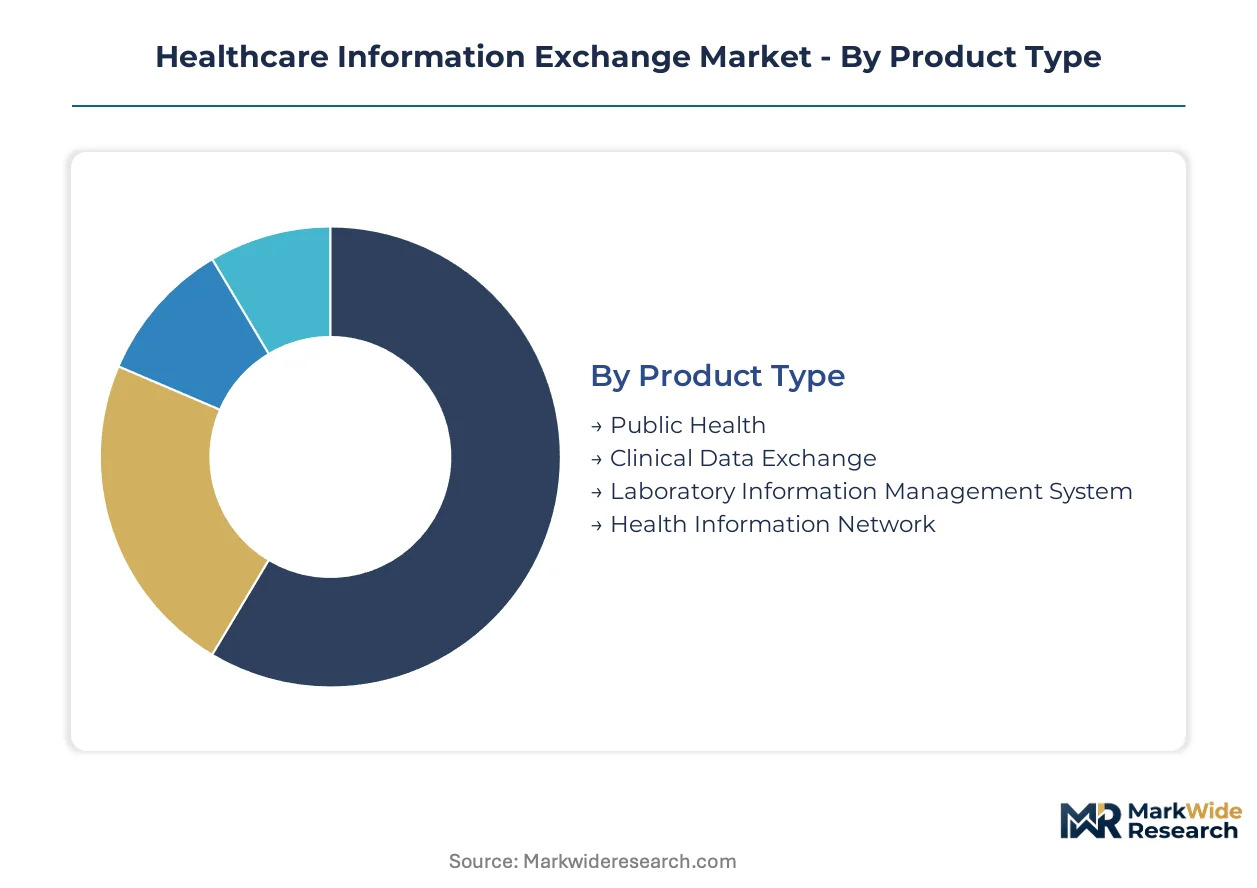
Healthcare information exchange platforms segment across functional layers that determine integration complexity and procurement priorities. Product architecture choices dictate whether deployments emphasize real-time clinical workflows or administrative batch processing. Technology selection increasingly separates cloud-native adopters from organizations maintaining legacy infrastructure investments.
Product Type:
Volume deployment clusters around administrative data movement, while premium margins concentrate in clinical interoperability requiring real-time validation.
- Clinical Data Exchange:Real-time transmission of structured patient records between EHR systems using HL7 FHIR protocols. Academic medical centers in the US and university hospitals in Germany prioritize these deployments for medication reconciliation and care transition alerts.
- Health Information Network:Multi-organization data sharing infrastructure connecting unaffiliated providers across geographic regions. State-level health data utilities in California and New York are consolidating procurement around these platforms to achieve statewide interoperability mandates.
- Public Health:Aggregated reporting systems for disease surveillance and immunization registries. National health agencies deploy these for population-level epidemiological monitoring.
- Laboratory Information Management System:Specimen tracking and result distribution platforms connecting diagnostic facilities with ordering providers. Regional laboratory networks utilize these for standardized test result formatting.
Mature deployment sits with Laboratory Information Management Systems. Newer deployment is concentrated in Health Information Networks.
End User:
Procurement authority varies by organizational scale, with integrated delivery systems driving enterprise platform decisions while independent practices prioritize modular interoperability tools.
- Hospitals:Large-scale EHR integration projects spanning inpatient, outpatient, and emergency departments. US-based integrated delivery networks and German university hospital systems anchor demand for comprehensive interoperability suites with 99.9% uptime requirements.
- Government Agencies:State and federal health departments managing Medicaid claims verification and public health reporting infrastructure. CMS interoperability mandates for Medicare Advantage plans are accelerating procurement timelines for these entities.
- Clinics:Ambulatory-focused interoperability tools prioritizing referral management and care coordination with hospital affiliates. Federally qualified health centers represent a concentrated demand segment.
- Laboratories:Diagnostic facilities requiring bidirectional interfaces with ordering systems and public health registries. Regional reference laboratories drive standardization around LOINC and SNOMED CT terminologies.
Procurement maturity clusters with Hospitals. Fastest technology refresh cycles appear among Government Agencies responding to regulatory compliance deadlines.
Technology:
Architecture choices separate organizations with API-native infrastructure from those bridging decades of technical debt through middleware layers.
- Cloud-based Solutions:Scalable API architectures hosted on hyperscale infrastructure enabling rapid network expansion. Canadian provincial health authorities and US multi-state integrated delivery networks are migrating from on-premise deployments to these platforms for per-member-per-month pricing alignment.
- API Integration:Direct system-to-system connectivity using RESTful interfaces and OAuth 2.0 security frameworks. Epic Systems and Cerner Corporation are competing to expose these capabilities for third-party application ecosystems.
- Interoperability Standards:Protocol implementations including HL7 FHIR, Direct Secure Messaging, and CDA document exchange. The 21st Century Cures Act enforcement by the US Office of the National Coordinator for Health IT mandates these capabilities.
- Blockchain:Distributed ledger architectures for immutable audit trails in multi-payer eligibility verification. US state Medicaid agencies are funding pilot deployments for fraud reduction in claims processing.
Established production workloads run on Interoperability Standards. Steepest expansion trajectory belongs to Cloud-based Solutions.
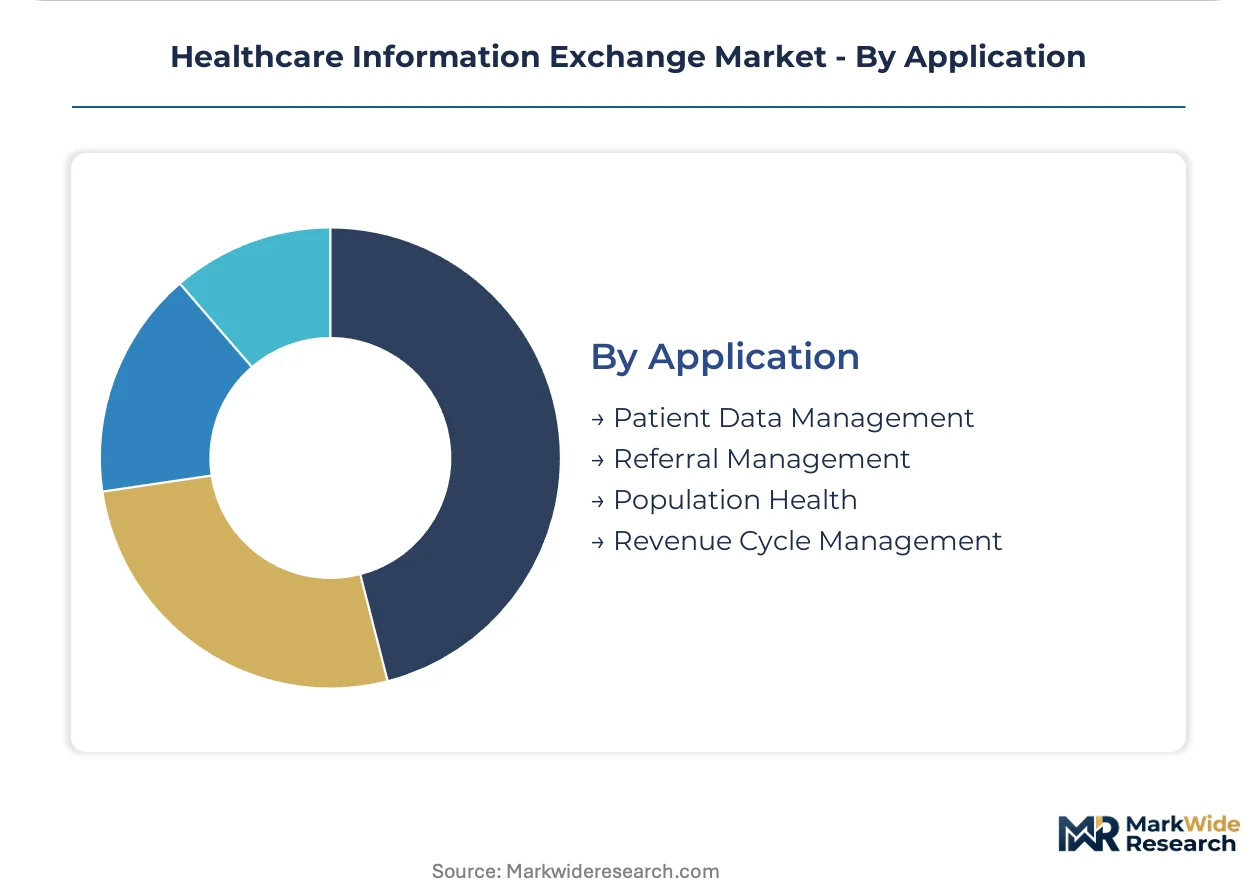
Application:
Functional priorities segment by organizational reimbursement model, with fee-for-service environments emphasizing revenue capture and value-based care organizations investing in risk stratification capabilities.
- Patient Data Management:Consolidated longitudinal records spanning multiple care settings and payer relationships. Accountable care organizations in the US are deploying these capabilities for care gap closure and HEDIS measure reporting.
- Population Health:Integration of clinical records with social determinants of health data for risk stratification. German sickness funds and US Medicare Advantage plans are prioritizing these analytics platforms.
- Referral Management:Automated routing of specialty care requests with clinical documentation attachment. Multi-specialty group practices utilize these tools to reduce referral leakage.
- Revenue Cycle Management:Claims submission, eligibility verification, and prior authorization workflows. Hospital systems maintaining fee-for-service revenue models concentrate investment here.
Operational maturity centers on Revenue Cycle Management. Emerging deployment concentrates in Population Health as value-based reimbursement contracts expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health technology special economic zones in Research Triangle Park, North Carolina, and Kendall Square, Massachusetts, concentrate vendor R&D operations and federal interoperability pilot funding.
United States
The 21st Century Cures Act enforcement by the Office of the National Coordinator for Health IT drives hospital network procurement of open API platforms. CMS interoperability mandates for Medicare Advantage plans accelerate compliance timelines across multi-state integrated delivery systems. Epic Systems Corporation anchors its installed base across large academic medical centers in the Upper Midwest and Pacific Northwest.
Germany
University hospital systems prioritize FHIR-native medication reconciliation tools for cross-facility care coordination. The EU AI Act's risk classification framework extends conformity assessment timelines for algorithmic clinical decision support. Berlin-Brandenburg health data utilities consolidate regional procurement around interoperable laboratory networks.
Canada
Provincial health authorities migrate from on-premise infrastructure to cloud-native architectures with per-member-per-month pricing models. Health Canada interoperability standards align with federal privacy frameworks for cross-jurisdictional patient data sharing. Ontario and British Columbia anchor national deployment of scalable health information networks.
United Kingdom
NHS England mandates open API standards for electronic patient record systems across integrated care systems. The UK regulator enforces data portability requirements that compress vendor replacement cycles. London and Greater Manchester health innovation clusters attract interoperability pilot funding for real-time clinical data streaming.
Australia
My Health Record expansion drives demand for secure messaging infrastructure connecting primary care and hospital networks. The Therapeutic Goods Administration aligns software as a medical device regulations with international interoperability standards. Sydney and Melbourne health technology precincts concentrate vendor regional headquarters and implementation partnerships.
Healthcare Information Exchange Market Competitive Environment
Top-tier vendors anchor enterprise hospital contracts, while mid-market specialists compete for ambulatory and regional network share. The vendor base stratifies across three tiers: dominant EHR-integrated platforms, cloud-native interoperability specialists, and niche workflow tool providers. Strategic archetypes include installed-base defenders leveraging switching costs, API-first challengers compressing integration timelines, and payer-agnostic aggregators targeting Medicare Advantage compliance. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and portfolio diversification into population health analytics.
Within the EHR-integrated tier, Epic Systems Corporation and Cerner Corporation exemplify installed-base defenders with deep federal health system penetration. Oracle Corporation occupies a position as a scale-driven platform consolidator following its Cerner acquisition. Cloud-native specialists include InterSystems Corporation and Orion Health, representing API-first architectures that compress deployment timelines for mid-market health networks.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Corporation |
| InterSystems Corporation |
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| Optum |
| Veradigm LLC |
| NextGen Healthcare |
| Orion Health |
| Others |
Value Chain & Pricing Dynamics
Cloud-to-on-premise deployment bifurcation splits procurement economics between subscription-native platforms and legacy infrastructure maintenance contracts, concentrating vendor pricing power with hyperscale providers while fragmenting buyer leverage across technical debt-laden health systems. This divergence feeds back into supply configurations, as API-first specialists bypass traditional channel intermediaries while incumbent EHR vendors defend embedded bases through multi-year lock-in structures.
Pricing Analysis
Short lead-time premiums attach to cloud-native deployments with immediate FHIR API availability, while extended implementation cycles for on-premise middleware attract discounted spot contracting. Per-member-per-month SaaS pricing dominates Canadian provincial authorities and US integrated delivery networks, with differentiation driven by uptime SLA tiers and FHIR R4 certification depth. Cost compression in legacy EHR integration services is intensifying because cloud-native alternatives compress deployment timelines from months to weeks. Federally qualified health centers exhibit highest price sensitivity due to constrained capital budgets, while large academic medical centers prioritize workflow continuity over unit cost.
Supply Chain Analysis
Direct-to-health-system channels handle enterprise procurement for Epic Systems and Oracle Cerner, while cloud-native specialists like InterSystems and Orion Health distribute through regional implementation partners and GPO contracts. Engineering talent concentrates in the United States, Germany, and Canada, with integration specialist scarcity in India and Eastern Europe. Platform development draws from open-source FHIR libraries, OAuth 2.0 security frameworks, and hyperscale infrastructure APIs. Single-source vulnerability attaches to AWS, Azure, and Google Cloud dominance over critical health data infrastructure. Distribution runs through health system GPOs, state procurement cooperatives, and direct federal contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare information exchange sits in a technology-transition phase as HL7 FHIR R4 APIs displace decades-old HL7 v2 message protocols and proprietary document exchange formats. Cloud-native architectures are compressing replacement cycles and redistributing procurement authority from IT departments to finance functions.
For Market Incumbents: Anchor defensive positioning through deep workflow integration in large academic medical centers, where switching costs and clinician training investments create retention moats. Accelerate FHIR API exposure to neutralize cloud-native challengers attacking mid-market share. Prioritize backward integration into population health analytics to capture value-based care revenue streams escaping pure interoperability plays.
For New Entrants and Emerging Players: FHIR-native workflow tools offer the clearest technology-first wedge for penetrating ambulatory clinics and federally qualified health centers underserved by enterprise EHR suites. Target Medicaid claims verification pilots in US state agencies, where blockchain audit trail demand outstrips incumbent capability. Lead with per-member-per-month pricing alignment to bypass capital-constrained procurement committees.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscale cloud providers seeking healthcare vertical penetration and by EHR incumbents filling API capability gaps. Long-term viability favors platforms with demonstrated Medicare Advantage compliance traction and multi-state health data utility contracts. Watch CMS information blocking enforcement penalties as inflection indicator for vendor consolidation urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR R4 API Certification | ONC compliance mandates under 21st Century Cures Act enforcement timelines compress vendor roadmaps. |
| Cloud Migration Partnership | Hyperscale provider alliances unlock per-member-per-month pricing for Canadian provincial authorities. |
| Population Health Analytics Integration | Social determinants data convergence enables risk stratification tools for Medicare Advantage plans. |
| State Health Data Utility Contract | California and New York procurement consolidations anchor multi-year recurring revenue streams. |
| Blockchain Audit Trail Pilot | Medicaid fraud reduction funding from US state agencies creates early-adopter reference accounts. |
Study Parameters
Multi-period observation of vendor contract announcements, health system procurement databases, and CMS enforcement actions anchored the trend analysis, supplemented by interviews with health IT procurement officers, FHIR integration engineers, hospital CIOs, GPO contracts managers, and state Medicaid technology directors. Secondary validation drew from ONC regulatory filings, CMS Medicare Advantage plan data, hospital capital expenditure disclosures, and HL7 International standardization records. Bottom-up deployment tracking across 15 countries triangulated against top-down market sizing from interoperability platform revenue disclosures.
Segment-weighting applied differential growth assumptions across cloud-based versus on-premise architectures, clinical versus administrative data exchange functions, and enterprise versus mid-market buyer tiers throughout the forecast period. Modeled dimensions included product type, end user category, deployment technology, and application workflow. CAGRs derived from logistic adoption curves fitted to FHIR standardization penetration rates and health system consolidation velocity. Forecast inputs incorporated HIPAA compliance cost trajectories and 21st Century Cures Act enforcement intensity projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under multi-state regulatory fragmentation scenarios and hyperscale cloud service disruption events. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Healthcare Informatics Market
Health Informatics
North America Laboratory Information System Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Global Health IT Security Market
Health Informatics
Global Healthcare Integration Market
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
Healthcare Natural Language Processing Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Clinical Intelligence Market