
 USA Electronic Health Records (EHR) Market | 2026-2036
USA Electronic Health Records (EHR) Market Size, Share, and Industry Trends Forecast 2026-2036
USA Electronic Health Records (EHR) Market Analytics
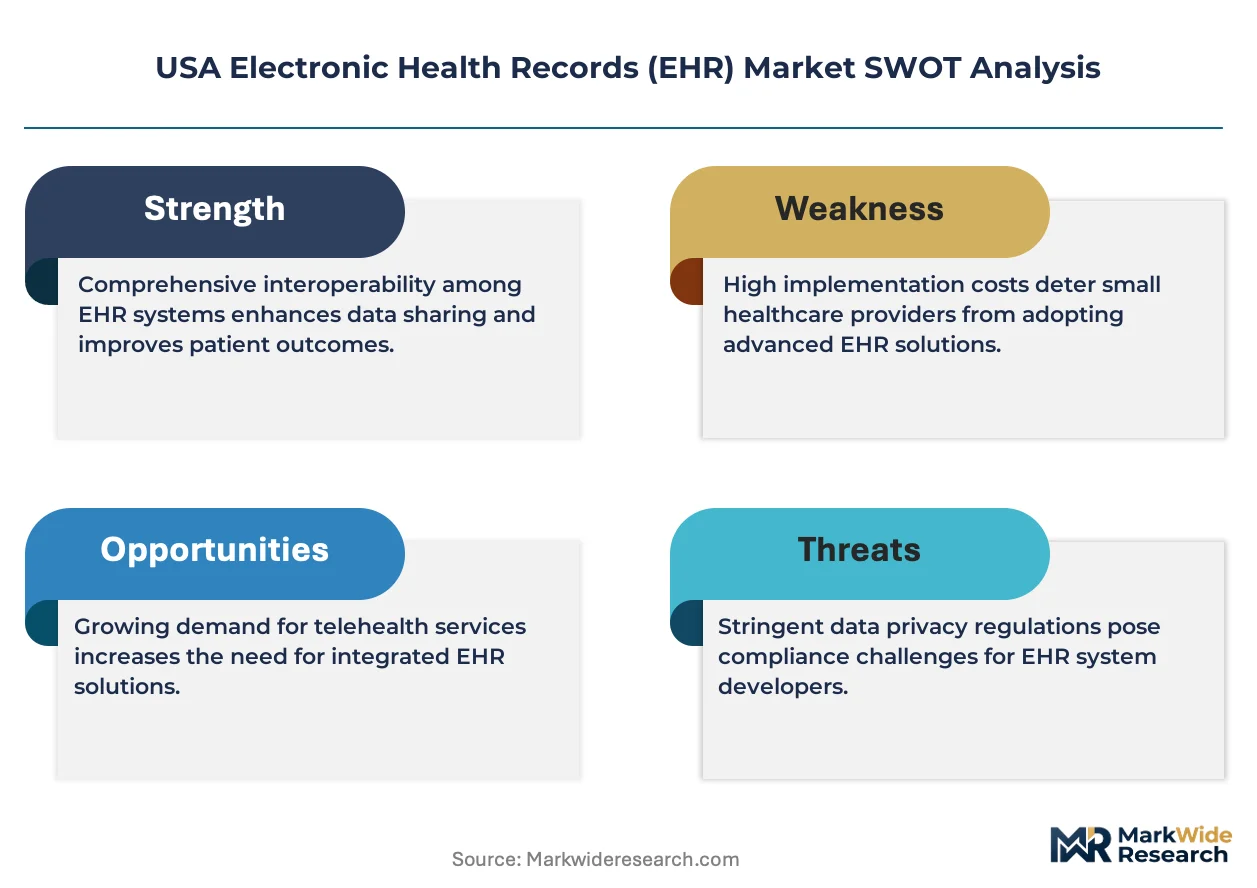
Interoperability-grade certification is reorganizing competitive dynamics across the USA EHR landscape. Epic Systems Corporation leverages deep integration with academic medical centers to sustain its position in high-complexity care environments. Oracle Health anchors enterprise-scale deployments through aggressive cloud infrastructure investments. MEDITECH competes effectively in community hospital segments where cost containment dominates procurement decisions.
Electronic Health Records constitute digital systems for capturing, storing, and exchanging patient medical information across care settings, typically structured around HL7 FHIR protocols for data exchange and CCDA formats for clinical document architecture. Cloud-based deployment models are capturing accelerating share as health systems abandon capital-intensive server infrastructure for subscription-based SaaS architectures. Among end users, hospitals generate the dominant revenue pool, while outpatient centers represent the fastest-expanding segment as ambulatory networks consolidate and seek unified patient record visibility.
FDA oversight of EHR-integrated clinical decision support tools, combined with CMS Promoting Interoperability Program requirements and HIPAA security rule enforcement, compels vendors to maintain continuous compliance investment or risk exclusion from federal reimbursement pathways. ONC certification timelines are tightening, pressuring smaller vendors to absorb compliance costs or exit the market. Stakeholders must weigh the trade-off between proprietary ecosystem depth and open-architecture interoperability as value-based care contracts demand seamless data fluidity across competing platforms.
Market Dynamics
CMS interoperability mandates are forcing rural health clinics and independent physician practices to upgrade from legacy paper systems or basic digital records to certified, network-connected platforms that exchange data across competing vendor ecosystems.
Growth Catalysts
- ONC Certification Timelines:Federal reimbursement pathways now require 21st Century Cures Act-compliant data exchange capabilities, compelling ambulatory networks to consolidate around interoperable platforms.
- Cloud Infrastructure Migration:Hospital systems in Texas and the Southeast are abandoning capital-intensive server farms for subscription-based SaaS architectures that scale with patient volume fluctuations.
- Value-Based Care Contracts:Medicare accountable care organizations demand seamless patient record visibility across competing platforms, creating network effects that favor connected systems.
Market Restraints
- Compliance Cost Burden:HIPAA security rule enforcement and FDA oversight of clinical decision support tools require continuous vendor investment that smaller developers cannot sustain.
- Technical Debt in Legacy Installations:Decades-old on-premise deployments at community hospitals resist cloud migration without expensive data architecture reengineering.
- Interoperability Implementation Complexity:HL7 FHIR protocol adoption across heterogeneous vendor environments demands specialized integration expertise that remains scarce in secondary markets.
Strategic Opportunities
- Rural Health Clinic Penetration:Federally qualified health centers in the Mississippi Delta and Appalachian regions remain underdigitized, presenting greenfield deployment opportunities for scalable cloud platforms.
- Behavioral Health Integration:Medicaid expansion states are mandating parity between physical and mental health records, creating demand for specialized EHR modules that bridge care silos.
- Telehealth Data Capture:Remote patient monitoring devices generate unstructured data streams that specialized analytics layers can normalize into reimbursable clinical documentation.
Industry Challenges
- Specialized Workforce Scarcity:Health informaticists with dual competency in clinical workflows and FHIR API architecture command premium compensation that strains hospital IT budgets.
- Legacy System Integration Friction:Decades of customized on-premise configurations resist standardized data migration without expensive professional services engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Electronic Health Records (EHR) Market |
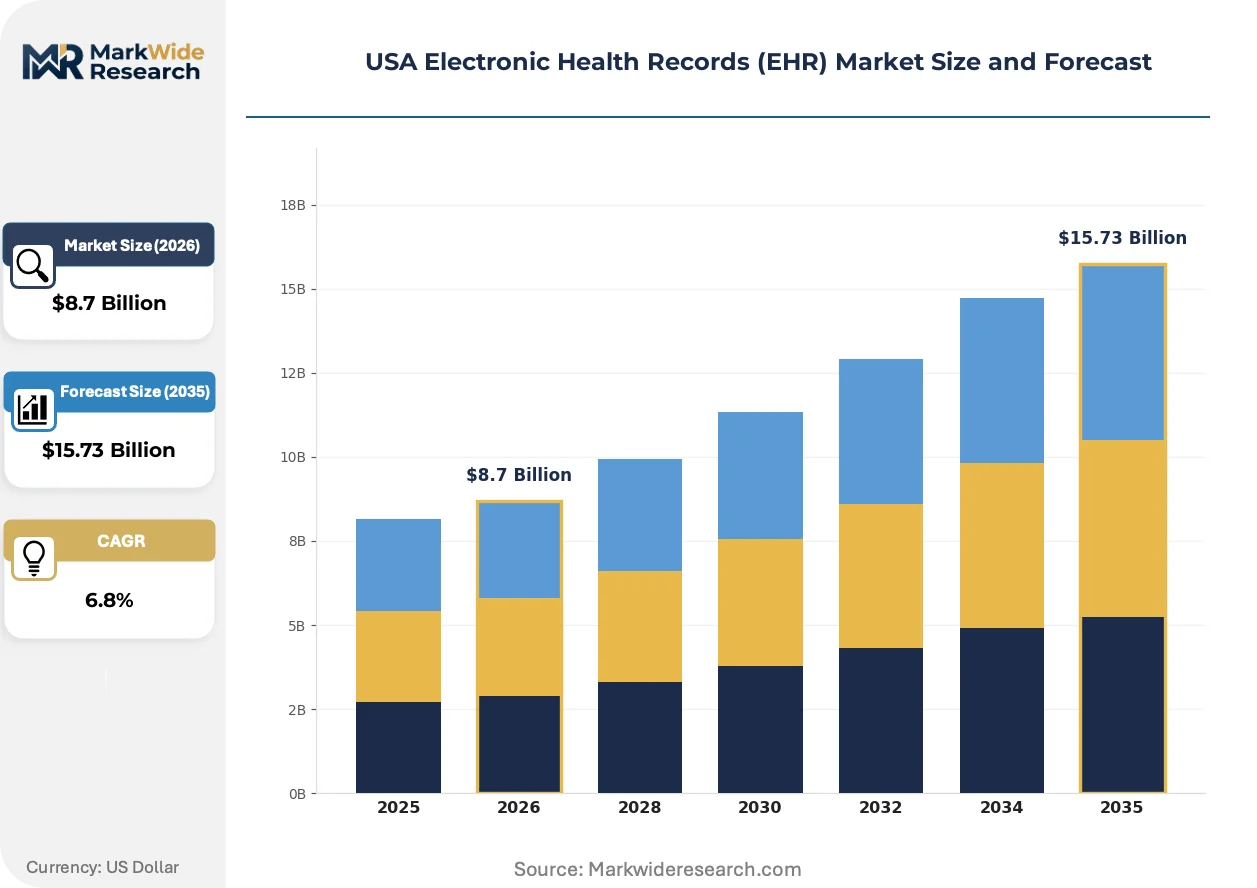
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Open Source End User: Hospitals, Clinics, Long-Term Care Facilities, Outpatient Centers Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Server-Based Integration Level: Interoperable, Standalone, Custom, Vendor-Specific |
| Companies Covered | Epic Systems Corporation, Oracle Health, MEDITECH, eClinicalWorks, athenahealth, NextGen Healthcare, Veradigm, TruBridge, Greenway Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Electronic Health Records (EHR) Market Evolving Landscape
Artificial intelligence is embedding into clinical workflows at the point of care, reshaping how physicians interact with patient data and how documentation gets generated, coded, and reimbursed.
Generative AI documentation tools are displacing manual physician note-taking in emergency departments and high-volume specialty clinics. Hospital systems in Florida and Arizona are piloting ambient listening technologies that transcribe patient encounters into structured EHR entries. This automation is compressing documentation time per encounter while raising concerns about liability attribution when algorithms generate clinical content.
FDA draft guidance on machine learning-enabled clinical decision support is tightening oversight of predictive algorithms integrated into EHR interfaces. The agency's risk-based framework categorizes certain diagnostic recommendations as medical devices requiring premarket review. Academic medical centers with embedded regulatory affairs teams are adapting submission pathways faster than community hospital systems.
Subscription pricing for EHR modules is replacing perpetual licensing arrangements in hospital procurement negotiations. Health systems in the Upper Midwest are bundling EHR costs into per-member-per-month capitation contracts with payers. This shift transfers technology risk from capital budgets to operational expenses and aligns vendor incentives with patient outcome metrics rather than seat licenses.
USA Electronic Health Records (EHR) Market Segmentation
EHR procurement patterns diverge sharply across care settings and technical architectures. Vendors align product roadmaps with distinct compliance burdens, infrastructure maturity, and reimbursement exposure that vary by segment.
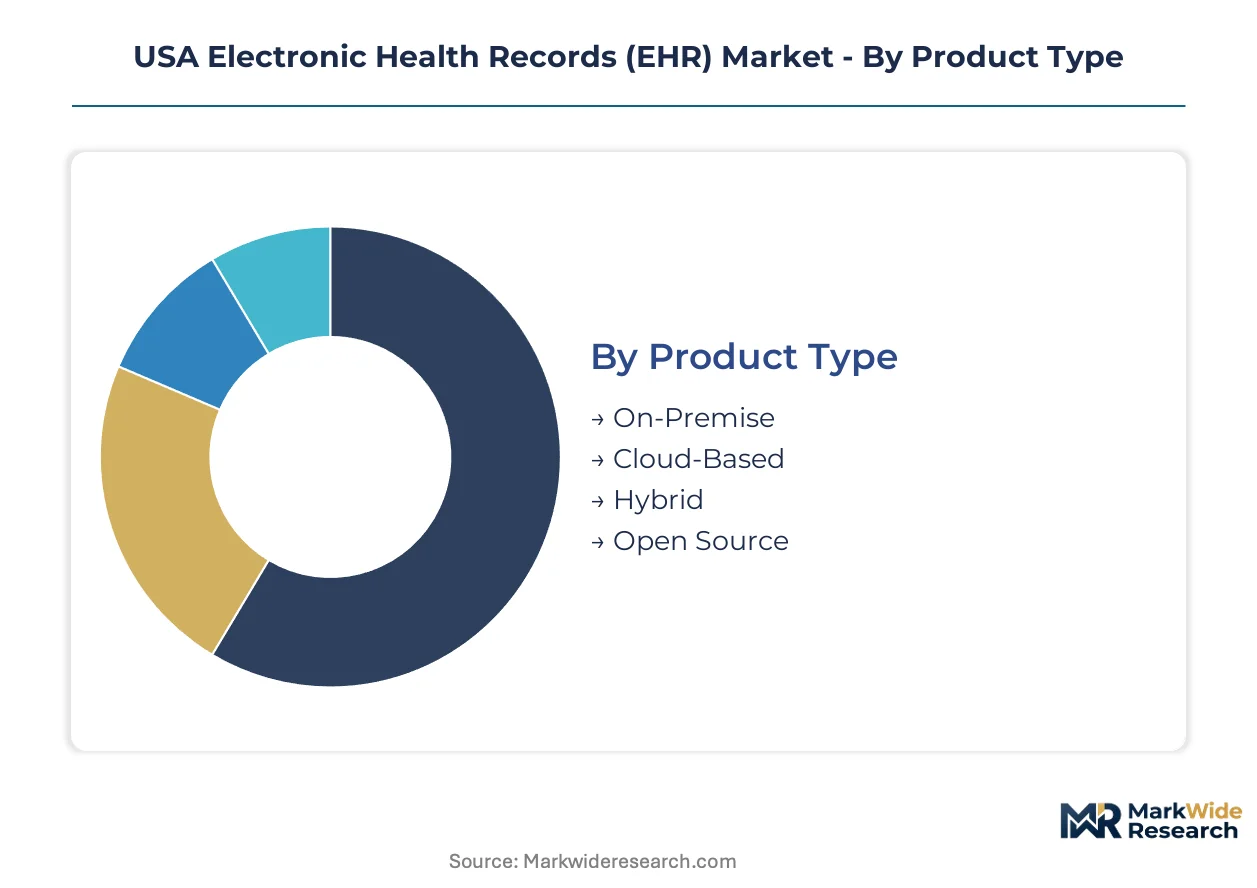
Product Type:
Cloud-based systems flow through health system IT departments and group purchasing organizations, while on-premise deployments concentrate in hospitals with captive data centers.
- Cloud-Based:Multi-tenant SaaS architectures with HL7 FHIR-native data exchange. Texas health systems and Southeast hospital networks are consolidating procurement around these platforms to escape server maintenance overhead.
- On-Premise:Client-server installations with localized data sovereignty. Academic medical centers with embedded research infrastructure and legacy integration layers sustain demand here despite higher capital intensity.
- Hybrid:Split architectures keeping sensitive data on-site while pushing analytics workloads to cloud environments. Appeals to mid-tier health systems navigating HIPAA security rule complexity.
- Open Source:Community-developed platforms with customizable codebases. Federally qualified health centers in budget-constrained regions pilot these for cost containment.
On-Premise dominates installed base. Cloud-Based is where expansion concentrates.
End User:
Cost tier stratification shapes vendor pricing: hospitals absorb enterprise licensing, while outpatient centers drive per-provider subscription models.
- Hospitals:Integrated delivery networks requiring enterprise-wide patient record visibility across emergency, inpatient, and surgical departments. CMS Promoting Interoperability Program compliance mandates anchor procurement decisions.
- Outpatient Centers:Ambulatory clinics and specialty practices with lighter workflow complexity. Consolidation of physician groups into larger networks is accelerating unified platform adoption here.
- Clinics:Small-to-mid-size primary care and urgent care operations. Rural health clinics in the Mississippi Delta and Appalachian regions represent underpenetrated addressable market.
- Long-Term Care Facilities:Skilled nursing and post-acute care settings with distinct regulatory reporting requirements. Medicaid billing complexity drives demand for specialized modules.
Hospitals anchor revenue concentration. Outpatient Centers are climbing the fastest.
Deployment Model:
Volume concentration follows cloud infrastructure geography, with Texas and Virginia data center clusters capturing health system migrations.
- Public Cloud:Shared infrastructure with elastic compute scaling. Cost-sensitive community hospital systems prioritize this model to convert capital expenditure to operational budgets.
- Private Cloud:Dedicated tenant environments with enhanced security controls. Large integrated delivery networks with risk-averse compliance postures sustain premium pricing here.
- Hybrid Cloud:Orchestrated workloads across on-premise and cloud resources. Organizations with technical debt in legacy applications use this as transitional architecture.
- Server-Based:Traditional rack-mounted infrastructure with direct hardware ownership. Declining segment concentrated in isolated rural facilities with unreliable broadband connectivity.
Public Cloud captures majority of new deployments. Private Cloud retains margin premium.
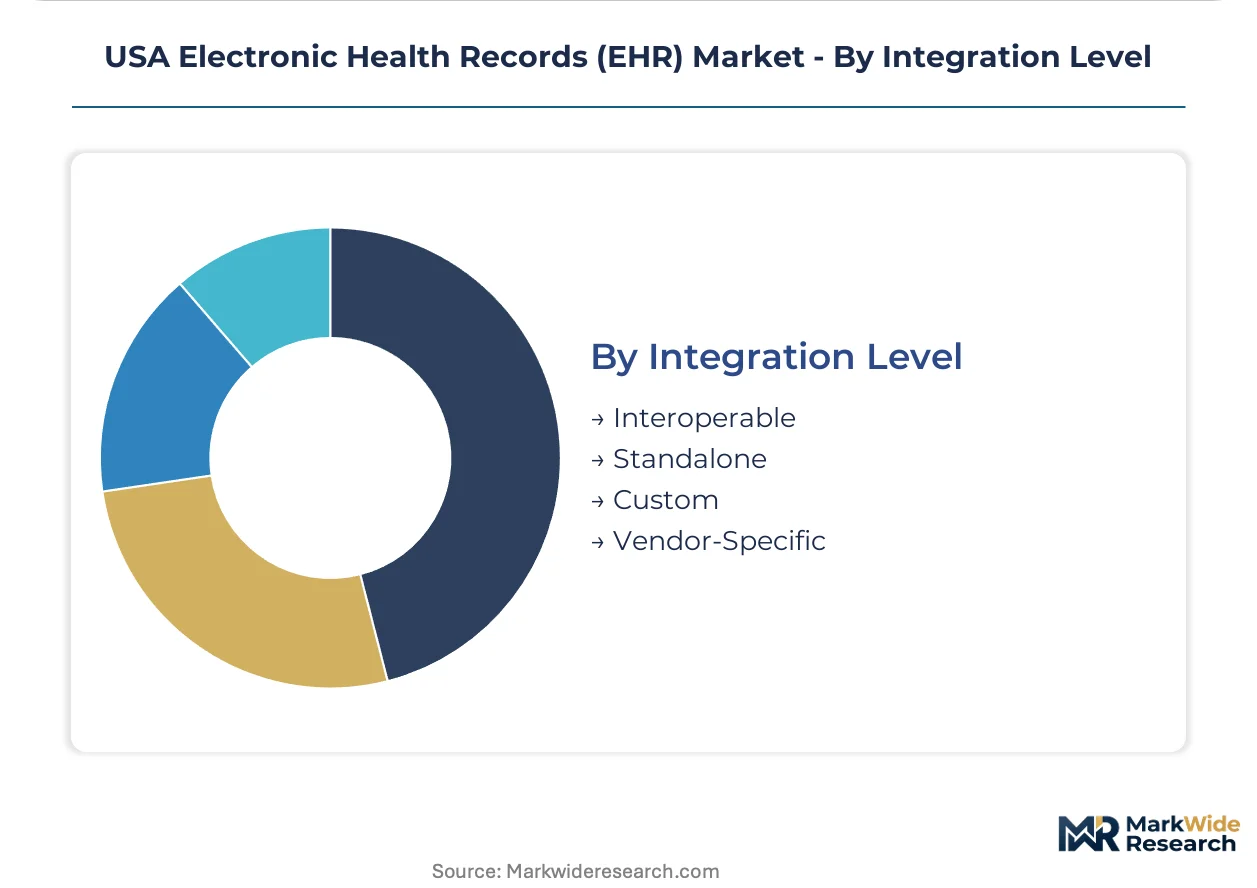
Integration Level:
Customer type determines integration depth: accountable care organizations mandate interoperability, while standalone practices tolerate siloed systems.
- Interoperable:ONC-certified platforms with 21st Century Cures Act-compliant APIs. Medicare accountable care organizations and value-based care contracts require this capability for network participation.
- Standalone:Closed systems without external data exchange. Independent physician practices and small clinics with limited referral networks accept this trade-off for simplicity.
- Custom:Bespoke integration layers built for specific health system workflows. Academic medical centers with unique research and clinical trial requirements commission these configurations.
- Vendor-Specific:Proprietary data formats locked to single vendor ecosystems. Organizations with deep Epic or Oracle Health deployments face high switching costs maintaining this posture.
Interoperable systems command procurement priority. Vendor-Specific retains legacy lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across US sub-regions. Texas health systems absorb premium cloud infrastructure costs, while Mississippi Delta clinics prioritize cost-containment above interoperability depth.
Texas
Hospital systems in Dallas-Fort Worth and Houston anchor the nation's largest cloud EHR migration wave. CMS Promoting Interoperability Program compliance deadlines accelerate procurement cycles. The Texas Medical Center in Houston concentrates enterprise-scale deployments from Oracle Health and Epic Systems Corporation.
Southeast
Florida and Georgia ambulatory networks consolidate rapidly around unified patient record platforms. HIPAA security rule enforcement tightens data sovereignty requirements. Atlanta's healthcare IT corridor attracts SaaS vendors targeting mid-tier health systems.
California
Academic medical centers in Los Angeles and San Francisco sustain demand for research-integrated EHR configurations. FDA oversight of clinical decision support tools shapes vendor selection criteria. The Bay Area's digital health cluster incubates AI documentation startups.
Upper Midwest
Minnesota and Wisconsin integrated delivery networks pioneer subscription pricing bundled into capitation contracts. ONC certification timelines pressure rural critical access hospitals. The Mayo Clinic in Rochester anchors specialized workflow customization demand.
Appalachia
Federally qualified health centers in Kentucky and West Virginia represent underdigitized greenfield opportunity. Technical debt in legacy paper systems resists rapid cloud migration. Pittsburgh's health informatics programs supply scarce FHIR integration talent to regional clinics.
USA Electronic Health Records (EHR) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US EHR landscape. The vendor base stratifies into three tiers: enterprise-scale platforms serving academic medical centers, mid-market solutions targeting community hospitals, and lightweight cloud systems for ambulatory practices. Dominant competitive moves include aggressive cloud infrastructure investments and strategic partnerships with group purchasing organizations.
Within the enterprise tier, Epic Systems Corporation and Oracle Health occupy positions defined by deep integration capabilities and federal compliance depth. MEDITECH exemplifies the community hospital archetype where procurement decisions center on total cost of ownership rather than feature breadth.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| MEDITECH |
| eClinicalWorks |
| athenahealth |
| NextGen Healthcare |
| Veradigm |
| TruBridge |
| Greenway Health |
| Others |
Value Network & Pricing Analysis
Subscription-based SaaS architectures replacing perpetual licensing arrangements are simultaneously redrawing vendor revenue geography and compressing customer total cost of ownership curves across the USA EHR landscape.
Pricing Analysis
Professional services and extended implementation contracts generate lifetime value multiples exceeding initial license fees. Three-tier pricing structure across enterprise, mid-market, and ambulatory levels reflects ONC certification depth and integration complexity. Cost compression in community hospital tiers intensifies because CMS reimbursement penalties for non-compliance force rapid procurement without competitive bidding cycles. Federally qualified health centers exhibit highest price sensitivity; academic medical centers with captive IT budgets absorb premium customization costs.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native implementations, though legacy data migration projects require strategic stockpiling of integration specialists. Software development concentrates in USA, India, and Ireland; cloud infrastructure draws from hyperscaler data center clusters in Virginia, Texas, and California. Specialized health informaticists, HL7 FHIR integration engineers, and clinical workflow architects constitute critical input dependencies. Single-source vulnerability in certified API developer talent pools threatens implementation timelines. Distribution runs through group purchasing organizations and health system IT departments with consolidated procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USA EHR market dynamics constitute a defensive-moat story anchored in regulatory entrenchment; ONC certification timelines and CMS interoperability mandates create structural barriers that favor incumbent platforms with compliance infrastructure already deployed.
For Market Incumbents: Secure ONC certification renewals ahead of tightened federal timelines to lock out undercapitalized competitors. Deepen backward integration into cloud infrastructure through captive data center investments or exclusive hyperscaler partnerships, insulating margin structures from compute cost volatility. Emerging AI-native documentation startups threaten ambulatory market share; vertical integration into ambient listening hardware preserves platform control. For New Entrants and Emerging Players: Differentiate on behavioral health module specialization as Medicaid expansion states mandate mental-physical record parity. Rural health clinics in Appalachian and Mississippi Delta regions represent the most penetrable geography, with greenfield cloud deployments replacing paper systems. Go-to-market through federally qualified health center networks with bundled subscription pricing that converts capital expenditure to operational budgets aligns procurement authority. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with installed base expansion capacity over pure technology plays. Long-term viability across the next decade hinges on interoperability-grade certification depth and value-based care contract penetration. Acquisition targets should display FHIR-native architecture and existing CMS Promoting Interoperability Program compliance. Watch ONC enforcement action against information blocking as the signal indicating regulatory tailwind acceleration or compliance cost spike.| Strategic Initiative | Industry Significance |
|---|---|
| ONC Certification Advancement | Accelerates federal reimbursement eligibility and excludes non-compliant competitors from hospital procurement cycles. |
| Cloud Infrastructure Partnership | Secures scalable compute capacity for Texas and Southeast health system migrations while converting capital to operational expenditure. |
| Behavioral Health Module Development | Captures Medicaid expansion demand for mental health parity integration across community hospital networks. |
| AI Documentation Integration | Reduces physician administrative burden in emergency departments while raising FDA oversight exposure for algorithm-generated content. |
| Rural Health Clinic Penetration | Establishes platform presence in underdigitized Appalachian and Delta regions ahead of CMS interoperability mandate deadlines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital CIOs, ambulatory clinic practice administrators, health informaticists, GPO contracts managers, and EHR implementation specialists. Secondary validation drew from CMS Medicare reimbursement databases, ONC certification registries, hospital procurement disclosures, and HHS interoperability compliance reports. Bottom-up sizing of installed base and top-down cross-check against health system IT expenditure surveys enabled triangulation.
Across the analysis window, the forecasting framework modeled deployment model transitions, end-user segment consolidation patterns, and integration level adoption curves. Segmentation dimensions included product architecture, care setting, and geographic cloud infrastructure maturity. CAGRs were derived from elasticity-adjusted penetration curves and replacement cycle analysis. Forecast inputs incorporated CMS Promoting Interoperability Program penalty schedules and ONC timeline accelerations.
The analysis sits within stated boundaries; outcomes outside sustained federal reimbursement pressure or cloud infrastructure reliability would require recalibration. Forecasts reflect assumptions about regulatory enforcement consistency and health system capital availability. Revision becomes warranted when HIPAA security rule enforcement intensity or AI documentation liability frameworks cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
Global Healthcare Integration Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Healthcare API Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
Middle East and Africa Healthcare Archiving and Ediscovery Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
EHR EMR Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
Global Radiology Information Systems Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Healthcare Information Exchange Market