
 France Drug Delivery Devices Market | 2026-2036
France Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Drug Delivery Devices Market Foresight
Pre-filled syringe bundling with biologic therapies is consolidating procurement decisions across French hospital networks and specialty clinics. Roche leverages its oncology portfolio to anchor dual-chamber device partnerships, while Sanofi competes through insulin delivery system specialization. Becton Dickinson and Company sustains manufacturing scale for glass-barrel syringes that dominate high-viscosity biologics administration.
France drug delivery devices are engineered systems for controlled pharmaceutical administration, incorporating elastomeric stoppers, borosilicate glass or cyclic olefin polymer barrels, and needle safety mechanisms manufactured through ISO 13485-certified cleanroom assembly. These devices serve to ensure dose precision, reduce contamination risk, and enable self-administration across chronic and acute therapeutic protocols. Auto-injectors and pre-filled syringes lead product type configurations due to biologics compatibility and patient adherence benefits, while needle-free injection and micro-needle arrays within delivery technology represent the fastest-expanding margin pools as dermatology and vaccine applications mature. Home healthcare providers occupy the most dynamic end user position, reflecting France's push toward ambulatory care cost containment and patient autonomy.
ANSM enforces post-market surveillance and vigilance reporting for drug-device combinations under transposed EU MDR requirements, compelling manufacturers to maintain clinical evidence dossiers and unique device identification traceability. The French national health authority (HAS) evaluates medico-economic benefit to inform reimbursement eligibility, directly shaping which delivery formats achieve market access. Stakeholders must monitor how CSRD sustainability disclosure mandates and evolving EMA guidance on human factors engineering will reshape R&D prioritization and supplier qualification criteria.
Market Dynamics
The migration of chronic disease management from inpatient to outpatient settings is consolidating procurement power around hospital networks and home healthcare providers, forcing device manufacturers to reconfigure supply relationships around volume bundling rather than specialty fragmentation.
Growth Catalysts
- EU MDR transposition:ANSM enforcement of post-market surveillance and unique device identification is accelerating replacement cycles for legacy delivery systems across French hospital networks.
- Biologics viscosity requirements:High-concentration monoclonal antibody formulations are driving demand for improved elastomeric closure systems and glass-barrel syringe compatibility.
- Paris-Saclay cluster concentration:Proximity between contract manufacturers and pharmaceutical R&D facilities is compressing development timelines for combination product submissions.
Market Restraints
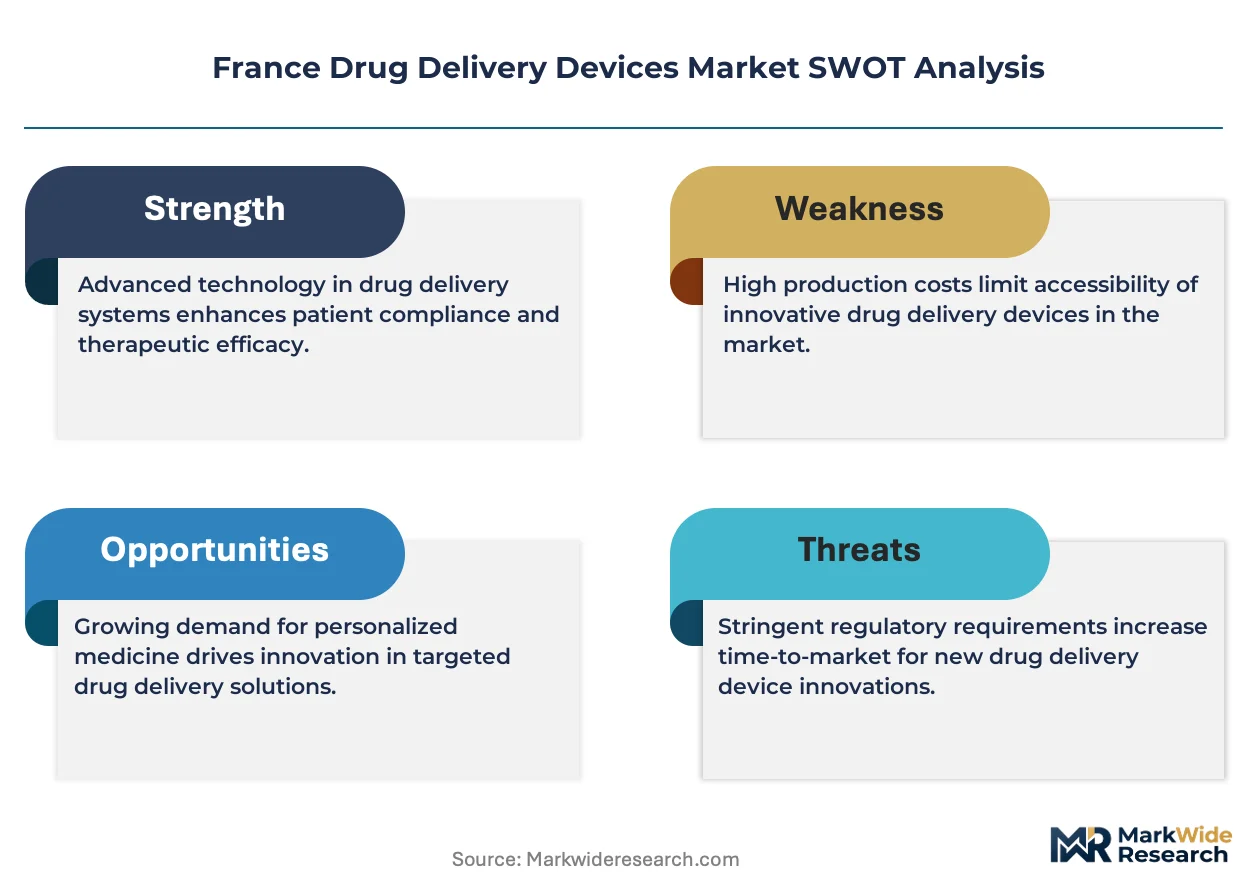
- Borosilicate glass supply concentration:European glass tubing production is concentrated among three specialized suppliers, creating input vulnerability for pre-filled syringe manufacturers.
- CSRD compliance costs:Sustainability disclosure mandates are adding documentation burden and audit expense for mid-scale device producers without captive supply chains.
- Human factors engineering requirements:EMA guidance on usability validation is extending clinical evidence timelines and raising barrier to entry for novel delivery mechanisms.
Strategic Opportunities
- Lyon biopharma corridor expansion:Underutilized cleanroom capacity in the Rhône-Alpes region offers co-location potential for device-drug integration partnerships.
- Micro-needle array dermatology:Cosmetic and therapeutic skin applications represent untapped white space beyond traditional injection modalities.
- HAS medico-economic pathways:Reimbursement evaluation frameworks favoring patient autonomy are creating regulatory tailwind for self-administration device categories.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified certification bodies are experiencing backlog, delaying market entry for novel combination products.
- Legacy ERP integration:UDI traceability requirements are forcing expensive system overhauls at established manufacturers with decades-old infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Drug Delivery Devices Market |
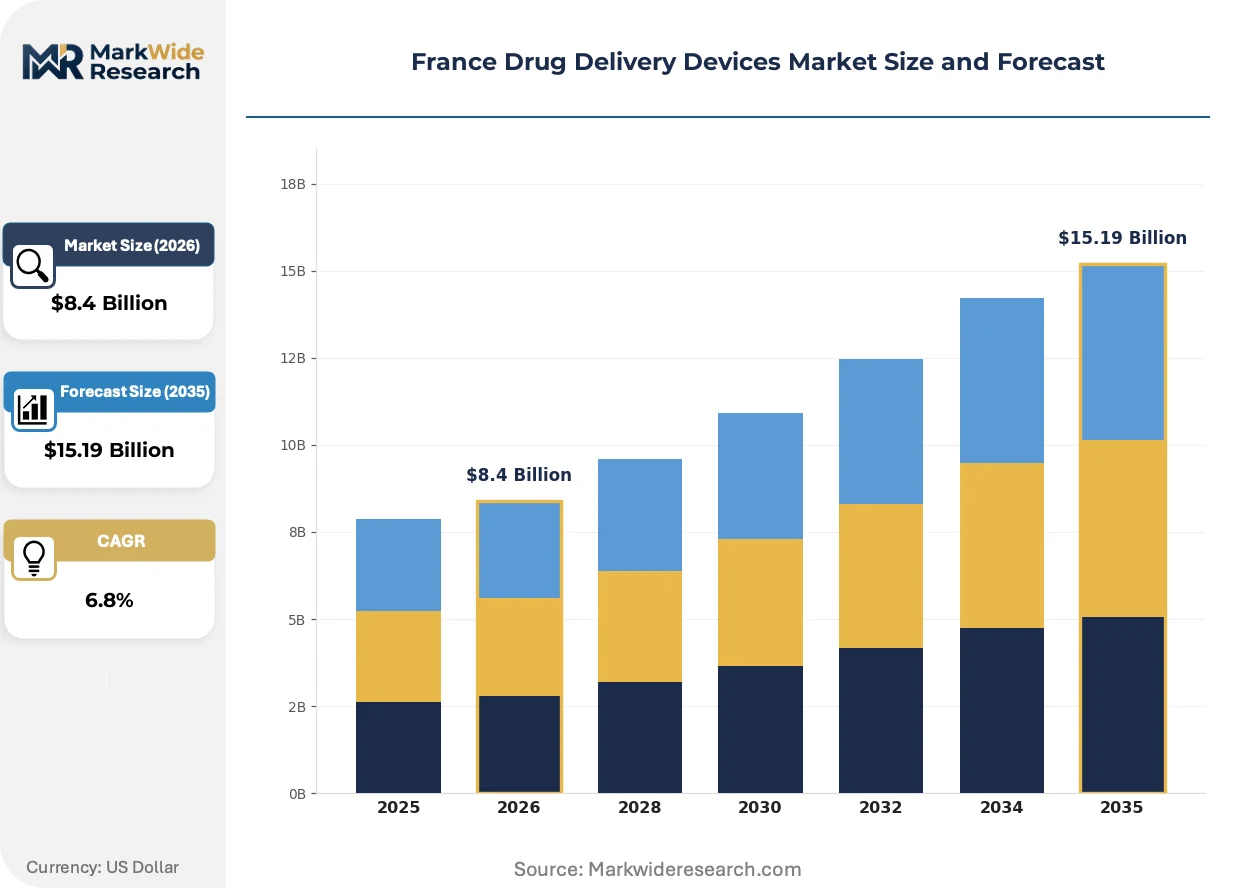
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-filled Syringes, Auto-Injectors, Metered-Dose Inhalers, Nebulizers, Nasal Sprayers Therapy Area: Oncology, Diabetes Management, Respiratory Disorders, Immunotherapy, Cardiovascular Diseases End User: Hospitals, Specialty Clinics, Home Healthcare Providers, Diagnostics Laboratories, Long-Term Care Facilities Delivery Technology: Needle-Free Injection, Dry Powder Inhalation, Micro-Needle Arrays, Jet Injection, Soft Mist Inhalers |
| Companies Covered | Roche, Bayer AG, Becton Dickinson and Company, Novo Nordisk, Medtronic, Sanofi, Novartis AG, Gerresheimer AG, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Drug Delivery Devices Market Shifts & Advancements
Connected delivery systems and sustainable materials are converging to redefine competitive advantage, with regulatory pressure on traceability and environmental disclosure accelerating investment in digital integration and circular design.
Cyclic olefin polymer barrels are rewriting material selection criteria for biologics storage. Specialty clinics in the Île-de-France region are adopting COP syringes at twice the rate of glass alternatives. This shift is compressing the addressable market for traditional borosilicate suppliers while expanding margin pools for polymer conversion specialists.
ANSM vigilance reporting requirements under transposed EU MDR are mandating real-world evidence collection for all combination products. Manufacturers must now maintain post-market clinical follow-up systems previously reserved for novel drug approvals. Device-drug integrators in the oncology segment are responding by embedding digital adherence sensors to automate outcome capture.
Home healthcare providers are consolidating purchasing decisions through regional procurement cooperatives, displacing fragmented clinic-level ordering. This concentration is favoring suppliers with scale certification and multi-site logistics capability. The phenomenon is most visible in the Grand Est and Occitanie regions, where hospital-at-home programs are expanding fastest.
France Drug Delivery Devices Market Segmentation
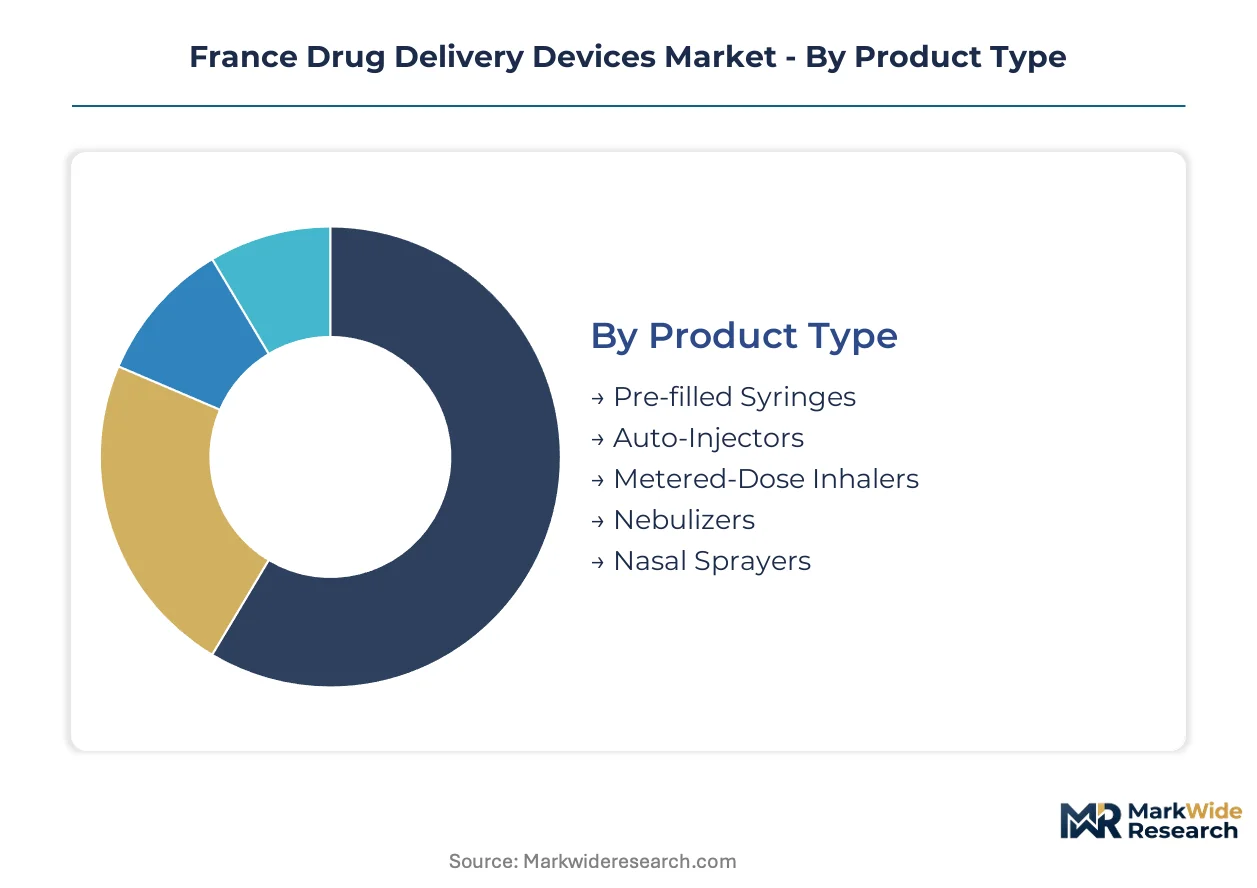
Segmentation in the France drug delivery devices market reveals how procurement power, regulatory pathways, and clinical workflows reshape device selection criteria. Understanding these divisions exposes where manufacturers must adapt specifications to capture volume versus margin opportunities.
Product Type:
Replacement cycles for legacy devices are accelerating as ANSM enforces EU MDR transposition requirements, forcing hospitals to retire non-compliant systems ahead of typical depreciation schedules.
- Pre-filled Syringes:Borosilicate glass or cyclic olefin polymer barrels with elastomeric closure systems ensure dose precision for high-viscosity biologics. Demand concentrates in Paris-Saclay hospital networks managing oncology outpatient protocols, where compatibility with monoclonal antibody formulations drives procurement specifications.
- Auto-Injectors:Spring-powered or electronic drive mechanisms with needle safety features enable self-administration for chronic conditions. Specialty clinics in the Lyon biopharma corridor are standardizing on these devices for immunotherapy regimens, compressing training burdens and reducing adverse event reporting.
- Metered-Dose Inhalers:Pressurized canister systems with dose counters serve asthma and COPD maintenance protocols.
- Nebulizers:Compressor or vibrating mesh systems for acute respiratory episodes in hospital and home settings.
- Nasal Sprayers:Pump-actuated or pressurized devices for hormone therapies and emergency medications.
Pre-filled syringes sit at the top of the volume ranking, with auto-injectors climbing the fastest as home healthcare expansion accelerates.
Therapy Area:
Cost tier differentiation separates premium biologic-compatible devices from standard commodity formats, with reimbursement pathways determining which categories justify higher specification investment.
- Oncology:Combination products for chemotherapy and targeted therapies require cold-chain stability and precise dosing. HAS medico-economic evaluations in the Île-de-France region favor devices with built-in adherence monitoring for value-based contracting.
- Diabetes Management:Insulin delivery systems span disposable pens, pumps, and continuous glucose monitor integrations. The Grand Est region's hospital-at-home programs are consolidating procurement around connected devices that reduce nursing visit frequency.
- Respiratory Disorders:Inhalation devices for asthma and COPD maintenance with dose tracking capabilities.
- Immunotherapy:Subcutaneous delivery systems for checkpoint inhibitors and allergy desensitization protocols.
- Cardiovascular Diseases:Emergency auto-injectors and infusion systems for acute cardiac events.
Oncology commands the steepest expansion trajectory as biologic therapy pipelines mature, while diabetes management holds the largest installed base.
End User:
Customer type fragmentation is giving way to consolidated purchasing through regional cooperatives, reshaping vendor qualification requirements.
- Home Healthcare Providers:Patient-facing devices with simplified interfaces and remote monitoring capabilities. Occitanie region procurement cooperatives are bundling delivery systems with nursing services, favoring suppliers with multi-site logistics.
- Hospitals:Institutional-grade systems with centralized inventory management and UDI traceability. The Rhône-Alpes acute care networks are replacing legacy ERP systems to meet ANSM vigilance reporting mandates.
- Specialty Clinics:Procedure-specific devices for dermatology, rheumatology, and endocrinology practices.
- Diagnostics Laboratories:Sample collection and reagent delivery systems with contamination controls.
- Long-Term Care Facilities:Staff-assisted devices with tamper-evident features for cognitively impaired populations.
Home healthcare providers are gaining share fastest, with hospitals retaining the deepest procurement volume.
Delivery Technology:
Supply concentration in glass tubing and polymer conversion is forcing device makers to secure captive capacity or dual-source critical inputs.
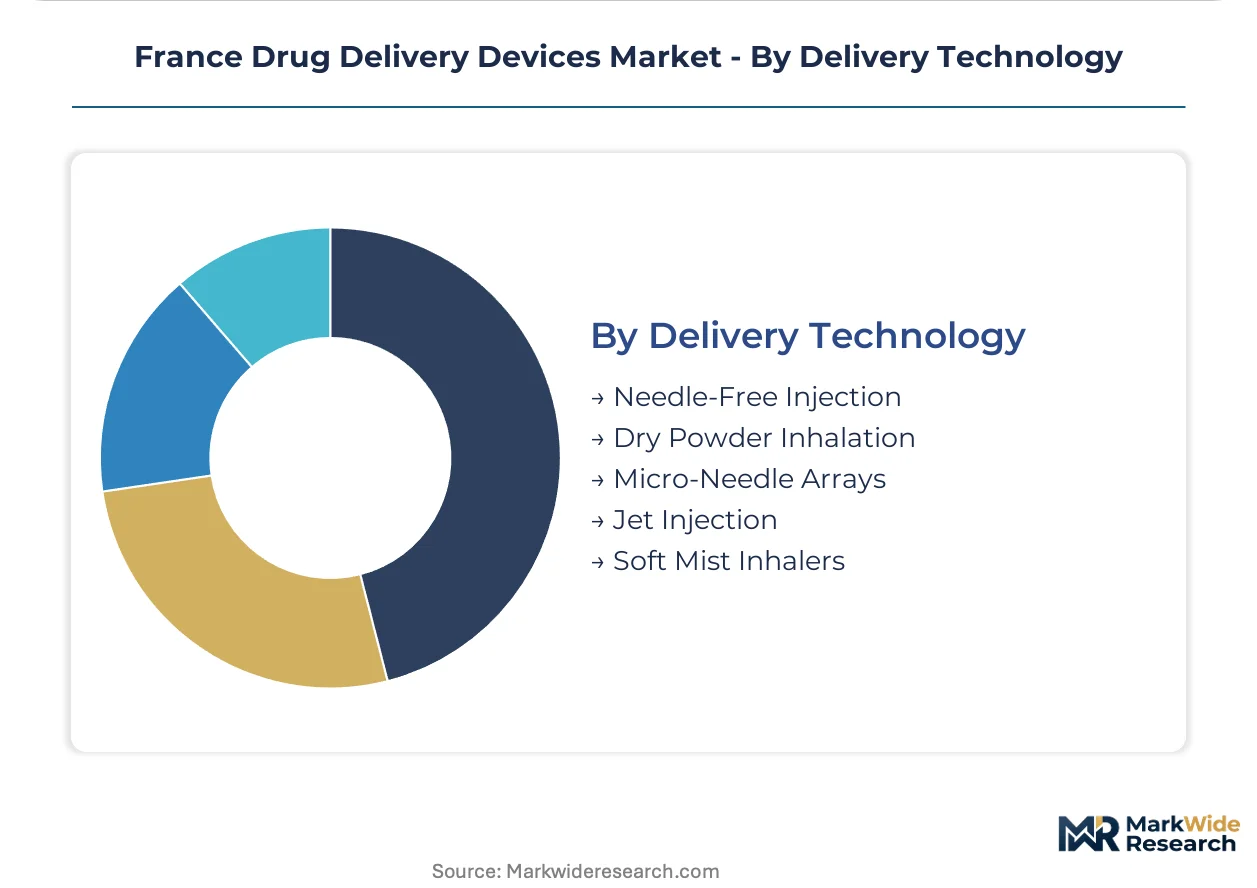
- Micro-Needle Arrays:Dissolving or coated microneedles for transdermal biologic delivery. Dermatology applications in the Côte d'Azur cosmetic medicine cluster are driving early adoption, with therapeutic vaccines representing the next expansion frontier.
- Needle-Free Injection:Spring-powered or gas-driven jet injectors for vaccine and insulin delivery. Pediatric and needle-phobic patient populations in Brittany hospital networks are creating procurement pull for these systems.
- Dry Powder Inhalation:Breath-actuated devices for corticosteroid and bronchodilator delivery.
- Jet Injection:High-pressure liquid or powder systems for intradermal and intramuscular administration.
- Soft Mist Inhalers:Mechanical energy systems generating slow-moving aerosol clouds for elderly patients.
Needle-free injection holds the largest current volume, with micro-needle arrays expanding most quickly as dermatology applications commercialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's drug delivery device industry traces its modern foundation to post-war pharmaceutical manufacturing expansion around Lyon and Paris, where glass syringe production and sterile packaging capabilities first scaled to serve European hospital networks.
Île-de-France
Oncology outpatient protocols and biologics cold-chain requirements dominate procurement specifications across Paris-Saclay hospital networks. ANSM post-market surveillance mandates accelerate device replacement cycles in this cluster. Contract manufacturers near the Saclay plateau compress development timelines for combination product submissions through proximity to pharmaceutical R&D facilities.
Auvergne-Rhône-Alpes
Immunotherapy regimens and specialty clinic consolidation drive standardization on auto-injector formats throughout the Lyon biopharma corridor. HAS medico-economic evaluations favor devices with adherence monitoring capabilities for value-based contracting. Underutilized cleanroom capacity in the Rhône-Alpes region attracts device-drug integration partnerships seeking co-location advantages.
Provence-Alpes-Côte d'Azur
Cosmetic medicine applications and therapeutic dermatology protocols create early adoption pull for micro-needle array technologies. EMA guidance on human factors engineering extends validation timelines for novel delivery mechanisms in this cluster. The Côte d'Azur aesthetic medicine concentration serves as a testbed for transdermal biologic delivery before broader therapeutic rollout.
Occitanie
Hospital-at-home program expansion and regional procurement cooperative formation concentrate purchasing decisions among home healthcare providers. CSRD sustainability disclosure mandates add documentation burden for device suppliers serving this geography. Multi-site logistics capability becomes a vendor qualification threshold as nursing service bundling displaces fragmented clinic-level ordering.
Grand Est
Diabetes management device procurement consolidates around connected systems that reduce nursing visit frequency in this region's hospital-at-home initiatives. EU MDR unique device identification requirements force ERP system overhauls at established manufacturers serving Grand Est networks. Insulin delivery system specialization defines competitive positioning among suppliers to this geography.
France Drug Delivery Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and biologics compatibility dimensions in the French market structure. The vendor base stratifies between multinational device manufacturers with captive polymer conversion capabilities and mid-scale specialists dependent on external glass tubing supply. Three archetypes dominate: integrated combination product developers, component-focused contract manufacturers, and pharmaceutical-owned delivery system divisions. Capacity expansion through cleanroom facility investment and strategic partnerships for UDI traceability compliance represent the dominant competitive moves.
Within the integrated pharmaceutical-device tier, Roche and Sanofi anchor combination product development through oncology and diabetes therapeutic portfolios respectively. Becton Dickinson and Company occupies a position exemplifying scale-driven manufacturing archetype, with its nomenclature indicating US-based corporate structure and historical concentration in injection and infusion device categories. These three entities represent distinct strategic postures: therapeutic anchoring, metabolic disease specialization, and manufacturing scale certification.
| Leading Market Players |
|---|
| Roche |
| Bayer AG |
| Becton Dickinson and Company |
| Novo Nordisk |
| Medtronic |
| Sanofi |
| Novartis AG |
| Gerresheimer AG |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Borosilicate glass tubing spot indices in European markets cascade through three distinct pricing tiers for pre-filled syringe procurement across French hospital networks, with cyclic olefin polymer alternatives compressing mid-tier margins as specialty clinics shift material specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified combination products from component-only suppliers and commodity injection devices. Price differentiation hinges on EU MDR compliance certification and captive polymer conversion capability. Cost compression in economy-tier glass-barrel syringes is intensifying because Grand Est procurement cooperatives are consolidating volume awards. Home healthcare providers exhibit highest price sensitivity, while oncology outpatient clinics in Paris-Saclay prioritize biologics compatibility over unit cost.
Supply Chain Analysis
Borosilicate glass tubing supply rests on German, Italian, and Swiss specialty manufacturers, with cyclic olefin polymer resin drawing from Belgian and Dutch petrochemical complexes. Critical inputs include elastomeric closure formulations, needle safety mechanisms, and cleanroom assembly capacity. Single-source vulnerability concentrates in European glass tubing production, where three specialized suppliers anchor global pharmaceutical-grade output. Distribution runs through regional hospital procurement cooperatives in Occitanie and Grand Est, displacing fragmented clinic-level ordering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France drug delivery devices function as a stable compounder anchored by chronic disease outpatient migration, with biologics pipeline maturation ensuring sustained replacement demand across hospital networks and home healthcare channels.
For Market Incumbents: Acquire underutilized cleanroom capacity in the Rhône-Alpes region to secure co-location advantages for device-drug integration partnerships. ISO 13485 auditor scarcity threatens certification timelines for novel combination products, making captive quality infrastructure essential. Backward integration into cyclic olefin polymer conversion preserves margin pools as glass-barrel alternatives expand. For New Entrants and Emerging Players: EU MDR transposition in France opens a window for digital adherence sensor development, with ANSM vigilance reporting mandates automating outcome capture for value-based contracting. Micro-needle array dermatology applications in the Côte d'Azur cosmetic medicine cluster represent the most penetrable white space. HAS medico-economic evaluation frameworks favor patient autonomy devices, creating regulatory tailwind for self-administration formats. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturers possessing multi-site logistics capability and UDI traceability compliance infrastructure. Long-term viability spans the biologics patent cliff cycle, with device-drug integration partnerships outlasting individual molecule exclusivity. Watch CSRD sustainability disclosure mandate enforcement as the inflection indicator for mid-scale producer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Acquisition | Rhône-Alpes facility investment compresses development timelines for ANSM combination product submissions. |
| Digital Adherence Sensor Development | Embedded monitoring automates post-market clinical follow-up under EU MDR vigilance requirements. |
| Cyclic Olefin Polymer Conversion | In-house polymer barrel production insulates margin pools from German glass tubing supply concentration. |
| Regional Procurement Cooperative Partnership | Occitanie and Grand Est logistics capability becomes vendor qualification threshold for hospital-at-home expansion. |
| HAS Reimbursement Strategy Investment | Medico-economic evidence dossiers secure market access for self-administration device categories. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down device manufacturer production tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and ANSM regulatory affairs specialists cross-validated against secondary sources including EMA guidance documents, HAS reimbursement evaluations, EU MDR transposition texts, and French hospital procurement database extracts. Triangulation between end-user demand signals and supply-side capacity announcements ensures segmentation integrity.
Input-output matrices map device unit demand by therapy area against manufacturing capacity by material type and certification grade across the projection horizon. Segmentation dimensions span product type, delivery technology, end-user channel, and regional regulatory cluster. CAGRs derive from elasticity-adjusted volume projections and value-per-unit trends informed by biologics pipeline maturation and materials substitution patterns. Forecast inputs incorporate ANSM enforcement intensity indices and HAS evaluation pathway timelines.
Revisions become necessary when EU MDR implementation delays, borosilicate glass supply disruptions, or CSRD compliance cost shocks materialize beyond baseline assumptions. Forecasts reflect documented expectations about regulatory enforcement cadence and materials substitution velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pericardial Patches Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Corneal Implants Market
Medical Devices
Retinal Implant Market
Medical Devices
India Hemostats Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Directed Energy Based Surgical Systems Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Global Surgical Polypropylene Mesh Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Global Pupillometer Market
Medical Devices
Sinus Implants Market
Medical Devices
Stethoscope Hygiene Devices Market