
 United States EHR Cloud Computing Market | 2026-2036
United States EHR Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
United States EHR Cloud Computing Market Analytics
Health informatics talent scarcity is rotating hospital IT priorities toward managed service partnerships rather than in-house cloud engineering. Epic Systems Corporation leverages its proprietary interoperability framework to sustain dominance among large academic medical centers. Oracle Health anchors enterprise cloud migrations through its Cerner acquisition integration and federal footprint. NextGen Healthcare, Inc. competes aggressively for ambulatory market share with specialized cloud-native tools for physician practices.
Electronic health record cloud computing encompasses the remote hosting, processing, and storage of patient clinical data across distributed server architectures with guaranteed uptime thresholds exceeding 99.9% and encrypted transmission protocols satisfying federal privacy mandates. Its primary purpose eliminates on-premise hardware maintenance burdens while enabling real-time care coordination across geographically dispersed provider networks. Software as a Service dominates current revenue flows because subscription models align vendor incentives with continuous platform improvement and regulatory update delivery. Hybrid Cloud configurations represent the fastest-expanding deployment category as organizations balance sensitive data sovereignty requirements against elastic compute needs for analytics workloads. Managed Services capture expanding margin pools as hospitals outsource HIPAA compliance monitoring and disaster recovery operations to specialized vendors.
FDA oversight of clinical decision support algorithms embedded within EHR platforms intersects with HHS enforcement of HIPAA breach notification rules and ONC certification requirements for interoperability standards. These regulatory layers shape vendor product roadmaps by mandating audit logging, patient access APIs, and standardized data formats that determine market access eligibility. Stakeholders must monitor how CMS reimbursement policies for telehealth and remote patient monitoring reshape cloud capacity planning and data latency requirements across regional health systems.
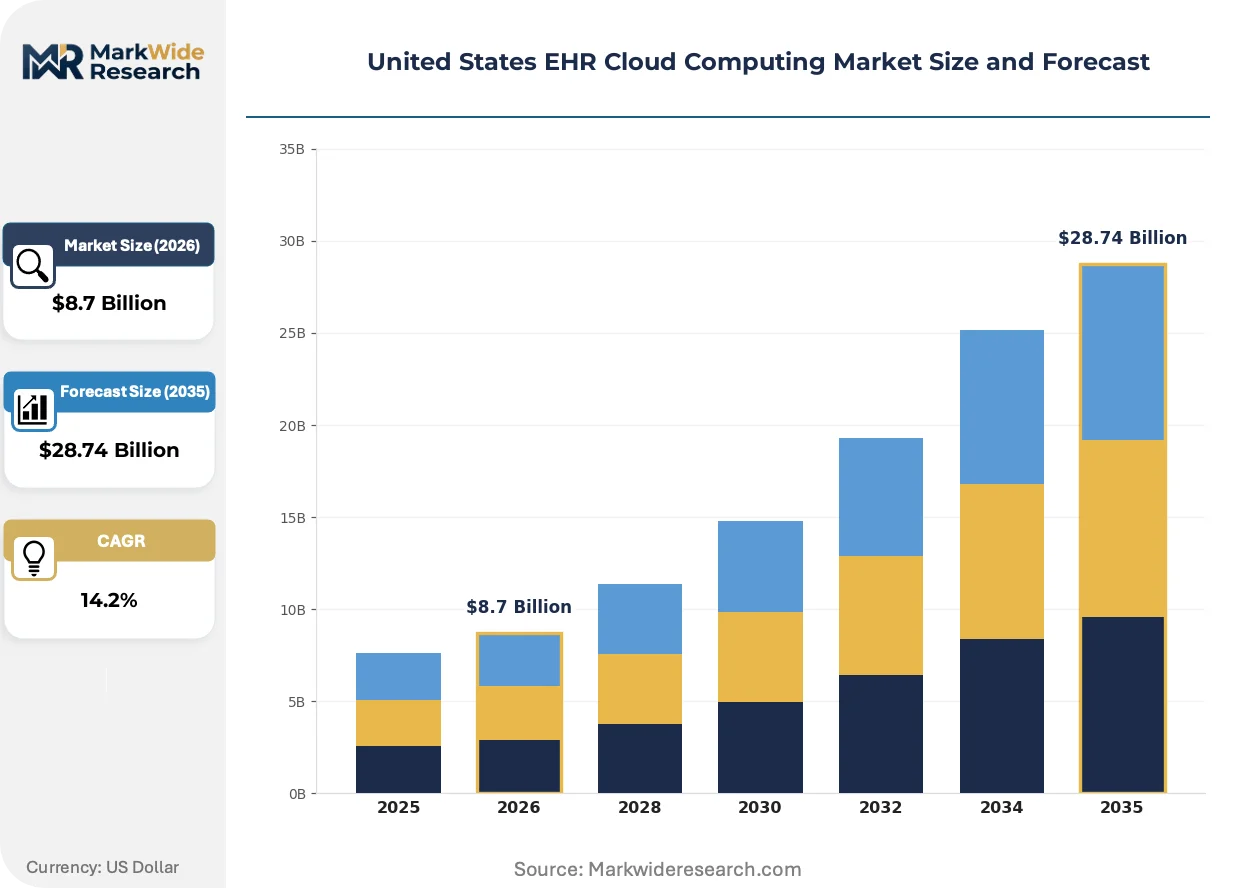
Market Dynamics
Health systems are consolidating data center footprints into multi-tenant cloud architectures to satisfy interoperability mandates while containing operational expenditure. This structural migration is compressing vendor selection cycles and elevating managed service dependencies.
Growth Catalysts
- The 21st Century Cures Act:Information blocking prohibitions compel API-based data exchange, forcing health systems toward cloud-native infrastructure that supports real-time patient record portability.
- Integrated delivery network consolidation:Multi-hospital systems in Texas and California achieve scale economies through centralized cloud deployments, reducing per-site infrastructure redundancy.
- Telehealth reimbursement permanency:CMS policy shifts sustain demand for elastic cloud capacity that handles episodic volume spikes without capital-intensive server provisioning.
Market Restraints
- Specialized health informatics talent scarcity:Cloud architecture expertise gaps force hospitals toward premium-priced managed service contracts rather than in-house engineering.
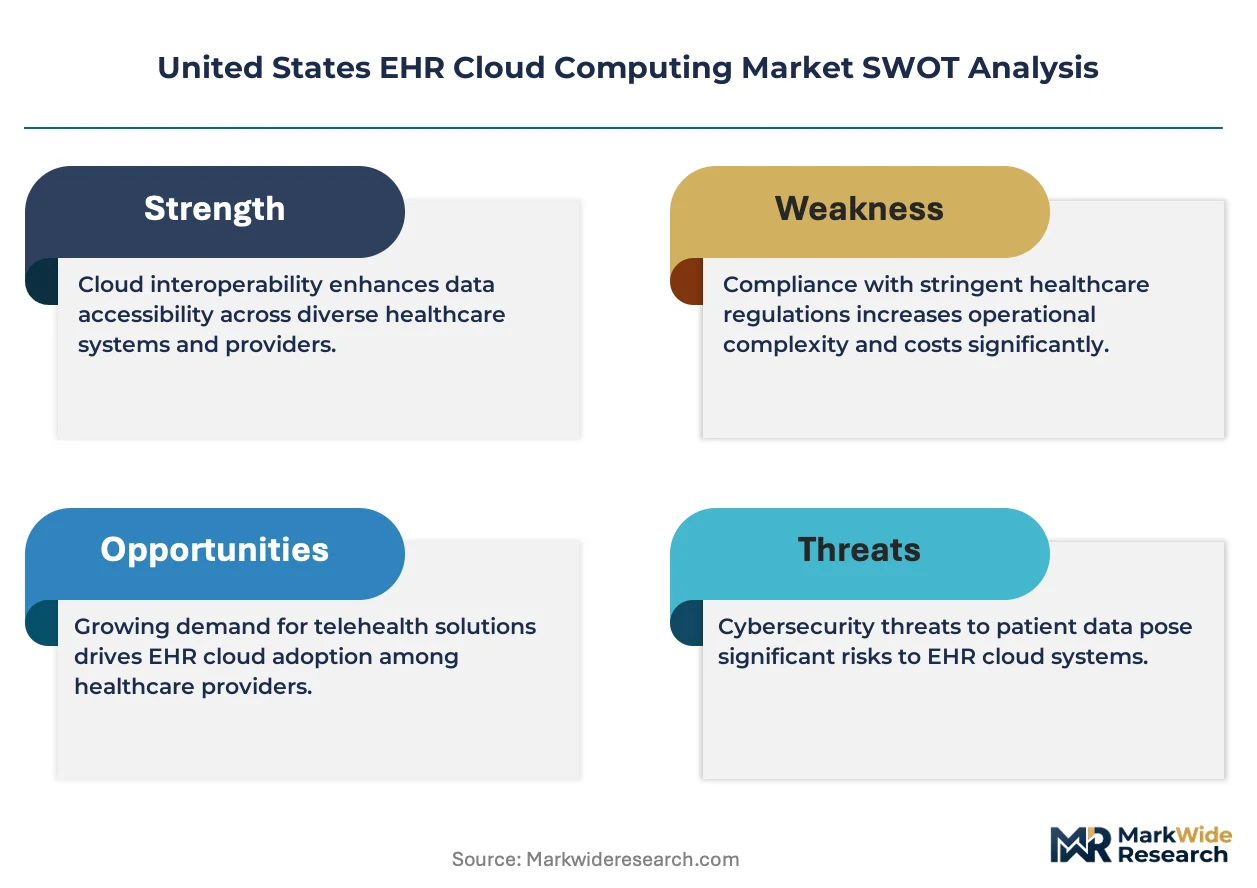
- Data sovereignty requirements:State-level patient privacy variations constrain pure public cloud adoption, mandating costly hybrid configurations with on-premise encryption gateways.
- Legacy EHR technical debt:Proprietary on-premise systems from dominant vendors create integration friction that slows cloud migration timelines.
Strategic Opportunities
- Rural health system underpenetration:Critical access hospitals in the Mountain West and Deep South remain underserved by enterprise cloud solutions, creating white space for specialized vendors.
- AI-enabled clinical decision support:FDA regulatory pathways for algorithmic diagnostics intersect with cloud compute elasticity, enabling real-time inference at scale.
- Federal health system modernization:VA and DHA cloud-first mandates create concentrated procurement opportunities with simplified contracting vehicles.
Industry Challenges
- HIPAA compliance monitoring complexity:Continuous security posture verification across distributed cloud environments strains hospital security operations centers.
- Interoperability standard implementation:ONC certification requirements for FHIR-based APIs demand multi-year platform reengineering that disrupts clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States EHR Cloud Computing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Software as a Service, Infrastructure as a Service, Platform as a Service, Managed Services End User: Hospitals, Physician Practices, Clinics, Long-Term Care Facilities Compliance Standard: HIPAA, HITECH, Meaningful Use, ISO 27001 |
| Companies Covered | Epic Systems Corporation, Oracle Health, NextGen Healthcare, Inc., Allscripts Healthcare, LLC, Medical Information Technology, Inc., eClinicalWorks, Athenahealth, Greenway Health, LLC, Computer Programs and Systems, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States EHR Cloud Computing Market Evolving Landscape
Cloud architecture choices are fragmenting as health systems balance elastic compute against data residency requirements. This tension is producing specialized deployment patterns that diverge from generic enterprise cloud adoption.
Containerized microservices architectures are fragmenting monolithic EHR platforms into modular components that interoperate through standardized APIs. Academic medical centers are piloting these decompositions to isolate analytics workloads from core clinical transaction processing. This technical shift is fragmenting vendor lock-in patterns by enabling best-of-breed component substitution.
HHS enforcement of HIPAA breach notification rules intersects with FDA oversight of clinical decision support algorithms, creating overlapping compliance obligations. Cloud vendors must now maintain audit logging capabilities that satisfy both privacy and safety regulatory frameworks. Large integrated delivery networks are responding by demanding consolidated compliance dashboards from their infrastructure providers.
Hospital IT procurement is compressing vendor evaluation cycles as executive boards mandate accelerated cloud migration timelines. Traditional twelve-month selection processes are collapsing into ninety-day decisions driven by capital lease expirations and security vulnerability exposures. This behavioral shift is most visible among faith-based health systems in the Midwest that face simultaneous EHR end-of-life and data center contract renewals.
United States EHR Cloud Computing Market Segmentation
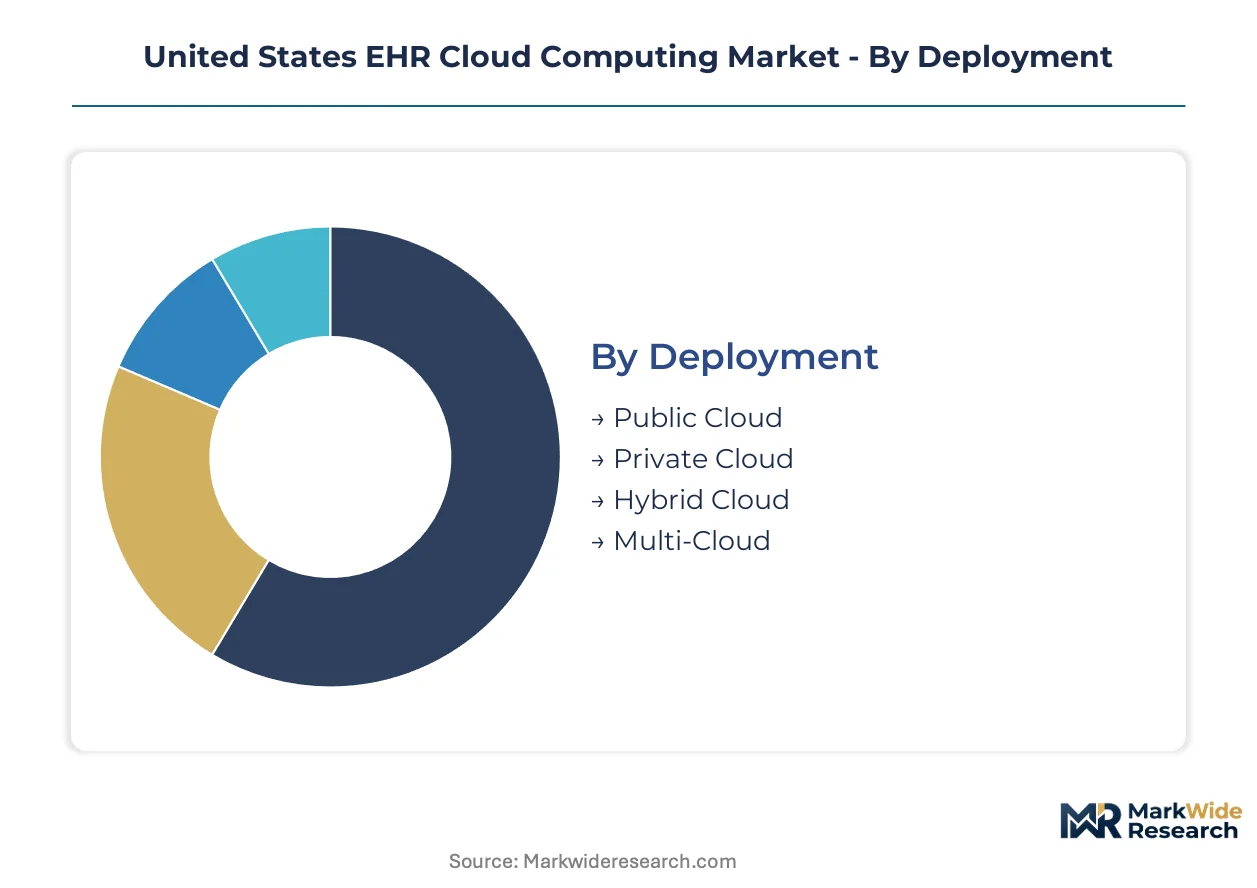
EHR cloud segmentation reveals how deployment architecture, service delivery models, end-user scale, and compliance frameworks stratify vendor opportunity. Procurement patterns diverge sharply across these dimensions as health systems balance elasticity against regulatory exposure.
Deployment:
Hybrid Cloud and Multi-Cloud configurations face intensifying substitution pressure from unified platform offerings that promise simplified vendor management.
- Public Cloud:Third-party infrastructure delivers elastic compute without capital commitment. Demand concentrates among ambulatory networks in Florida and Arizona where seasonal patient volume swings require burst capacity without on-premise overprovisioning.
- Private Cloud:Dedicated single-tenant environments isolate patient data within health system-controlled boundaries. Academic medical centers in Massachusetts and Pennsylvania favor this architecture for genomics research workloads that trigger heightened HIPAA scrutiny.
- Hybrid Cloud:Split architectures retain sensitive records on-premise while pushing analytics to public infrastructure. Texas integrated delivery networks deploy this pattern to satisfy state medical board data residency rules while accessing AWS SageMaker for population health modeling.
- Multi-Cloud:Distributed workloads across competing hyperscalers reduce vendor lock-in and outage risk. Large California systems pursue this strategy to negotiate pricing leverage and satisfy disaster recovery mandates requiring geographic separation.
Hybrid Cloud retains volume leadership; Multi-Cloud holds the steepest expansion curve.
Service Type:
Cost tier stratification separates capital-light subscription models from infrastructure-heavy engagements that demand specialized engineering talent.
- Software as a Service:Subscription-based EHR applications eliminate version management and patch deployment burdens. Physician practices in the Pacific Northwest prefer this model for predictable operational expenditure and automatic ONC certification updates.
- Infrastructure as a Service:Raw compute, storage, and networking resources provisioned on demand. Rural critical access hospitals in Montana leverage IaaS to replace aging on-premise servers without maintenance staff expansion.
- Platform as a Service:Development environments and middleware enabling custom application deployment. Health systems in North Carolina use PaaS layers to build patient-facing mobile apps without managing underlying Kubernetes clusters.
- Managed Services:Outsourced security operations, compliance monitoring, and disaster recovery. Midwest faith-based hospitals contract these services to address HIPAA Security Rule audit requirements with limited internal cybersecurity expertise.
Software as a Service dominates current revenue; Managed Services is climbing the fastest.
End User:
Customer type determines integration complexity, with consolidation trends favoring vendors who can scale across facility categories.
- Hospitals:Inpatient facilities with 24/7 critical care demands and extensive ancillary system integration. Multi-hospital systems in Ohio and Illinois centralize cloud procurement to standardize EHR instances across acquired community hospitals.
- Physician Practices:Outpatient ambulatory settings with lighter interoperability requirements. Solo and small group practices in Texas select cloud-native EHRs that minimize IT overhead and support value-based care reporting.
- Clinics:Federally qualified health centers and retail health locations. Community health centers in the Deep South prioritize cloud solutions with embedded social determinants of health screening tools.
- Long-Term Care Facilities:Skilled nursing and assisted living operators with distinct medication management and care plan workflows. Post-acute providers in Florida adopt specialized cloud platforms that bridge acute-to-post-acute care transitions.
Hospitals retain volume leadership; Long-Term Care Facilities hold the steepest expansion curve.
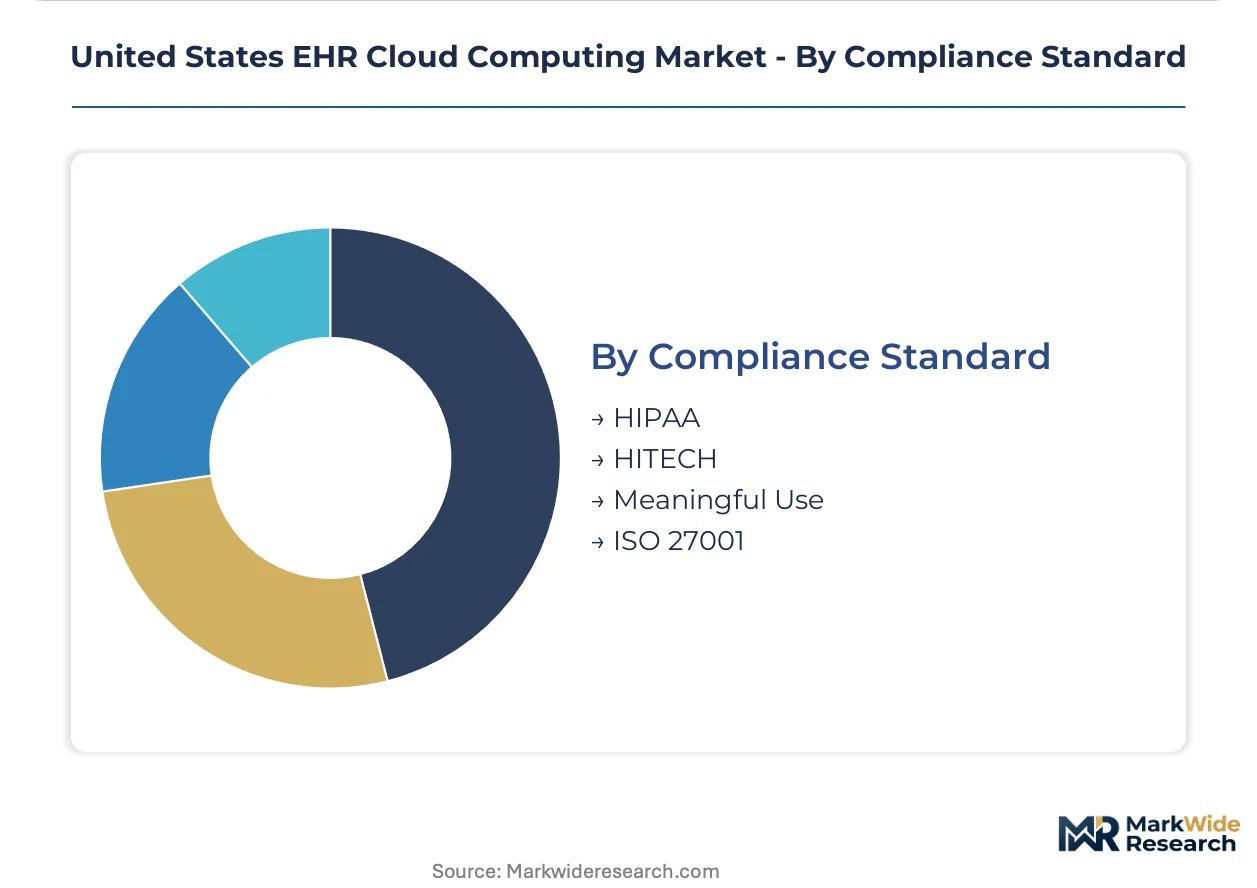
Compliance Standard:
Maturity differentiation separates legacy frameworks from emerging requirements that reshape vendor certification roadmaps.
- HIPAA:Federal privacy and security regulations governing protected health information. All cloud deployments must satisfy HIPAA Security Rule technical safeguards with business associate agreements.
- HITECH:Breach notification and enforcement enhancements strengthening HIPAA accountability. Cloud vendors must demonstrate audit logging capabilities that support HHS Office for Civil Rights investigation protocols.
- Meaningful Use:CMS incentive program criteria driving EHR adoption and interoperability. Stage 3 requirements push cloud platforms toward patient-facing API capabilities.
- ISO 27001:International information security management system certification. Large integrated delivery networks demand this standard as a procurement gate for international cloud providers entering the US market.
HIPAA retains volume leadership; ISO 27001 holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HHS enforcement of HIPAA breach notification rules and ONC certification requirements for interoperability standards anchor cloud migration patterns across state health systems. The 21st Century Cures Act information blocking prohibitions accelerate API-based data exchange requirements that favor centralized infrastructure deployments.
Texas
Integrated delivery network consolidation drives multi-hospital cloud centralization in Dallas-Fort Worth and Houston metro clusters. State medical board data residency rules mandate hybrid configurations with on-premise encryption gateways for sensitive records. Texas Medical Center institutions deploy AWS SageMaker for population health modeling while retaining clinical data within state boundaries.
California
Multi-cloud strategies dominate among large health systems seeking pricing leverage and geographic disaster recovery separation. Kaiser Permanente and Stanford Health Care anchor Silicon Valley's concentration of containerized microservices pilots. The California Consumer Privacy Act layering onto HIPAA creates dual compliance frameworks that elevate managed service demand.
Massachusetts
Academic medical centers in Boston-Cambridge favor private cloud architectures for genomics research triggering heightened HIPAA scrutiny. Partners HealthCare and Mass General Brigham sustain Epic Systems dominance through proprietary interoperability frameworks. NIH grant requirements for data sharing accelerate FHIR-based API investments across research hospitals.
Florida
Ambulatory networks exploit public cloud elasticity for seasonal patient volume swings without capital-intensive server overprovisioning. Tampa Bay and South Florida physician practices select cloud-native EHRs minimizing IT overhead for value-based care reporting. CMS Medicare Advantage penetration concentrates cloud procurement among Medicare-focused provider groups.
Ohio
Multi-hospital systems centralize cloud procurement to standardize EHR instances across acquired community hospitals in Cleveland and Cincinnati clusters. Faith-based health systems face simultaneous EHR end-of-life and data center contract renewals compressing vendor selection cycles. Ohio Medicaid managed care expansion drives interoperability investments among safety-net providers.
United States EHR Cloud Computing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a tiered market structure with concentrated dominance at the top and fragmentation below. Epic Systems Corporation and Oracle Health anchor the enterprise tier through proprietary frameworks and federal footprint scale, while ambulatory specialists compete on cloud-native deployment speed. Three archetypes define competitive positioning: integrated platform vendors, best-of-breed component specialists, and managed service aggregators. M&A activity concentrates among hyperscalers acquiring healthcare vertical capabilities, while strategic partnerships between EHR vendors and cloud infrastructure providers reshape deployment economics.
Within the enterprise platform tier, Epic Systems Corporation and Oracle Health exemplify divergent scale strategies, with the former leveraging academic medical center lock-in and the latter exploiting Cerner acquisition integration for federal system access. NextGen Healthcare, Inc. occupies a position among ambulatory-focused cloud-native vendors competing for physician practice market share through specialized workflow tools. These three anchors represent the spectrum from monolithic enterprise dominance to modular outpatient specialization, with competitive tension intensifying as containerized microservices enable component substitution across deployment categories.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| NextGen Healthcare, Inc. |
| Allscripts Healthcare, LLC |
| Medical Information Technology, Inc. |
| eClinicalWorks |
| Athenahealth |
| Greenway Health, LLC |
| Computer Programs and Systems, Inc. |
| Others |
Value Network & Pricing Analysis
Multi-tenant data center consolidation among Texas and California integrated delivery networks creates scale economies that compress per-seat pricing floors while elevating vendor concentration. Cloud infrastructure hyperscalers leverage these capacity commitments to extract preferential egress pricing from regional hospitals, forcing mid-tier vendors toward managed service bundling to defend margin structures.
Pricing Analysis
Geographic price spreads between Dallas-Fort Worth and Boston-Cambridge academic medical centers exceed thirty percent for equivalent Epic Systems deployments, reflecting localized vendor lock-in and specialized compliance engineering costs. Subscription-based SaaS tiers dominate, with pricing stratifying across premium enterprise, standard health system, and economy ambulatory levels based on API call volumes and HIPAA Business Associate Agreement scope. Cost compression in the standard tier intensifies because Oracle Health's Cerner integration subsidizes migration pricing to capture federal health system share. Critical access hospitals in Montana and the Deep South exhibit highest price sensitivity, while Mass General Brigham and Kaiser Permanente anchor least-sensitive procurement through research grant funding and captive IT capital pools.
Supply Chain Analysis
AWS GovCloud and Azure Government accreditation backlogs create procurement chokepoints that extend federal health system onboarding timelines by quarters. Cloud infrastructure draws from concentrated hyperscaler supply bases in Northern Virginia, Oregon, and Iowa data center clusters, with compute hardware sourcing from Taiwan semiconductor foundries and South Korean memory fabricators. Single-source vulnerability concentrates in FDA-validated server configurations for clinical decision support workloads, where hardware certification dependencies limit vendor substitution. Distribution runs through direct enterprise sales teams and specialized healthcare value-added resellers, with GPO contracts capturing sixty percent of hospital procurement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source FHIR-based EHR platforms and containerized microservices architectures threaten incumbent substitution by fragmenting monolithic vendor lock-in patterns. Incumbents must navigate this modularization pressure while defending enterprise platform consolidation economics.
For Market Incumbents: Compound proprietary interoperability framework investments to deepen Epic Systems' academic medical center entrenchment against modular substitution threats. Anchor federal health system relationships through Oracle Health's VA and DHA cloud-first mandate execution, using this footprint to subsidize commercial pricing pressure. Prioritize backward integration into managed security operations to capture HIPAA compliance monitoring margins that independent vendors currently extract.
For New Entrants and Emerging Players: ONC certification fast-track specialization opens procurement doors for ambulatory-focused vendors targeting solo physician practices in Texas and Florida. Rural critical access hospitals in the Mountain West represent the most penetrable segment, with legacy EHR end-of-life cycles compressing vendor selection windows to ninety-day decisions. Pursue white-label platform partnerships with regional health information exchanges as the primary go-to-market angle, embedding social determinants of health screening tools to differentiate from incumbent workflow rigidity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors managed service aggregators with HIPAA Security Rule audit capabilities over pure-play infrastructure vendors. Long-term viability across the projection horizon hinges on container orchestration expertise that enables best-of-breed component substitution without clinical workflow disruption. Acquisition targets should demonstrate FHIR-based API engineering depth and existing GPO contract relationships. The signal to watch is CMS telehealth reimbursement policy volatility, which would recalibrate cloud capacity planning assumptions and reshape vendor valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| ONC Certification Fast-Track Investment | Accelerates market access eligibility for API-based interoperability compliance under 21st Century Cures Act mandates. |
| Hybrid Cloud Architecture Deployment | Balances Texas medical board data residency rules against AWS SageMaker analytics elasticity for population health modeling. |
| Managed Security Service Expansion | Captures HIPAA compliance monitoring margins from Midwest faith-based hospitals with limited internal cybersecurity expertise. |
| FHIR-Based API Platform Integration | Enables containerized microservices substitution that fragments Epic Systems' proprietary framework lock-in patterns. |
| Federal Health System Partnership | Leverages VA and DHA cloud-first mandates for concentrated procurement opportunities with simplified contracting vehicles. |
Research Methodology
A standing panel of hospital CIOs, health informatics directors, GPO contracts managers, and cloud infrastructure procurement officers provided ongoing calibration against secondary validation sources. Primary interviews with integrated delivery network technology executives and ambulatory practice administrators combined with CMS Medicare data, hospital procurement databases, ONC certification registries, and hyperscaler healthcare vertical disclosures. Bottom-up deployment volume estimates triangulated against top-down health system IT expenditure benchmarks.
Consistency checks against external benchmarks validated model outputs across the projection horizon, with segmentation dimensions spanning deployment architecture, service delivery model, end-user facility type, and compliance framework maturity. CAGRs derived from weighted capacity expansion trajectories and substitution elasticity parameters, incorporating CMS telehealth reimbursement permanency and FDA clinical decision support algorithm oversight as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained 21st Century Cures Act enforcement and stable hyperscaler accreditation timelines would require recalibration. Forecasts reflect documented assumptions regarding health system consolidation velocity and interoperability standard implementation pace. Practitioners should keep alternative scenarios live as HHS HIPAA breach notification enforcement intensity and ONC certification requirement evolution reshape vendor compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
High Acuity Information Systems Market
Health Informatics
Global Radiology Information Systems Market
Health Informatics
Indonesia Connected Healthcare Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Healthcare BI Market
Health Informatics
Global Laboratory Information Management System (LIMS) Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
IHE XDS.B Market
Health Informatics
Clinical Intelligence Market