
 Healthcare Operational Analytics Market | 2026-2036
Healthcare Operational Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Operational Analytics Market Outlook
The direct-to-hospital software channel is narrowing as health systems consolidate vendor relationships under enterprise agreements. McKesson Corporation leverages its pharmaceutical distribution footprint to cross-sell analytics modules into existing accounts. Oracle Corporation anchors its position through database-to-cloud migration contracts that bundle operational analytics. SAS Institute Inc. competes on statistical depth in predictive workforce planning.
Healthcare operational analytics encompasses the computational analysis of clinical, financial, and logistical data streams to optimize institutional performance, typically processing real-time feeds from EHR systems, supply chain databases, and staffing rosters through machine learning pipelines. Cloud-Based Solutions lead deployment preference as hospitals retire on-premise server rooms, though On-Premise Systems retain share among organizations with legacy cybersecurity protocols. Predictive Analytics captures the fastest expansion as staffing shortages drive demand for patient volume forecasting algorithms.
FDA guidance on clinical decision support software and HIPAA security rule enforcement shape product certification requirements for US vendors, while GDPR data residency provisions constrain cloud architecture choices for European deployments. The EU AI Act's risk classification framework for health-related algorithms will force recalibration of model validation protocols. Stakeholders must monitor how interoperability mandates in multiple jurisdictions redefine data liquidity standards and platform switching costs.
Market Dynamics
Hospital consolidation into mega-systems is compressing vendor sales cycles and forcing analytics platforms to prove interoperability across heterogeneous EHR environments before contract approval.
Growth Catalysts
- HIPAA Interoperability Mandates:Federal rules requiring seamless data exchange between hospital systems are accelerating procurement of platforms with native FHIR compliance.
- Cloud Migration Timelines:Health systems retiring on-premise infrastructure are bundling operational analytics into enterprise cloud contracts with major providers.
- Accountable Care Infrastructure:Germany, India, and the United States are scaling ACO frameworks that require predictive patient volume forecasting to manage capitated reimbursement risk.
Market Restraints
- GDPR Data Residency Requirements:European deployments face architectural constraints that fragment cloud infrastructure and inflate compliance costs for multi-national health systems.
- Legacy Cybersecurity Protocols:Organizations with rigid on-premise security postures resist cloud-native analytics, creating a bifurcated addressable market.
- Workforce Analytics Skill Scarcity:Hospital IT departments lack personnel trained in machine learning pipeline management, slowing implementation velocity.
Strategic Opportunities
- EU AI Act Risk Classification:The new algorithm validation framework creates first-mover advantage for vendors with pre-certified predictive workforce planning modules.
- Supply Chain-Clinical Convergence:Integration of RFID inventory tracking with real-time staffing algorithms opens white space in perioperative optimization.
- India's PLI Scheme for Healthcare IT:Domestic manufacturing incentives for software development are lowering cost-to-serve for cloud analytics targeting emerging hospital networks.
Industry Challenges
- Interoperability Certification Complexity:Vendors must maintain parallel validation protocols for FDA clinical decision support guidance, HIPAA security rule enforcement, and emerging state-level data liquidity standards.
- EHR Integration Friction:Epic and Cerner environment heterogeneity forces costly custom API development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Operational Analytics Market |
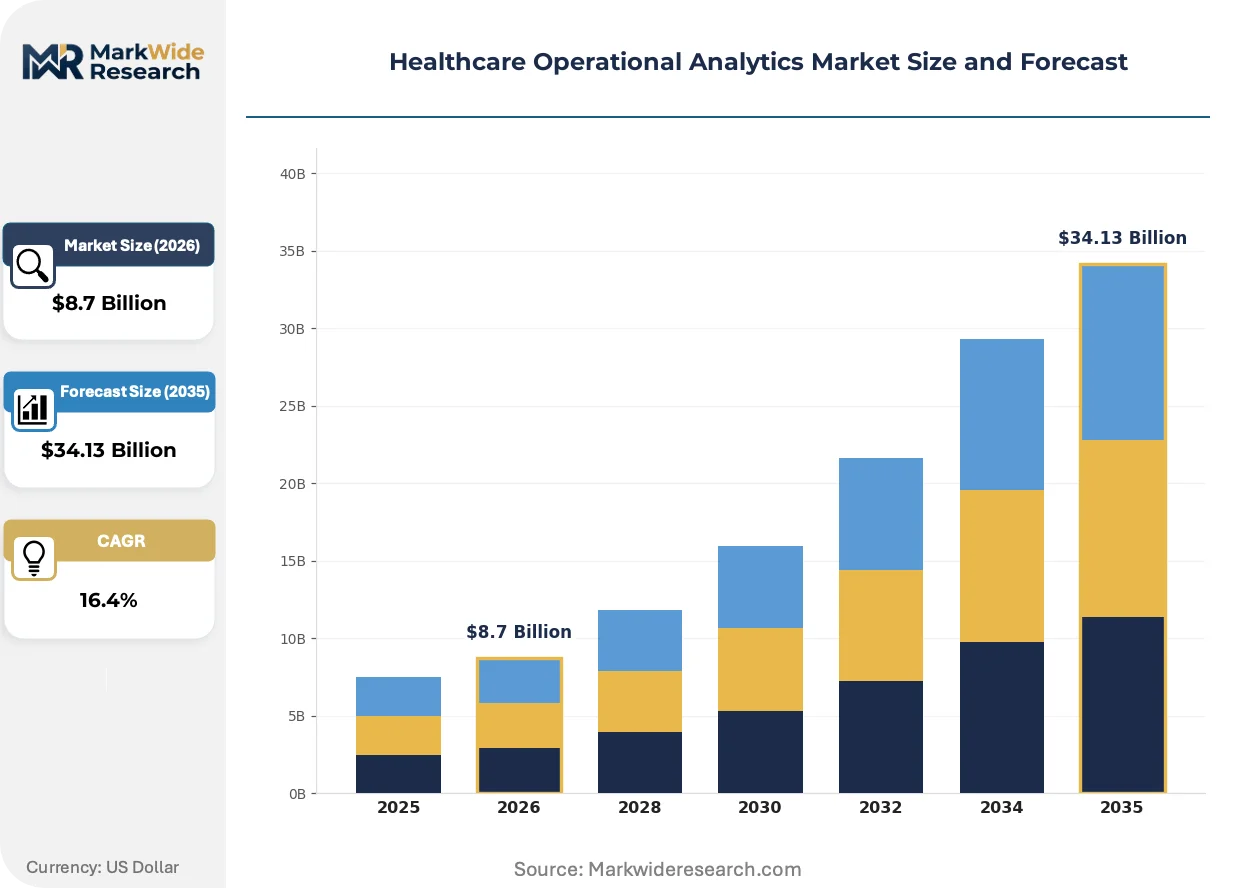
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard Solutions, Reporting Tools, Predictive Analytics, Workflow Management Technology: Cloud-Based Solutions, On-Premise Systems, Mobile Applications, Big Data Technologies End User: Hospitals, Clinics, Long-Term Care Facilities, Emergency Departments Application: Resource Management, Performance Improvement, Financial Analysis, Patient Flow Optimization |
| Companies Covered | McKesson Corporation, Health Catalyst Inc., Oracle Corporation, IBM Corporation, Optum Inc., Merative, UnitedHealth Group, SAS Institute Inc., Veradigm LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Operational Analytics Market Strategic Shifts
Real-time data streaming architectures are displacing batch-processed analytics in hospital operational command centers, compressing decision latency from hours to minutes.
Edge computing nodes deployed within hospital server closets are digitizing patient flow monitoring by processing bed occupancy and discharge prediction algorithms locally before cloud synchronization. Large academic medical centers in Boston and Houston are piloting these deployments to reduce latency for emergency department throughput optimization. The architecture is digitizing how capacity management interfaces with clinical workflow systems.
The EU AI Act's risk classification framework for health-related algorithms is forcing vendors to recalibrate model validation protocols before European market entry. High-risk algorithm categories now require documented training data provenance and post-market performance monitoring. German hospital procurement committees are prioritizing vendors with existing conformity assessments.
Health system CFOs are consolidating vendor relationships under enterprise master service agreements that bundle operational analytics with EHR, supply chain, and workforce management platforms. The direct-to-hospital software channel is narrowing as procurement authority centralizes at the system level. This concentration is most visible in the United States, where ten health systems now control over one-third of licensed beds.
Healthcare Operational Analytics Market Segmentation
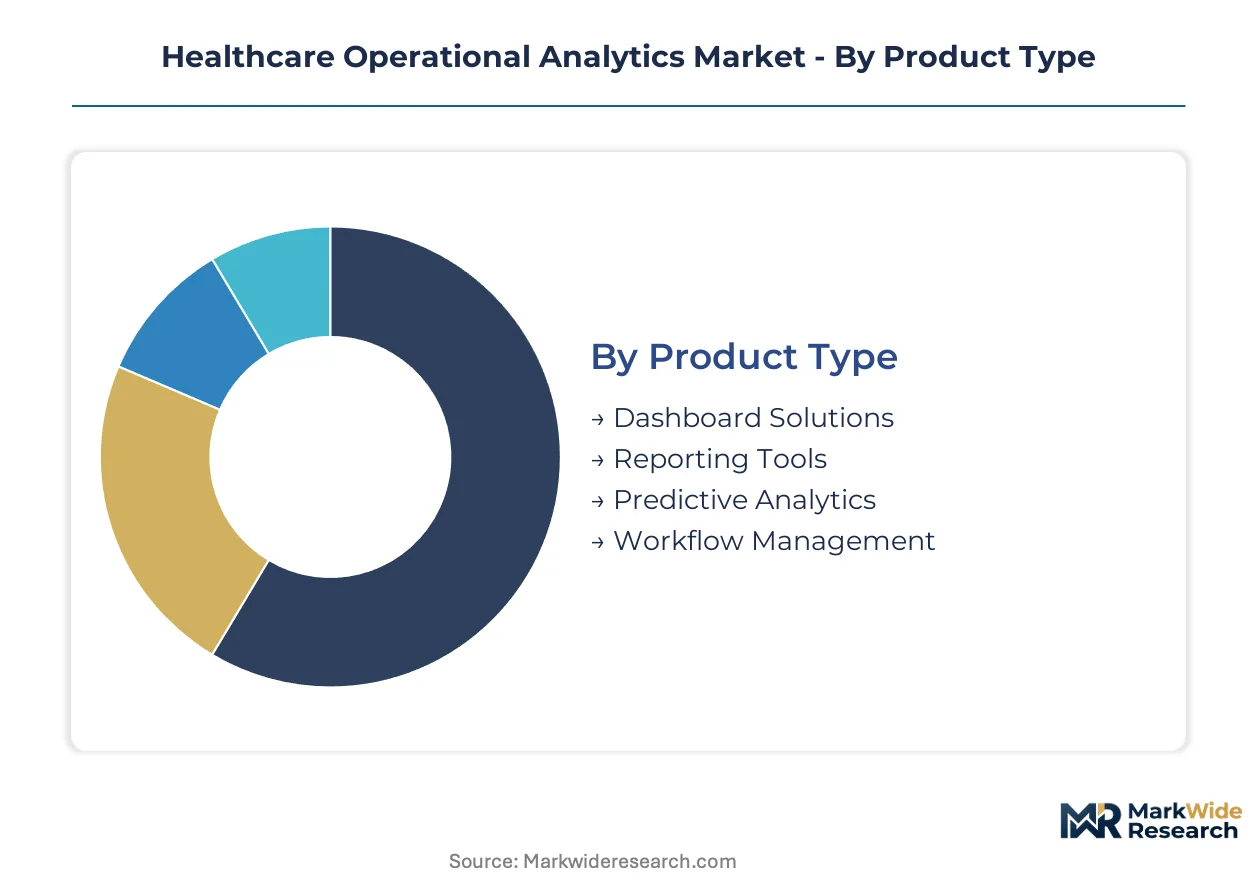
Healthcare operational analytics vendors configure service intensity and support models around product architecture complexity. Cloud deployments demand continuous monitoring and API maintenance, while on-premise installations require heavier upfront integration labor. Segmentation choices directly determine margin structure and renewal economics across hospital system contracts.
Product Type:
After-sales-service intensity varies sharply across product categories, with predictive analytics modules requiring ongoing model retraining and dashboard solutions demanding continuous UX optimization.
- Predictive Analytics:Machine learning pipelines processing patient volume forecasting and staffing algorithms demand continuous model recalibration. Hospital systems in the United States concentrate procurement here as accountable care organizations manage capitated reimbursement risk through algorithmic bed management.
- Workflow Management:Real-time orchestration platforms integrate EHR feeds with supply chain databases and staffing rosters, requiring extensive API customization per deployment. German hospital networks prioritize these tools as EU AI Act compliance deadlines compress vendor validation timelines.
- Dashboard Solutions:Visualization layers aggregating operational KPIs for executive consumption.
- Reporting Tools:Scheduled and ad-hoc analytics output for regulatory submission and internal audit.
By volume, Dashboard Solutions leads. By growth pace, Predictive Analytics is ahead.
Technology:
Cost tier stratification separates cloud-native architectures with subscription economics from capital-intensive on-premise deployments with perpetual licensing.
- Cloud-Based Solutions:Scalable infrastructure with FHIR-native interoperability and automatic security patching. Health systems across India favor this architecture as domestic hospital networks expand without legacy server room investments.
- On-Premise Systems:Localized data processing satisfying rigid cybersecurity protocols and HIPAA security rule enforcement. United States defense health facilities and certain academic medical centers in Boston maintain this posture despite higher total cost of ownership.
- Mobile Applications:Point-of-care alerting and executive dashboards on iOS and Android endpoints.
- Big Data Technologies:Distributed processing frameworks for multi-terabyte clinical and operational data lakes.
By installed base, On-Premise Systems retains plurality share. By expansion trajectory, Cloud-Based Solutions climbs the fastest.
End User:
Customer type determines deployment complexity, with mega-system hospitals demanding enterprise-wide integration versus single-facility clinics requiring lighter configurations.
- Hospitals:Multi-departmental deployments spanning emergency departments, perioperative suites, and inpatient wards with heterogeneous EHR environments. Consolidated health systems in the United States now control procurement authority for over one-third of licensed beds under enterprise master service agreements.
- Emergency Departments:Time-critical throughput optimization with real-time bed occupancy and discharge prediction algorithms. Houston academic medical centers pilot edge computing nodes here to compress decision latency from hours to minutes.
- Clinics:Ambulatory-focused analytics with lighter integration requirements and lower data volumes.
- Long-Term Care Facilities:Staffing ratio compliance and resident acuity tracking across extended care horizons.
By revenue concentration, Hospitals dominates. By implementation velocity, Emergency Departments is expanding most quickly.
Application:
Margin structure diverges across use cases, with patient flow optimization commanding premium pricing for real-time decision support versus financial analysis modules with more standardized feature sets.
- Patient Flow Optimization:Real-time capacity management integrating admission, transfer, and discharge prediction with bed board visualization. German procurement committees prioritize vendors with EU AI Act conformity assessments for these high-risk algorithm categories.
- Resource Management:Supply chain-clinical convergence integrating RFID inventory tracking with staffing algorithms for perioperative optimization. Indian hospital networks exploit PLI scheme incentives to deploy these modules at lower cost-to-serve.
- Performance Improvement:Quality metric tracking and clinical pathway adherence monitoring.
- Financial Analysis:Cost accounting, payer mix analysis, and revenue cycle analytics.
By contract value, Financial Analysis leads. By strategic priority, Patient Flow Optimization is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' interstate fiber backbone and cloud data center corridor linking Northern Virginia to Dallas underwrites its dominance in health data infrastructure. Germany's DE-CIX internet exchange in Frankfurt anchors European health data liquidity. India's National Knowledge Network provides the grid interconnect enabling hospital network digitization.
United States
Hospital consolidation into mega-systems concentrates procurement authority under ten health networks controlling over one-third of licensed beds. HIPAA interoperability mandates and FDA clinical decision support guidance compress vendor validation timelines. Academic medical centers in Boston and Houston pilot edge computing nodes for emergency department throughput optimization.
Germany
Hospital procurement committees prioritize vendors with EU AI Act conformity assessments for high-risk patient flow algorithms. The EU AI Act's risk classification framework forces recalibration of model validation protocols. The Rhine-Ruhr hospital network cluster accelerates workflow management platform deployment ahead of compliance deadlines.
India
Domestic hospital networks expand cloud-native analytics without legacy server room investments. The PLI scheme for healthcare IT lowers cost-to-serve for software development targeting emerging hospital infrastructure. Karnataka's Bangalore hospital corridor and Maharashtra's Mumbai-Pune medical cluster drive procurement concentration.
United Kingdom
NHS England's integrated care system reforms create demand for predictive patient volume forecasting across capitated reimbursement frameworks. GDPR data residency provisions constrain cloud architecture choices for multi-national health system deployments. London's academic hospital consortium leads procurement of real-time operational command centers.
Canada
Provincial health authority consolidation mirrors US mega-system trends, centralizing analytics procurement under enterprise agreements. Health Canada and provincial privacy commissioners enforce data residency requirements shaping vendor selection. Ontario's Toronto-Waterloo hospital corridor and British Columbia's Vancouver health authority cluster drive regional demand concentration.
Healthcare Operational Analytics Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: pharmaceutical distributors cross-selling analytics modules, cloud hyperscalers bundling operational tools into migration contracts, and statistical specialists competing on predictive workforce depth. Enterprise master service agreements are narrowing the direct-to-hospital software channel. Dominant competitive moves include strategic partnerships with EHR vendors and portfolio diversification into supply chain-clinical convergence modules.
Among distribution-anchored players, McKesson Corporation exemplifies the cross-sell archetype leveraging pharmaceutical footprint for analytics module penetration. Oracle Corporation and SAS Institute Inc. occupy positions on the cloud-migration and statistical-specialist vectors respectively, with Oracle anchoring database-to-cloud bundling and SAS representing predictive workforce planning depth.
| Leading Market Players |
|---|
| McKesson Corporation |
| Health Catalyst Inc. |
| Oracle Corporation |
| IBM Corporation |
| Optum Inc. |
| Merative |
| UnitedHealth Group |
| SAS Institute Inc. |
| Veradigm LLC |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in cloud data center infrastructure across India's hospital corridor is forcing vendors to prioritize enterprise contract renewals over new customer acquisition, compressing margins for mid-tier deployments while premium FHIR-compliant modules retain pricing power.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement, with enterprise master service agreements bundling operational analytics into EHR and workforce management contracts at 30-40% per-module discounts versus standalone purchases. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated predictive workforce modules from basic dashboard solutions and unvalidated open-source alternatives. Cost compression in the standard tier is intensifying as Oracle and McKesson cross-sell analytics into existing accounts, eroding standalone vendor margins. Single-facility clinics and emerging hospital networks in India exhibit highest price sensitivity, while consolidated US mega-systems prioritize interoperability certification over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent edge computing deployments in emergency departments. Software development talent concentrates in India, Germany, and the United States, with Bangalore and Frankfurt anchoring predictive algorithm development. Cloud infrastructure draws from hyperscaler data center networks in Northern Virginia, Frankfurt, and Mumbai, creating single-source vulnerability during regional connectivity disruptions. Distribution runs through pharmaceutical distributors cross-selling analytics modules, cloud hyperscalers bundling operational tools, and direct enterprise sales teams targeting consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare operational analytics functions as a defensive-moat market where regulatory entrenchment through FDA clinical decision support guidance and EU AI Act conformity assessments creates substantial switching costs for hospital customers.
For Market Incumbents: Insulate market position by deepening API integration with Epic and Cerner environments to raise rival replacement costs, while accelerating EU AI Act conformity assessments ahead of German procurement committee deadlines. Cloud-native entrants with FHIR-native architectures threaten established on-premise vendors; vertical integration into edge computing hardware for emergency department deployments secures latency-critical workflows.
For New Entrants and Emerging Players: Establish a beachhead in India's emerging hospital networks exploiting PLI scheme cost advantages before incumbent cloud contracts solidify. Supply chain-clinical convergence modules integrating RFID inventory with staffing algorithms represent the most penetrable white space, with perioperative suites in mid-tier US health systems offering lighter EHR integration requirements than mega-system deployments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with predictive analytics modules requiring continuous model retraining, as hospital systems lock into multi-year contracts for algorithm maintenance. Over a five-to-ten-year horizon, acquisition targets should display pre-certified EU AI Act conformity for high-risk patient flow algorithms and established GPO relationships with US hospital purchasing committees. The signal to watch is procurement committee prioritization of conformity-assessed vendors in German Rhine-Ruhr network tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Development | HIPAA interoperability mandates accelerate procurement cycles for compliant vendors in US hospital systems. |
| EU AI Act Conformity Assessment | German procurement committees prioritize pre-certified vendors for high-risk patient flow algorithm categories. |
| Edge Computing Node Deployment | Houston academic medical centers pilot local processing to compress emergency department decision latency. |
| Supply Chain-Clinical Integration | RFID inventory tracking convergence with staffing algorithms opens perioperative optimization white space. |
| Enterprise Master Service Agreements | Consolidated US health systems bundle analytics procurement under contracts controlling one-third of licensed beds. |
Study Parameters
Desk research of FDA 510(k) filings, CMS Medicare reimbursement databases, and EU AI Act implementation guidance preceded structured interviews with hospital CIOs, health system procurement committee chairs, predictive analytics product managers, and GPO contracts managers. Primary fieldwork across Boston, Houston, Frankfurt, and Bangalore validated cloud migration timeline assumptions and EU AI Act compliance cost estimates. Secondary sources included hospital procurement databases, EHR vendor partnership disclosures, and hyperscaler healthcare vertical revenue segmentation. Bottom-up contract value analysis triangulated against top-down market size estimates from pharmaceutical distributor cross-sell disclosures.
Assumption sets held cloud migration velocity and HIPAA interoperability enforcement constant while varying EU AI Act implementation timing and hospital consolidation pace across geographies. Segmentation modeling spanned deployment architecture, product type complexity, end-user scale tier, and application criticality. CAGRs derived from weighted average of vendor disclosed growth rates and health system IT budget allocation surveys. Forecast inputs included EHR vendor market share trajectories and accountable care organization penetration curves by country.
Sensitivities concentrate around EU AI Act risk classification enforcement timing, Epic-Cerner environment heterogeneity resolution, and India PLI scheme extension decisions. Forecasts embed assumptions about regulatory stability and hospital capital expenditure continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare Information Exchange Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Healthcare Laboratory Informatics Market
Health Informatics
Global Non Clinical Information System Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
IHE XDS.B Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
Global Consumer Genomics Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Healthcare Application Programming Interfaces Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Healthcare BI Market
Health Informatics
Indonesia Connected Healthcare Market
Health Informatics
Global Healthcare Integration Market