
 Middle East and Africa Healthcare Archiving and Ediscovery Market | 2026-2036
Middle East and Africa Healthcare Archiving and Ediscovery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Healthcare Archiving and Ediscovery Market Foresight
Enterprise-grade compliance archiving is reorganizing procurement priorities across Middle East and Africa healthcare systems. Oracle Cerner leverages its integrated EHR-archive stack to anchor large hospital contracts in the Gulf. Siemens sustains imaging-centric dominance through PACS-to-VNA migration pathways. GE Healthcare differentiates via modality-agnostic data lakes that span radiology, cardiology, and pathology silos.
Healthcare archiving and ediscovery encompasses the systematic retention, indexing, and legally defensible retrieval of clinical records, diagnostic images, and administrative documents with metadata integrity chains and audit-trail immutability, serving both operational continuity and litigation readiness. Cloud Archiving deployment models now capture the fastest expansion as sovereign data center investments by hyperscalers resolve prior residency anxieties. AI technology applications within document classification and predictive legal hold are displacing manual review workflows, while On-Premises installations retain residual share among defense and ministry hospitals with air-gapped security mandates. Health Insurers as an end-user category represent an underdeveloped margin pool where claims dispute archiving lags provider-side sophistication.
Saudi Arabia's National Data Management Office standards, South Africa's POPIA framework, and the UAE's health data residency requirements collectively elevate encryption, access logging, and cross-border transfer protocols to baseline market entry conditions. The Saudi Food and Drug Authority and South African Health Products Regulatory Authority both intensify clinical trial record retention inspections, tightening ediscovery readiness for pharmaceutical sponsors operating across the region. Stakeholders must weigh sovereign cloud partnerships against interoperability standards as Gulf states issue divergent localization decrees.
Market Dynamics
Cloud archiving adoption is fragmenting procurement authority across Middle East and Africa healthcare systems, as hospital IT departments lose sole control over data governance to newly empowered compliance officers and legal teams demanding immutable audit trails.
Growth Catalysts
- Saudi Health Sector Transformation Program:National digitization mandates require tertiary hospitals to implement enterprise-grade archiving infrastructure with 15-year retention guarantees, creating immediate procurement pull for compliant vendors.
- POPIA enforcement waves:South Africa's Protection of Personal Information Act has triggered systematic audits of cross-border patient data flows, forcing healthcare networks to localize storage or face administrative penalties.
- AI-powered document classification:Machine learning pipelines now automate legal hold identification and privilege tagging, compressing ediscovery preparation timelines from months to days for litigation-ready providers.
Market Restraints
- Data residency fragmentation:Divergent localization decrees across Gulf Cooperation Council states prevent standardized cloud architectures, forcing vendors to maintain redundant sovereign infrastructure that elevates operational costs.
- Legacy PACS lock-in:Proprietary DICOM formats from dominant imaging vendors create technical debt that obstructs seamless migration to vendor-neutral archives without expensive middleware development.
- Specialized forensic talent scarcity:Certified ediscovery professionals with healthcare domain expertise remain concentrated in Johannesburg, Dubai, and Riyadh, constraining regional expansion for compliance-heavy deployments.
Strategic Opportunities
- Health insurer archiving gap:Claims dispute resolution infrastructure lags provider-side sophistication across the Gulf, presenting first-mover advantage for vendors offering litigation-ready retention for payor litigation.
- Clinical trial record convergence:Saudi Food and Drug Authority and South African Health Products Regulatory Authority inspections are intensifying, creating demand for unified archiving spanning research sites, CROs, and sponsor headquarters.
- Edge-to-core AI pipelines:Federated learning architectures that train models on distributed hospital data without centralizing raw records are emerging as a privacy-preserving alternative to traditional cloud concentration.
Industry Challenges
- Interoperability standard proliferation:FHIR R4, DICOMweb, and national health information exchange specifications are evolving asynchronously, forcing vendors to maintain multiple integration layers that delay implementation timelines.
- Air-gapped security mandates:Defense and ministry hospitals across the region require physically isolated infrastructure that excludes cloud-native architectures, fragmenting vendor R&D investment across incompatible deployment models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Healthcare Archiving and Ediscovery Market |
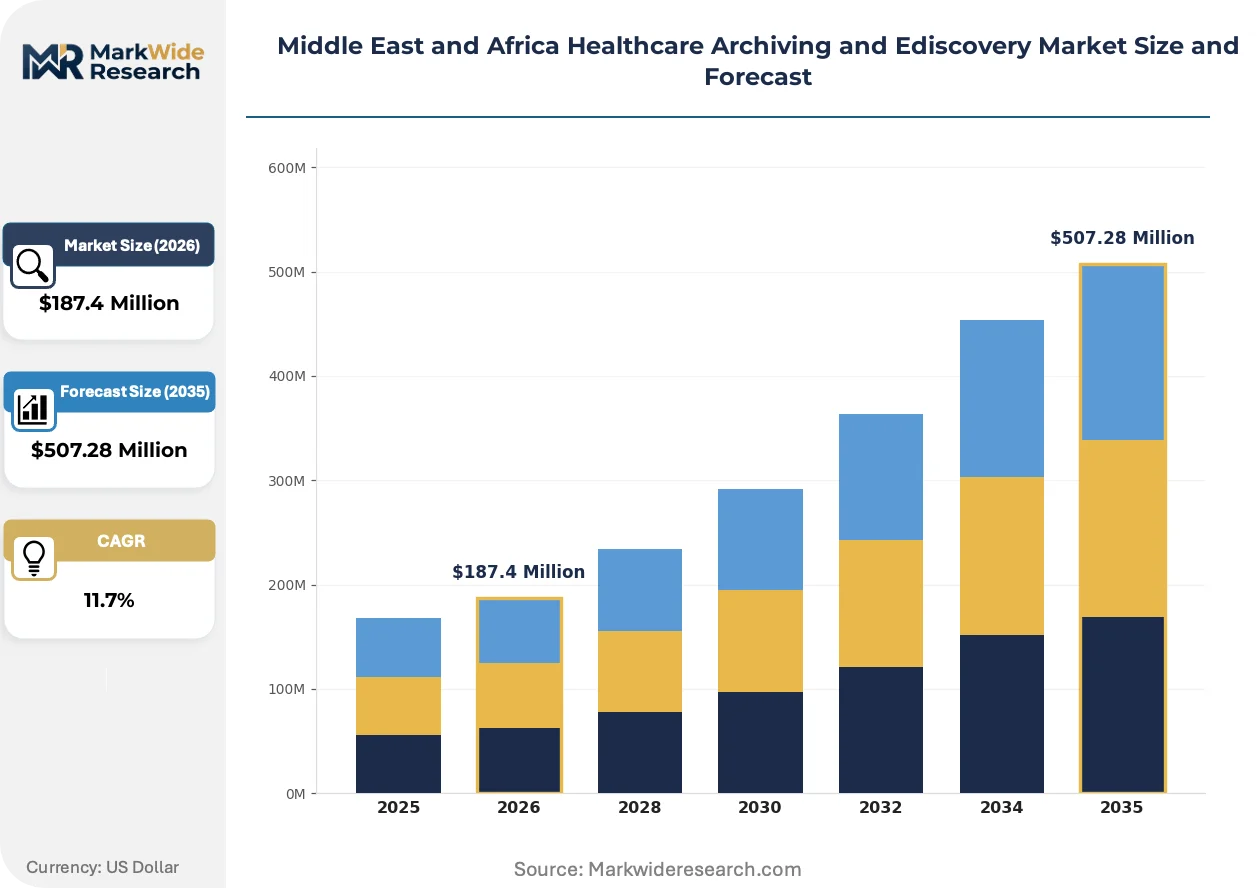
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EHR, PACS, CMS, Cloud Archiving Technology: AI, Machine Learning, Blockchain, Document Management End User: Hospitals, Clinics, Laboratories, Health Insurers Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | GE Healthcare, Siemens, Oracle Cerner, Allscripts, NextGen Healthcare, Meditech, McKesson, BridgeHead, Mach7 Technologies, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Healthcare Archiving and Ediscovery Market Shifts & Advancements
Generative AI is compressing document review workflows while sovereign cloud investments by hyperscalers are resolving data residency anxieties that previously obstructed regional expansion.
Immutable blockchain audit trails are bifurcating the compliance archiving market between premium providers offering cryptographic proof-of-existence and commodity vendors relying on conventional access logging. Saudi Arabia's National Data Management Office now recognizes distributed ledger attestations for regulatory submissions, accelerating adoption among hospitals seeking competitive differentiation in procurement tenders. This technology is compressing vendor margins for basic storage while expanding addressable spend for forensic-grade verification services.
South Africa's POPIA framework has triggered systematic cross-border data flow restrictions that reshape cloud contracting patterns across the subcontinent. Healthcare networks must now demonstrate explicit patient consent for offshore processing or maintain entirely domestic infrastructure, elevating local data center operators to strategic partnership status. Pharmaceutical sponsors running multi-site trials are responding by fragmenting archive architectures into jurisdictional silos with synchronized metadata indexing.
Subscription-based managed archiving services are displacing perpetual license models as hospital CFOs prioritize operational expenditure predictability over capital ownership. Large hospital groups in the UAE and Saudi Arabia are consolidating vendor relationships through enterprise framework agreements that bundle storage, ediscovery response, and AI-powered search into unified per-petabyte pricing. This shift is most visible among Gulf Cooperation Council health systems where transformation program funding cycles favor recurring service contracts over upfront infrastructure investment.
Middle East and Africa Healthcare Archiving and Ediscovery Market Segmentation
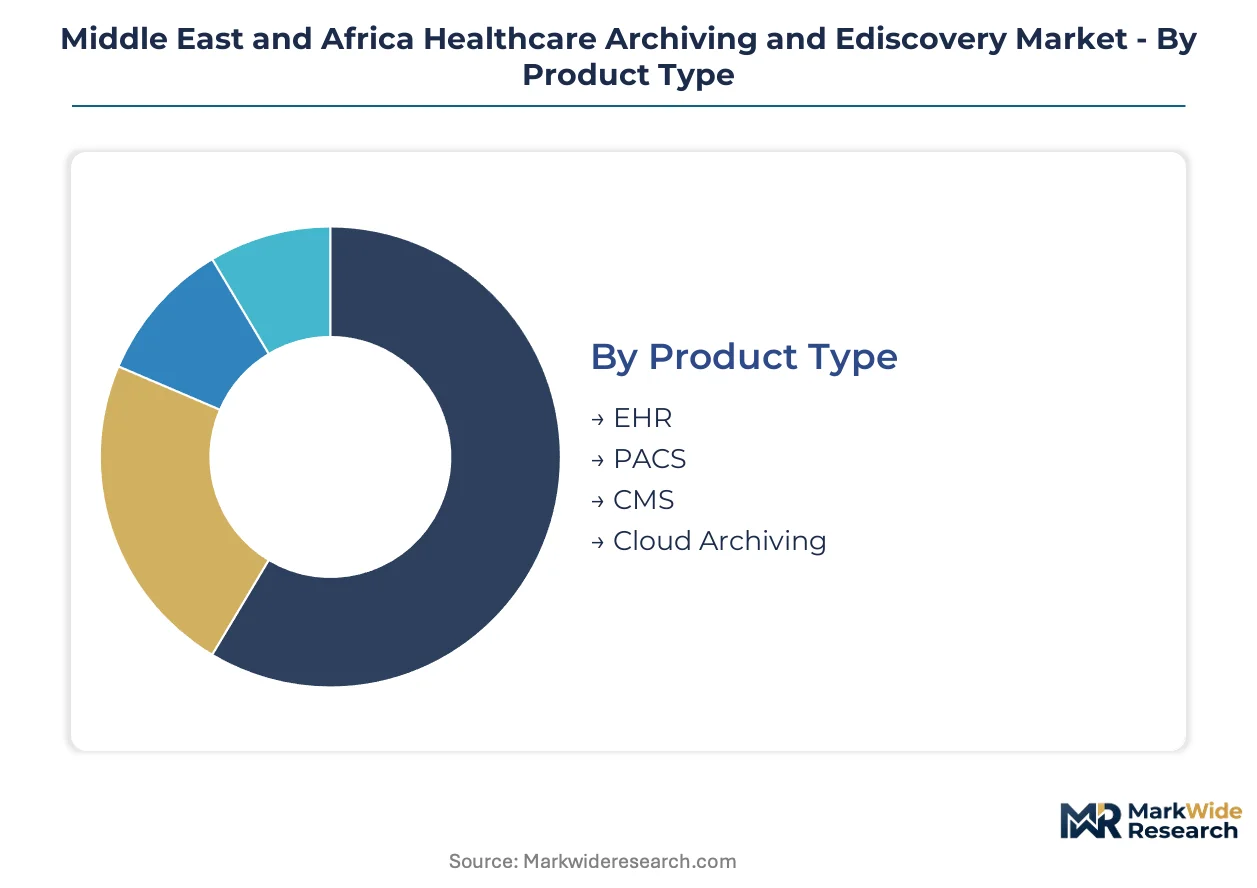
Healthcare archiving procurement patterns diverge sharply across Middle East and Africa markets, with Gulf Cooperation Council states favoring sovereign cloud infrastructure while South African networks navigate POPIA-mandated localization requirements. Segment boundaries are blurring as AI-powered classification and blockchain audit trails reshape traditional product categories.
Product Type:
Domestic procurement concentrates in Saudi Arabia and UAE hospital networks, while South African demand flows through Johannesburg health clusters with export-linked clinical trial sponsors.
- EHR:Electronic health record archiving systems integrate longitudinal patient data with immutable audit trails for litigation readiness. Saudi Health Sector Transformation Program corridors drive enterprise contract consolidation among tertiary hospital networks seeking 15-year retention guarantees.
- PACS:Picture archiving and communication systems manage diagnostic imaging workflows with DICOM metadata integrity. Migration pathways from legacy proprietary formats to vendor-neutral archives dominate procurement conversations in Dubai and Riyadh medical districts.
- CMS:Content management systems govern administrative and operational document retention with workflow automation.
- Cloud Archiving:Scalable storage architectures with sovereign data center residency resolve prior cross-border transfer anxieties.
EHR commands the established base. The steepest expansion runs through Cloud Archiving.
Technology:
Cost tier stratification separates premium forensic-grade verification from commodity storage, with AI and blockchain commanding implementation premiums against legacy document management.
- AI:Machine learning pipelines automate legal hold identification, privilege tagging, and predictive document classification. Claims dispute resolution compression from months to days drives payor-side procurement in Abu Dhabi and Cape Town insurance clusters.
- Machine Learning:Supervised learning models trained on regional healthcare terminology improve extraction accuracy for Arabic and multilingual clinical records.
- Blockchain:Distributed ledger attestations provide cryptographic proof-of-existence for regulatory submissions. Saudi National Data Management Office recognition accelerates hospital procurement tenders seeking competitive differentiation.
- Document Management:Conventional indexing and retrieval systems retain residual share among budget-constrained clinic networks.
Document Management retains volume leadership. AI is climbing the fastest.
End User:
Customer type maturity varies dramatically, with hospital sophistication outpacing health insurer archiving readiness across Gulf markets.
- Hospitals:Tertiary medical centers require enterprise-grade infrastructure spanning clinical, administrative, and research data domains. Saudi Arabia's transformation program mandates create immediate procurement pull for compliant vendors with sovereign cloud partnerships.
- Clinics:Ambulatory settings prioritize lightweight, subscription-based solutions with minimal IT overhead.
- Laboratories:Diagnostic testing networks demand LIS-integrated archiving with specimen chain-of-custody documentation.
- Health Insurers:Payor organizations lag provider-side sophistication, presenting first-mover opportunity for litigation-ready claims dispute retention.
Hospitals command the established base. Health Insurers represent the steepest expansion trajectory.
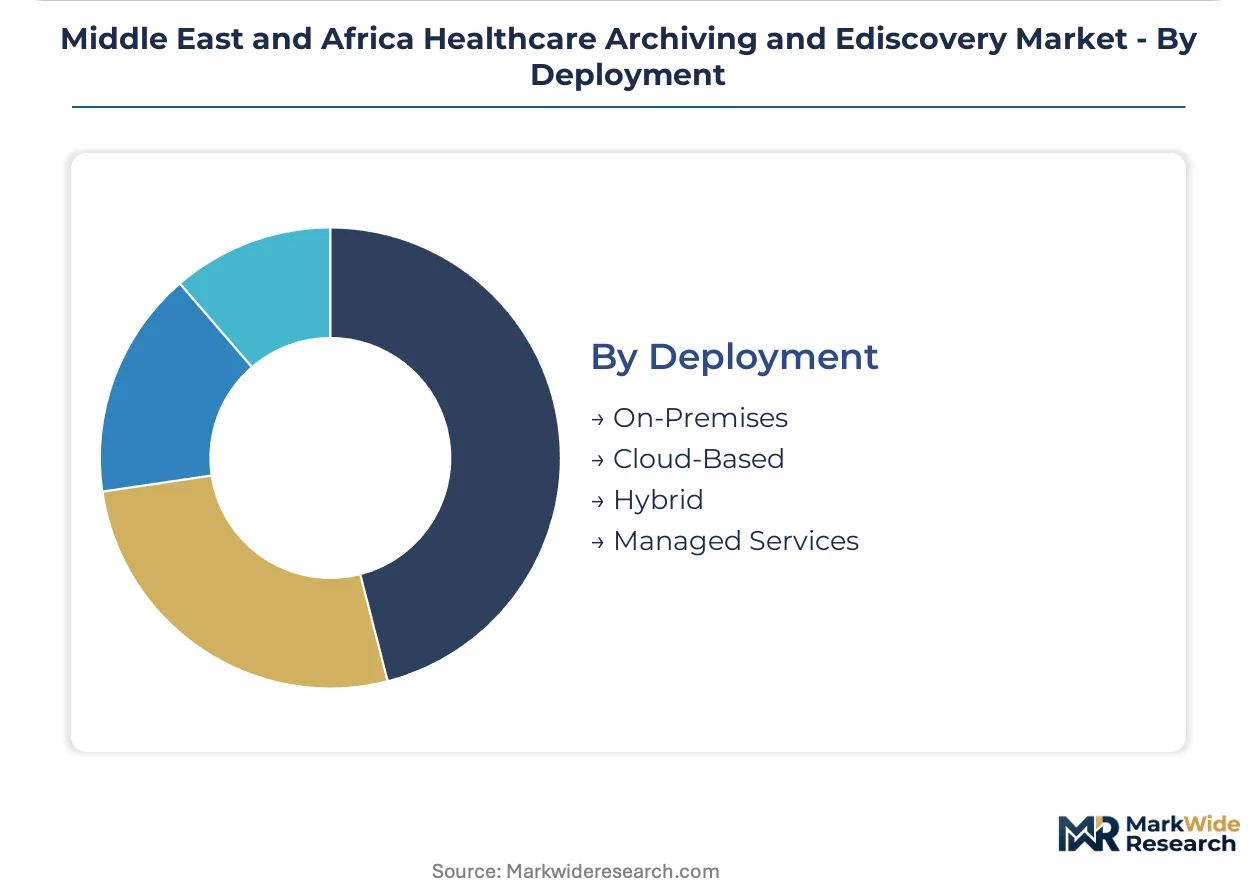
Deployment:
Volume concentration shifts toward recurring service contracts as CFOs prioritize operational expenditure predictability over capital ownership.
- Cloud-Based:Hyperscaler sovereign data center investments resolve residency anxieties that previously obstructed regional expansion. UAE and Saudi framework agreements bundle storage, ediscovery response, and AI search into unified per-petabyte pricing.
- Managed Services:Third-party operational responsibility for retention, indexing, and legal hold response appeals to mid-tier hospital groups lacking specialized forensic talent.
- On-Premises:Physically isolated infrastructure satisfies air-gapped security mandates from defense and ministry hospitals across the region.
- Hybrid:Split architectures balance sensitive record local control with cost-optimized bulk storage in sovereign cloud.
On-Premises retains legacy dominance. Cloud-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor infrastructure investments concentrate in sovereign cloud partnerships across Gulf Cooperation Council states, while South African localization requirements reshape subcontinental procurement patterns. Healthcare networks in Riyadh, Dubai, and Johannesburg medical corridors drive demand for compliant archiving architectures.
Saudi Arabia
Tertiary hospital digitization mandates under the Health Sector Transformation Program create immediate procurement pull for enterprise-grade retention infrastructure. The National Data Management Office standards elevate encryption and cross-border transfer protocols to baseline market entry conditions. King Faisal Specialist Hospital and Research Centre anchors demand in Riyadh's medical district for 15-year guaranteed archiving solutions.
United Arab Emirates
Dubai Health Authority and MOHAP health data residency requirements accelerate sovereign cloud adoption among private hospital groups. Federal localization decrees prevent standardized architectures across emirates, forcing redundant infrastructure investments. Dubai Healthcare City clusters specialized providers seeking litigation-ready ediscovery capabilities for medical tourism liability protection.
South Africa
POPIA enforcement waves trigger systematic audits of cross-border patient data flows, compelling healthcare networks to localize storage or face administrative penalties. The Protection of Personal Information Act shapes explicit consent requirements for offshore processing. Johannesburg health clusters dominate procurement volume, with Cape Town insurance corridors emerging for claims dispute archiving.
Israel
Defense and ministry hospital air-gapped security mandates sustain demand for physically isolated on-premises infrastructure. National cybersecurity directives restrict cloud-native architectures for sensitive medical records. Tel Aviv medical technology corridors concentrate specialized vendors serving both domestic hospitals and export-linked clinical trial sponsors.
Egypt
Public hospital digitization initiatives under national health insurance expansion create foundational demand for basic document management systems. The country's pharmaceutical regulator intensifies clinical trial record retention inspections for multinational sponsors operating across North Africa. Cairo-Giza medical districts concentrate procurement activity among university hospital networks.
Middle East and Africa Healthcare Archiving and Ediscovery Market Competitive Landscape
Concentration sits with integrated health IT conglomerates that bundle EHR-archive stacks into enterprise hospital contracts. The vendor landscape separates into three strategic archetypes: imaging-centric equipment manufacturers extending into vendor-neutral archives, cloud-native software specialists offering AI-powered classification, and legacy document management providers defending installed base relationships. Competitive moves center on sovereign cloud partnership formations and M&A activity targeting regional compliance expertise.
Within the integrated health IT tier, Oracle Cerner and GE Healthcare exemplify contrasting approaches to Gulf market penetration. Oracle Cerner anchors large hospital contracts through unified EHR-archive infrastructure, while GE Healthcare occupies a position emphasizing modality-agnostic data lakes across radiology and cardiology silos. Siemens represents the imaging equipment archetype, sustaining dominance through PACS-to-VNA migration pathways that leverage existing modality relationships.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens |
| Oracle Cerner |
| Allscripts |
| NextGen Healthcare |
| Meditech |
| McKesson |
| BridgeHead |
| Mach7 Technologies |
| Others |
Supply & Pricing Matrix
Enterprise framework agreements that bundle storage, ediscovery response, and AI-powered search into unified per-petabyte pricing lock in supply access for Gulf hospital networks while compressing vendor margins through operational expenditure predictability. Saudi Arabia's Health Sector Transformation Program funding cycles favor these recurring service contracts over upfront infrastructure investment, reshaping procurement authority across Riyadh and Dubai medical corridors.
Pricing Analysis
POPIA dictates the pricing tier structure across South African healthcare networks, forcing explicit localization premiums for domestic data center infrastructure against offshore alternatives. Three-tier pricing structure across premium, standard, and economy levels separates forensic-grade blockchain verification from commodity storage and basic document management. Cost compression in the economy tier is intensifying because hyperscaler sovereign cloud investments resolve prior residency anxieties. Mid-tier hospital groups lacking specialized forensic talent exhibit the highest price sensitivity, while tertiary centers under transformation program mandates prioritize compliance guarantees over unit cost.
Supply Chain Analysis
Extended lead times for certified ediscovery professionals concentrate inventory risk in Johannesburg, Dubai, and Riyadh talent clusters. Hardware components draw from Taiwan semiconductor fabricators, German imaging equipment manufacturers, and US enterprise software providers. Single-source vulnerability sits with proprietary DICOM format dependencies that obstruct seamless migration to vendor-neutral archives. Distribution runs through sovereign cloud partnerships with hyperscalers rather than traditional channel partners, elevating local data center operators to strategic status across Gulf Cooperation Council states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa healthcare archiving market is recovering from pandemic-delayed infrastructure investments as Saudi transformation program disbursements accelerate procurement cycles. Digitization mandates create immediate demand pull that vendors can capture through compliance-first positioning.
For Market Incumbents: Secure sovereign cloud partnerships with hyperscalers before localization decrees harden across remaining Gulf states. Deepen vertical integration into AI-powered document classification to defend against cloud-native software specialists. Anchor large hospital contracts through unified EHR-archive infrastructure that satisfies National Data Management Office encryption standards. For New Entrants and Emerging Players: Lead with health insurer claims dispute archiving where payor-side sophistication lags provider infrastructure across Abu Dhabi and Cape Town corridors. Target clinical trial record convergence spanning research sites, CROs, and sponsor headquarters under intensifying Saudi Food and Drug Authority inspections. Pursue subscription-based managed services positioning that appeals to mid-tier hospital groups prioritizing operational expenditure predictability. For Investors and Strategic Acquirers: Regional compliance expertise boutiques with POPIA and National Data Management Office specialization represent the most defensible acquisition targets. Long-term viability rests on federated learning architectures that preserve privacy without raw record centralization. Watch for sovereign cloud partnership announcements from hyperscalers as the inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Resolves data residency anxieties under Saudi National Data Management Office standards. |
| AI-Powered Classification Development | Compresses ediscovery preparation timelines from months to days for litigation-ready providers. |
| Blockchain Audit Trail Integration | Provides cryptographic proof-of-existence recognized by Saudi regulatory submissions. |
| Health Insurer Vertical Expansion | Captures underdeveloped margin pool in claims dispute resolution infrastructure. |
| Clinical Trial Record Convergence | Addresses intensifying inspections by Saudi Food and Drug Authority and South African Health Products Regulatory Authority. |
Research Methodology
Operator-level perspectives from hospital CIOs, compliance officers, legal team leads, and health insurer procurement managers anchored the qualitative base for this study. Primary interviews combined with secondary validation from hospital procurement databases, GPO contracts, CMS Medicare data, and regulatory filing repositories. Bottom-up demand modeling across deployment models, organization size, and regional adoption patterns triangulated against top-down market sizing.
Sensitivity analysis tested forecast robustness across varying sovereign cloud investment timelines and AI adoption rates throughout the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and deployment architecture alongside health data residency requirement patterns. CAGRs were derived from fitted growth curves applied to base year estimates, with inputs from health sector transformation program funding disbursement schedules and POPIA enforcement intensity indicators.
Forecasts assume regulatory continuity in Saudi National Data Management Office standards, South Africa's POPIA framework, and UAE health data residency requirements; material policy shifts would require re-modeling. Specific risks include divergent localization decrees fragmenting cloud architectures and air-gapped security mandates excluding cloud-native solutions for defense hospitals. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
Global E-Health Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Vocal Biomarkers Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
North America Laboratory Information System Market
Health Informatics
Healthcare Natural Language Processing Market
Health Informatics
Global Laboratory Information System Market