
 AI in Epidemiology Market | 2026-2036
AI in Epidemiology Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Epidemiology Market Insights
Cloud computing capacity in North American data center clusters is realigning how epidemiological AI platforms deploy at scale. Microsoft Corporation leverages its Azure infrastructure to anchor public health analytics partnerships across multiple government tiers. IBM Corporation competes through specialized disease surveillance architectures that integrate with legacy hospital systems. Intel Corporation differentiates via hardware-optimized inference engines designed for real-time outbreak detection workloads.
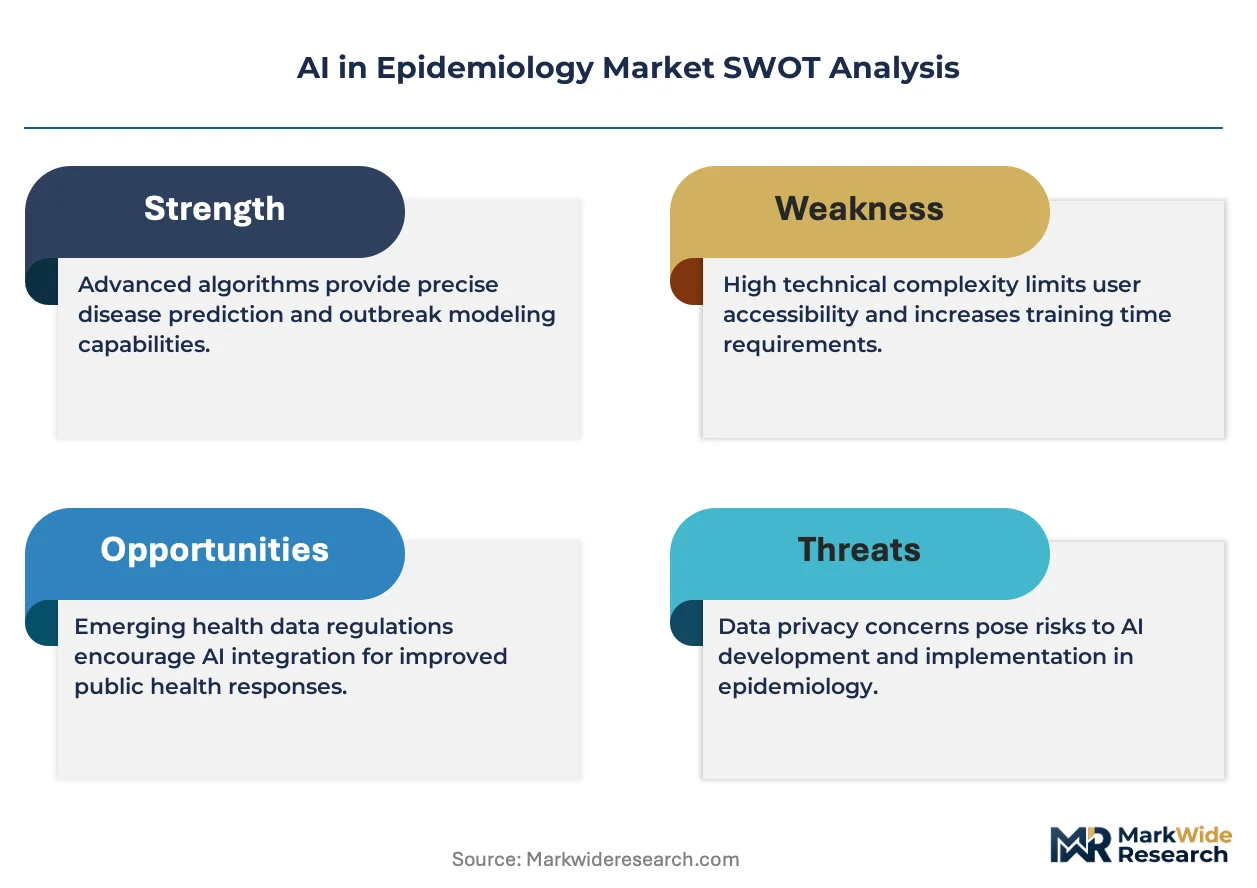
AI in epidemiology denotes the application of computational algorithms and statistical models to analyze population-level health data, identify disease transmission patterns, and forecast epidemic trajectories using inputs ranging from electronic health records to genomic sequencing data and environmental sensors. Predictive modeling software commands the largest revenue share as health agencies prioritize forecast accuracy for resource allocation, while natural language processing is the fastest-expanding technology segment as unstructured clinical notes and social media streams become critical epidemic signals. Public health agencies represent the most concentrated end-user pool, though pharmaceutical companies are emerging as high-margin accounts for clinical trial site selection and pharmacovigilance applications.
The FDA regulates AI-based epidemiological tools through its Software as a Medical Device framework, while the CDC's data interoperability mandates shape how platforms exchange syndromic surveillance information across jurisdictions. HIPAA compliance requirements constrain how patient-level data trains predictive models, creating architectural trade-offs between accuracy and privacy preservation. Stakeholders must monitor how emerging state-level AI governance laws fragment the regulatory landscape and force platform vendors to maintain multiple compliance configurations.
Market Dynamics
Federal pandemic preparedness infrastructure in the United States is accelerating procurement cycles for AI-driven surveillance platforms, compressing vendor qualification timelines from years to months.
Growth Catalysts
- Syndromic Surveillance Mandates:The CDC's data interoperability requirements are forcing state health departments to modernize legacy reporting systems, creating immediate upgrade demand.
- Federated Learning Architectures:Privacy-preserving model training techniques are expanding addressable data pools beyond HIPAA-constrained environments.
- Genomic Sequencing Integration:Public health laboratories are embedding pathogen genomic data into real-time transmission models, sharpening outbreak origin attribution.
Market Restraints
- Specialized Talent Scarcity:The intersection of epidemiological domain expertise and machine learning engineering remains severely underpopulated, inflating compensation costs.
- Cloud Concentration Risk:Dominant hyperscaler infrastructure creates single-point-of-failure exposure for mission-critical outbreak detection workloads.
- FDA Validation Friction:The Software as a Medical Device framework imposes iterative clinical evidence requirements that extend commercialization timelines.
Strategic Opportunities
- Pharmaceutical Site Selection:Clinical trial sponsors are purchasing predictive infection-risk models to optimize geographic enrollment strategies.
- EU AI Act Alignment:Early compliance with European high-risk AI system requirements opens procurement pathways for WHO-affiliated agencies.
- Edge Deployment Convergence:On-premise inference hardware combined with lightweight model compression is enabling hospital-network localized outbreak detection.
Industry Challenges
- Interoperability Tax:Each new jurisdiction's data format requirements force expensive connector development and maintenance.
- Model Drift Management:Pathogen behavioral evolution degrades predictive accuracy faster than retraining cycles can accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Epidemiology Market |
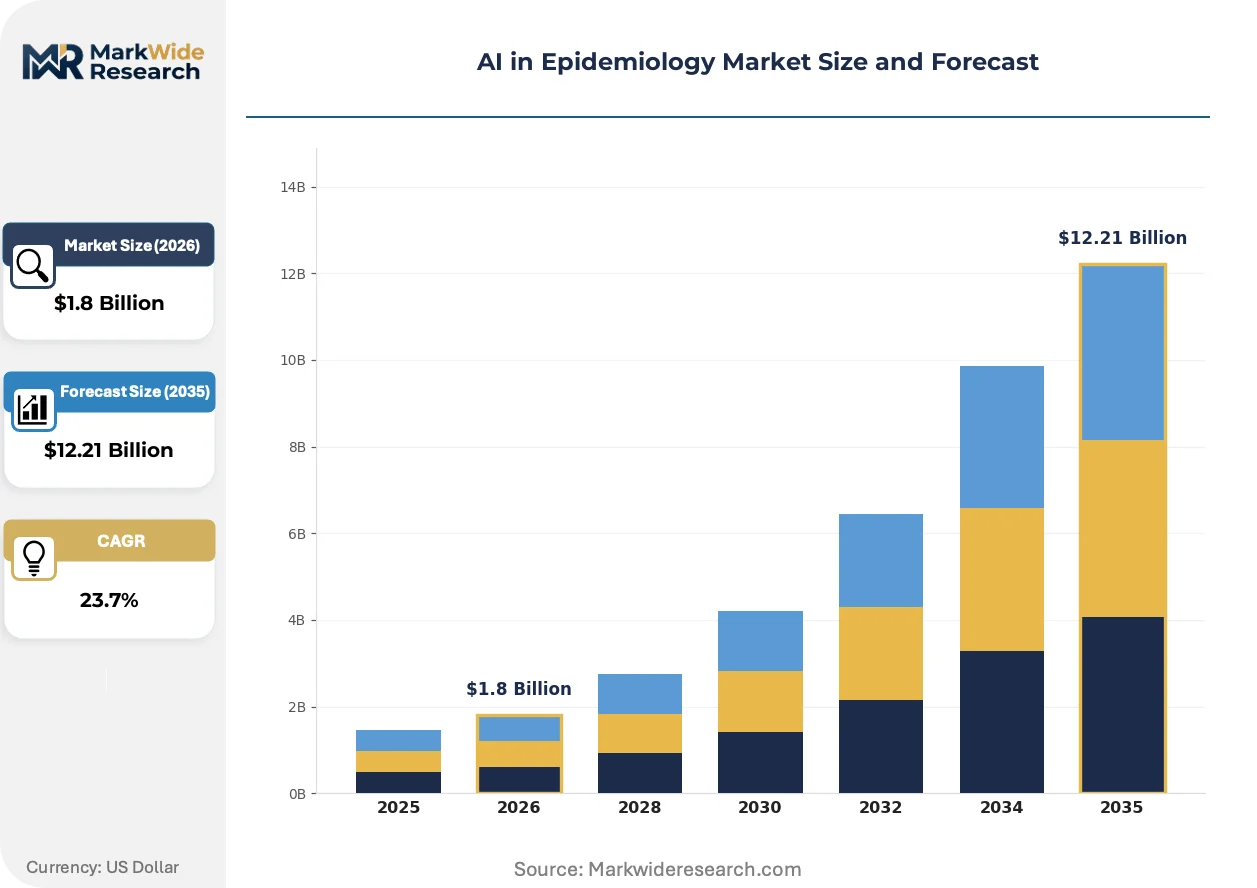
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Analysis Tools, Predictive Modeling Software, Visualization Platforms, Reporting Solutions Technology: Machine Learning, Natural Language Processing, Deep Learning, Data Mining End User: Public Health Agencies, Research Institutions, Hospitals, Pharmaceutical Companies Application: Surveillance, Disease Prediction, Outbreak Analysis, Health Trend Monitoring |
| Companies Covered | Microsoft Corporation, Cognizant Technology Solutions Corporation, Cerner Corporation, Alphabet Inc, Epic Systems Corporation, Intel Corporation, Siemens Healthineers, IBM Corporation, SAS Institute, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Epidemiology Market Trends and Innovations
Foundation models trained on multimodal health data are compressing development timelines for specialized epidemiological applications, shifting competitive advantage from algorithmic novelty to data access and integration depth.
Transformer-based architectures for genomic sequence analysis are integrating protein structure prediction with transmission dynamics modeling. Research consortia across the United Kingdom, Singapore, and Switzerland are deploying these unified pipelines for variant emergence forecasting. The structural consequence is collapsing the latency between sequence identification and public risk assessment from weeks to days.
The FDA's evolving enforcement discretion for AI-based outbreak detection tools is creating regulatory clarity gaps that vendors must navigate through pre-submission pathways. This policy trajectory is segmenting the vendor base between those pursuing formal device authorization and those operating under public health emergency exemptions. Hospital systems in the United States are favoring contracted vendors with established quality management systems.
Public health agencies are consolidating procurement through multi-year enterprise agreements rather than project-based contracts, shifting vendor relationships from transactional software licensing to sustained performance partnerships. This pattern concentrates account control among established platforms and raises barriers for emerging entrants. State-level health departments in California, Texas, and New York are pioneering these consolidated buying frameworks.
AI in Epidemiology Market Segmentation
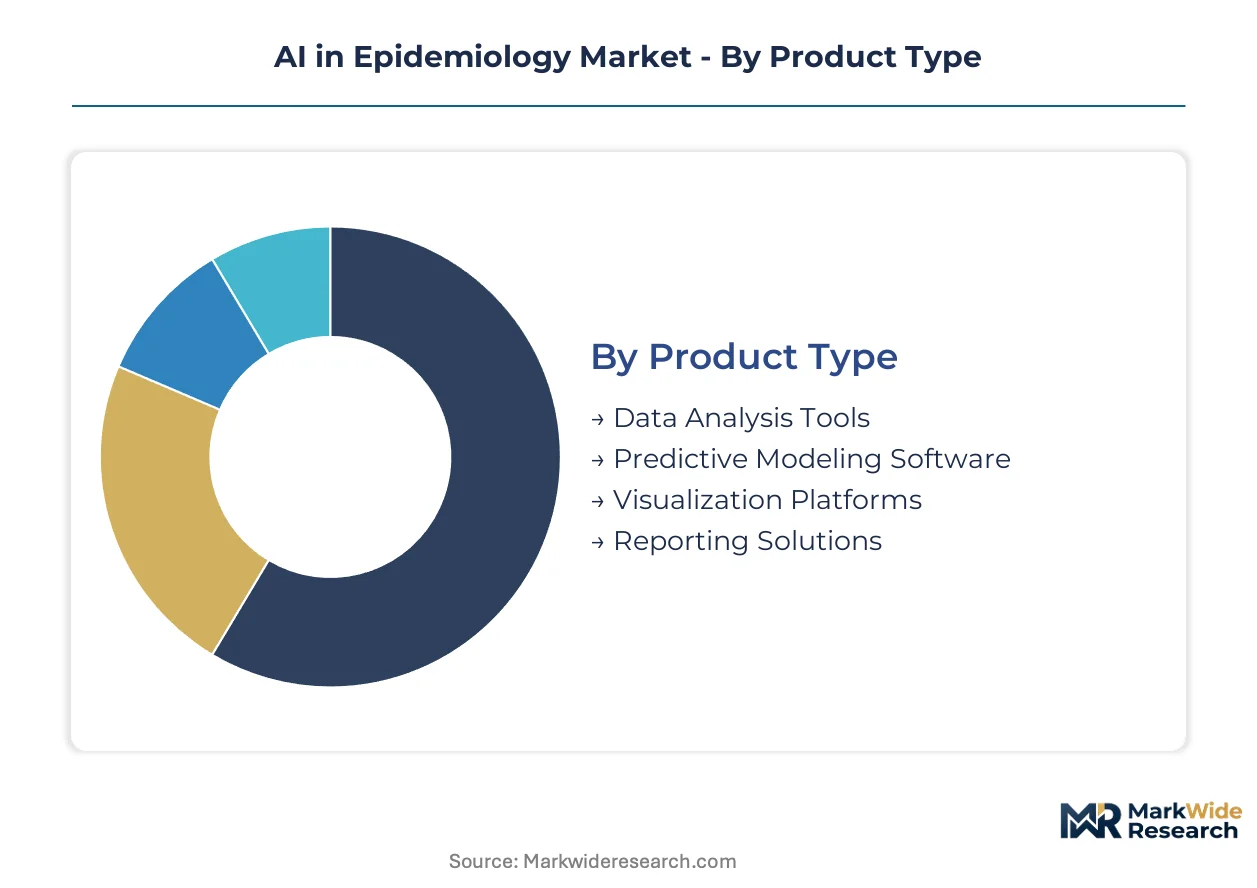
Segmentation in epidemiological AI reveals how procurement priorities diverge across institutional budgets, technical sophistication, and regulatory exposure. Vendors configure platform architectures differently for each category, creating distinct margin profiles and renewal dynamics.
Product Type:
Standardized modules dominate low-budget deployments, while bespoke integrations command premium pricing in multi-agency federations.
- Predictive Modeling Software:Statistical engines process electronic health records, genomic sequences, and environmental sensor feeds to forecast epidemic trajectories. Public health agencies in the United States concentrate procurement here, driven by CDC mandates for forecast-driven resource allocation during surge events.
- Data Analysis Tools:Platforms aggregate syndromic surveillance streams from emergency departments, urgent care networks, and laboratory information systems. Research institutions across the United Kingdom and Singapore deploy these for population-level transmission studies where algorithmic transparency outweighs predictive precision.
- Visualization Platforms:Dashboard systems render geospatial outbreak patterns for command-center decision support. Hospitals in California and Texas favor these for localized situational awareness.
- Reporting Solutions:Automated compliance generators structure data for regulatory submissions and inter-jurisdictional information exchange. State health departments purchase these to satisfy CDC interoperability requirements.
Most installed capacity flows through Predictive Modeling Software. Expansion is steepest in Data Analysis Tools.
Technology:
Proven techniques absorb the bulk of current spending, while experimental architectures attract pilot funding from innovation-forward agencies.
- Natural Language Processing:Algorithms extract epidemic signals from unstructured clinical notes, social media streams, and news corpora. The technology is expanding most quickly as public health agencies in Switzerland and the United Kingdom integrate these feeds into real-time surveillance pipelines.
- Machine Learning:Supervised classification and regression methods identify anomalous disease patterns from structured health data. Hospitals across the United States deploy these for automated case detection in emergency department triage workflows.
- Deep Learning:Neural architectures process high-dimensional genomic and imaging data for variant characterization. Research consortia in Singapore pioneer these applications for pathogen evolution forecasting.
- Data Mining:Pattern discovery techniques surface hidden correlations across disparate health databases. Pharmaceutical companies apply these for pharmacovigilance signal detection in post-market surveillance.
Machine Learning carries the largest deployment base. Natural Language Processing is gaining share fastest among new procurements.
End User:
Budget scale and procurement cycle length separate institutional buyers, with federal agencies operating on multi-year horizons and hospital systems on annual capital cycles.
- Public Health Agencies:National and subnational health departments operate syndromic surveillance networks and coordinate outbreak response. The United States CDC and its state-level counterparts represent the most concentrated demand pool, with pandemic preparedness infrastructure accelerating platform adoption.
- Pharmaceutical Companies:Clinical trial sponsors purchase infection-risk models for geographic site selection and patient enrollment optimization. These accounts generate premium margins due to proprietary data integration requirements.
- Research Institutions:Academic medical centers and public health schools deploy AI platforms for population studies and methodological development. Consortia across the United Kingdom, Singapore, and Switzerland lead in genomic-epidemiological integration.
- Hospitals:Health systems implement localized outbreak detection for nosocomial infection control and emergency department surge planning. California and New York hospital networks are consolidating procurement through shared services organizations.
Public Health Agencies anchor current revenue. Pharmaceutical Companies are expanding most quickly as clinical trial complexity intensifies.
Application:
Reactive capabilities retain larger installed bases, while predictive applications capture disproportionate new investment.
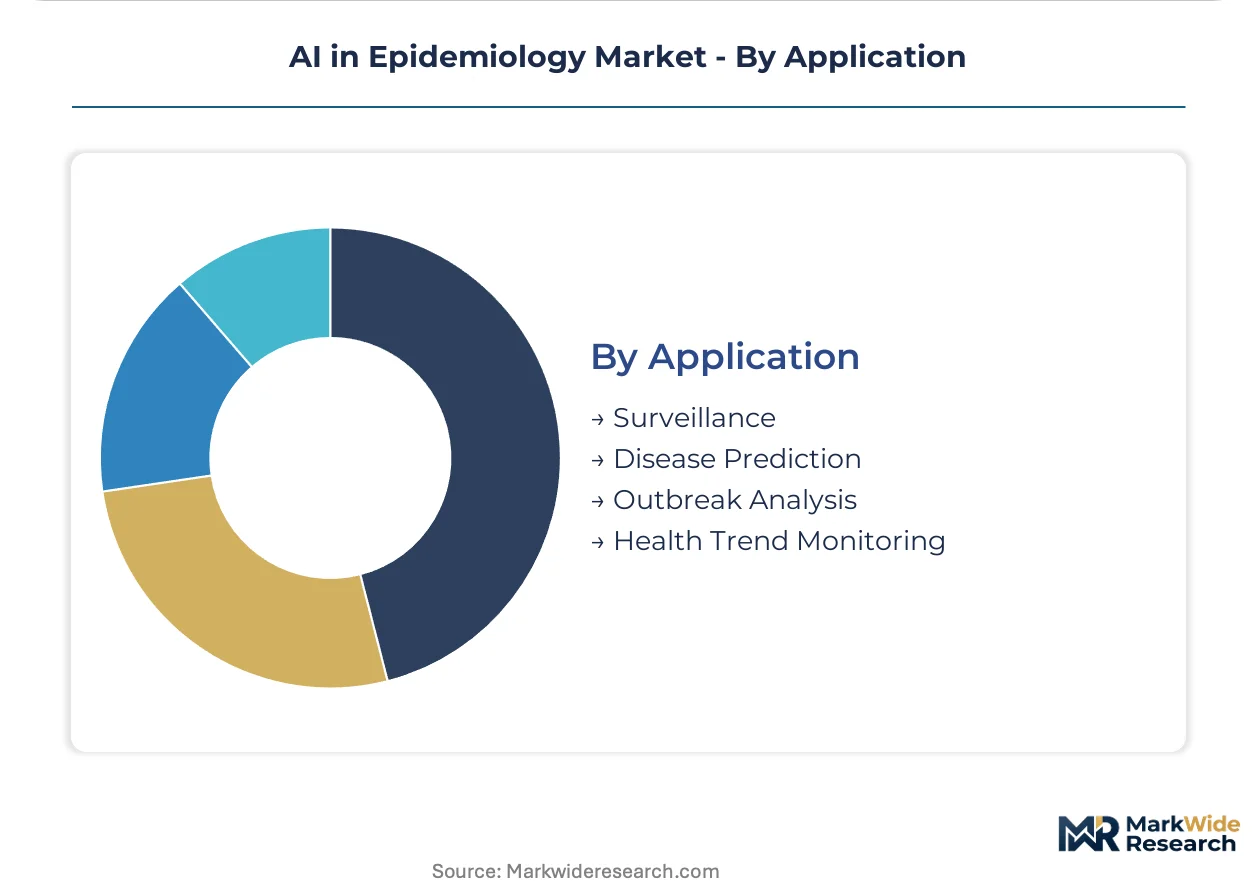
- Surveillance:Continuous monitoring systems detect anomalous health event patterns from multi-source data feeds. Public health agencies in the United States deploy these under CDC data interoperability mandates, with California, Texas, and New York pioneering consolidated enterprise agreements.
- Disease Prediction:Forecasting models project epidemic trajectories to inform resource pre-positioning and intervention timing. Federal pandemic preparedness programs are accelerating procurement cycles for these capabilities from years to months.
- Outbreak Analysis:Retrospective and real-time investigation tools trace transmission chains and identify index cases. Research institutions combine these with genomic sequencing for variant emergence attribution.
- Health Trend Monitoring:Longitudinal analysis platforms track chronic disease burden and behavioral risk factor evolution. Hospital systems use these for population health management in accountable care arrangements.
Surveillance absorbs the largest share of deployed systems. Disease Prediction is climbing the fastest as forecast accuracy becomes a procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping AI epidemiology deployment as vendors migrate development operations toward jurisdictions with clearer AI governance frameworks and streamlined health data access protocols. Cost-of-compliance gaps between the United States and European markets are accelerating platform localization strategies.
United States
Federal pandemic preparedness infrastructure and CDC syndromic surveillance mandates drive concentrated procurement demand. The FDA's Software as a Medical Device framework imposes iterative clinical evidence requirements that extend commercialization timelines. California, Texas, and New York state health departments are pioneering multi-year enterprise agreements that consolidate vendor relationships.
United Kingdom
Research consortia integrating genomic sequencing with transmission dynamics modeling attract significant public investment. NHS data interoperability standards shape how platforms exchange patient-level information across trusts. London and Oxford anchor development clusters where academic medical centers partner with AI vendors on population-level transmission studies.
Singapore
National health agencies deploy unified pipelines for variant emergence forecasting with compressed latency between sequence identification and risk assessment. The country's national pharmaceutical regulator maintains alignment with WHO prequalification standards. Biopolis research precinct hosts consortia pioneering transformer-based architectures for genomic sequence analysis.
Switzerland
Swissmedic's regulatory clarity for AI-based medical software attracts vendors seeking European market entry pathways. Federal public health offices integrate unstructured clinical notes and social media streams into real-time surveillance pipelines. Basel and Zurich concentrate pharmaceutical company demand for clinical trial site selection and pharmacovigilance applications.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia implement localized outbreak detection for nosocomial infection control and emergency department surge planning. The EU AI Act's high-risk system requirements are forcing early compliance investments among platform vendors. Berlin health authorities are consolidating procurement through shared services organizations.
AI in Epidemiology Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized disease surveillance architectures and edge deployment convergence. The vendor base stratifies across three maturity tiers: hyperscale cloud providers anchoring public-private partnerships, specialized health IT vendors integrating with legacy hospital systems, and research-focused consortia developing genomic-epidemiological pipelines. Dominant competitive moves include strategic partnerships with public health agencies and portfolio diversification into pharmaceutical applications.
Within the hyperscale infrastructure tier, Microsoft Corporation and Alphabet Inc exemplify platform providers leveraging cloud capacity to anchor government analytics partnerships. IBM Corporation and Intel Corporation occupy positions among specialized technology vendors optimizing hardware and software stacks for real-time outbreak detection workloads. Epic Systems Corporation and Cerner Corporation represent health IT incumbents integrating AI modules into established electronic health record deployments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cognizant Technology Solutions Corporation |
| Cerner Corporation |
| Alphabet Inc |
| Epic Systems Corporation |
| Intel Corporation |
| Siemens Healthineers |
| IBM Corporation |
| SAS Institute |
| Others |
Pricing and Supply Chain Analysis
Performance-tier divergence between FDA-validated predictive platforms and unvalidated analytics tools manifests in both subscription pricing and cloud infrastructure sourcing. Premium tiers anchor on Azure and AWS government cloud regions with FedRAMP authorization, while budget deployments run through commercial hyperscaler instances without sovereign data guarantees.
Pricing Analysis
Distributor margins for health IT channel partners compress as direct enterprise sales to state health departments expand. SaaS-tiered subscription models dominate, with price differentiation driven by FDA Software as a Medical Device validation status and data residency certification. Pricing pressure stems from federal pandemic preparedness grants standardizing procurement budgets. Public health agencies exhibit highest price sensitivity; pharmaceutical companies show lowest.
Supply Chain Analysis
Regional distribution centers for AI inference hardware cluster in Northern Virginia, Frankfurt, and Singapore to minimize latency for real-time outbreak detection. Cloud compute capacity draws from United States, Ireland, and Singapore data center networks. GPU and specialized AI accelerator dependencies create single-source vulnerability through NVIDIA supply concentration. Distribution runs through hyperscaler marketplaces and direct OEM contracts with hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI in epidemiology functions as a stable compounder, with CDC syndromic surveillance mandates and pandemic preparedness infrastructure providing durable demand visibility across budget cycles.
For Market Incumbents: Deepen integration with legacy electronic health record systems to raise switching costs for hospital network customers. Expand FedRAMP-authorized cloud regions to capture state health department procurement. Counter emerging entrant threat through exclusive data partnerships with CDC and WHO-affiliated agencies. Prioritize R&D investment in federated learning architectures that preserve HIPAA compliance. For New Entrants and Emerging Players: Begin with pharmaceutical clinical trial site selection applications, where proprietary data integration commands premium pricing and regulatory barriers are lower than FDA device pathways. Target mid-tier hospital systems in Texas and Florida that lack dedicated epidemiology IT staff. Pursue channel partnerships with health IT distributors rather than direct enterprise sales. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized talent scarcity inflates compensation costs beyond independent vendor sustainability. Frame long-term viability around platform data network effects rather than algorithmic differentiation. Target acquisition archetype: genomic-epidemiological pipeline developers with established research consortia relationships. Watch for FDA enforcement discretion clarity as inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Unlocks procurement eligibility for CDC-funded state health department contracts. |
| Strategic Partnership with Public Health Agency | Secures multi-year enterprise agreement revenue visibility and reference credibility. |
| Acquisition of Specialist Genomic Analytics Firm | Accelerates variant emergence forecasting capabilities for research consortia demand. |
| Platform Integration with Epic/Cerner EHR Systems | Captures hospital network outbreak detection workflows through embedded deployment. |
| Geographic Expansion to EU AI Act-Compliant Regions | Opens WHO-affiliated agency procurement pathways in Switzerland and Germany. |
Research Methodology
Bottom-up public health agency procurement modeling reconciled against top-down hyperscaler cloud capacity tracking forms the analytical core. Primary interviews with state epidemiologists, CDC program officers, hospital IT procurement directors, and AI platform product managers combined with secondary validation from FDA 510(k) filings, CDC surveillance system documentation, and hospital GPO contract databases. Triangulation across stakeholder inputs and published regulatory guidance ensures segmentation integrity.
Input-output matrices map technology adoption curves against jurisdictional budget cycles across the projection horizon. Segmentation dimensions include product type, technology architecture, end-user institution class, and application workflow. CAGRs derive from weighted scenario analysis incorporating federal funding trajectory assumptions and regulatory timeline uncertainty. Forecast inputs include pandemic preparedness appropriations and genomic sequencing infrastructure deployment rates.
Several conditions sit outside the modeled scope, including emergent pathogen characteristics that outpace model retraining cycles and state-level AI governance fragmentation that multiplies compliance configurations. Forecasts reflect documented assumptions about CDC mandate continuity and hyperscaler pricing stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
IHE XDS.B Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
Cat Allergy in Humans Market
Health Informatics
Allergy Care Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
EHR EMR Market
Health Informatics
Vocal Biomarkers Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Global E-Health Market
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
Global Healthcare EDI Market