
 Global in Silico Clinical Trials Market | 2026-2036
Global in Silico Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Global in Silico Clinical Trials Market Foresight
ISO 14155 certification for clinical investigation of medical devices is collapsing the barrier between traditional and simulated trial pathways, forcing vendors to demonstrate validated computational models. Certara, Inc. leverages decades of pharmacokinetic modeling expertise to anchor its position across regulatory submissions. Insilico Medicine, Inc. competes through generative AI platforms that specialize in de novo molecule design with embedded toxicity prediction. Dassault Systemes SE extends its dominance from engineering simulation into biopharma through the BIOVIA portfolio, controlling a unique cross-industry data architecture.
In silico clinical trials deploy computational models, physics-based simulations, and machine learning algorithms to predict drug behavior, patient response, and safety outcomes without physical human subjects, typically operating through virtual patient cohorts with parameterized physiological variables to generate evidence for regulatory decision-making. Physics-based modeling and machine learning currently occupy the largest technology segments, though agent-based modeling is recording the fastest expansion as immunology and oncology applications demand individual-level heterogeneity capture. Drug discovery and toxicity assessment lead application revenue, while dose optimization is emerging as a high-margin specialty where failure-to-optimize costs in late-phase trials create acute sponsor willingness-to-pay.
The FDA's Model-Informed Drug Development program and EMA's qualification opinion pathway for novel methodologies are reshaping how sponsors structure regulatory submissions, with both agencies now accepting simulation-derived evidence for dosing decisions and pediatric extrapolation. WHO and ICH guidelines on extrapolation and master protocols are further standardizing the evidentiary threshold for virtual cohorts. Stakeholders must monitor how qualification opinion precedents accumulate across therapeutic areas, as these determinations will dictate which modeling platforms achieve de facto regulatory standard status and which remain niche analytical tools.
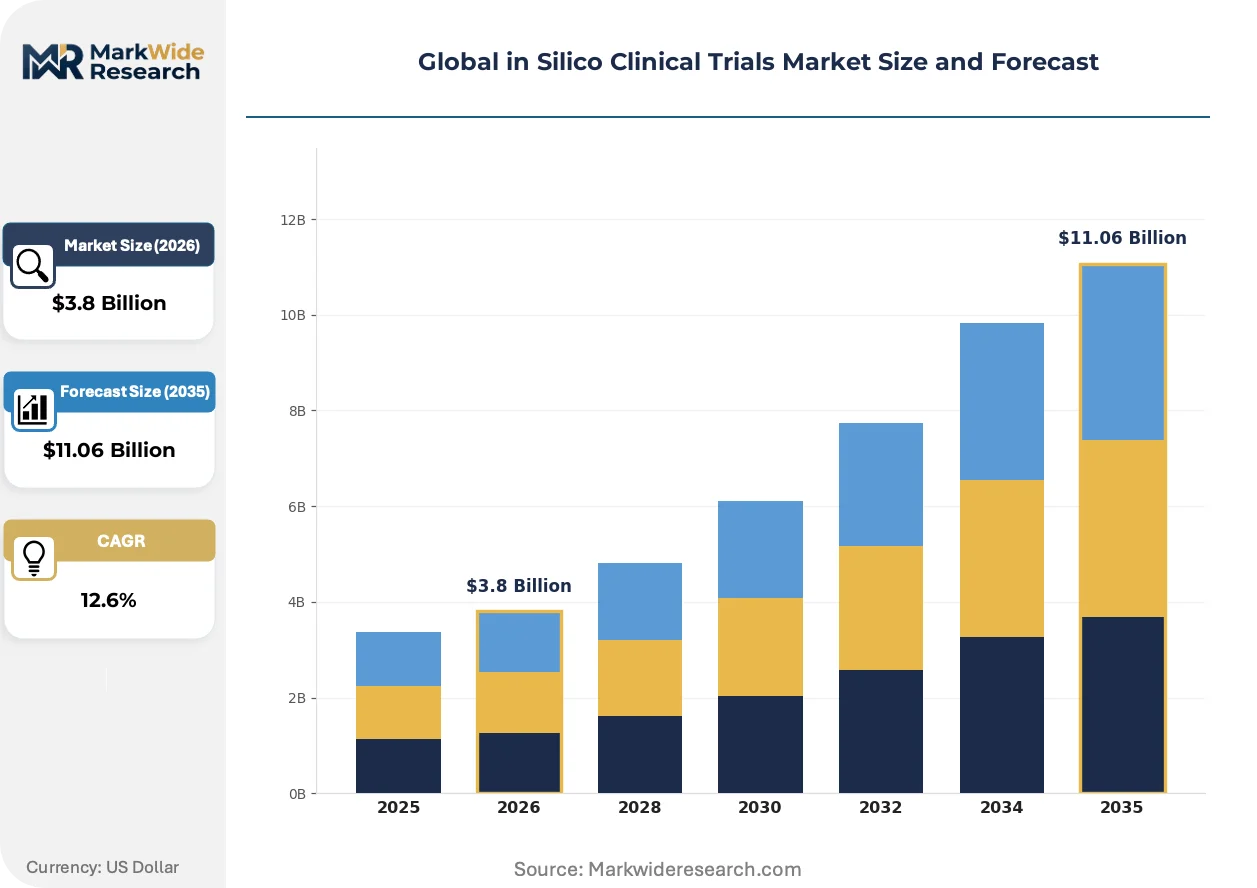
Market Dynamics
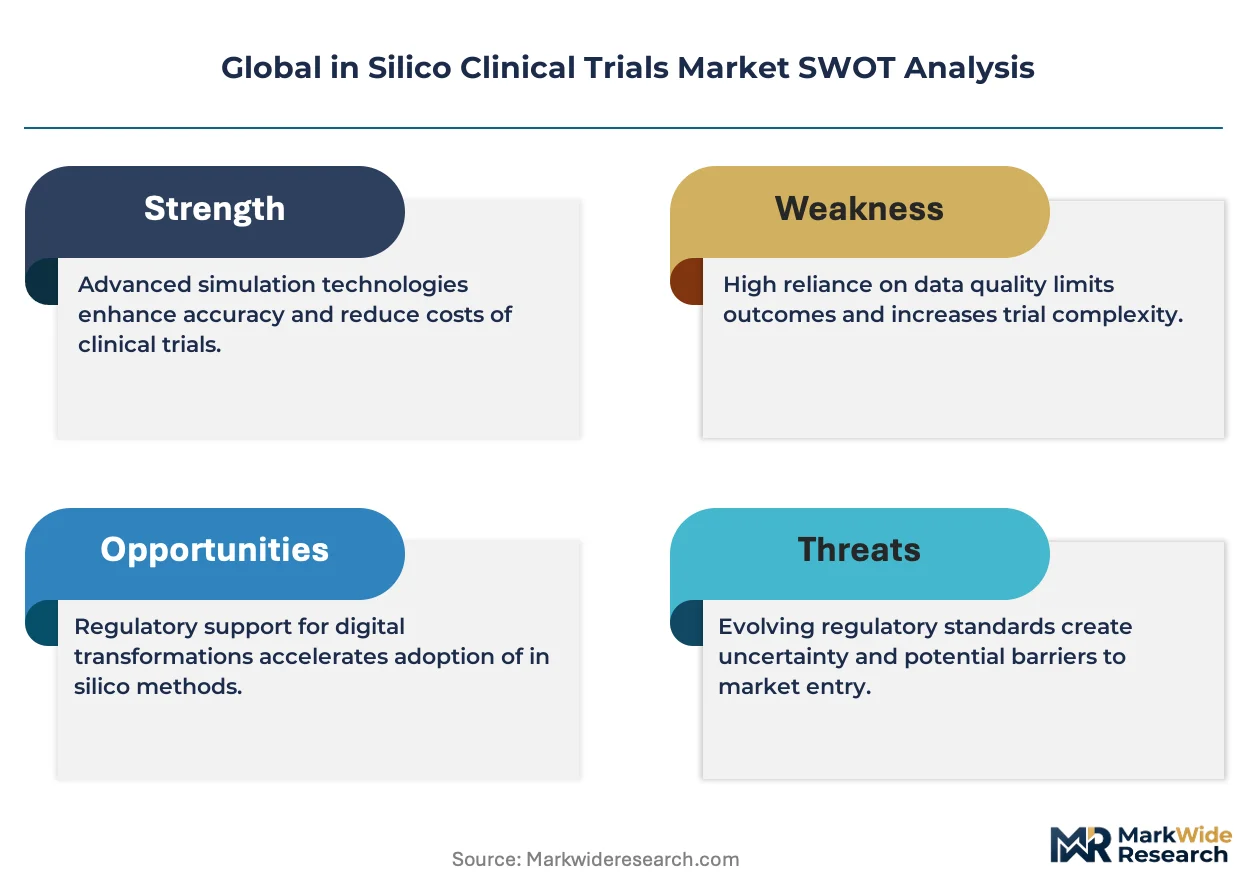
Regulatory qualification pathways for virtual patient cohorts are compressing the evidentiary gap between simulated and physical trials, forcing sponsors to rebuild submission strategies around model-informed drug development frameworks.
Growth Catalysts
- FDA Model-Informed Drug Development:The FDA's MIDD guidance creates explicit channels for simulation-derived evidence in dosing decisions and pediatric extrapolation, reducing reliance on traditional human cohorts.
- Agent-based modeling:Immunology and oncology applications demand individual-level heterogeneity capture that agent-based methods uniquely deliver, accelerating platform specialization in these therapeutic areas.
- EMA qualification opinion pathway:The EMA's formal mechanism for novel methodology acceptance establishes precedents that de-risk sponsor investment in computational modeling infrastructure.
Market Restraints
- Computational infrastructure costs:High-performance computing clusters and specialized cloud architecture for physics-based simulations impose capital barriers on mid-tier pharmaceutical developers.
- Validation standard fragmentation:Absence of harmonized ISO protocols across jurisdictions forces redundant model qualification efforts, inflating regulatory preparation timelines.
- Biological uncertainty quantification:Incomplete parameterization of rare disease pathophysiology limits virtual cohort reliability in niche therapeutic indications.
Strategic Opportunities
- Pediatric and orphan disease extrapolation:Regulatory frameworks accepting simulated evidence for dosing in populations where traditional trials are ethically constrained open high-margin specialty service lines.
- Digital twin integration:Convergence of wearable biosensor streams with physiological modeling enables real-time virtual patient calibration against actual patient trajectories.
- Academic-industry consortia in the United States:Federally funded pre-competitive research partnerships reduce individual sponsor validation burdens while building shared model repositories.
Industry Challenges
- Cross-disciplinary talent scarcity:The intersection of pharmacology, computational science, and regulatory science demands hybrid skill sets that existing training pipelines fail to produce at sufficient scale.
- Legacy clinical data architecture:Sponsor IT systems designed for traditional trial capture require expensive reconfiguration to feed structured inputs into simulation platforms.
- IP fragmentation across model components:Proprietary algorithms, publicly funded physiological parameters, and licensed biological data create complex royalty stacking in commercial platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in Silico Clinical Trials Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Physics-Based Modeling, Machine Learning, Pharmacokinetics, Systems Biology, Agent-Based Modeling, Statistical Simulation Application: Drug Discovery, Toxicity Assessment, Biomarker Identification, Dose Optimization, Clinical Endpoint Prediction, Adverse Event Monitoring End User: Pharmaceutical Developers, Biotech Innovators, Contract Research Organizations, Regulatory Agencies, Academic Institutions, Medical Device Companies Deployment: Cloud-Based Platforms, On-Premises Systems, Hybrid Solutions, SaaS Models, High-Performance Computing, Federated Networks |
| Companies Covered | Certara, Inc., Novadiscovery Sas, Insilico Medicine, Inc., Dassault Systemes SE, GNS Healthcare Inc., InSilicoTrials, Immunetrics Inc., The AnyLogic Company, Abzena Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in Silico Clinical Trials Market Shifts & Advancements
Generative architectures are rewriting how molecular candidates enter virtual testing pipelines, compressing the front end of discovery while regulatory agencies scramble to validate the back end of evidence generation.
Generative AI platforms for de novo molecule design are displacing traditional high-throughput screening as the primary input into toxicity prediction workflows. Large pharmaceutical sponsors now mandate embedded simulation checkpoints before physical synthesis authorization. This compression is eliminating entire wet-lab cycles from early-phase development timelines.
The FDA's MIDD program and EMA's parallel qualification pathway are creating divergent evidentiary standards that sponsors must simultaneously satisfy. European regulators emphasize mechanistic model transparency while US authorities prioritize predictive accuracy metrics. Oncology and immunology submissions bear the highest compliance burden as these therapeutic areas dominate qualification opinion precedents.
Pharmaceutical procurement departments now unbundle simulation services from full-service contract research relationships, establishing direct platform licensing agreements with specialized vendors. This disintermediation strips traditional CROs of high-margin modeling revenue. The United States exhibits the most advanced procurement sophistication, with several top-ten sponsors operating captive in silico units alongside external vendor panels.
Global in Silico Clinical Trials Market Segmentation
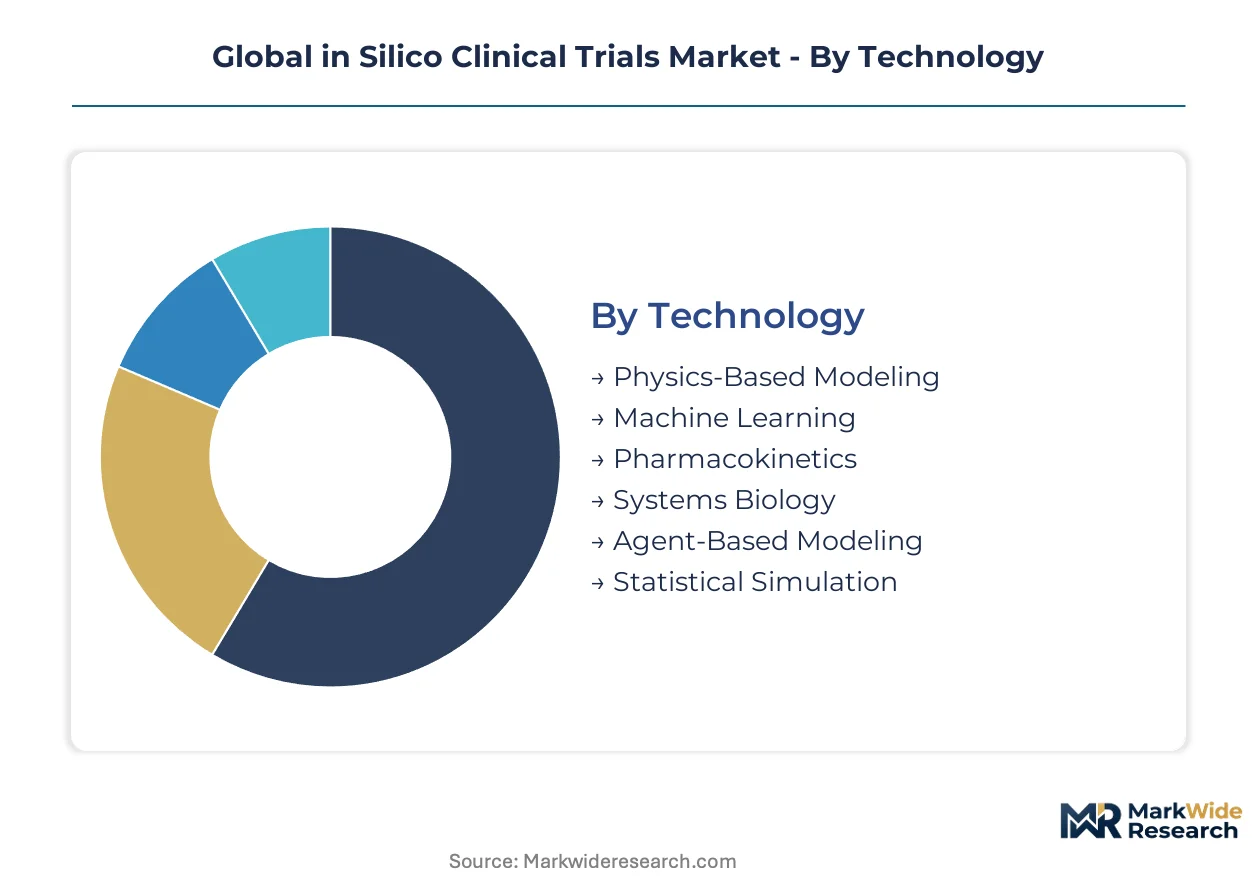
Technology and application segments in the in silico clinical trials market face divergent substitution pressures as generative AI displaces legacy statistical methods while regulatory validation requirements protect incumbent modeling approaches. Deployment models compete directly for pharmaceutical IT budgets against traditional physical infrastructure investments.
Technology:
Physics-based modeling confronts the strongest substitution threat from machine learning architectures that promise faster parameterization with lower computational overhead.
- Physics-Based Modeling:Mechanistic simulations grounded in physiological and biochemical first principles deliver transparent, interpretable outputs that regulators prefer for safety-critical decisions. Demand concentrates in late-phase submissions to the FDA and EMA where mechanistic transparency outweighs speed advantages. Validation requirements and cross-jurisdictional acceptance sustain its defensive position against faster alternatives.
- Machine Learning:Pattern recognition algorithms trained on historical trial data accelerate prediction timelines for drug behavior and patient response. Adoption concentrates among mid-tier pharmaceutical developers in the United States seeking to compress early-phase timelines without specialized computational infrastructure investments. Regulatory skepticism toward black-box predictions limits deployment in pediatric and orphan disease applications.
- Pharmacokinetics:Compartmental and physiologically-based PK models remain essential for dose-exposure-response relationships.
- Systems Biology:Network-level pathway simulations capture multi-scale biological interactions for complex disease modeling.
- Agent-Based Modeling:Individual-level heterogeneity capture enables immunology and oncology applications where population averaging fails.
- Statistical Simulation:Monte Carlo and bootstrap methods provide reference benchmarks for model qualification exercises.
Physics-based modeling anchors the volume base while agent-based modeling gains share at the steepest rate.
Application:
Cost tier differentiation separates high-investment discovery applications from optimization services where failure-to-optimize penalties create acute sponsor willingness-to-pay.
- Drug Discovery:Virtual screening and target identification workflows compress the front end of development by eliminating non-viable candidates before physical synthesis. Demand concentrates in large pharmaceutical developers operating integrated discovery-simulation pipelines. Generative AI integration is displacing traditional high-throughput screening as the primary input modality.
- Toxicity Assessment:Predictive safety modeling identifies off-target effects and organ-specific liabilities prior to in vivo exposure. Adoption concentrates among sponsors seeking to reduce preclinical animal study requirements under FDA and EMA pressure. Regulatory qualification precedents in hepatotoxicity and cardiotoxicity establish de facto platform standards.
- Biomarker Identification:Computational patient stratification enables precision trial designs with enriched responder populations.
- Dose Optimization:Model-informed dosing decisions reduce late-phase failure rates from suboptimal exposure-response relationships.
- Clinical Endpoint Prediction:Virtual cohort simulations forecast trial outcomes to inform go/no-go investment decisions.
- Adverse Event Monitoring:Signal detection algorithms process simulated patient data to anticipate safety liabilities.
Toxicity assessment commands the highest margin tier while dose optimization expands most quickly as sponsors internalize late-phase failure costs.
End User:
Customer type fragmentation reflects divergent procurement sophistication, with top-tier pharmaceutical developers unbundling services while smaller innovators rely on full-service relationships.
- Pharmaceutical Developers:Large sponsors operate captive in silico units alongside external vendor panels, mandating embedded simulation checkpoints before physical synthesis authorization. Procurement departments in the United States lead direct platform licensing agreements that disintermediate traditional CRO relationships.
- Contract Research Organizations:Full-service providers face revenue pressure as sponsors unbundle high-margin modeling services into specialized vendor relationships.
- Biotech Innovators:Capital-constrained developers prioritize SaaS and federated network access over infrastructure investment.
- Regulatory Agencies:FDA and EMA internal modeling capabilities inform qualification opinion precedents and submission review standards.
- Academic Institutions:Federally funded consortia build shared model repositories that reduce individual validation burdens.
- Medical Device Companies:ISO 14155 certification requirements extend simulation adoption beyond pharmaceutical applications.
Pharmaceutical developers anchor demand volume while biotech innovators represent the steepest customer expansion trajectory.
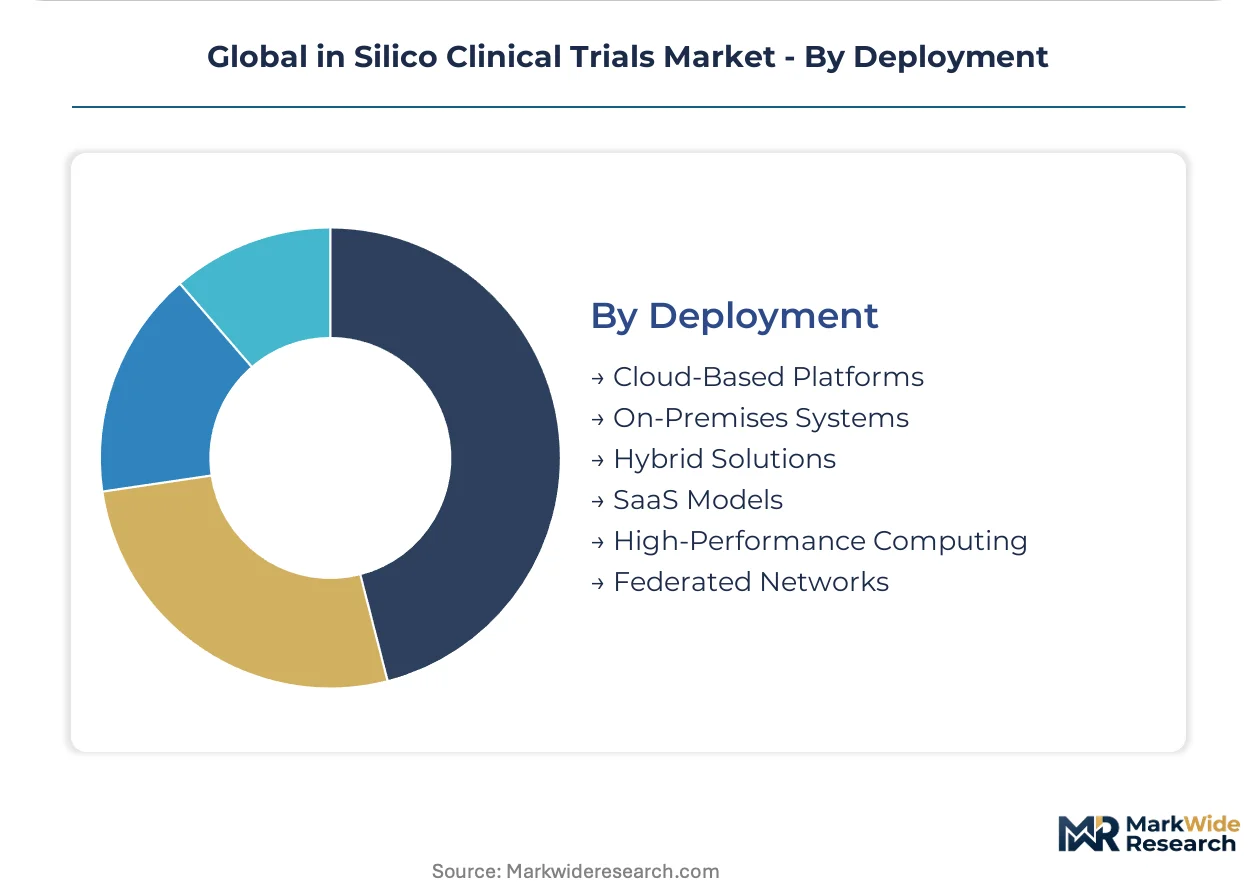
Deployment:
Supply concentration in cloud infrastructure shapes competitive positioning as hyperscaler partnerships determine platform scalability and regulatory data residency compliance.
- Cloud-Based Platforms:Elastic compute resources enable on-demand scaling for physics-based simulations without capital-intensive cluster ownership. Adoption concentrates in the United States where academic-industry consortia and federal research partnerships have normalized cloud-first strategies for pre-competitive model development.
- High-Performance Computing:Dedicated clusters serve sponsors with persistent computational demands and stringent data sovereignty requirements.
- On-Premises Systems:Air-gapped deployments satisfy regulatory agencies and sponsors handling competitively sensitive molecule structures.
- Hybrid Solutions:Tiered architectures partition sensitive data locally while offloading compute-intensive simulations to cloud resources.
- SaaS Models:Subscription access lowers entry barriers for mid-tier developers and academic researchers.
- Federated Networks:Distributed learning architectures enable multi-site collaboration without centralizing proprietary patient data.
Cloud-based platforms anchor deployment volume while federated networks climb the fastest as data privacy requirements fragment computational geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Model-Informed Drug Development guidance and EMA's qualification opinion pathway are accelerating regulatory acceptance of simulation-based evidence across multiple jurisdictions. Pharmaceutical developers in the United States, Germany, Japan, China, and the United Kingdom are expanding cloud-based platform investments and academic-industry consortia.
United States
Cloud-first deployment strategies and federally funded pre-competitive research partnerships dominate pharmaceutical procurement patterns. FDA's MIDD program creates explicit channels for simulation-derived evidence in dosing decisions and pediatric extrapolation. Boston-Cambridge and San Francisco Bay Area clusters host the densest concentrations of specialized in silico vendors and captive pharma units.
Germany
Mechanistic model transparency requirements from EMA regulators drive demand for physics-based modeling platforms with interpretable outputs. The country's national pharmaceutical regulator emphasizes validation documentation for novel methodologies. Baden-Württemberg and Bavaria industrial corridors concentrate engineering simulation expertise migrating into biopharma applications.
Japan
PMDA's evolving stance on model-informed drug development is reshaping sponsor submission strategies for dose optimization and toxicity assessment. METI research initiatives fund academic-industry collaboration on virtual patient cohort standardization. Tokyo-Osaka pharmaceutical corridors anchor domestic platform adoption alongside multinational R&D centers.
China
NMPA's expanding acceptance of foreign simulation-derived evidence is opening pathways for multinational sponsors to leverage global modeling infrastructure. The country's dual carbon goals pressure developers to reduce physical trial footprints through virtual cohort substitution. Yangtze River Delta biotech clusters are emerging as regional hubs for AI-driven molecule design platforms.
United Kingdom
Post-Brexit regulatory divergence from EMA frameworks creates parallel validation requirements for sponsors seeking UK market access. MHRA's innovation pathways accommodate simulation-based evidence for rare disease indications where traditional trials face ethical constraints. London-Oxford-Cambridge life sciences corridor concentrates academic modeling expertise and startup platform development.
Global in Silico Clinical Trials Market Competitive Landscape
Player mix skews toward specialized computational platform vendors with pharmacokinetic modeling heritage and diversified engineering simulation conglomerates extending into biopharma. Market structure exhibits moderate consolidation around regulatory qualification precedents that favor incumbent validation histories. Three archetypes dominate: legacy PK modeling specialists, generative AI-native platforms, and cross-industrial simulation providers. Competitive dynamics center on M&A activity targeting specialized algorithm portfolios and strategic partnerships with hyperscaler cloud infrastructure providers.
Among established modeling specialists, Certara, Inc. and Immunetrics Inc. occupy positions anchored by decades of regulatory submission experience and mechanistic model libraries. Dassault Systemes SE exemplifies the cross-industrial archetype, leveraging engineering simulation dominance into biopharma through unified data architecture. Insilico Medicine, Inc. represents the generative AI-native tier, competing through de novo molecule design platforms with embedded toxicity prediction workflows.
| Leading Market Players |
|---|
| Certara, Inc. |
| Novadiscovery Sas |
| Insilico Medicine, Inc. |
| Dassault Systemes SE |
| GNS Healthcare Inc. |
| InSilicoTrials |
| Immunetrics Inc. |
| The AnyLogic Company |
| Abzena Ltd. |
| Others |
Supply & Pricing Matrix
FDA Model-Informed Drug Development qualification gates both platform vendor entry and price tiering, compressing margins for uncertified entrants while rewarding validated incumbents with premium positioning. ISO 14155 certification for medical device simulation creates parallel quality tiers that pharmaceutical procurement departments use to unbundle services from traditional CRO relationships.
Pricing Analysis
Certification level creates the primary spread between premium FDA-qualified platforms and standard analytical tools lacking regulatory precedent. Three-tier pricing structure across validated, qualified, and exploratory levels reflects validation burden and submission history depth. Pricing pressure stems from mid-tier pharmaceutical developers demanding SaaS alternatives to capital-intensive licensing. Biotech innovators exhibit acute price sensitivity, while top-ten sponsors prioritize regulatory certainty over cost.
Supply Chain Analysis
Inventory cycles for high-performance computing clusters stretch 12-18 months, tethering platform scalability to hyperscaler capacity allocation. The United States, Germany, and China anchor cloud infrastructure deployment, with specialized GPU availability constraining physics-based simulation throughput. NVIDIA and AMD chip architectures feed computational demands, while proprietary algorithm libraries and licensed biological data create IP stacking complexity. Tariff exposure on semiconductor components threatens hardware cost trajectories. Distribution runs through direct enterprise licensing and academic-industry consortium channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in in silico clinical trials reflects FDA MIDD guidance penetration accelerating sponsor adoption beyond traditional pharmacokinetic niches. Regulatory qualification precedents are concentrating competitive advantage among validated platform vendors.
For Market Incumbents: Secure regulatory qualification opinion precedents in oncology and immunology as defensive moats against generative AI-native entrants. Deepen backward integration into cloud infrastructure partnerships to control compute cost trajectories. Defend margin position by embedding simulation checkpoints into sponsor discovery pipelines before physical synthesis authorization. For New Entrants and Emerging Players: Lead with federated network architectures targeting European data privacy requirements as the most penetrable deployment wedge. Target mid-tier biotech innovators in the United States with SaaS pricing that bypasses capital-intensive licensing barriers. Position through academic consortia partnerships that reduce individual validation burdens. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based platform delivery, compressing barrier-to-entry timelines for scaled entrants. Long-term viability favors vendors with accumulated FDA submission histories and mechanistic model libraries. Target acquisition archetype: specialized agent-based modeling shops with immunology validation records. Watch EMA qualification opinion accumulation rates as inflection signal for platform standardization winners.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Qualification Pathway Investment | FDA MIDD and EMA opinion precedents establish de facto platform standards for dosing decisions. |
| Academic-Industry Consortium Formation | Federally funded partnerships reduce individual sponsor validation burdens while building shared repositories. |
| Generative AI Platform Integration | De novo molecule design with embedded toxicity prediction compresses discovery timelines before physical synthesis. |
| Cloud Infrastructure Partnership | Hyperscaler alliances determine platform scalability and regulatory data residency compliance across jurisdictions. |
| Pediatric Extrapolation Service Launch | Ethically constrained populations open high-margin specialty lines with regulatory acceptance of simulated evidence. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, platform engineers, and hospital procurement managers converged on the working assumptions governing adoption trajectories. Primary interviews across pharmaceutical sponsors, CRO procurement departments, and academic modeling centers combined with secondary validation from FDA MIDD guidance documents, EMA qualification opinions, ClinicalTrials.gov simulation entries, and SEC R&D expenditure filings. Bottom-up platform deployment estimates triangulated against top-down pharmaceutical IT budget allocations.
Segmentation dimensions modeled span technology type, application workflow, end-user procurement sophistication, and deployment architecture across the analysis window. Treatment line positioning, regional regulatory cluster, and computational infrastructure tier provided additional stratification. CAGRs derived from fitted adoption curves incorporating FDA guidance release timing and sponsor pipeline restructuring announcements. Physics-based simulation demand and generative AI platform penetration served as primary forecast inputs.
Underlying assumptions cover regulatory acceptance continuity, with deviation risk concentrated in qualification opinion precedent accumulation rates and hyperscaler capacity allocation constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
North America Clinical Trials Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
Healthcare Europe Clinical Data Analytics Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
Preclinical CRO Market