
 Europe Hospital Supplies Market | 2026-2036
Europe Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hospital Supplies Market Foresight
Hospital procurement channels across Europe is narrowing as group purchasing organizations consolidate vendor lists and centralize contract negotiations. Medtronic PLC leverages its broad surgical portfolio to sustain long-term supply agreements with major hospital networks. B. Braun Melsungen AG anchors its position through deep manufacturing integration in Germany and Central Europe. Cardinal Health Inc competes on logistics density, operating distribution hubs that reduce delivery lead times to regional hospital systems.
Europe hospital supplies encompass instruments, equipment, disposables, and sterilization products manufactured to ISO 13485 and MDR compliance standards, primarily serving acute care delivery and infection prevention workflows. Consumables generate recurring revenue streams with shorter replacement cycles than capital equipment, while surgical instruments command premium pricing tied to steel grade precision and sterilization durability. Diagnostic equipment integrates with AI-enabled imaging platforms, and telemedicine technology expands remote patient monitoring capabilities in post-acute settings.
EMA guidelines, EU MDR requirements, and CE marking protocols govern product registration, clinical evidence standards, and post-market surveillance obligations across member states. These frameworks elevate compliance costs for non-European manufacturers while creating protected demand zones for certified domestic suppliers. Stakeholders must monitor evolving notified body capacity constraints and MDR transition timelines that determine market access speed.
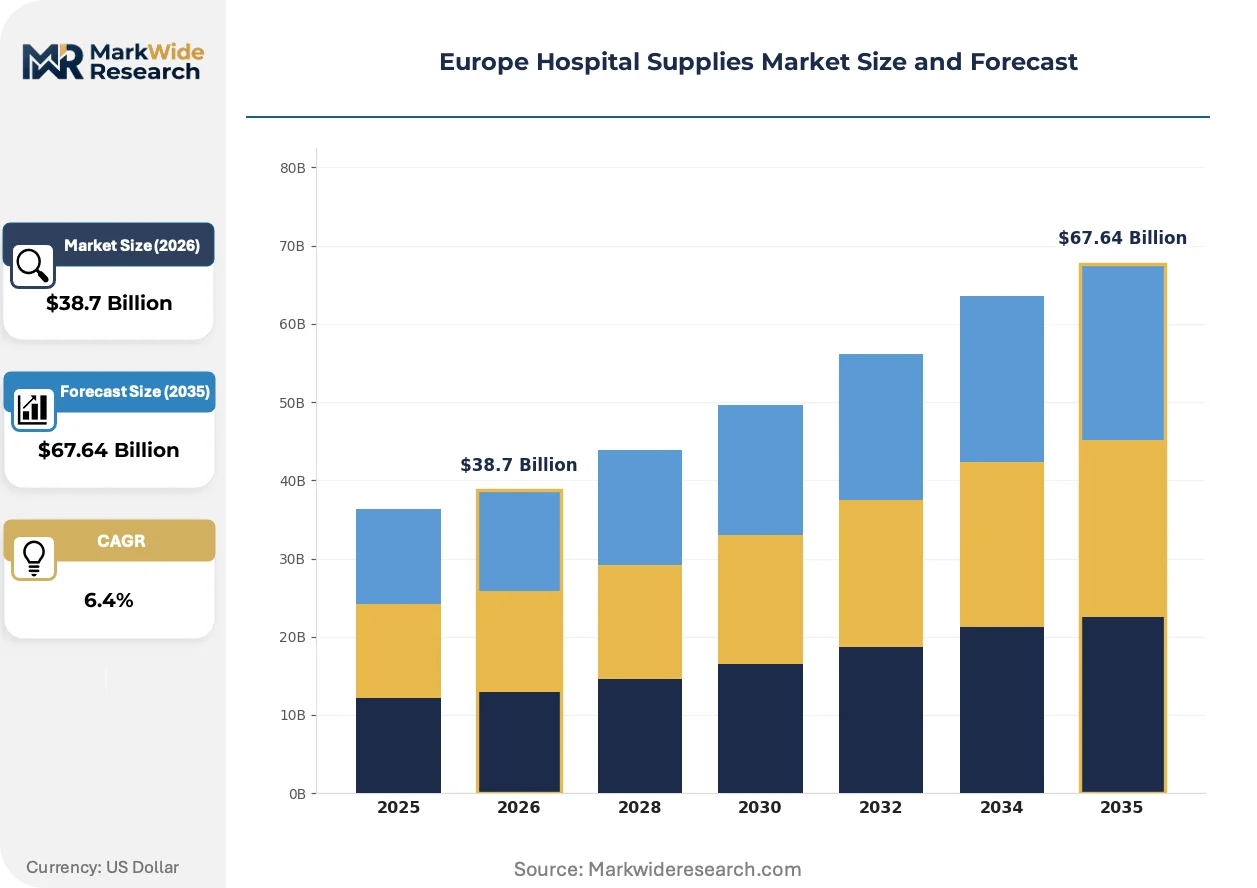
Market Dynamics
EU MDR compliance deadlines are compressing vendor certification timelines while hospital group purchasing organizations consolidate supplier rosters across Germany, France, and Italy. This dual pressure is restructuring competitive access before the regulatory transition completes.
Growth Catalysts
- MDR Recertification Mandate:The EU Medical Device Regulation is forcing product portfolio upgrades across notified body networks, creating replacement demand for legacy surgical instruments and sterilization consumables in tertiary care facilities.
- Single-Use Surgical Kit Expansion:German hospital clusters are expanding procurement of disposable procedure packs to reduce cross-contamination risk in orthopedic and cardiovascular intervention suites.
- AI-Enabled Diagnostic Integration:Imaging equipment manufacturers are embedding machine learning algorithms into radiology and pathology workflows, driving capital refresh cycles in university hospitals.
Market Restraints
- Notified Body Bottleneck:EU MDR transition has overwhelmed TÜV SÜD and BSI Group capacity, extending certification timelines to 18-24 months for Class III devices.
- Stainless Steel Price Volatility:Surgical instrument manufacturers face margin compression from nickel and chromium input cost swings tied to energy-intensive European smelter operations.
- Reusable Device Substitution:Central sterilization departments in French public hospitals are extending instrument lifecycle through refurbishment programs, displacing new unit purchases.
Strategic Opportunities
- Poland and Romania Hospital Modernization:EU cohesion funds are financing surgical suite upgrades in Eastern European secondary care facilities underserved by premium instrument suppliers.
- Remote Patient Monitoring Expansion:Post-acute care networks in the UK are integrating disposable biosensors with telemedicine platforms for chronic disease management.
- Green Procurement Incentives:The EU Green Deal is creating preferential purchasing criteria for sterilization products with reduced chemical waste profiles in Nordic hospital systems.
Industry Challenges
- MDR Technical Documentation Gap:Clinical evidence requirements for legacy devices are forcing manufacturers to reconstruct decade-old performance data or withdraw SKUs.
- Legacy ERP Integration:Hospital supply chain software from the 2000s lacks API compatibility with modern inventory tracking systems, complicating automated reorder implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hospital Supplies Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, Sterilization Supplies, Consumables Delivery Mode: Direct Sales, Online Platforms, Contracts, Distributors End User: Clinics, Diagnostic Labs, Rehabilitation Centers, Emergency Services Technology: Telemedicine, Wearable Devices, AI Diagnostics, 3D Printing |
| Companies Covered | Medtronic PLC, B. Braun Melsungen AG, Cardinal Health Inc, Baxter International Inc, Becton Dickinson & Company, Johnson & Johnson, 3M Company, Fresenius Medical Care AG & Co. KGaA, Koninklijke Philips N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hospital Supplies Market Shifts & Advancements
Hospital supply chains across Europe are digitizing procurement workflows while regulatory compliance reshapes product design priorities. Three converging developments are compressing traditional competitive advantages.
Smart surgical instruments with embedded RFID tracking are migrating from pilot programs in Swiss university hospitals to standard procurement specifications in German hospital clusters. These devices enable real-time sterilization cycle verification and loss prevention. The technology is migrating from high-value orthopedic sets to general surgery trays as unit economics improve through semiconductor miniaturization.
REACH chemical restriction expansions are phasing out certain sterilization agents in medical device manufacturing, forcing reformulation of disinfectant chemistries and packaging materials. Manufacturers serving the French and Benelux markets are accelerating substitution timelines ahead of regulatory deadlines. Diagnostic equipment with reduced hazardous substance profiles is capturing preferential positioning in public tender evaluations.
Consolidated procurement frameworks are displacing hospital-level purchasing autonomy across England's National Health Service supply chain. Integrated care systems now negotiate multi-year consumable contracts covering dozens of acute trusts, compressing vendor margins through volume aggregation. This concentration is most advanced in the Midlands and North West regions where procurement collaboratives manage combined spend exceeding individual continental European countries.
Europe Hospital Supplies Market Segmentation
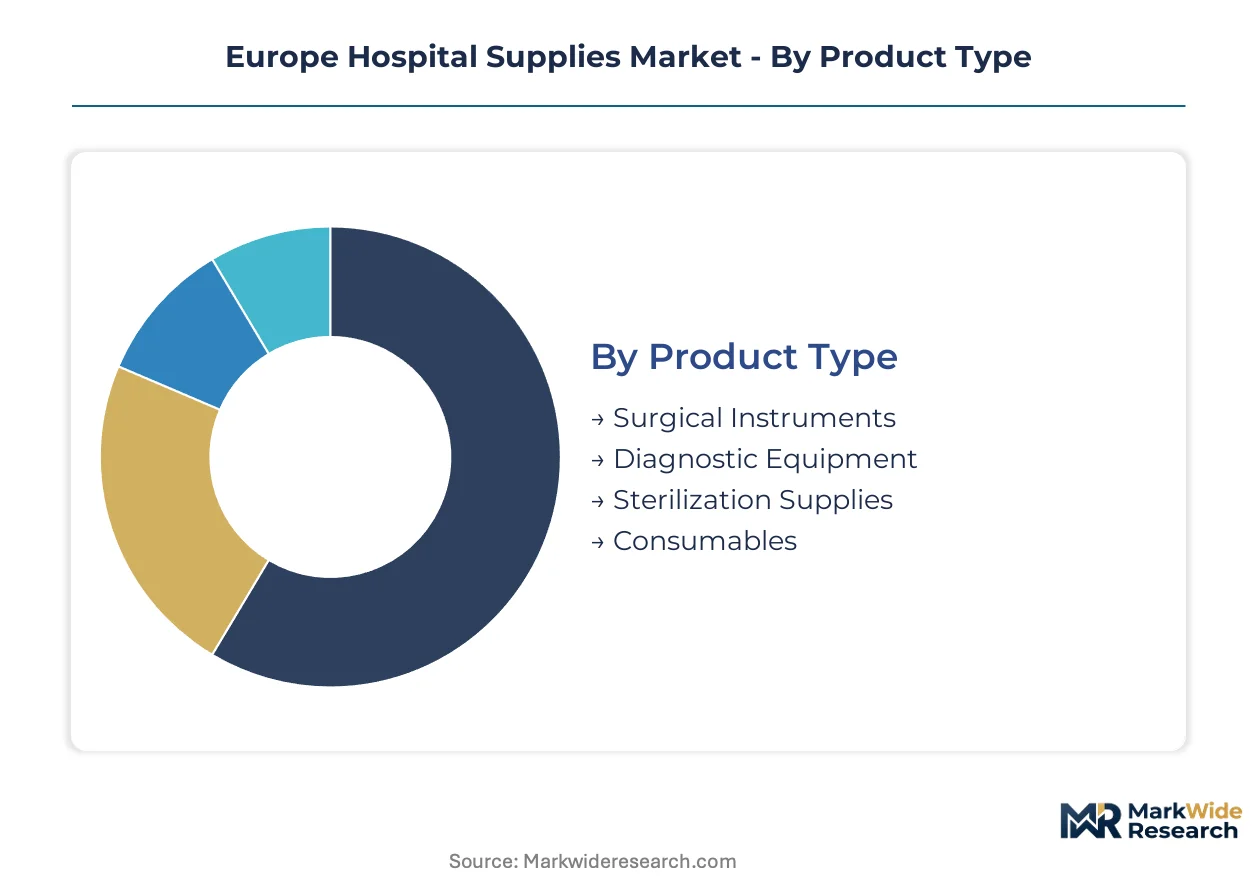
Segmentation in hospital supplies determines procurement pathways, margin structures, and regulatory exposure across European healthcare systems. Product durability, delivery reliability, and technology integration each create distinct competitive arenas with separate vendor qualification requirements.
Product Type:
Cost tier stratification separates capital-intensive equipment from high-velocity consumables with radically different replacement economics.
- Surgical Instruments:Precision-manufactured stainless steel and titanium tools graded by alloy composition and sterilization cycle tolerance. German tertiary care clusters in Bavaria and North Rhine-Westphalia are upgrading to RFID-tracked instrument sets under MDR traceability mandates.
- Consumables:Single-use disposables including syringes, catheters, wound dressings, and procedure kits with ISO 13485-certified sterility assurance. French hospital procurement cooperatives are consolidating disposable surgical pack contracts to reduce per-procedure costs.
- Diagnostic Equipment:Imaging and laboratory analyzers with embedded software and AI-enabled interpretation modules.
- Sterilization Supplies:Chemical indicators, biological monitors, and packaging materials for central sterile processing departments.
Surgical instruments hold installed capacity. Consumables are rotating up the share rankings.
Delivery Mode:
Channel structure reflects hospital purchasing autonomy erosion and logistics technology migration.
- Contracts:Multi-year framework agreements negotiated by group purchasing organizations and national health service procurement bodies. England's NHS Supply Chain and Germany's EKAP purchasing cooperative dominate volume allocation through centralized tender processes.
- Distributors:Regional logistics networks maintaining temperature-controlled warehousing and just-in-time delivery to hospital receiving docks. Benelux distributors are consolidating last-mile capabilities to serve Dutch academic medical centers with sub-24-hour replenishment cycles.
- Direct Sales:Manufacturer field representatives managing capital equipment specification and installation.
- Online Platforms:Digital procurement portals with automated reorder triggers and real-time inventory visibility.
Contract channels hold installed capacity. Distributor networks are rotating up the share rankings.
End User:
Customer type determines product specification intensity and regulatory documentation requirements.
- Diagnostic Labs:High-throughput clinical laboratories requiring automated analyzers with LIS integration and CE-IVD certification. Italian regional health authorities are consolidating lab instrument procurement through Lombardy and Emilia-Romagna hub facilities.
- Clinics:Outpatient and ambulatory surgical centers with space-constrained equipment footprints and disposable-heavy supply profiles. Polish private clinic chains are expanding procedure volume through EU cohesion fund-financed facility upgrades.
- Emergency Services:Pre-hospital care and trauma units with portable, battery-operated equipment and rapid-deployment supply configurations.
- Rehabilitation Centers:Post-acute facilities integrating remote monitoring disposables with telemedicine infrastructure.
Diagnostic labs hold installed capacity. Clinics are rotating up the share rankings.
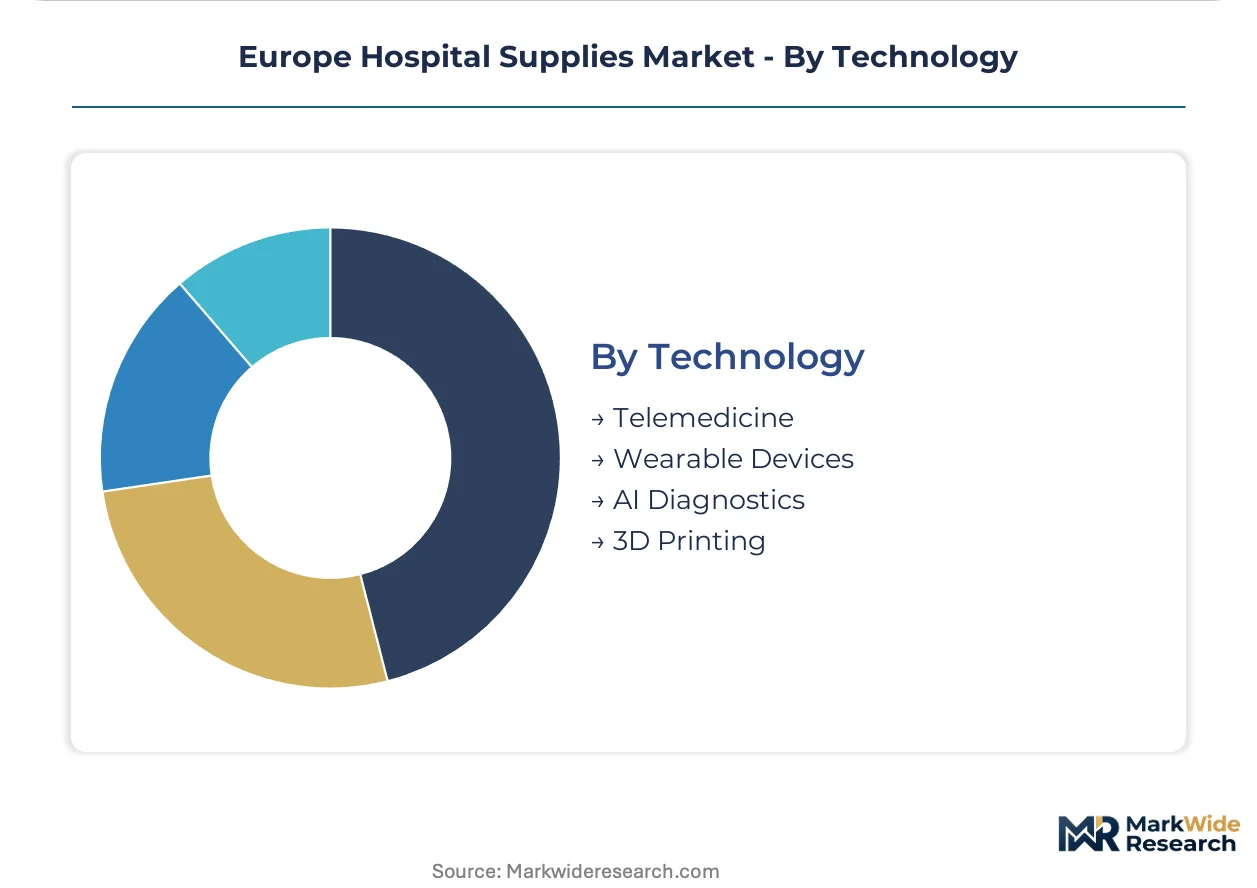
Technology:
Technology maturity separates established diagnostic platforms from emerging digital health modalities with unproven reimbursement pathways.
- AI Diagnostics:Machine learning algorithms embedded in radiology workstations and pathology image analysis systems. University hospitals in Switzerland and the UK are piloting AI-enabled mammography and histology screening under EMA guidance for software-as-medical-device classification.
- Wearable Devices:Continuous monitoring biosensors for glucose, cardiac rhythm, and respiratory function with cloud-connected data transmission. Nordic hospital systems are deploying post-discharge wearable programs under EU Green Deal sustainability criteria for reduced readmission rates.
- Telemedicine:Remote consultation platforms with integrated diagnostic peripherals for virtual examination.
- 3D Printing:Patient-specific surgical guides and prosthetic components manufactured at point-of-care.
Telemedicine holds installed capacity. AI diagnostics are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR compliance deadlines are restructuring procurement patterns across member states. Hospital clusters in Germany, France, and Italy are consolidating vendor lists while Eastern European facilities modernize surgical infrastructure.
Germany
Bavarian and North Rhine-Westphalian hospital clusters are expanding RFID-tracked surgical instrument procurement under MDR traceability mandates. The Federal Institute for Drugs and Medical Devices (BfArM) is accelerating notified body coordination for Class III device recertification. EKAP purchasing cooperative in Berlin centralizes multi-year consumable contracts covering university hospitals across the country.
United Kingdom
NHS Supply Chain procurement collaboratives in the Midlands and North West are aggregating spend across dozens of acute trusts. The Medicines and Healthcare products Regulatory Agency (MHRA) maintains parallel MDR recognition protocols post-Brexit. London teaching hospitals are piloting AI-enabled diagnostic integration into radiology workflows.
France
Public hospital central sterilization departments in Île-de-France are extending instrument lifecycles through refurbishment programs. ANSM oversees MDR transition timelines for legacy device portfolios. Hospital procurement cooperatives in Auvergne-Rhône-Alpes are consolidating disposable surgical pack contracts to reduce per-procedure expenditure.
Italy
Lombardy and Emilia-Romagna regional health authorities are consolidating diagnostic laboratory instrument procurement through hub facilities. The Italian Medicines Agency (AIFA) coordinates CE marking recognition with EMA guidance. Tertiary care centers in Milan are upgrading to single-use procedure packs in cardiovascular intervention suites.
Poland
EU cohesion funds are financing surgical suite upgrades in secondary care facilities across Warsaw and Kraków metropolitan areas. The Office for Registration of Medicinal Products oversees MDR implementation timelines for imported devices. Private clinic chains are expanding ambulatory surgical capacity through facility modernization programs.
Europe Hospital Supplies Market Competitive Landscape
Integrated surgical portfolio suppliers and specialized sterilization manufacturers split the market between comprehensive contract coverage and niche technical positioning. Vendor consolidation is compressing margins for mid-tier distributors while premium instrument makers defend pricing through MDR-certified traceability systems. Two archetypes dominate: diversified medtech conglomerates with broad hospital relationships, and focused consumables specialists with manufacturing integration in Central Europe. Competitive moves center on group purchasing organization contract capture and notified body certification capacity expansion.
Among diversified portfolio anchors, Medtronic PLC and B. Braun Melsungen AG exemplify the conglomerate archetype with deep European manufacturing footprints. Cardinal Health Inc occupies a position within the logistics-intensive distribution tier, competing on delivery density to regional hospital systems. These three represent contrasting strategic postures: surgical instrument breadth, manufacturing verticality, and supply chain velocity respectively.
| Leading Market Players |
|---|
| Medtronic PLC |
| B. Braun Melsungen AG |
| Cardinal Health Inc |
| Baxter International Inc |
| Becton Dickinson & Company |
| Johnson & Johnson |
| 3M Company |
| Fresenius Medical Care AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
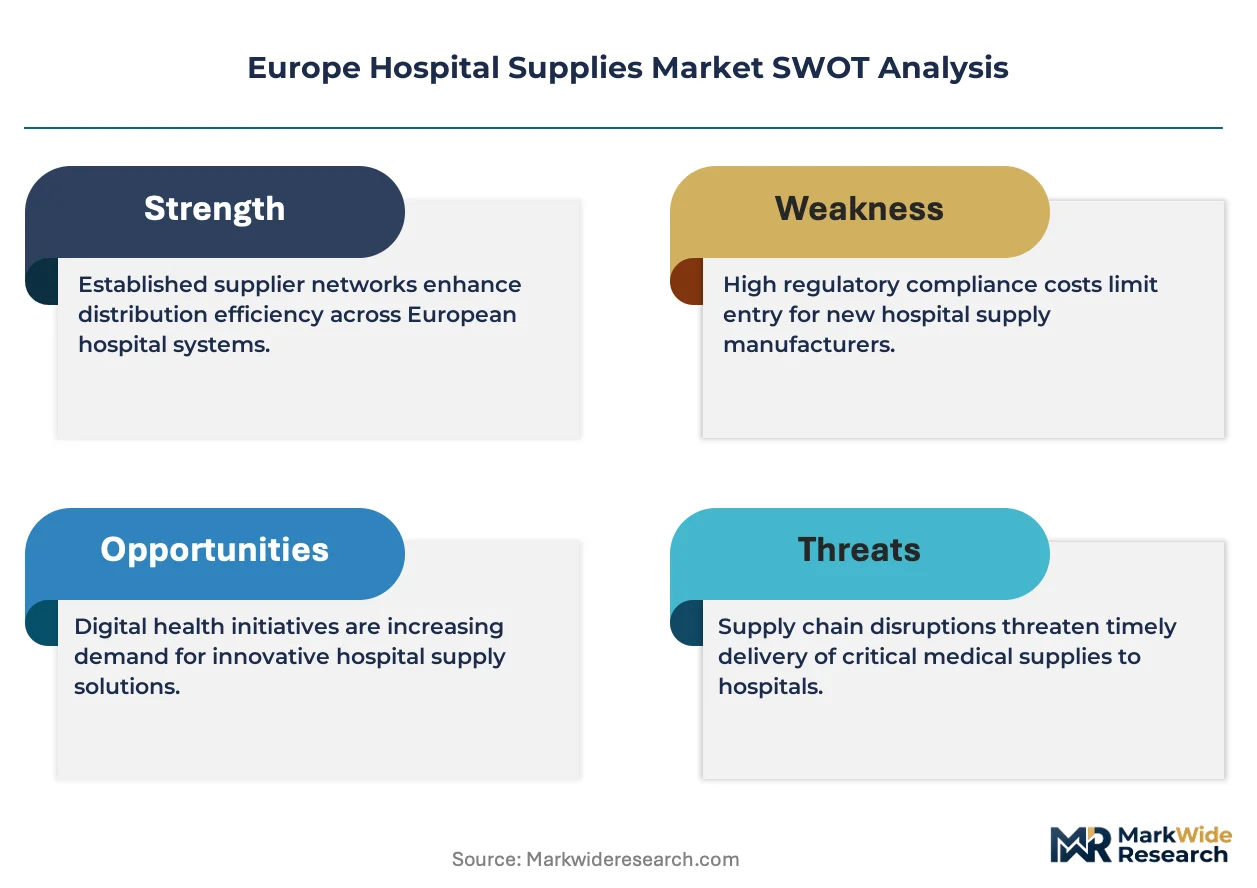
Bavarian surgical instrument manufacturing clusters concentrate ISO 13485-certified production capacity, granting incumbent suppliers asymmetric pricing power over NHS Supply Chain and EKAP procurement frameworks. This geographic concentration enables premium tier suppliers to defend margins through MDR-certified traceability systems while standard-tier competitors face cost compression from centralized contract negotiations.
Pricing Analysis
German tertiary care clusters pay 15-25% premiums over Polish secondary facilities for identical instrument specifications, reflecting MDR compliance cost absorption and logistics density advantages. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and sterilization cycle tolerance, with RFID-tracked sets commanding brand premiums. Pricing pressure stems from NHS procurement collaboratives aggregating consumable spend across Midlands and North West acute trusts. Group purchasing organizations exhibit highest price sensitivity; university hospitals with research budgets show lowest.
Supply Chain Analysis
Tariff exposure between Germany and post-Brexit UK dominates supply chain risk planning for instrument manufacturers serving dual markets. Production concentrates in Germany, Switzerland, and Italy, drawing from stainless steel feedstock anchored in European smelter networks. Nickel and chromium input cost volatility from energy-intensive smelter operations creates margin vulnerability. Distribution runs through regional logistics hubs maintaining temperature-controlled warehousing for sterilization-sensitive consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe hospital supplies function as a regulatory-entrenchment market where MDR certification timelines create switching costs that protect incumbent positions. Network effects concentrate in group purchasing organization contract capture, where vendor list consolidation rewards early compliance investment.
For Market Incumbents: Entrench position through notified body certification capacity expansion and backward integration into stainless steel instrument forging. Medtronic PLC and B. Braun Melsungen AG should prioritize EKAP and NHS Supply Chain contract renewal ahead of MDR transition completion. Threat substitution from reusable device refurbishment programs in French public hospitals demands counter-positioning through single-use kit innovation.
For New Entrants and Emerging Players: Build out presence in Poland and Romania surgical suite modernization projects financed through EU cohesion funds, where premium instrument supplier penetration remains limited. Target ambulatory surgical centers in Polish private clinic chains as the most penetrable segment. Go-to-market angle: AI-enabled diagnostic peripherals bundled with disposable biosensor contracts for remote patient monitoring expansion.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sterilization consumables specialists with manufacturing integration in Central Europe over capital equipment vendors facing extended replacement cycles. Long-term viability rests on MDR compliance infrastructure as a durable moat. Acquisition target archetype: notified body-certified consumables manufacturers with NHS Supply Chain contract presence. Signal to watch: notified body capacity expansion announcements from TÜV SÜD and BSI Group as inflection indicator for certification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR recertification priority unlocks EKAP and NHS contract eligibility before competitor portfolios clear. |
| Hospital System Partnership | RFID-tracked instrument sets with real-time sterilization verification secure multi-year German cluster agreements. |
| Software Companion Development | AI-enabled imaging integration differentiates diagnostic equipment in Lombardy and Emilia-Romagna hub tenders. |
| Backward Integration into Forging | In-house stainless steel instrument production insulates margins from nickel price volatility at European smelters. |
| Reimbursement Strategy | Telemedicine platform qualification under NHS remote monitoring frameworks expands post-acute disposable biosensor demand. |
Research Methodology
The analysis maps surgical instruments, consumables, diagnostic equipment, and sterilization supplies, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies. Primary interview insights triangulate against secondary sources including EMA MDR guidance documents, NHS Supply Chain tender databases, BfArM certification records, and hospital procurement cooperative contract disclosures. Bottom-up product-level demand estimates reconcile with top-down healthcare expenditure allocations across member states.
Assumption sets held EU MDR transition timelines and notified body capacity constraints fixed while varying hospital consolidation pace and AI diagnostic reimbursement pathway development. Segmentation dimensions modeled include product durability tier, delivery channel structure, end-user facility type, and technology maturity level. CAGRs derive from replacement cycle analysis and procurement volume aggregation trends. Forecast inputs incorporate stainless steel price trajectory assumptions and group purchasing organization contract renewal patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private equity-backed consumables roll-ups would shift outcomes. Macroeconomic deviation in healthcare budget allocations, regulatory acceleration of REACH chemical restrictions, or breakthrough AI diagnostic reimbursement decisions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
NPWT Canisters Market
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
Cerumen Removal Market