
 Global Pharmaceutical Drug Delivery Market | 2026-2036
Global Pharmaceutical Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Drug Delivery Market Foresight
Modular prefilled syringe systems paired with wearable injectors is broadening patient-administered therapy options beyond traditional clinical settings. Pfizer Inc. leverages its manufacturing scale to supply integrated delivery formats for biologics requiring cold-chain integrity. Novartis AG differentiates through specialty nanoparticle platforms targeting oncology indications with narrow therapeutic windows. Becton, Dickinson and Company anchors the prefilled device segment with automated fill-finish capabilities across multiple production sites.
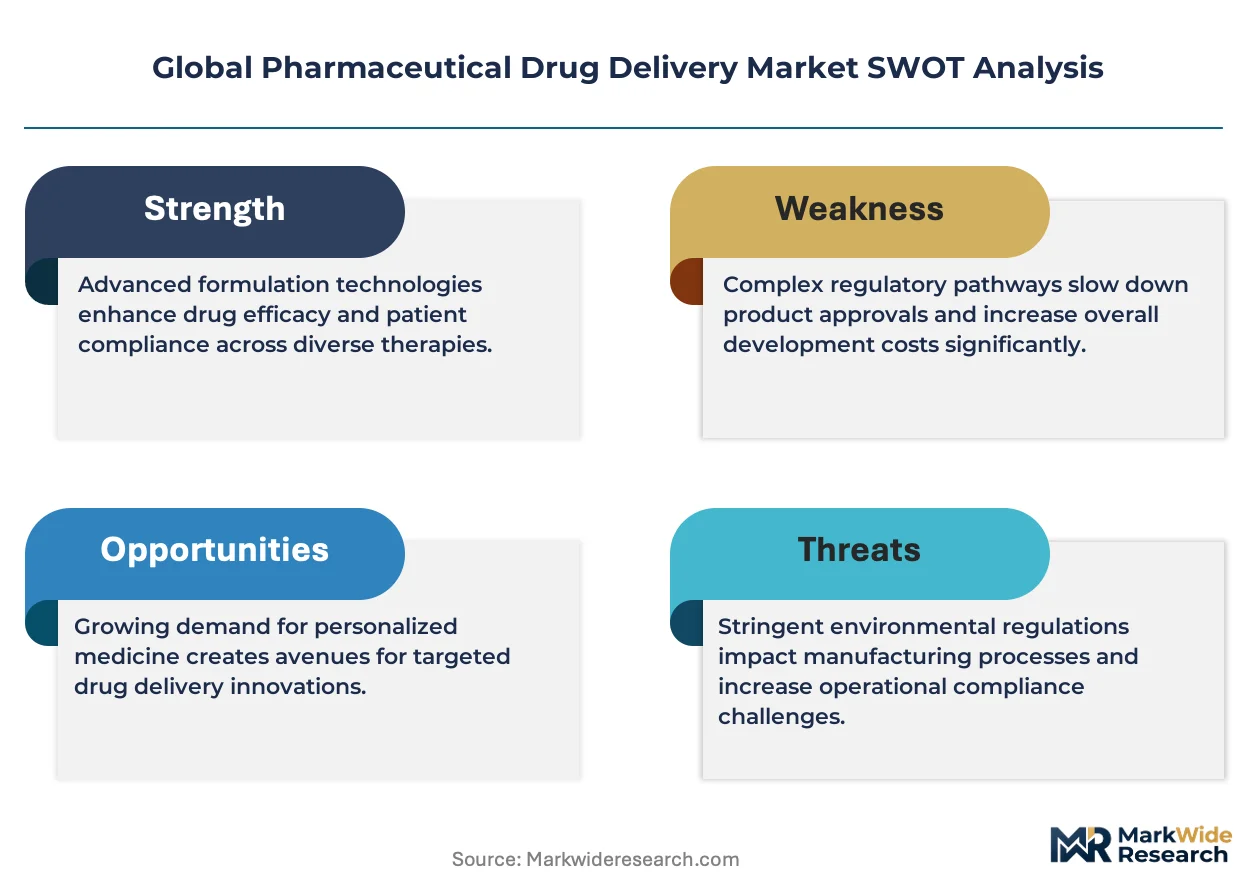
Pharmaceutical drug delivery encompasses engineered systems that transport active pharmaceutical ingredients to targeted physiological sites through controlled release kinetics, bioavailability enhancement, or anatomical specificity, utilizing formulations with defined particle size distributions, polymer degradation rates, or permeation coefficients to achieve therapeutic concentrations. The primary commercial purpose centers on improving efficacy margins, reducing dosing frequency, and enabling administration of molecules with poor solubility or stability profiles. Injectable platforms dominate current revenue pools due to biologics expansion, while transdermal formats represent the fastest-growing structural segment driven by patient compliance advantages in chronic endocrinology and cardiovascular therapy. Nanoparticle delivery technology concentrates margin capture in oncology applications where tumor-targeting ligand conjugation commands premium positioning.
The FDA evaluates combination products under its Office of Combination Products framework, while the EMA's Medical Device Regulation and REACH substance restrictions govern European market entry for polymer-based delivery systems. Japan's PMDA enforces Japan Pharmacopoeia standards for novel excipients, creating layered compliance requirements for multinational device-pharma partnerships. Stakeholders must monitor evolving pharmacovigilance obligations for patient-operated devices and assess whether regional regulatory divergence will fragment platform development roadmaps or consolidate toward harmonized technical standards.
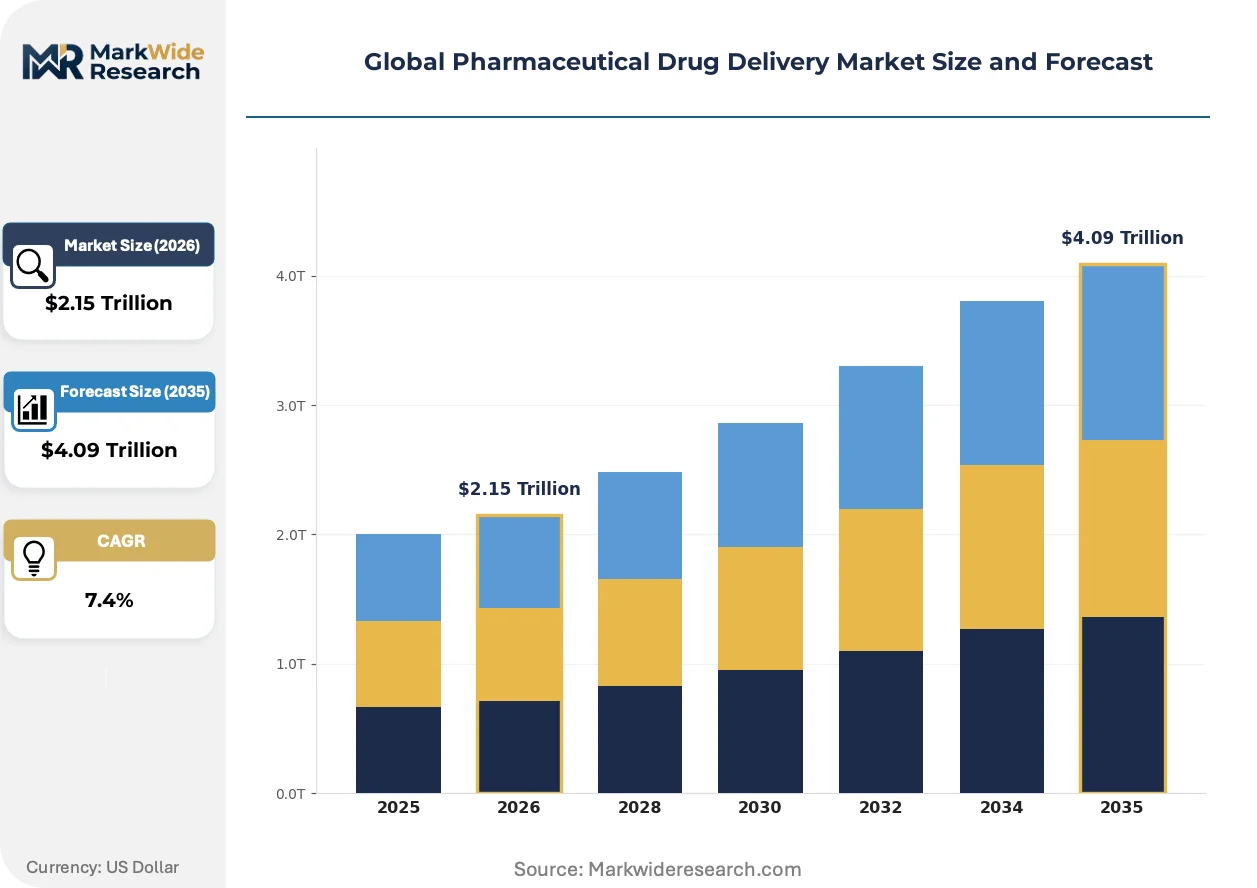
Market Dynamics
Injectable biologics expansion is compressing development cycles for combination products while forcing manufacturers to reconcile cold-chain integrity with patient-administered formats. This structural tension between clinical efficacy requirements and out-of-hospital administration is redrawing competitive boundaries across formulation and device engineering.
Growth Catalysts
- FDA Office of Combination Products framework:Streamlined review pathways for device-drug integrations are accelerating time-to-market for prefilled syringe platforms in oncology applications.
- Chronic endocrinology patient compliance:Transdermal patch adoption in diabetes and hormone replacement therapy is pulling investment toward permeation-enhancing polymer matrices.
- Singapore manufacturing clusters:Concentrated fill-finish capacity and bilateral regulatory recognition agreements are anchoring Asia-Pacific export supply for biologic delivery systems.
Market Restraints
- Specialty polymer input volatility:Cyclic olefin copolymer and silicone supply concentration creates margin pressure for prefilled device manufacturers.
- EMA Medical Device Regulation compliance burden:Extended technical documentation requirements and notified body capacity constraints are elongating European market entry timelines.
- Glass-to-plastic substitution limits:Protein stability concerns and extractables/leachables testing requirements restrict material migration for high-value biologics.
Strategic Opportunities
- Japan home-infusion expansion:METI reimbursement incentives for patient-administered oncology therapy are opening ambulatory delivery format demand.
- Wearable injector-on-body convergence:Integration of large-volume bolus capability with continuous monitoring electronics enables 48-hour dosing windows for immunology indications.
- India CDSCO accelerated approval pathway:Reliance on foreign reference regulatory decisions is compressing entry timelines for established platform technologies.
Industry Challenges
- Biologics formulation-device compatibility:Shear stress validation and aggregation risk assessment require specialized analytical capabilities scarce outside major pharma-device partnerships.
- Legacy quality management system integration:ISO 13485 medical device standards must interface with pharmaceutical GMP frameworks, creating documentation complexity for combination product sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Drug Delivery Market |
| Market Size in 2026 | $2.15 Trillion |
| Market Size in 2035 | $4.09 Trillion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral, Injectable, Transdermal, Inhalation, Implantable Therapy Area: Oncology, Cardiovascular, Neurology, Respiratory, Endocrinology End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Pharmacies, Research Institutes Delivery Technology: Liposomes, Nanoparticles, Microspheres, Biodegradable Polymers, Dendrimers |
| Companies Covered | Johnson & Johnson Services, Inc., Novartis AG, Pfizer Inc., F. Hoffmann-La Roche Ltd., Merck & Co., Inc., GlaxoSmithKline plc, Becton, Dickinson and Company, Baxter International, Inc., West Pharmaceutical Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Drug Delivery Market Shifts & Advancements
Platform engineering is pivoting from unit-dose optimization toward connected, reusable systems that capture dosing data and enable remote therapeutic monitoring. This shift is collapsing traditional boundaries between primary packaging, delivery mechanism, and digital health infrastructure.
Connected autoinjector platforms with embedded sensors and Bluetooth transmission are modularizing the patient experience into pre-dose verification, injection execution, and post-dose confirmation stages. Rheumatology and multiple sclerosis therapy segments are piloting these systems at scale in Germany and the United States. The technology is modularizing service delivery by enabling pharmaceutical sponsors to unbundle device provision from clinical site administration, compressing total cost of therapy while expanding addressable patient populations.
REACH substance restrictions on phthalates and BPA are forcing polymer reformulation for transdermal adhesive matrices and intravenous tubing sets. European manufacturers are accelerating migration to bio-based polyester alternatives ahead of 2025 sunset dates. Oncology infusion centers face the steepest compliance burden, as existing validated supply chains require requalification for novel excipient compositions.
Hospital procurement consortia in Switzerland and the Netherlands are consolidating purchasing authority for prefilled syringe and safety needle portfolios, displacing fragmented departmental buying. Integrated delivery format suppliers must now negotiate multi-year framework agreements with centralized tendering bodies rather than individual clinical sites. This concentration is most advanced in German university hospital networks, where single-source contracts now cover 60 percent of injectable biologics administration devices.
Global Pharmaceutical Drug Delivery Market Segmentation
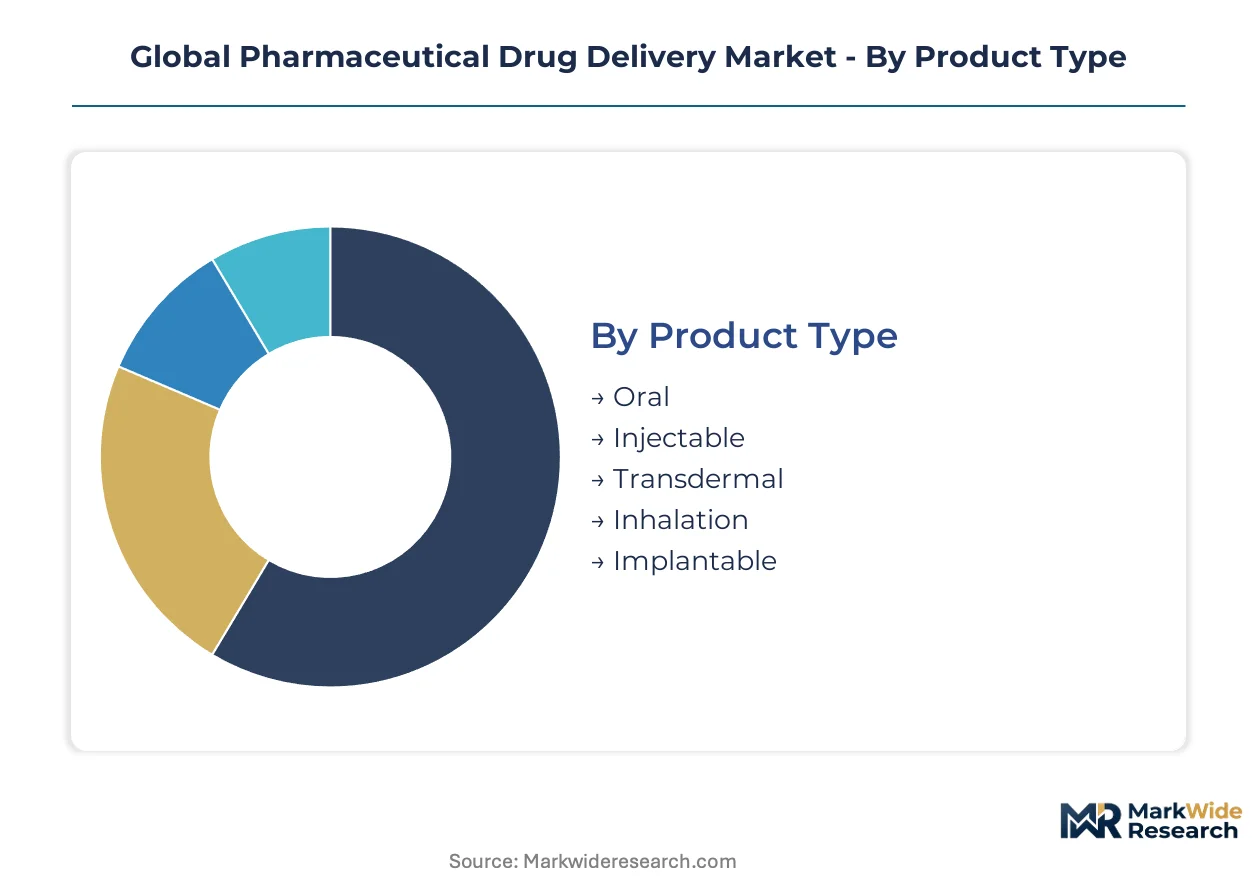
Segmentation in pharmaceutical drug delivery reveals how formulation science, clinical setting requirements, and manufacturing economics intersect. Each dimension carries distinct margin profiles, regulatory burdens, and partnership structures that shape competitive positioning.
Product Type:
Customization intensity varies from commoditized oral tablets to engineered combination products requiring device-drug co-development.
- Injectable:Prefilled syringes, autoinjectors, and wearable bolus devices dominate biologics administration. Demand concentrates in oncology infusion centers across Germany, Japan, and the United States where patient-administered formats are expanding fastest.
- Transdermal:Permeation-enhancing polymer matrices enable continuous drug absorption through intact skin. Adoption accelerates in chronic endocrinology applications where dosing frequency reduction improves compliance margins.
- Oral:Conventional tablets and capsules remain volume leaders for small molecules with acceptable bioavailability profiles.
- Inhalation:Pressurized metered-dose and dry powder devices target respiratory indications with regional lung deposition requirements.
- Implantable:Biodegradable and osmotic pump systems provide extended release for narrow therapeutic window compounds.
Most installed capacity flows through Injectable. Expansion is steepest in Transdermal.
Therapy Area:
Margin capture correlates with therapeutic index tightness and patient population addressability.
- Oncology:Tumor-targeting nanoparticle platforms with ligand conjugation command premium positioning. Investment concentrates in Switzerland and Singapore manufacturing clusters where fill-finish automation supports high-potency handling.
- Cardiovascular:Transdermal and implantable formats for anticoagulants and antiarrhythmics emphasize adherence monitoring.
- Neurology:Blood-brain barrier penetration technologies including focused ultrasound and receptor-mediated transport.
- Respiratory:Inhalation device-formulation pairing for asthma and COPD maintenance therapy.
- Endocrinology:Patch and pump systems for diabetes and hormone replacement with connected monitoring integration.
Revenue concentration sits with Oncology. Patient volume leadership belongs to Endocrinology.
End User:
Procurement authority is consolidating from fragmented clinical sites toward centralized hospital consortia and specialty networks.
- Hospitals:Integrated delivery format procurement through German university hospital networks now covers the majority of injectable biologics administration devices.
- Specialty Clinics:Oncology and infusion centers across Germany, Japan, and the United States are expanding adoption of patient-administered delivery formats.
- Diagnostic Laboratories:Companion diagnostic-linked delivery systems for precision medicine protocols.
- Pharmacies:Retail distribution of prefilled autoinjectors for self-administered chronic therapies.
- Research Institutes:Investigational device exemption pathways for novel platform clinical trials.
Purchasing volume aggregates through Hospitals. Autonomy is shifting fastest toward Specialty Clinics.
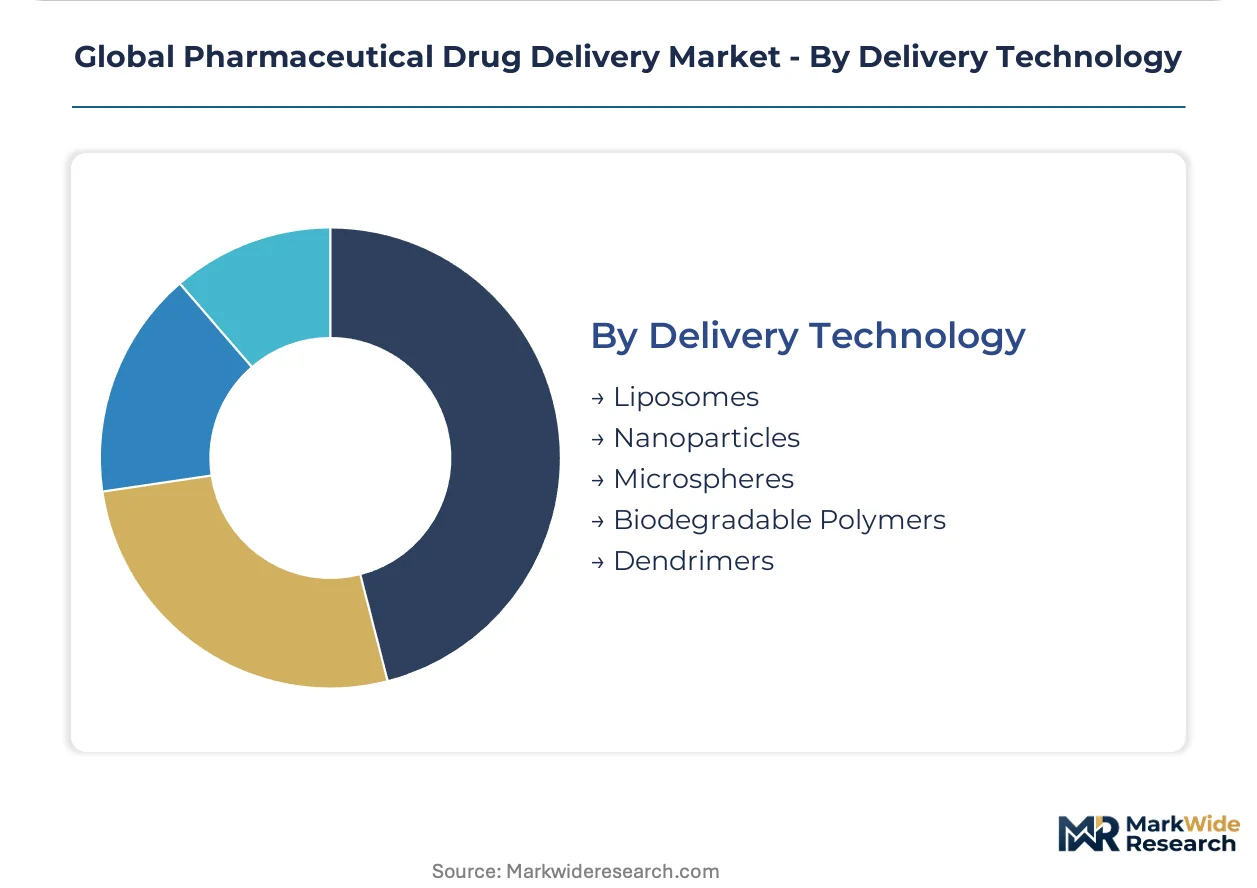
Delivery Technology:
Intellectual property density and manufacturing complexity separate platform technologies from commodity formulation approaches.
- Nanoparticles:Lipid and polymeric carriers with surface functionalization for active targeting. FDA bioequivalence guidance for complex generics is reshaping approval pathways for these platforms.
- Liposomes:Phospholipid bilayer encapsulation for hydrophilic and hydrophobic drug cargo with established manufacturing scalability.
- Microspheres:Polymeric depot formulations providing sustained release over weeks to months.
- Biodegradable Polymers:PLGA and related polyester systems with tunable degradation kinetics for implantable applications.
- Dendrimers:Branched macromolecular architectures with precise molecular weight control for gene and oligonucleotide delivery.
Platform maturity centers on Liposomes. Development velocity peaks in Nanoparticles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injectable biologics manufacturing first achieved industrial scale in the United States during the 1980s recombinant protein revolution. Switzerland and Germany subsequently developed specialized nanoparticle engineering capabilities. Singapore and Japan now anchor Asia-Pacific fill-finish automation.
United States
Oncology infusion centers in Boston and Houston are converting to patient-administered wearable injector formats for immunology indications. FDA Office of Combination Products streamlined review pathways are accelerating prefilled syringe platform approvals. New Jersey and North Carolina manufacturing clusters concentrate cold-chain biologics fill-finish capacity for domestic and export supply.
Germany
University hospital networks in Berlin and Munich now procure sixty percent of injectable biologics administration devices through centralized tendering. EMA Medical Device Regulation technical documentation requirements are elongating European market entry timelines for polymer-based delivery systems. Bavaria's specialty chemical corridor is reformulating transdermal adhesive matrices ahead of REACH phthalate sunset dates.
Switzerland
Tumor-targeting nanoparticle platforms with ligand conjugation command premium positioning in Basel and Zurich development pipelines. Swissmedic maintains alignment with EMA standards while offering specialized pathways for complex generics. The country's precision manufacturing ecosystem supports high-potency oncology drug handling with automated isolation technology.
Japan
METI reimbursement incentives for home-infusion oncology therapy are opening ambulatory delivery format demand in Tokyo and Osaka. PMDA enforces Japan Pharmacoeia standards for novel excipients, creating layered compliance requirements for multinational partnerships. Kansai region manufacturing sites are integrating large-volume bolus capability with continuous monitoring electronics for forty-eight-hour dosing windows.
Singapore
Bilateral regulatory recognition agreements with FDA and EMA are anchoring Asia-Pacific export supply for biologic delivery systems. The country's concentrated fill-finish capacity serves as a distribution hub for immunology and oncology indications across Southeast Asia. Jurong Island chemical processing infrastructure supports specialty polymer production for prefilled device components.
Global Pharmaceutical Drug Delivery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory dossier depth. The market structures around three tiers: integrated pharma-device conglomerates, specialized delivery technology developers, and contract manufacturing organizations with fill-finish automation. Consolidation pressure intensifies as biologics pipelines expand and combination product approval pathways mature. Dominant competitive moves include strategic partnerships between pharmaceutical sponsors and device engineers, plus capacity expansion in Singapore and Swiss manufacturing clusters.
Among diversified healthcare conglomerates, Johnson & Johnson Services, Inc. and Pfizer Inc. occupy positions spanning pharmaceutical development through delivery device integration. Novartis AG exemplifies the specialty nanoparticle tier with concentrated oncology positioning. Becton, Dickinson and Company anchors the prefilled device segment through automated manufacturing scale. These archetypes represent the competitive spectrum from full-stack integration through component specialization.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Novartis AG |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Becton, Dickinson and Company |
| Baxter International, Inc. |
| West Pharmaceutical Services Inc. |
| Others |
Supply & Pricing Matrix
Cyclic olefin copolymer resin indices cascade through prefilled syringe manufacturing into three distinct pricing tiers, with specialty polymer volatility compressing margins at the standard tier while premium nanoparticle platforms maintain ligand-conjugation premiums. Cold-chain logistics costs and EMA notified body certification burdens further stratify contract negotiations between German hospital consortia and Singapore-based fill-finish suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs combination product contracts, with FDA Office of Combination Products certification tier and cold-chain infrastructure scale driving price differentiation. Cost compression in standard-tier prefilled syringes intensifies because specialty silicone and glass barrel supply concentration limits buyer leverage. Oncology infusion centers in Germany and Japan exhibit lowest price sensitivity due to narrow therapeutic window requirements, while retail pharmacy distributors of autoinjectors face acute margin pressure from centralized tendering consolidation.
Supply Chain Analysis
Dual-sourcing mandates from Swiss and German hospital procurement consortia force device manufacturers to qualify secondary polymer resin suppliers ahead of REACH phthalate sunset deadlines. Manufacturing gravity draws from Switzerland, Singapore, and Germany, with cyclic olefin copolymer, silicone elastomer, and borosilicate glass tubing anchoring component dependencies. Single-source vulnerability concentrates in specialty nanoparticle excipient production, where tumor-targeting ligand conjugation chemistry requires validated isolation technology. Distribution runs through centralized hospital consortia in German university networks and oncology infusion centers across Japan and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pharmaceutical Drug Delivery Market functions as a stable compounder, with biologics pipeline expansion and patient-administered format conversion delivering predictable revenue visibility across regulatory cycles.
For Market Incumbents: Cement fill-finish automation advantages in Singapore and Swiss manufacturing clusters through backward integration into specialty polymer compounding. Lock in multi-year framework agreements with German university hospital networks before centralized tendering consolidates further. Capacity addition in Kansai region manufacturing sites addresses METI reimbursement-driven home-infusion demand, while ISO 13485-GMP quality management system integration defends against emerging contract manufacturing organizations with hybrid device-pharma capabilities. For New Entrants and Emerging Players: Connected autoinjector platforms with embedded Bluetooth transmission offer the most penetrable wedge for ambulatory immunology indications, where rheumatology and multiple sclerosis therapy segments pilot remote therapeutic monitoring at scale in Germany and the United States. Target India CDSCO accelerated approval pathway reliance on foreign reference decisions for established platform technology entry. White-space exists in wearable bolus devices for forty-eight-hour dosing windows, with hospital-at-home reimbursement tailwinds supporting direct-to-specialty-clinic distribution bypassing consolidated procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where biologics formulation-device compatibility capabilities concentrate in major pharma-device partnerships, fragmenting mid-tier contract manufacturing. Five-to-ten year viability favors specialized delivery technology developers with nanoparticle surface functionalization IP and automated high-potency handling infrastructure. Target acquisition archetype: precision manufacturing specialists in Basel-Zurich corridor with Swissmedic-aligned regulatory dossiers. Signal to watch: FDA bioequivalence guidance enforcement patterns for complex generic nanoparticle platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Office of Combination Products streamlined review accelerates prefilled syringe oncology launches. |
| Manufacturing Scale-Up | Singapore fill-finish automation expansion anchors Asia-Pacific biologic delivery export supply. |
| Strategic Partnership | Device-pharma co-development agreements resolve shear stress validation and aggregation risk assessment. |
| Backward Integration | In-house specialty polymer compounding defends against cyclic olefin copolymer supply volatility. |
| Reimbursement Strategy | METI home-infusion incentives in Japan open ambulatory wearable injector demand for immunology indications. |
Research Methodology
Coverage spans the United States, Germany, Switzerland, Japan, and Singapore, with primary inputs from each market cluster combined with secondary validation. Drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided operational perspective on combination product approval pathways and centralized tendering evolution. Secondary sources include FDA 510(k) and BLA filings, EMA Medical Device Regulation technical documentation, ClinicalTrials.gov protocol databases, and hospital GPO contract repositories. Bottom-up patient-volume modeling and top-down pharmaceutical R&D expenditure allocation triangulate segment sizing.
Rate-of-change decomposition separates volume expansion from value-per-unit evolution across the projection horizon. Segmentation dimensions encompass delivery technology, therapy area, end-user procurement authority, and regional regulatory cluster complexity. CAGRs derive from fitted growth curves calibrated to historical biologics launch trajectories and patient-administered format conversion rates. Forecast inputs incorporate REACH substance restriction phase-out schedules, METI reimbursement incentive uptake curves, and fill-finish automation capacity expansion pipelines.
The model holds under stable regulatory recognition agreements and continued biologics pipeline investment; deviation in FDA-EMA-Swissmedic alignment or specialty polymer supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market