
 Plastic Syringes Market | 2026-2036
Plastic Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Syringes Market Analytics
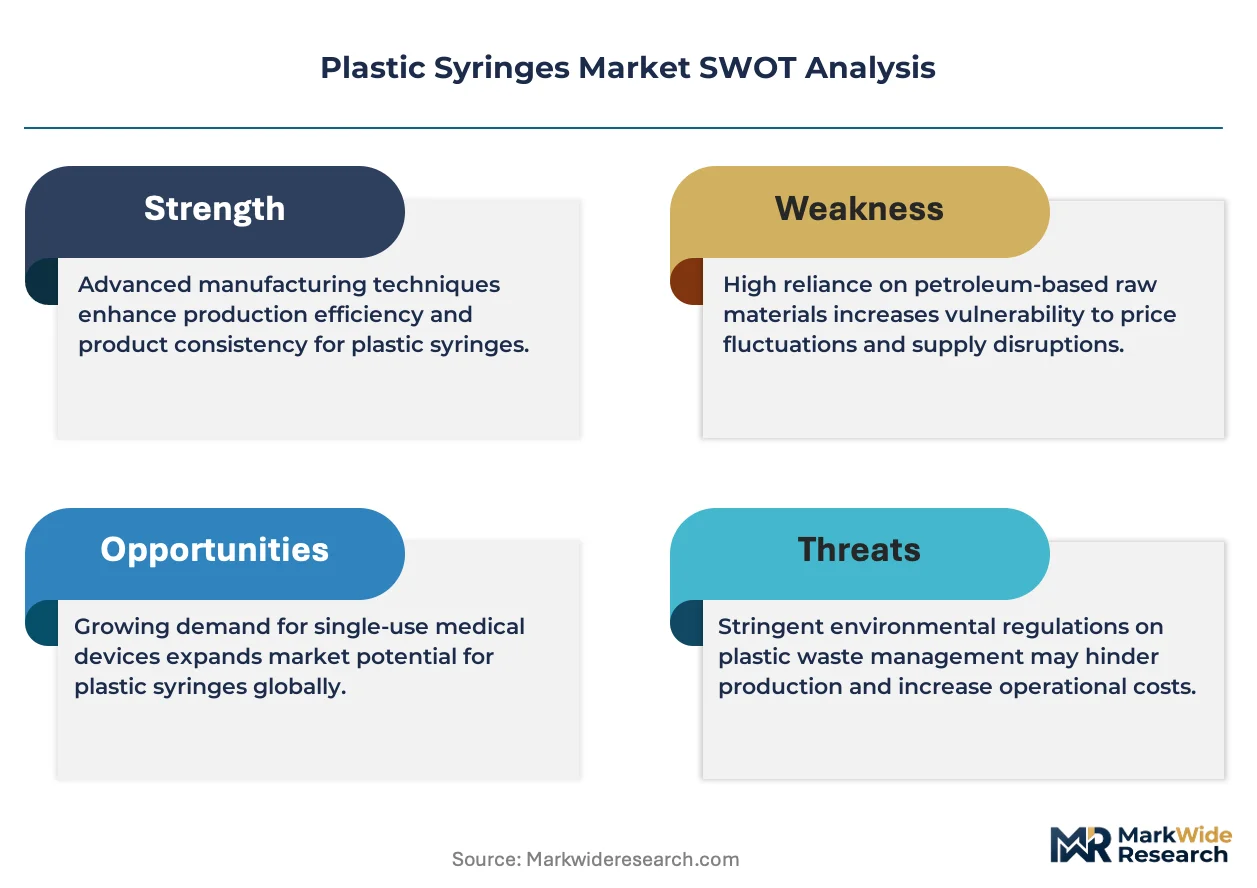
Home care delivery is realigning plastic syringe procurement patterns as diabetes self-management and biologic injectables migrate from clinical settings. Becton Dickinson and Company leverages its safety-engineered portfolio to dominate hospital-system contracts across North America. Terumo Corporation anchors Japanese precision manufacturing standards while competing aggressively in European pre-filled segments. Nipro Corporation specializes in emerging-market volume plays, particularly in immunization and dialysis applications.
Plastic syringes are cylindrical medical devices molded from polypropylene or cyclic olefin polymer, featuring graduated barrels and plunger systems designed for sterile fluid aspiration or injection with precise dose control. Manufacturing relies on high-speed injection molding with subsequent siliconization for plunger glide and terminal sterilization via ethylene oxide or gamma irradiation. Safety and pre-filled categories command premium positioning due to integrated needle retraction mechanisms and pharmaceutical co-development requirements, while standard Luer Lock variants occupy commoditized hospital procurement channels where bulk pricing and supply security determine contract awards.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements govern safety performance validation, with OSHA Bloodborne Pathogens Standard and EU needlestick prevention directives directly mandating retractable or shielded designs in clinical workplaces. India's CDSCO and BIS standards increasingly align with WHO prequalification benchmarks for immunization-grade syringes, tightening market access for uncertified suppliers. Stakeholders must monitor polymer resin cost volatility and shifting sterilization modality preferences as sustainability pressures intensify.
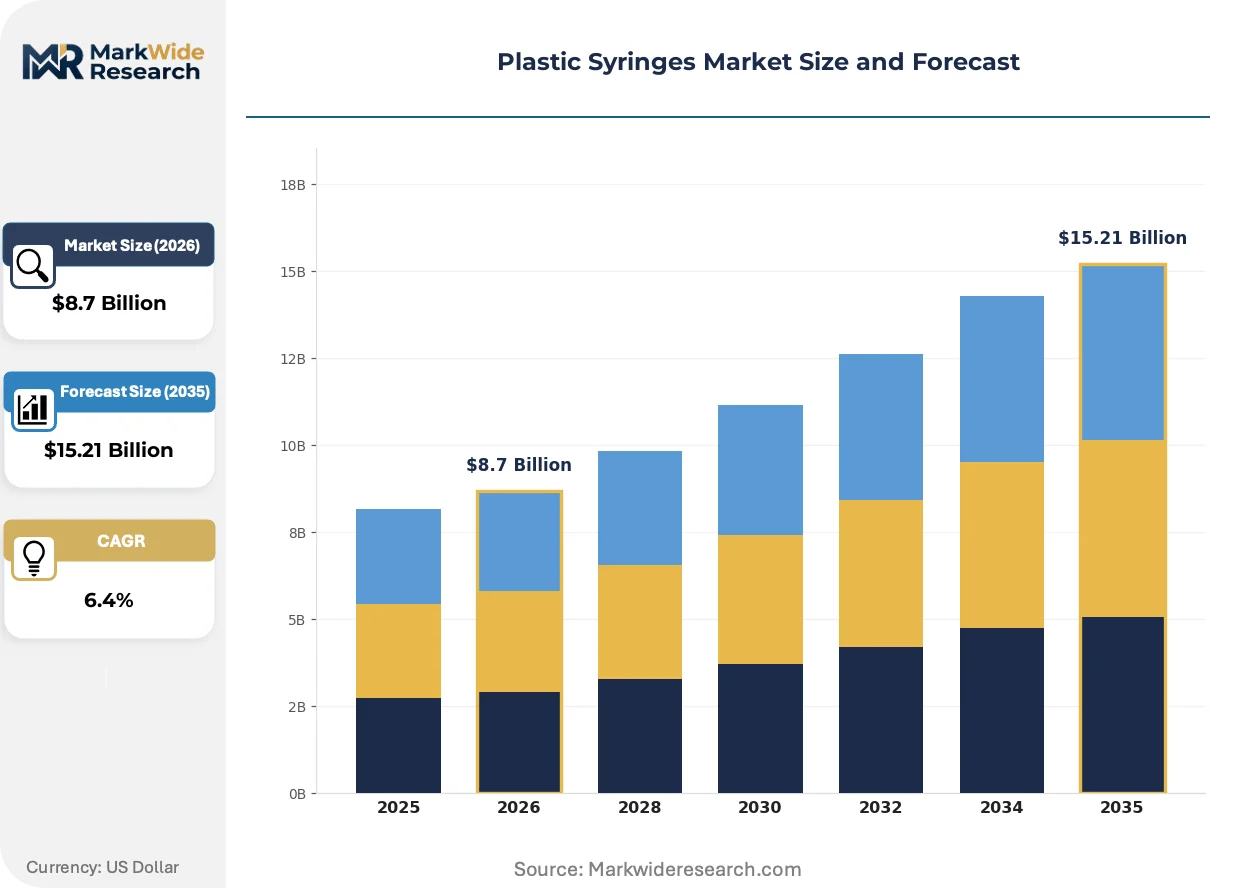
Market Dynamics
Safety-engineered syringe mandates from OSHA and EU MDR are forcing wholesale manufacturing retooling, compressing margins for commoditized standard syringe producers while creating protected pricing tiers for retractable and shielded designs.
Growth Catalysts
- Home-based biologic administration:Diabetes and autoimmune patients now self-inject specialty pharmaceuticals outside clinical settings, expanding addressable syringe volumes beyond traditional hospital procurement channels.
- EU MDR needlestick prevention directives:Mandatory shielded or retractable needle designs in European healthcare workplaces are accelerating safety syringe conversions and premium product adoption.
- Polypropylene resin advances:Cyclic olefin polymer formulations with improved drug compatibility are enabling pre-filled syringe expansion into sensitive biologic formulations previously requiring glass containment.
Market Restraints
- Propylene feedstock volatility:Crude oil and natural gas price swings directly compress molding margins, particularly for high-volume standard syringe producers locked into annual hospital contracts.
- Gamma sterilization capacity concentration:Contract sterilization providers cluster in specific manufacturing corridors, creating geographic bottlenecks during demand surges and regulatory inspection backlogs.
- Glass pre-filled substitution:Pharmaceutical manufacturers retain preference for borosilicate glass in high-value biologics, limiting plastic syringe penetration in the fastest-growing injectable segments.
Strategic Opportunities
- Indian immunization procurement scale:Government tender programs for auto-disable syringes under Universal Immunization Programme create volume anchor demand for qualified suppliers.
- Connected syringe-device convergence:Integration of Bluetooth-enabled dose tracking with disposable syringes opens adherence monitoring revenue streams in clinical trial and chronic disease management applications.
- Amazon Business healthcare distribution:Direct-to-clinic e-procurement platforms are disintermediating traditional medical distributor networks for standard Luer Lock variants.
Industry Challenges
- Safety mechanism validation timelines:FDA 510(k) pathways for novel retractable designs require extensive human factors testing, extending product development cycles to 24-36 months.
- Siliconization process expertise scarcity:Uniform plunger glide coating requires specialized equipment and formulation knowledge concentrated among legacy suppliers, constraining new manufacturing capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Syringes Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable, Standard, Safety, Luer Lock End User: Hospitals, Clinics, Home Care, Pharmaceutical Companies Functionality: Single-use, Multi-use, Pre-filled, Disposable Packaging Type: Blister Packs, Bulk Packaging, Individual Wraps, Sterile Kits |
| Companies Covered | Becton Dickinson and Company, Terumo Corporation, Nipro Corporation, Cardinal Health, Hindustan Syringes & Medical Devices Ltd, B. Braun Melsungen AG, Gerresheimer AG, Retractable Technologies, Inc., Henke-Sass Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Syringes Market Evolving Landscape
Manufacturing automation and material science advances are compressing production economics while regulatory harmonization pressures are standardizing safety performance benchmarks across previously fragmented national approval systems.
Cyclic olefin polymer is modularizing pre-filled syringe architecture by replacing glass in temperature-sensitive biologics requiring cold-chain stability. Specialty pharmaceutical packagers are adopting these polymer barrels for monoclonal antibody formulations. This material shift is modularizing the traditional glass-dominated supply base and enabling plastic converters to capture value previously reserved for borosilicate specialists.
EU MDR Class IIa certification requirements are mandating extensive clinical performance documentation for safety-engineered designs. Manufacturers must now submit human factors validation data and needlestick prevention effectiveness studies. Pre-filled safety syringe categories face the steepest compliance burdens, with European notified bodies imposing 12-18 month review timelines that favor established players with dedicated regulatory affairs infrastructure.
Hospital procurement consolidation is compressing supplier rosters as integrated delivery networks centralize contracting authority. Standard Luer Lock syringe purchasing is migrating toward sole-source agreements with price-volume tiers. This concentration is most visible in United States health systems where GPOs like Vizient and Premier are reducing approved vendor lists from fifteen suppliers to three or four strategic partners.
Plastic Syringes Market Segmentation
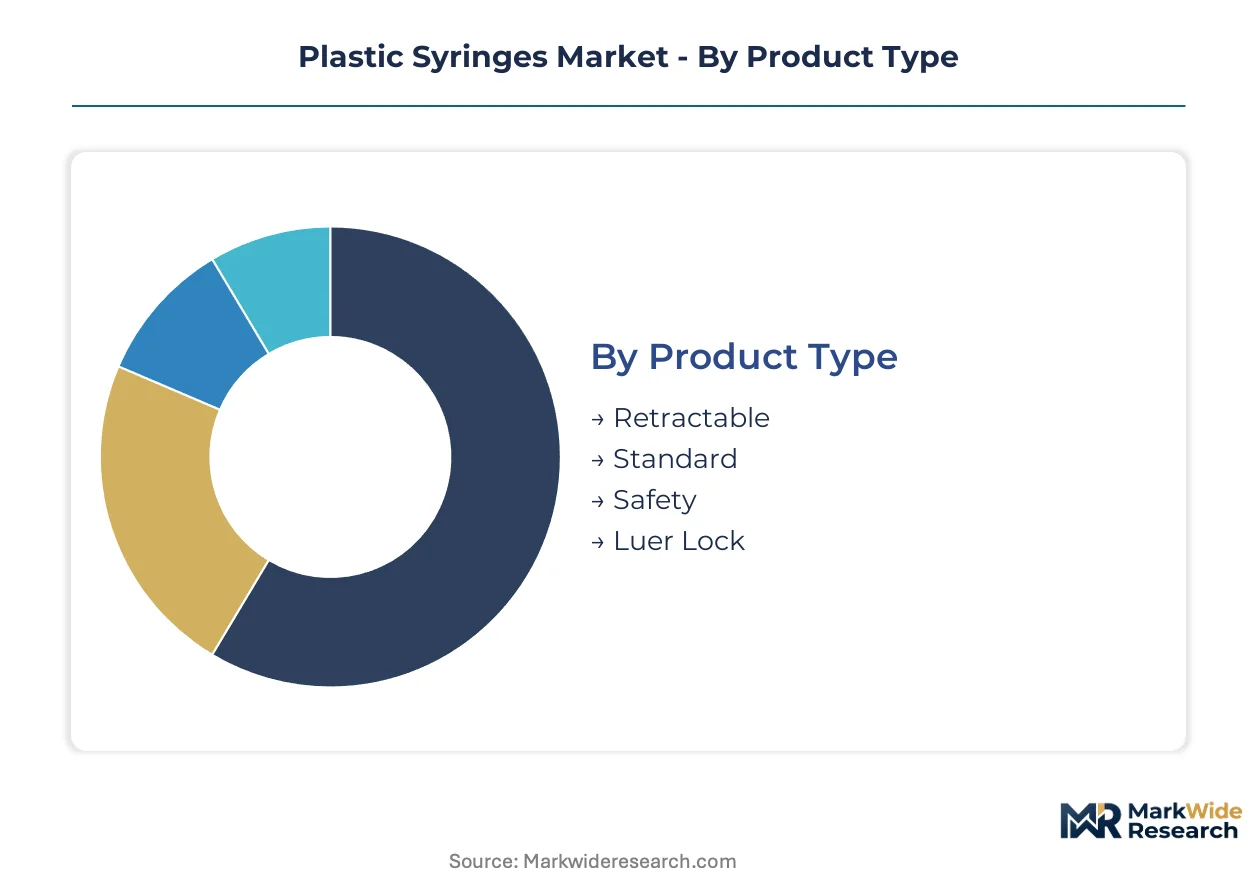
Plastic syringe procurement patterns diverge sharply across clinical settings, with safety mandates reshaping hospital purchasing while home care expansion creates volume opportunities in standard disposables. Material compatibility requirements and sterilization modality preferences further stratify supplier selection criteria across end-use categories.
Product Type:
Hospital procurement teams prioritize needlestick prevention features, while cost-sensitive immunization programs optimize for single-use compliance at scale.
- Safety:Integrated shielding or retraction mechanisms satisfy OSHA Bloodborne Pathogens Standard and EU MDR needlestick directives. European hospital systems and US integrated delivery networks now mandate these designs for clinical staff protection, compressing demand for unshielded alternatives.
- Retractable:Spring-loaded needle retraction systems eliminate post-injection exposure risk entirely. FDA 510(k) pathways require extensive human factors validation, favoring established manufacturers with dedicated regulatory infrastructure over new entrants.
- Standard:Conventional Luer slip designs without integrated safety features serve cost-constrained bulk procurement channels. India's Universal Immunization Programme tenders specify auto-disable variants in this category for single-use compliance.
- Luer Lock:Threaded hub connections prevent needle detachment during high-pressure injections. Dialysis centers and oncology clinics specify these for secure medication delivery.
Standard syringes lead volumes today; safety-engineered variants are gaining share fastest.
End User:
Clinical settings demand validated safety performance, while pharmaceutical packaging partners require material compatibility documentation for biologic formulations.
- Hospitals:Integrated delivery networks consolidate purchasing through GPO contracts emphasizing safety compliance and supply security. OSHA mandates and Joint Commission accreditation standards drive retractable and shielded syringe specifications.
- Home Care:Diabetes self-management and biologic injectable administration outside clinical settings expands addressable volumes. Patients require intuitive designs with minimal training burden.
- Clinics:Outpatient facilities balance cost constraints against staff protection requirements, often selecting shielded designs over premium retractable alternatives.
- Pharmaceutical Companies:Pre-filled syringe co-development partnerships demand cyclic olefin polymer compatibility data and extractables testing for sensitive biologics.
Hospitals anchor current procurement volumes; home care applications are climbing the fastest.
Functionality:
Single-use mandates dominate infectious disease protocols, while multi-use designs persist in specialized veterinary and research applications.
- Single-use:WHO prequalification standards and national immunization programs mandate auto-disable mechanisms preventing reuse. Polypropylene barrels with fixed needles serve high-volume vaccination campaigns.
- Pre-filled:Pharmaceutical manufacturers specify cyclic olefin polymer barrels for temperature-sensitive biologics requiring cold-chain stability. EU MDR Class IIa certification imposes extended validation timelines.
- Disposable:Standard polypropylene designs without safety features serve veterinary, industrial, and research applications where human needlestick risk is absent.
- Multi-use:Glass-barrel designs with replaceable needles persist in specialized laboratory and veterinary settings requiring sterilization between applications.
Single-use configurations dominate current volumes; pre-filled formats show the steepest expansion trajectory.
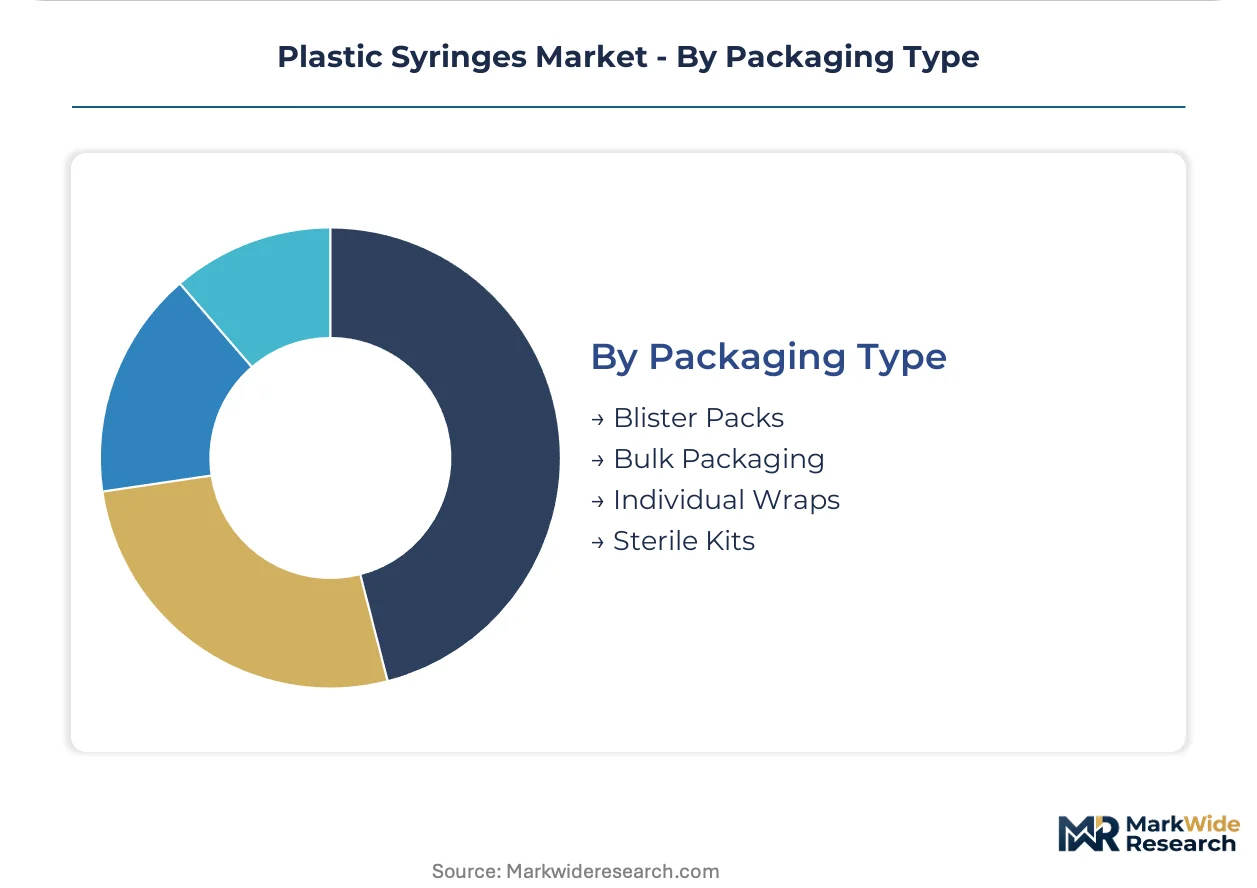
Packaging Type:
Sterility assurance level requirements and point-of-use workflow efficiency determine packaging selection across clinical environments.
- Sterile Kits:Complete procedure packages combining syringes with needles, swabs, and disposal containers streamline operating room workflows. Ambulatory surgery centers specify these for regulatory compliance efficiency.
- Blister Packs:Individual thermoformed compartments protect single units through distribution while enabling unit-dose inventory tracking. Hospital pharmacies favor these for controlled substance accountability.
- Individual Wraps:Pealable pouch packaging balances sterility maintenance against material cost for mid-volume clinical settings.
- Bulk Packaging:Polypropylene bags containing 100 units minimize per-unit cost for high-consumption environments accepting trade-offs in sterility assurance convenience.
Bulk packaging leads volumes today; sterile kits are expanding most quickly in ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's medical device manufacturing corridor anchors plastic syringe production capacity, with clusters in Ahmedabad and Vadodara supplying immunization-grade volumes to government tenders. Regional procurement patterns diverge sharply between safety-mandated hospital systems and cost-optimized vaccination programs.
United States
Integrated delivery networks consolidate purchasing through GPO contracts emphasizing OSHA Bloodborne Pathogens Standard compliance. The FDA 510(k) clearance pathway governs safety-engineered designs, with human factors validation extending development timelines. Manufacturing concentrates in North Carolina's Research Triangle and Massachusetts medical device corridor, where sterilization infrastructure clusters near polymer molding facilities.
Germany
EU MDR Class IIa certification requirements mandate extensive clinical performance documentation for safety syringes. The country's notified bodies impose 12-18 month review timelines that favor established regulatory affairs infrastructure. Baden-Württemberg's precision engineering cluster near Stuttgart hosts specialized siliconization equipment suppliers serving pre-filled syringe manufacturers.
India
CDSCO and BIS standards increasingly align with WHO prequalification benchmarks for immunization-grade syringes. The Universal Immunisation Programme creates volume anchor demand for auto-disable variants. Haryana's Faridabad-Gurgaon corridor and Tamil Nadu's Chennai-Coimbatore belt concentrate domestic molding capacity serving government tender programs.
Japan
PMDA quality management standards enforce rigorous plunger glide consistency and extractables testing protocols. METI industrial policy supports cyclic olefin polymer research for temperature-sensitive biologic applications. The Kansai region around Osaka maintains precision manufacturing heritage serving domestic pharmaceutical packaging partnerships.
Brazil
ANVISA registration requirements for imported medical devices create compliance barriers favoring local assembly operations. The country's national immunization program drives standard disposable volumes through public procurement channels. São Paulo state's medical device free trade zone near Guarulhos concentrates distribution infrastructure for Latin American market access.
Plastic Syringes Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retool lines for safety-engineered variants to satisfy OSHA and EU MDR mandates. The vendor base stratifies across three tiers: integrated multinationals with full regulatory infrastructure, regional specialists capturing immunization tenders, and contract manufacturers serving private-label pharmaceutical partnerships. Two strategic archetypes define competitive positioning: safety-technology leaders commanding premium hospital contracts, and volume-scale operators optimizing for government procurement price points. M&A activity concentrates on sterilization capacity acquisition, while strategic partnerships proliferate between polymer suppliers and pre-filled syringe developers.
Among integrated multinationals, Becton Dickinson and Company represents the safety-engineered archetype with established hospital-system relationships, while Terumo Corporation exemplifies precision manufacturing standards applied to pharmaceutical co-development. Nipro Corporation occupies a position within the emerging-market volume tier, leveraging immunization and dialysis application expertise. Hindustan Syringes & Medical Devices Ltd anchors the government-tender specialist segment, with B. Braun Melsungen AG and Gerresheimer AG representing European regulatory-compliance leadership. Retractable Technologies, Inc. and Henke-Sass Wolf GmbH sit within the niche safety-mechanism innovation space, each exemplifying focused engineering approaches to needlestick prevention.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Terumo Corporation |
| Nipro Corporation |
| Cardinal Health |
| Hindustan Syringes & Medical Devices Ltd |
| B. Braun Melsungen AG |
| Gerresheimer AG |
| Retractable Technologies, Inc. |
| Henke-Sass Wolf GmbH |
| Others |
Value Network & Pricing Analysis
Captive sterilization infrastructure near polymer molding hubs anchors supply positioning and pricing power for safety-engineered syringe producers serving North American and European hospital systems. This geographic bundling of ethylene oxide and gamma irradiation capacity with high-speed injection molding lines insulates integrated manufacturers from contract sterilization bottlenecks that disrupt spot-market suppliers.
Pricing Analysis
Polypropylene resin cost pass-through clauses dominate annual hospital procurement contracts, with propylene feedstock volatility compressing margins for standard Luer Lock producers locked into fixed-price agreements. Three-tier pricing structure across premium, standard, and economy levels separates retractable safety designs from shielded alternatives and commodity disposables. Pricing pressure stems from Indian government tender programs optimizing for auto-disable compliance at scale. Immunization procurement managers exhibit highest price sensitivity; pharmaceutical co-development partners for pre-filled formats show lowest.
Supply Chain Analysis
Specialized siliconization technicians concentrate in Gujarat's Ahmedabad-Vadodara corridor and Germany's Baden-Württemberg precision engineering cluster, constraining new capacity scaling for plunger glide consistency. Manufacturing concentrates in India, China, and the United States for molding operations, with Germany and Japan hosting pharmaceutical-grade pre-filled assembly. Polypropylene resin, cyclic olefin polymer, and medical-grade silicone oil constitute critical input dependencies. Single-source vulnerability runs through concentrated gamma sterilization providers in specific manufacturing corridors. Distribution runs through GPO contracts for hospital systems and direct government tender channels for immunization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in plastic syringes rests on cyclic olefin polymer adoption for temperature-sensitive biologics and connected-device premium tier development, offsetting commodity standard-syringe pricing compression.
For Market Incumbents: Acquire captive sterilization capacity near existing molding facilities to insulate against contract provider bottlenecks and regulatory inspection backlogs. Consolidate siliconization process expertise through specialized equipment acquisition in Gujarat or Baden-Württemberg clusters. Defend hospital-system GPO relationships against Amazon Business disintermediation by embedding safety-engineered portfolios into sole-source agreements with price-volume tiers. For New Entrants and Emerging Players: Bluetooth-enabled dose tracking integration represents the most penetrable technology wedge for clinical trial and chronic disease management applications. Target home care settings with intuitive self-injection designs requiring minimal training burden. Pursue pharmaceutical packaging partnerships for cyclic olefin polymer pre-filled development as glass substitution accelerates in monoclonal antibody cold-chain applications. For Investors and Strategic Acquirers: Consolidation pressure builds where sterilization infrastructure scarcity meets safety-engineered mandate compliance burdens. Long-term viability favors vertically integrated manufacturers with dedicated regulatory affairs infrastructure spanning FDA 510(k) and EU MDR Class IIa pathways. Monitor cyclic olefin polymer adoption rates in pharmaceutical co-development pipelines as inflection indicator for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Safety Mechanism Regulatory Submission | FDA 510(k) clearance for retractable designs protects premium hospital contract access. |
| Cyclic Olefin Polymer Capacity Expansion | Material substitution in temperature-sensitive biologics captures glass-dominated value pools. |
| Connected Device Platform Development | Bluetooth dose tracking opens adherence monitoring revenue in clinical trials. |
| Sterilization Infrastructure Acquisition | Captive ethylene oxide capacity insulates against geographic bottlenecks during demand surges. |
| Indian Immunization Tender Qualification | WHO prequalification alignment secures volume anchor demand from government programs. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract reviews, and pharmaceutical packaging partnership disclosures — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at sterilization service providers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, WHO prequalification registries, and CDSCO immunization tender records. Bottom-up volume modeling across product type, end user, functionality, and packaging format segments was triangulated with top-down market sizing.
Data-stream reconciliation applied across the analysis window modeled safety-engineered conversion rates, home care expansion trajectories, and cyclic olefin polymer substitution patterns in biologic packaging. Segmentation dimensions included product type tier, clinical setting, sterilization modality preference, and regional regulatory cluster. CAGRs were derived from patient population growth in diabetes and autoimmune indications, immunization program scale-up schedules, and safety mandate implementation timelines. Forecast inputs incorporated propylene feedstock cost scenarios and gamma sterilization capacity utilization assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR review timeline extensions, propylene price volatility, and pharmaceutical manufacturer glass retention preferences for high-value biologics. Forecasts reflect documented assumptions regarding safety conversion elasticity and tender program volume allocation. Material deviation in regulatory harmonization progress or polymer substitution rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Lavage Kits Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Smear Mask Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Blood Collection Market
Medical Supplies
Nipple Shield Market