
 Histology and Cytology Consumables Supplies Market | 2026-2036
Histology and Cytology Consumables Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Histology and Cytology Consumables Supplies Market Foresight
Polymer-based mounting media is pivoting away from traditional xylene-dependent formulations in histology consumables, reducing hazardous waste handling costs and improving laboratory safety compliance. Thermo Fisher Scientific leverages its vertically integrated chemical supply chain to control raw material quality for specialty stains. Danaher Corporation anchors its position through automated slide preparation systems that integrate proprietary reagent cartridges. F. Hoffmann-La Roche Ltd differentiates via companion diagnostic workflows that bind cytology consumables to pharmaceutical testing protocols.
Histology and cytology consumables encompass stains, reagents, fixatives, and slides designed for tissue preservation, cellular visualization, and diagnostic interpretation, typically manufactured to ISO 13485 quality standards with pH tolerances within 0.2 units for batch consistency. These products serve pathology, hematology, and oncology diagnostics by enabling microscopic examination of biopsied or exfoliated cellular material. The stains and reagents segment dominates current revenue as specialized immunohistochemistry dyes command premium pricing for rare biomarker detection. Digital imaging technology in cytology represents the fastest-expanding application area as whole-slide scanners displace conventional light microscopy in high-throughput laboratories. Research laboratories constitute the most mature end-user channel with predictable replenishment cycles, while diagnostic centers concentrate margin pools through bundled consumable contracts tied to equipment placements.
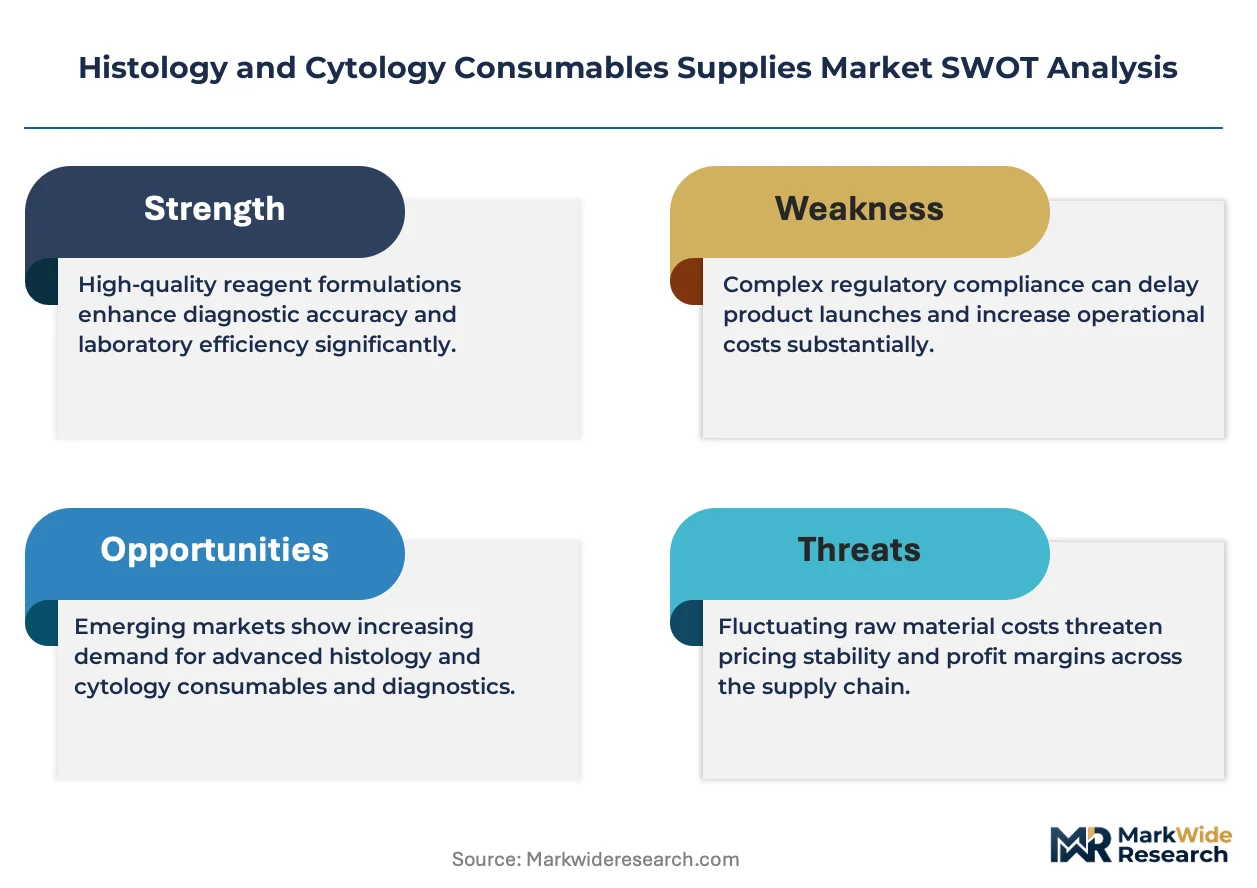
FDA quality system regulations for in vitro diagnostics and the EU In Vitro Diagnostic Regulation (IVDR) mandate traceable manufacturing records and clinical performance documentation for cytology consumables used in cancer screening programs. ISO 15189 accreditation requirements for clinical laboratories in Japan and Germany further tighten procurement standards around stain reproducibility and shelf-life validation. Stakeholders must monitor evolving IVDR conformity assessment timelines and FDA guidance on artificial intelligence-assisted pathology, as these frameworks will determine which consumable suppliers can maintain market access across regulated jurisdictions.
Market Dynamics
Pathology digitization is compressing replenishment cycles for histology consumables as laboratories transition from batch processing to continuous automated workflows, forcing suppliers to reconfigure distribution networks around real-time inventory systems.
Growth Catalysts
- Oncology screening mandates:Germany's statutory health insurance system mandates population-scale cervical cytology screening, creating predictable demand for Pap stain reagents and fixative solutions.
- ISO 15189 laboratory accreditation:Clinical laboratories in Japan pursue this quality standard, tightening procurement specifications for stain reproducibility and traceability documentation.
- Polymer mounting media:These xylene-free formulations reduce hazardous waste disposal costs and improve laboratory safety compliance, accelerating replacement of traditional solvent-based products.
Market Restraints
- Petrochemical feedstock volatility:Specialty stain formulations depend on aromatic hydrocarbon derivatives, exposing margin structures to crude oil price swings.
- IVDR conformity assessment bottlenecks:The European Union's extended transition timelines for in vitro diagnostic regulation create certification backlogs, delaying market entry for new consumable suppliers.
- Fluorescent in situ hybridization substitutes:Molecular cytology techniques reduce reliance on chromogenic stains for certain oncology biomarker detection applications.
Strategic Opportunities
- Companion diagnostic binding:Pharmaceutical testing protocols in the United States create captive demand for cytology consumables tied to specific therapeutic development pipelines.
- Whole-slide scanner integration:High-throughput laboratories seek consumable bundles optimized for digital imaging capture, opening premium pricing tiers for slide preparation systems.
- Artificial intelligence-assisted pathology:FDA guidance development creates first-mover advantage for suppliers capable of validating consumable performance under algorithmic interpretation workflows.
Industry Challenges
- Histotechnologist workforce constraints:Specialized tissue processing expertise shortages in clinical laboratories delay adoption of automated workflows despite equipment availability.
- Legacy light microscopy infrastructure:Capital-intensive replacement cycles for conventional microscope fleets slow uniform digital pathology deployment across hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histology and Cytology Consumables Supplies Market |
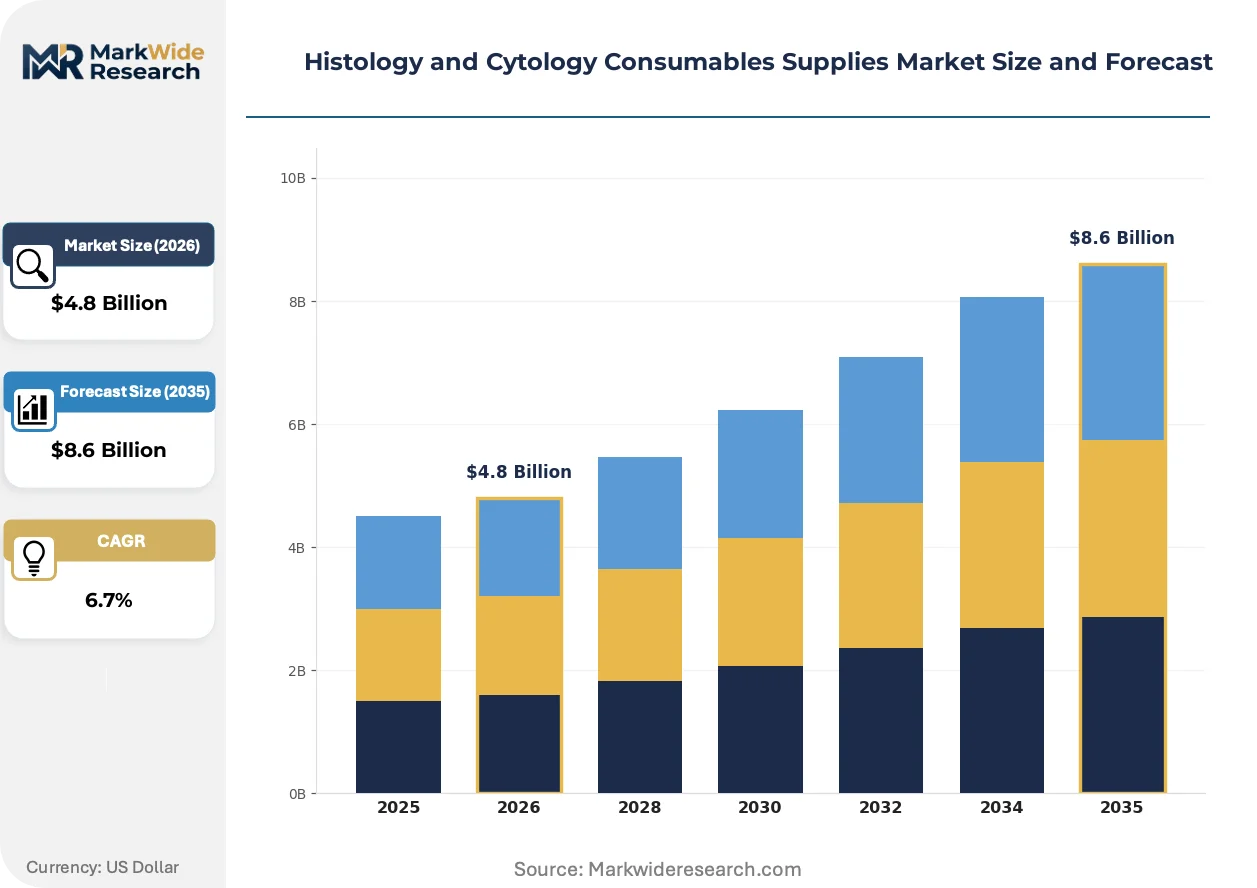
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stains, Reagents, Fixatives, Slides End User: Research Laboratories, Clinical Laboratories, Educational Institutions, Diagnostic Centers Application: Oncology, Hematology, Pathology, Cytogenetics Technology: Microscopy, Digital Imaging, Tissue Processing, Automation |
| Companies Covered | Thermo Fisher Scientific, Inc., Danaher Corporation, Abbott Laboratories, Becton Dickinson and Company, F. Hoffmann-La Roche Ltd, Agilent Technologies Inc., Merck KGaA, PerkinElmer, Inc., Hologic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histology and Cytology Consumables Supplies Market Shifts & Advancements
Automation integration is redefining competitive advantage in histology consumables, with suppliers racing to develop reagent cartridges and slide preparation systems that lock into closed-loop laboratory workflows.
Whole-slide imaging is consolidating diagnostic workflows in high-throughput pathology laboratories. Academic medical centers and regional reference laboratories adopt these systems at accelerated pace, replacing conventional light microscopy for routine case review. The technology is consolidating purchasing authority around integrated consumable contracts that bundle stains, reagents, and slides with scanner maintenance agreements.
REACH chemical registration requirements in the European Union impose substance-by-substance documentation burdens on stain and reagent manufacturers. Industrial consequence includes reformulation of legacy products to eliminate candidate list substances. The stains and reagents segment bears the heaviest compliance cost, with suppliers establishing dedicated regulatory affairs functions in Brussels to manage technical dossier preparation.
Bundled service contracts are displacing transactional consumable purchasing in diagnostic centers. Hospital procurement departments consolidate vendor relationships around multi-year agreements tied to equipment placements. This pattern is most visible in the United States, where integrated delivery networks leverage volume commitments to extract price concessions on specialty immunohistochemistry dyes.
Histology and Cytology Consumables Supplies Market Segmentation
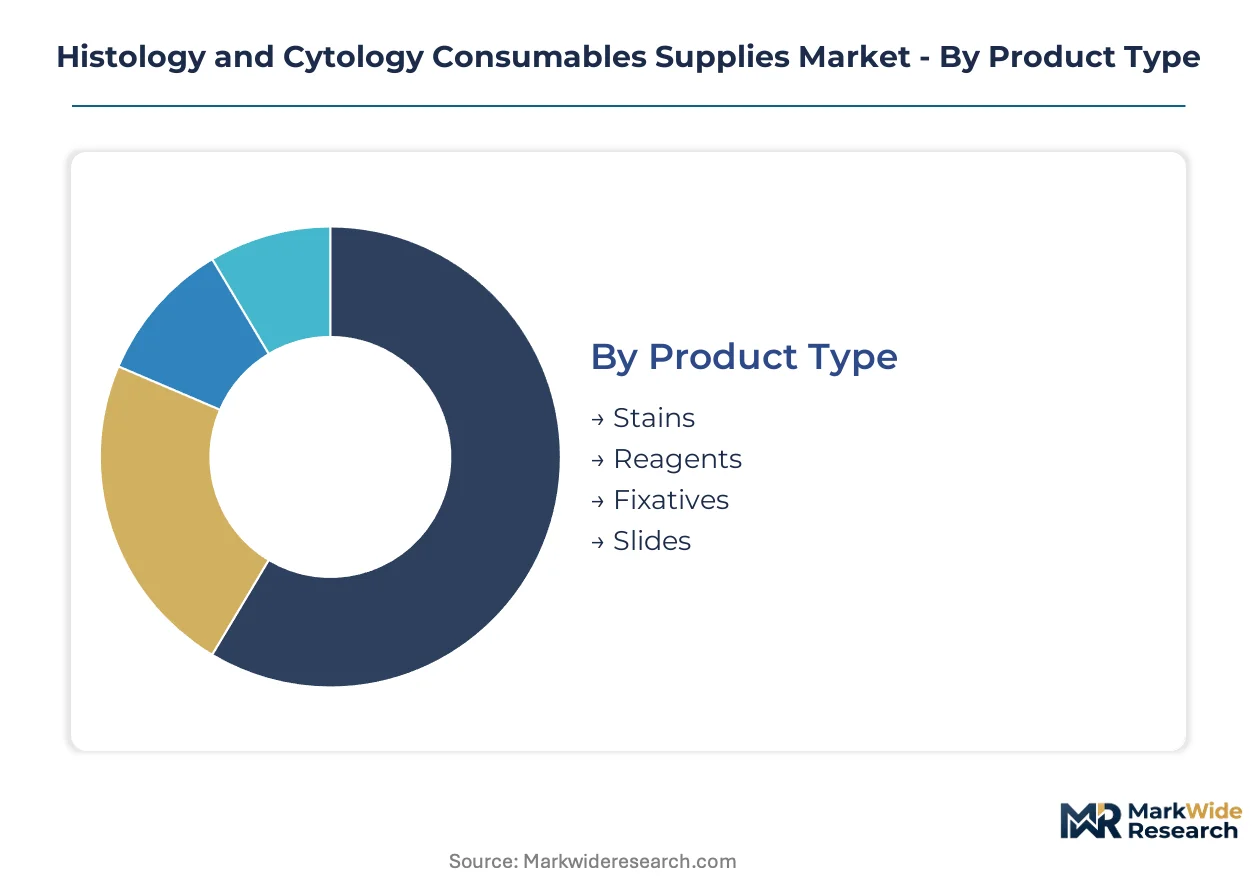
Histology and cytology consumables fragment across four distinct dimensions, each revealing divergent procurement priorities and margin structures. Product type segmentation exposes raw material intensity differentials, while end-user channels separate predictable research replenishment from bundled diagnostic contracting.
Product Type:
Cost tier separates commodity slides from specialty reagents commanding formulation premiums.
- Stains:Chromogenic and fluorescent dye formulations enable cellular visualization with pH tolerances within 0.2 units for batch consistency. Specialty immunohistochemistry stains command premium pricing in oncology applications across Germany and the United States as pathology digitization accelerates biomarker detection workflows.
- Reagents:Chemical solutions for antigen retrieval, blocking, and counterstaining constitute the revenue-dominant segment through recurring consumption patterns. Polymer-based mounting media formulations are displacing xylene-dependent alternatives in clinical laboratories seeking reduced hazardous waste handling costs.
- Fixatives:Formalin and alternative tissue preservation solutions maintain specimen structural integrity during processing.
- Slides:Glass and coated substrates provide mounting surfaces for tissue sections and cellular preparations.
Stains lead volumes today; polymer-based reagents are gaining share fastest.
End User:
Volume concentration shifts from fragmented research procurement to consolidated diagnostic purchasing authority.
- Research Laboratories:Academic and pharmaceutical research facilities generate predictable replenishment cycles with standardized specifications. These buyers prioritize ISO 13485 quality documentation and consistent shelf-life validation for longitudinal study reproducibility.
- Clinical Laboratories:Hospital-based and independent diagnostic laboratories drive automation adoption under FDA quality system oversight for in vitro diagnostics. Japanese clinical laboratories pursuing ISO 15189 accreditation tighten procurement specifications around stain reproducibility and traceability documentation.
- Educational Institutions:University pathology departments and training programs consume entry-level consumable volumes for instructional microscopy.
- Diagnostic Centers:Specialized imaging and pathology service providers consolidate margin pools through multi-year bundled contracts tied to equipment placements.
Research laboratories anchor current volume; diagnostic centers are climbing the fastest through integrated contract expansion.
Application:
Margin structure stratifies by diagnostic complexity and reimbursement intensity.
- Oncology:Cancer screening and biomarker detection applications concentrate demand for high-sensitivity immunohistochemistry stains. Germany's statutory health insurance system mandates population-scale cervical cytology screening, creating predictable demand for Pap stain reagents and fixative solutions.
- Hematology:Blood cell morphology and bone marrow analysis applications require specialized Wright-Giemsa and Romanowsky stain formulations.
- Pathology:General tissue diagnostic workflows span routine histology to complex subspecialty consultations.
- Cytogenetics:Chromosomal analysis applications employ fluorescent in situ hybridization consumables for genetic abnormality detection.
Oncology leads volumes today; cytogenetics shows steepest expansion trajectory as molecular diagnostic integration deepens.
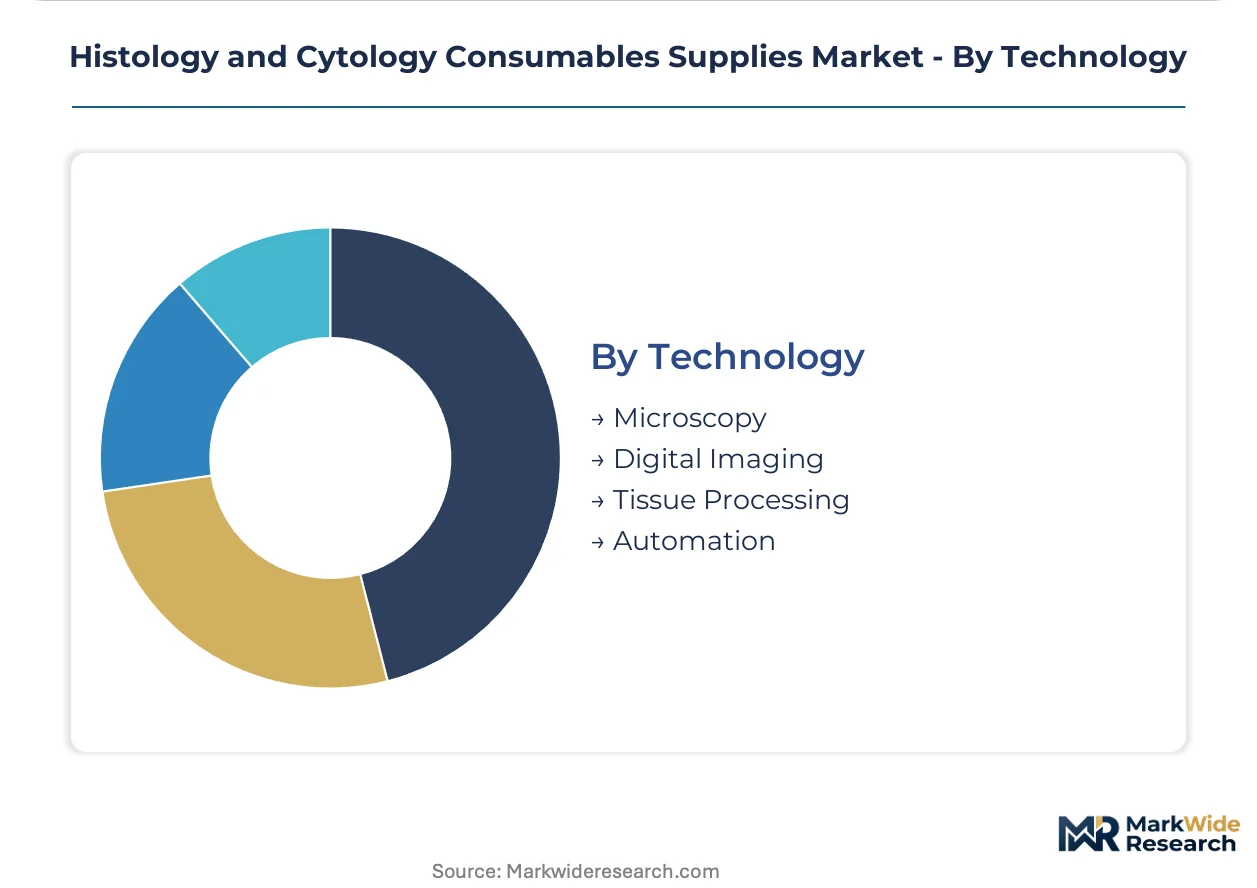
Technology:
Customer type separates legacy microscopy infrastructure from digital imaging adopters.
- Microscopy:Conventional light microscopy consumables serve installed bases of manual slide review systems. Legacy infrastructure replacement cycles slow uniform digital pathology deployment across hospital networks in the United States.
- Digital Imaging:Whole-slide scanner consumables represent the fastest-expanding application area as high-throughput laboratories displace conventional light microscopy. Academic medical centers adopt these systems at accelerated pace, consolidating purchasing authority around integrated consumable contracts.
- Tissue Processing:Automated embedding, sectioning, and staining equipment requires proprietary reagent cartridges and maintenance supplies.
- Automation:Robotic slide preparation and staining systems demand closed-loop consumable integration for workflow continuity.
Microscopy leads volumes today; digital imaging is expanding most quickly through scanner placement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biomedical corridor anchors North American histology consumables demand through dense academic medical center clustering and companion diagnostic development pipelines. Diagnostic digitization accelerates procurement consolidation across four major national markets.
United States
FDA quality system regulations for in vitro diagnostics drive automated tissue processing adoption in clinical laboratories. The agency's evolving guidance on artificial intelligence-assisted pathology creates compliance complexity for stain and reagent suppliers. The Boston-Cambridge corridor concentrates biopharma research demand, while Texas Medical Center anchors high-throughput diagnostic volume in Houston.
Germany
Statutory health insurance mandates for population-scale cervical cytology screening generate predictable Pap stain reagent consumption. ECHA REACH chemical registration requirements impose substance-by-substance documentation burdens on stain manufacturers. The Rhine-Ruhr industrial belt hosts specialty chemical suppliers serving pathology laboratories across Baden-Württemberg and Bavaria.
Japan
ISO 15189 laboratory accreditation requirements tighten procurement specifications for stain reproducibility and traceability documentation. PMDA oversight of in vitro diagnostics aligns with international quality standards. The Kanto region surrounding Tokyo concentrates automated pathology system deployments, while Osaka-Kobe anchors traditional histology service capacity.
China
NMPA medical device regulations increasingly harmonize with international standards for diagnostic consumables. The country's dual carbon goals accelerate xylene-free mounting media substitution in hospital laboratories. The Yangtze River Delta clusters contract research organizations driving cytology consumable volume, while Beijing-Tianjin-Hebei concentrates academic pathology research demand.
United Kingdom
NHS England's pathology consolidation program compresses supplier relationships around integrated consumable contracts. MHRA post-Brexit regulatory autonomy maintains alignment with IVDR technical standards. London and the Southeast concentrate private diagnostic laboratory capacity, while the Midlands hosts distribution infrastructure serving hospital networks.
Histology and Cytology Consumables Supplies Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers seek scanner integration and pharmaceutical protocol binding. The market structures around three tiers: diversified life science conglomerates with chemical supply chain control, diagnostic equipment specialists with closed-loop reagent systems, and regional consumable manufacturers serving price-sensitive segments. Two competitive archetypes prevail—vertically integrated chemical suppliers and automation-integrated platform providers. M&A activity and technology licensing agreements represent the dominant competitive moves as scale advantages harden.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify upstream chemical control married to downstream diagnostic workflow integration. F. Hoffmann-La Roche Ltd occupies a distinct position binding cytology consumables to pharmaceutical companion diagnostic protocols. These three entities represent contrasting strategic postures: chemical supply chain mastery, automation platform lock-in, and therapeutic development pipeline anchoring respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Danaher Corporation |
| Abbott Laboratories |
| Becton Dickinson and Company |
| F. Hoffmann-La Roche Ltd |
| Agilent Technologies Inc. |
| Merck KGaA |
| PerkinElmer, Inc. |
| Hologic, Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between ISO 13485-accredited specialty reagents and commodity consumables manifests in divergent margin structures and supply chain configurations across the United States, Germany, and Japan. Premium immunohistochemistry stains command formulation premiums through controlled chemical supply chains, while standard slides and fixatives compete on scale economics with distributed manufacturing footprints.
Pricing Analysis
Petrochemical feedstock pass-through dynamics anchor pricing volatility for chromogenic and fluorescent dye formulations, with aromatic hydrocarbon derivative costs transmitting directly to stain and reagent price schedules. Three-tier pricing structure across premium, standard, and economy levels separates companion diagnostic-grade consumables from clinical laboratory specifications and educational procurement tiers. Pricing pressure stems from bundled contract consolidation by integrated delivery networks extracting volume concessions on specialty immunohistochemistry dyes. Diagnostic centers demonstrate lowest price sensitivity through equipment-tied multi-year agreements, while educational institutions anchor the economy tier with standardized specifications.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA quality system regulations and ISO 15189 accreditation standards compel clinical laboratories to qualify multiple suppliers for critical stains and reagents, preventing single-source dependency. Manufacturing concentration centers on the United States, Germany, and China, with specialty chemical synthesis anchored in the Rhine-Ruhr industrial belt and polymer-based mounting media production scaling in Chinese hospital laboratory supply chains. Raw material dependencies rest on petrochemical derivatives, optical-grade glass substrates, and pharmaceutical-grade solvents. Tariff exposure on imported reagent chemicals from China presents structural risk to margin stability. Distribution runs through regional laboratory supply distributors serving hospital networks and diagnostic center procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The histology and cytology consumables market functions as a stable compounder, with oncology screening mandates and pathology digitization sustaining predictable replenishment cycles across regulated jurisdictions.
For Market Incumbents: Anticipate molecular cytology substitution pressure from fluorescent in situ hybridization techniques by deepening proprietary reagent cartridge integration with automated slide preparation systems. Lock in diagnostic center purchasing authority through whole-slide scanner bundling contracts that tie consumable replenishment to equipment maintenance agreements. Prioritize backward integration into specialty chemical supply chains to control pH tolerance consistency and batch reproducibility for immunohistochemistry stains. For New Entrants and Emerging Players: Enter via xylene-free mounting media formulations targeting European Union REACH compliance gaps and Chinese hospital laboratory dual carbon goals, where incumbent reformulation lags create procurement opening. Focus initial penetration on educational institutions and regional reference laboratories outside consolidated integrated delivery network contracts. Pursue private-label supply agreements with regional laboratory distributors lacking captive chemical manufacturing capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where automated workflow integration creates captive consumable demand and specialized chemical synthesis expertise concentrates in family-owned European specialty chemical suppliers. The five-to-ten year viability window favors platform providers with closed-loop reagent systems over pure-play consumable manufacturers exposed to price compression. Target acquisition archetypes include regional stain manufacturers with ISO 13485 certification and established pathology laboratory relationships. Monitor FDA guidance development on artificial intelligence-assisted pathology as inflection indicator for algorithmic-optimized consumable validation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Binding | Pharmaceutical protocol integration in the United States creates captive demand tied to therapeutic development pipelines. |
| Polymer Mounting Media Scale-Up | Xylene-free formulation expansion reduces hazardous waste costs and aligns with ECHA REACH substance restrictions. |
| Automated Workflow Integration | Proprietary reagent cartridge development locks consumable replenishment into closed-loop laboratory equipment systems. |
| ISO 15189 Accreditation Support | Traceability documentation and stain reproducibility validation services capture Japanese clinical laboratory procurement. |
| Whole-Slide Scanner Partnership | Consumable bundle optimization for digital imaging capture opens premium pricing tiers in academic medical centers. |
Research Methodology
Multiple input streams — structured interviews with histotechnologists and pathology laboratory directors, procurement database analysis from hospital GPO contracts, and regulatory filing review from FDA and PMDA submissions — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged clinical laboratory managers, biomedical engineers, diagnostic center operations heads, and specialty chemical manufacturing executives across the United States, Germany, Japan, and China. Secondary validation drew from FDA quality system guidance documents, ISO 15189 accreditation standards, ECHA REACH substance registrations, and trade flow data for histology reagent imports.
Data-stream reconciliation across product type, end-user channel, application, and technology segmentation dimensions enabled volume and value modeling throughout the forecast period. CAGRs were derived from segment-level growth rate synthesis anchored to oncology screening mandate implementation timelines and pathology digitization adoption curves. Industry-specific forecast inputs incorporated petrochemical feedstock price indices, automated tissue processing equipment placement data, and companion diagnostic pipeline development disclosures from pharmaceutical sponsors.
Inputs from hospital procurement databases and regulatory submission filings were available through the study window; gaps in real-time inventory system deployment data from private diagnostic laboratories introduce uncertainty bands around automation adoption trajectory assumptions. Deviation in FDA artificial intelligence-assisted pathology guidance timing or IVDR conformity assessment completion rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Sterile Container Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Micro Vials Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Face Mask Market