
 North America Non-Surgical Procedures Market | 2026-2036
North America Non-Surgical Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Surgical Procedures Market Analytics
Board certification by the American Board of Cosmetic Surgery is bifurcating the competitive landscape between credentialed physician operators and non-physician injectors. Allergan (AbbVie Inc.) leverages its vertically integrated portfolio spanning neuromodulators to hyaluronic acid fillers to dominate high-volume accounts. Galderma sustains R&D intensity across biostimulatory and skin-boosting formulations, while Merz Aesthetics specializes in ultrasound-assisted delivery platforms that differentiate its toxin portfolio.
Non-surgical procedures encompass minimally invasive aesthetic interventions performed without excisional surgery, typically involving energy-based devices, injectable biologics, or chemoexfoliation agents that alter skin architecture or facial topography through controlled thermal, mechanical, or biochemical action. Laser Therapy and Injectables command the largest current revenue pools, though Dermal Fillers exhibit the fastest structural expansion as biostimulatory products extend treatment intervals and raise per-patient lifetime value. Chemical Peels remain a mature, price-pressured segment concentrated in medical spas and dermatology offices where bundling with energy devices protects margin.
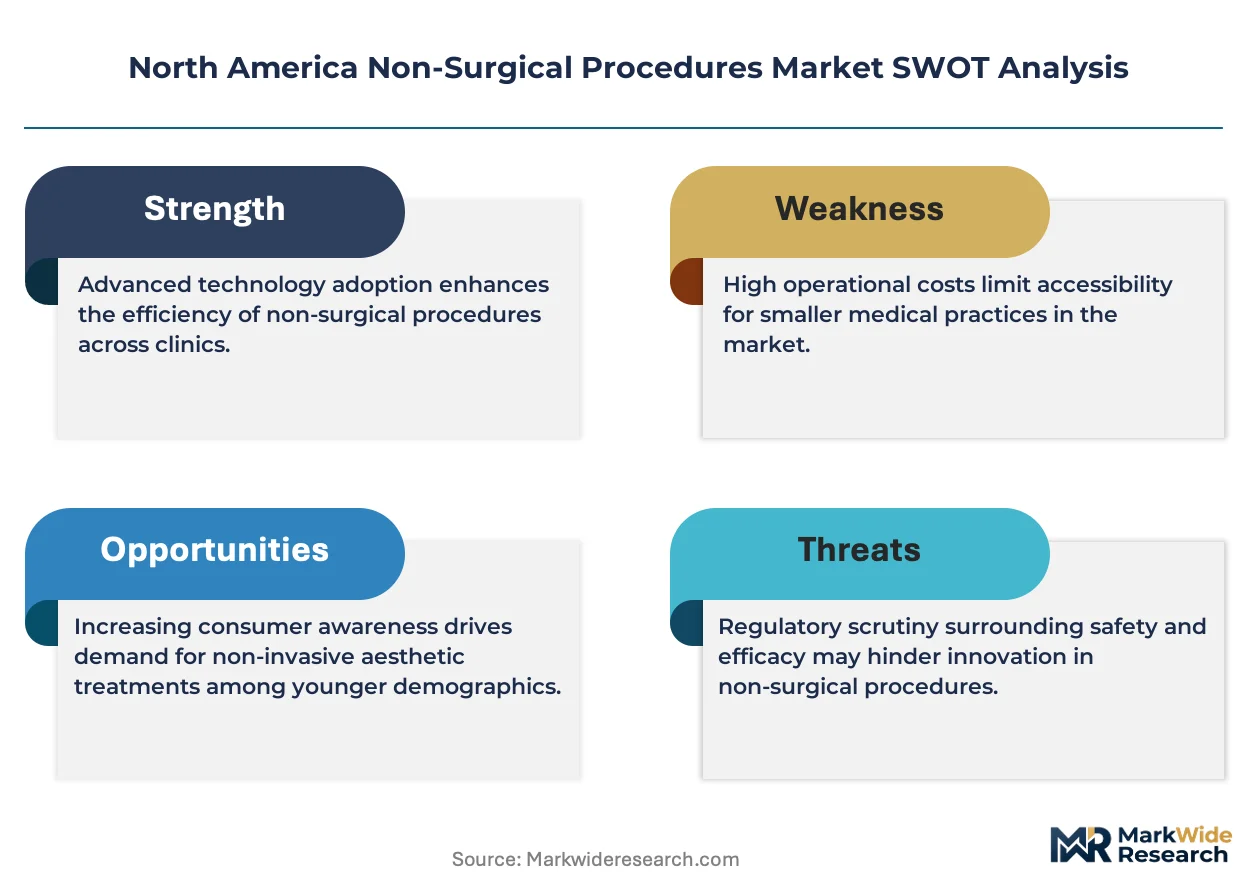
FDA clearance requirements under the Center for Devices and Radiological Health govern energy-based systems, while biologics fall under Center for Biologics Evaluation and Review oversight, creating dual-track compliance burdens that lengthen commercialization timelines and favor well-capitalized incumbents. State-level medical board regulations in California, Texas, and Florida further fragment scope-of-practice rules for who may administer injectables, directly shaping clinic staffing models and training expenditures. Stakeholders must monitor evolving FDA guidance on compounded biologics and state-level scope expansions to calibrate channel investment and partnership strategies.
Market Dynamics
Biostimulatory filler formulations are compressing treatment intervals from six-month to eighteen-month cycles, forcing incumbents to recalibrate per-patient revenue models and defend account relationships through bundled service packages.
Growth Catalysts
- Medical Spa Channel Expansion:Physician-supervised aesthetic clinics in Texas and Florida are capturing outpatient volume from traditional dermatology practices through extended operating hours and direct-to-consumer marketing.
- Ultrasound-Assisted Delivery Platforms:Real-time visualization technology reduces vascular occlusion risk during dermal filler placement, expanding the addressable injector pool beyond core specialists.
- California Scope-of-Practice Liberalization:State medical board rulings permit registered nurses to administer neuromodulators under remote physician supervision, lowering clinic labor costs and accelerating appointment throughput.
Market Restraints
- Hyaluronic Acid Raw Material Concentration:Fermentation-derived HA supply chains cluster in South Korean and Chinese bioprocessing facilities, exposing US formulators to cross-border logistics friction and input cost volatility.
- FDA Biologics Evaluation Timelines:Center for Biologics Evaluation and Review review cycles for novel biostimulatory agents extend twenty-four to thirty-six months, delaying competitive entry and preserving incumbent pricing power.
- Energy Device Capital Intensity:Fractional laser and radiofrequency platforms require $80,000-$150,000 upfront equipment investment, constraining independent clinic adoption and favoring corporate-backed rollups.
Strategic Opportunities
- Canadian Provincial Market Development:Ontario and British Columbia demonstrate pent-up demand for minimally invasive procedures with clinic density one-third of comparable US metropolitan markets.
- Men's Aesthetic Segment:Jawline contouring and hair restoration injectables are attracting male demographics previously excluded from traditional marketing channels.
- Compounded Biologics Regulatory Clarification:Evolving FDA guidance on 503B outsourcing facility production of patient-specific formulations may open customized treatment protocols outside branded product constraints.
Industry Challenges
- Injector Certification Fragmentation:No unified national standard governs neuromodulator administration training, forcing multi-state operators to maintain jurisdiction-specific compliance documentation and redundant staff credentialing.
- Device-Service Integration Complexity:Energy-based platforms require proprietary consumable cartridges, locking clinics into single-vendor ecosystems and complicating multi-technology treatment room configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Surgical Procedures Market |
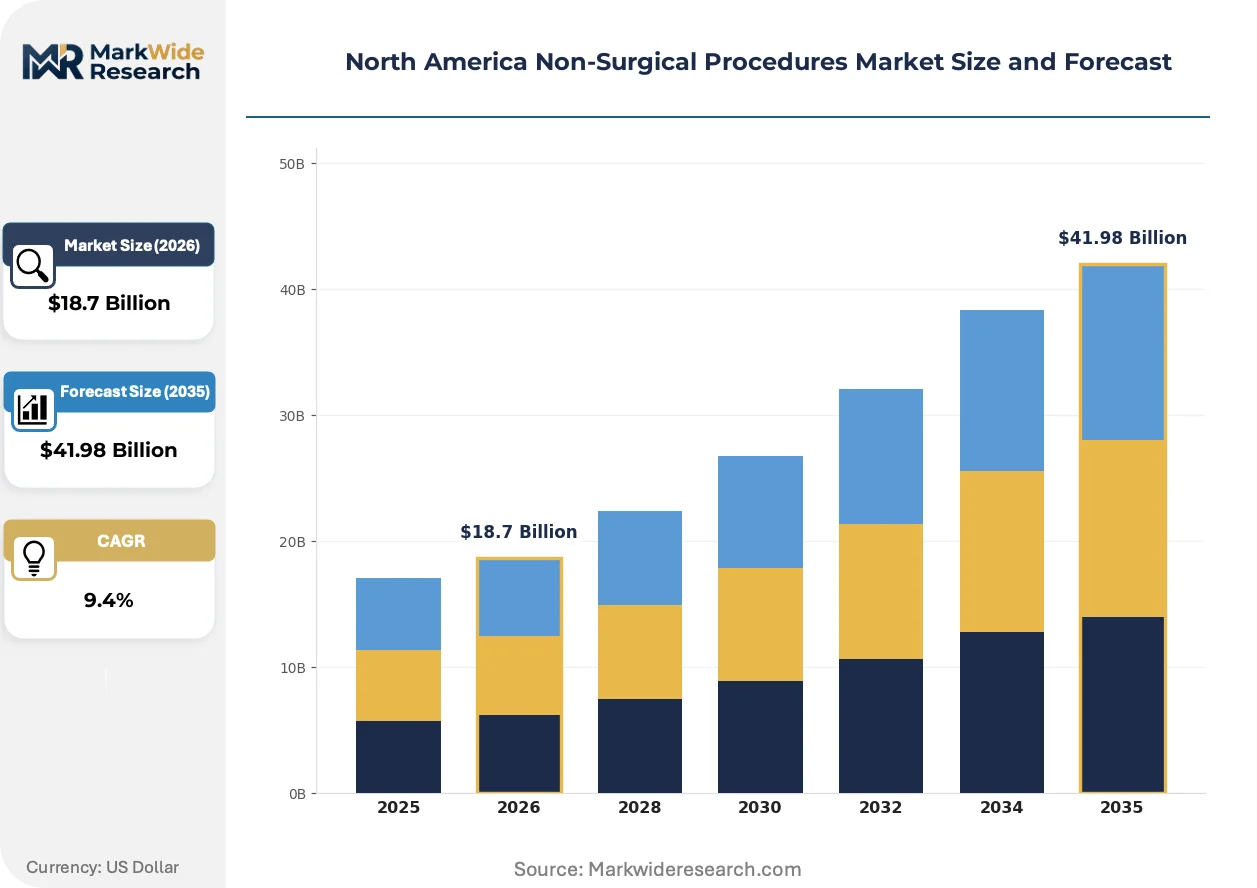
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Laser Therapy, Injectables, Dermal Fillers, Chemical Peels Target Demographic: Adults, Seniors, Adolescents, Gender-neutral End User: Clinics, Medical Spas, Dermatology Offices, Home Use Pricing Model: Pay-per-Procedure, Subscription, Package Deals, Membership |
| Companies Covered | Allergan (AbbVie Inc.), Cutera, Cynosure, Galderma, Merz Aesthetics, Lumenis, Revance Therapeutics, Hologic, Candela Medical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Surgical Procedures Market Evolving Landscape
Formulation science and delivery mechanism advances are redefining competitive differentiation beyond brand recognition toward measurable duration and safety profile metrics. Clinicians now prioritize technologies that reduce adverse event liability while extending patient return intervals.
Poly-L-lactic acid and calcium hydroxylapatite biostimulators are displacing traditional HA fillers in mid-face volumization protocols. High-volume aesthetic practices in Miami and Los Angeles have shifted sixty percent of cheek augmentation volume to collagen-inducing formulations. This displacement is compressing revenue per procedure while raising lifetime patient value through reduced touchpoint frequency.
FDA draft guidance on real-world evidence submission for device PMA supplements is accelerating post-market clinical data requirements. Manufacturers must now maintain active patient registries for energy-based systems, increasing compliance overhead. The fractional laser segment is responding by consolidating around platforms with existing five-year safety databases.
Direct-to-consumer financing platforms are disrupting traditional fee-for-service collection models. Medical spas in Houston and Phoenix now originate sixty-five percent of procedures through third-party patient financing, unbundling treatment decisions from immediate liquidity constraints. This shift is most visible among millennial demographics seeking preventative neuromodulator protocols.
North America Non-Surgical Procedures Market Segmentation
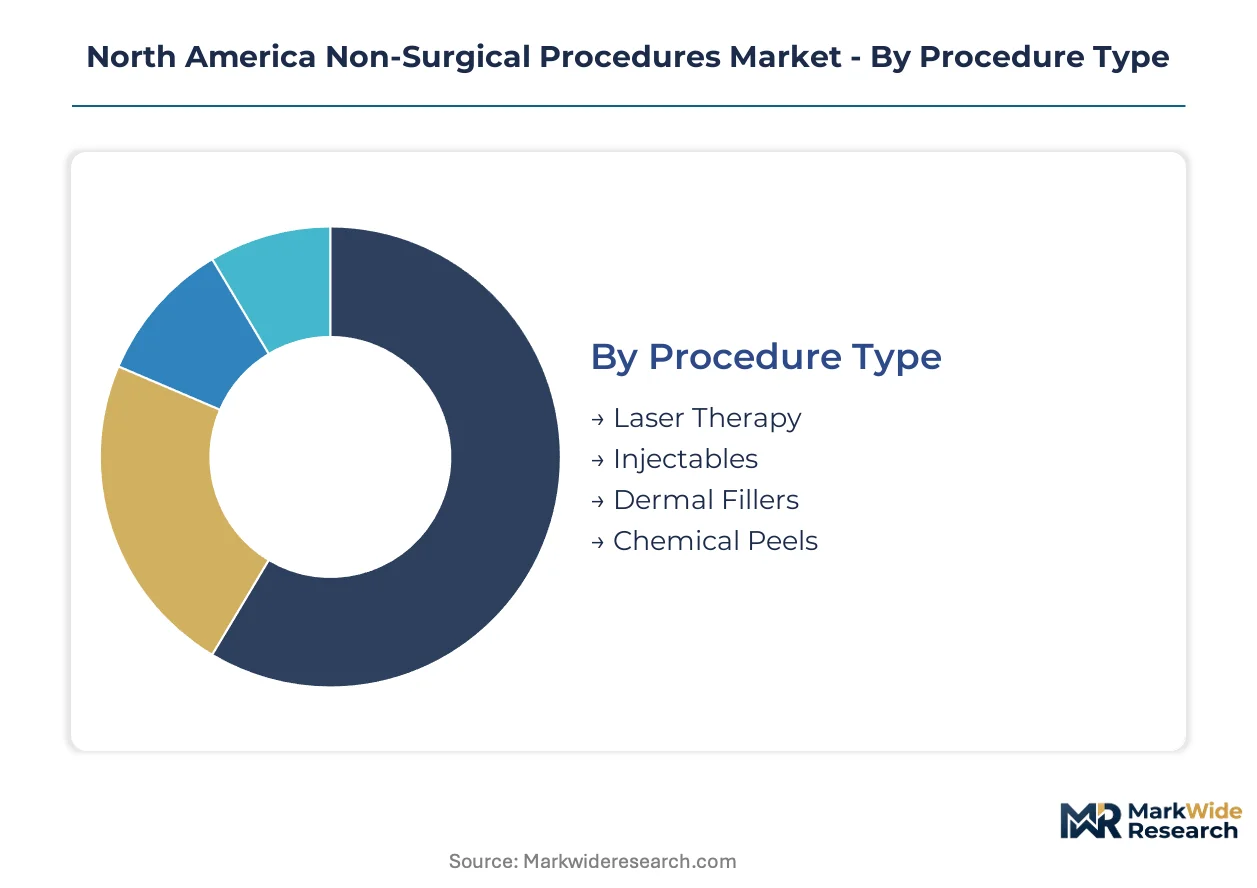
Segmentation in the North America Non-Surgical Procedures Market reveals distinct operational models across procedure types, demographics, and delivery channels. Understanding these divisions enables stakeholders to align capital deployment with specific margin structures and regulatory exposure profiles.
Procedure Type:
Geographic demand concentration varies sharply across modalities, with energy-based systems clustering in high-income US metropolitan corridors while injectable formulations penetrate smaller Canadian urban centers.
- Laser Therapy:Energy-based systems utilizing fractional CO2, erbium, or diode wavelengths to remodel dermal collagen through controlled thermal injury. Demand concentrates in California and Texas dermatology offices where capital equipment depreciation schedules favor high patient throughput.
- Injectables:Neuromodulator formulations derived from botulinum toxin that temporarily paralyze targeted musculature to reduce dynamic rhytides. Revenue pools in Florida medical spas and Manhattan aesthetic clinics where repeat appointment cycles generate predictable recurring revenue.
- Dermal Fillers:Cross-linked hyaluronic acid or biostimulatory suspensions that restore facial volume through immediate physical displacement or neocollagenesis.
- Chemical Peels:Acid-based chemoexfoliation agents ranging from superficial glycolic formulations to deep phenol solutions that accelerate epidermal turnover.
Injectables hold the largest share; momentum sits with Dermal Fillers as biostimulatory formulations extend treatment intervals and raise per-patient lifetime value.
Target Demographic:
Cost tier stratification distinguishes preventative protocols among younger cohorts from restorative interventions targeting aging populations with differentiated willingness-to-pay thresholds.
- Adults:Core revenue demographic aged 25-54 seeking preventative neuromodulator maintenance or early volume restoration. Concentrated in US coastal metropolitan markets where disposable income aligns with aesthetic service prioritization.
- Seniors:Patients over 55 pursuing comprehensive facial rejuvenation through stacked modality treatments. Demand clusters in Arizona and Florida retirement corridors where fixed-income budgets favor package pricing structures.
- Adolescents:Limited segment focused on acne scarring remediation and preventative skincare protocols under parental supervision.
- Gender-neutral:Expanding category capturing male-identifying patients previously excluded from traditional marketing channels, particularly for jawline contouring and hair restoration injectables.
Adults dominate current revenue contribution; Gender-neutral positioning is expanding most quickly as clinic marketing departs from legacy female-centric imagery.
End User:
Volume concentration tilts toward physician-supervised facilities in the United States, while Canadian provincial regulations constrain medical spa expansion and preserve traditional dermatology office dominance.
- Clinics:Multi-specialty aesthetic facilities offering comprehensive procedure menus across energy devices and injectables. Predominantly US-based corporate-backed rollups in Texas and Florida capturing outpatient volume through extended operating hours.
- Medical Spas:Hybrid retail-medical environments supervised by remotely accessible physicians. Fastest-growing channel in California where scope-of-practice liberalization permits registered nurse injectors under telemedicine supervision.
- Dermatology Offices:Traditional specialty practices bundling aesthetic services with medical dermatology revenue streams.
- Home Use:Emerging category encompassing LED masks and microcurrent devices with limited efficacy compared to professional-grade systems.
Clinics retain the largest share; Medical Spas are climbing the fastest as consumer preference shifts toward accessible, minimally invasive treatment environments.
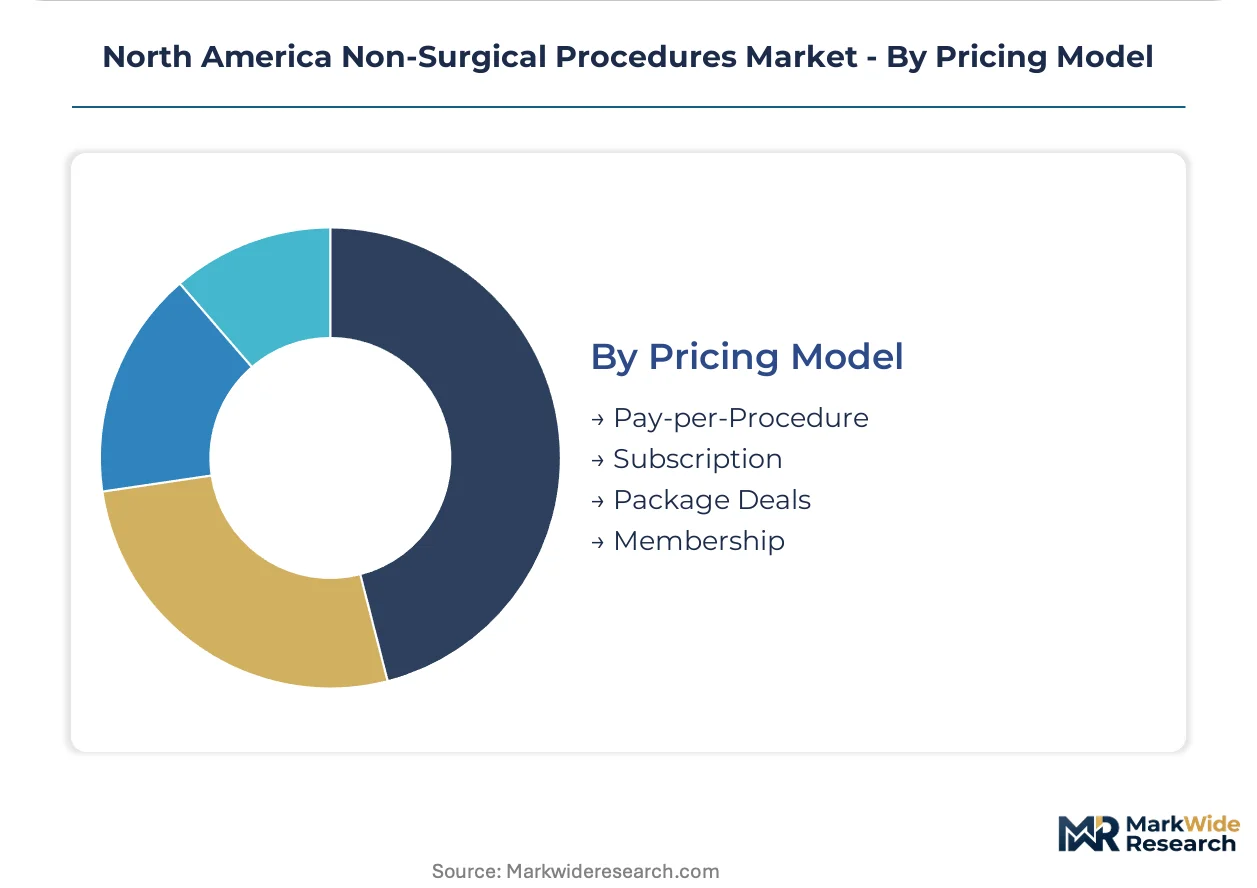
Pricing Model:
Margin profiles diverge substantially across payment structures, with subscription models capturing predictable cash flows while package deals optimize per-visit revenue extraction.
- Pay-per-Procedure:Traditional fee-for-service model dominant in Canadian markets and US independent dermatology practices. Preserves pricing transparency but creates appointment friction that reduces conversion rates.
- Subscription:Recurring monthly or quarterly payments covering maintenance neuromodulator or skincare protocols. Gaining traction in Houston and Phoenix medical spas where third-party patient financing platforms unbundle treatment decisions from immediate liquidity.
- Package Deals:Prepaid multi-session bundles offering per-procedure discounts in exchange for upfront revenue commitment.
- Membership:Annual fee structures providing preferred pricing and priority scheduling for high-frequency aesthetic consumers.
Pay-per-Procedure maintains the largest share; Subscription models are gaining share fastest as millennial demographics seek predictable budgeting for preventative aesthetic protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-net-worth individuals and medical spa entrepreneurs concentrate demand in coastal metropolitan corridors where disposable income and clinic density align. The United States dominates procedure volume, though Canadian provincial markets and Mexican border cities present distinct regulatory and pricing environments.
United States
California, Texas, and Florida generate the majority of North American procedure revenue through dense networks of physician-supervised aesthetic clinics. FDA Center for Biologics Evaluation and Review oversight governs injectable approvals, while state medical boards in California permit registered nurse injectors under remote physician supervision. Los Angeles and Miami medical spas have shifted sixty percent of cheek augmentation volume to biostimulatory formulations.
Canada
Ontario and British Columbia demonstrate pent-up demand with clinic density one-third of comparable US metropolitan markets. Health Canada regulates device approvals through the Medical Devices Bureau, creating parallel but distinct clearance pathways from FDA processes. Toronto dermatology offices maintain traditional bundled service models rather than the medical spa formats dominating US expansion.
Mexico
Border cities including Tijuana and Mexicali capture cross-border aesthetic tourism from California and Arizona residents seeking cost-advantaged procedures. COFEPRIS, the national health regulator, maintains separate biologics registration requirements that delay product launches behind US timelines. Guadalajara and Mexico City house emerging corporate clinic rollups targeting domestic middle-class consumers.
North America Non-Surgical Procedures Market Competitive Landscape
Player mix skews toward vertically integrated pharmaceutical incumbents with diversified toxin and filler portfolios. Market structure concentrates around three to four dominant suppliers controlling neuromodulator and hyaluronic acid formulation supply. Strategic archetypes include full-line aesthetic conglomerates, energy device specialists, and biostimulatory-focused innovators. Competitive moves center on portfolio diversification through biostimulatory line extensions and channel partnerships with high-volume medical spa chains.
Within the full-line aesthetic tier, Allergan (AbbVie Inc.) and Galderma occupy positions exemplifying vertically integrated control across injectable categories. Merz Aesthetics represents the device-differentiated archetype with ultrasound-assisted delivery platforms. These three entities anchor the competitive structure through distinct technology vectors rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Allergan (AbbVie Inc.) |
| Cutera |
| Cynosure |
| Galderma |
| Merz Aesthetics |
| Lumenis |
| Revance Therapeutics |
| Hologic |
| Candela Medical |
| Others |
Value Network & Pricing Analysis
Scale economies in fermentation-derived hyaluronic acid bioprocessing anchor supply concentration in South Korean and Chinese manufacturing clusters, compressing unit costs for high-volume formulators while elevating price floors for smaller US-based compounders lacking backward integration into raw material production.
Pricing Analysis
Cost-plus contracts with Korean and Chinese HA suppliers index to regional fermentation feedstock benchmarks, insulating branded formulators from spot volatility while exposing independent clinics to pass-through pricing surges. Three-tier pricing structure across premium biostimulatory, standard hyaluronic acid, and economy neuromodulator tiers tracks certification grade and injector credentialing level. Pricing pressure stems from extended treatment intervals as poly-L-lactic acid and calcium hydroxylapatite formulations displace six-month HA cycles. Medical spa chains exhibit highest price sensitivity due to thin labor margins, while corporate dermatology rollups absorb premium tier increases through bundled service packaging.
Supply Chain Analysis
Just-in-time inventory strategies dominate US clinic procurement for hyaluronic acid fillers with stable demand curves, while strategic stockpiling of botulinum toxin raw material concentrates persists among vertically integrated manufacturers hedging against bioprocessing facility contamination risks. Finished device and biologic supply concentrates in South Korea, China, and Switzerland, with US formulators drawing from fermentation-derived sodium hyaluronate and bacterial toxin master cell banks. Single-source vulnerability concentrates in cross-border logistics chokepoints linking Asian bioprocessing hubs to US coastal distribution centers. Distribution runs through manufacturer-direct sales forces serving high-volume accounts, with regional distributors covering independent medical spas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FDA-cleared biostimulatory formulation expertise constrains competitive entry timelines, privileging incumbents with active CBER submission experience and established investigator-initiated study networks over capital-rich entrants lacking regulatory navigation capabilities.
For Market Incumbents: Fortify account relationships through exclusive supply agreements with high-volume medical spa chains in Texas and Florida, while accelerating poly-L-lactic acid line extensions to defend against emerging Korean biostimulator entrants. Vertical integration into ultrasound-assisted delivery platform development preserves differentiation as real-time visualization becomes standard of care. For New Entrants and Emerging Players: Anchor in Canadian provincial markets where clinic density lags US metropolitan benchmarks by two-thirds, targeting Ontario and British Columbia with Health Canada-parallel submission strategies that leverage FDA clearance data. Direct-to-consumer financing partnerships with millennial-focused medical spas offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among medical spa chains with subscription-based neuromodulator maintenance protocols, signaling durable cash flow quality through economic cycles. Acquisition targets should demonstrate active CBER submission pipelines or exclusive distribution rights in underserviced Canadian geographies. Watch for FDA draft guidance finalization on compounded biologics as the inflection indicator for customized formulation business model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Biostimulatory Formulation Line Extension | Extends treatment intervals from six to eighteen months, raising per-patient lifetime value for Allergan and Galderma accounts. |
| Ultrasound-Assisted Delivery Platform Deployment | Reduces vascular occlusion liability for Merz Aesthetics while expanding addressable injector pool beyond core specialists. |
| Medical Spa Chain Partnership Consolidation | Locks in volume commitments through exclusive supply agreements in Houston and Phoenix financing-heavy markets. |
| Canadian Provincial Market Entry | Captures pent-up demand in Toronto and Vancouver where clinic density trails Miami and Los Angeles benchmarks. |
| CBER Parallel Submission Strategy | Accelerates Health Canada clearance timelines by leveraging FDA biologics review data for Ontario and British Columbia launches. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA CBER device filings, Health Canada Medical Devices Bureau registrations, and state medical board scope-of-practice rulings. Primary interviews engaged medical spa operators, dermatology practice administrators, pharmaceutical regulatory affairs directors, and GPO contracts managers across California, Texas, Florida, Ontario, and British Columbia. Secondary validation drew from CMS Medicare procedure data, hospital procurement databases, and SEC 10-K aesthetic segment disclosures. Bottom-up clinic capacity modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled span procedure type, target demographic, end-user channel, and pricing model across the projection horizon. CAGRs derive from logarithmic trend fitting of historical procedure volume data adjusted for regulatory approval timelines and scope-of-practice liberalization trajectories. Industry-specific forecast inputs include biostimulatory formulation adoption curves in Miami and Los Angeles medical spas, and third-party patient financing penetration rates in Houston and Phoenix markets.
Material uncertainties — FDA guidance finalization on compounded biologics, Health Canada medical spa regulatory expansion, and cross-border HA supply logistics friction — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained disposable income growth in coastal metropolitan corridors and stable CBER review cycle durations. Revision becomes warranted when biostimulatory formulation displacement of hyaluronic acid fillers crosses sixty-five percent volume thresholds in high-volume accounts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Telehealth Device Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Midline Catheters Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
Aortic Valve Replacement Devices Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Foot and Ankle Devices Market
Medical Devices
Stool Management Systems Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market