
 Global Benzodiazepines Market | 2026-2036
Global Benzodiazepines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Benzodiazepines Market Foresight
CE marking under the EU Medical Device Regulation is rotating competitive access for parenteral benzodiazepine formats across European acute care channels. Pfizer Inc. leverages its hospital-directed institutional sales infrastructure to sustain formulary positioning in high-throughput surgical centers. Teva Pharmaceutical Industries Ltd. anchors its portfolio through generic alprazolam and diazepam supply contracts with national procurement bodies across multiple geographies.
Benzodiazepines constitute a class of GABA-A receptor positive allosteric modulators characterized by fused benzene and diazepine rings, with half-lives ranging from ultra-short to long-acting durations depending on metabolic pathway. These compounds serve primarily as anxiolytics, sedative-hypnotics, anticonvulsants, and muscle relaxants in acute and chronic therapeutic settings. Oral formulations dominate volume due to chronic anxiety and insomnia maintenance prescriptions, while intravenous routes command premium positioning in perioperative and emergency medicine where rapid onset is clinically essential. The epilepsy therapy area presents concentrated margin pools as clonazepam and diazepam rectal gel carry specialized distribution requirements and limited generic substitution.
The FDA's REMS program for certain Schedule IV controlled substances shapes prescriber behavior and wholesale distribution licensing requirements across the United States. EMA pharmacovigilance obligations under the EU Good Pharmacovigilance Practices framework drive post-market surveillance intensity for long-acting formulations in European markets. Stakeholders must monitor evolving scheduling decisions by national drug control agencies and the therapeutic substitution policies of consolidated hospital purchasing organizations.
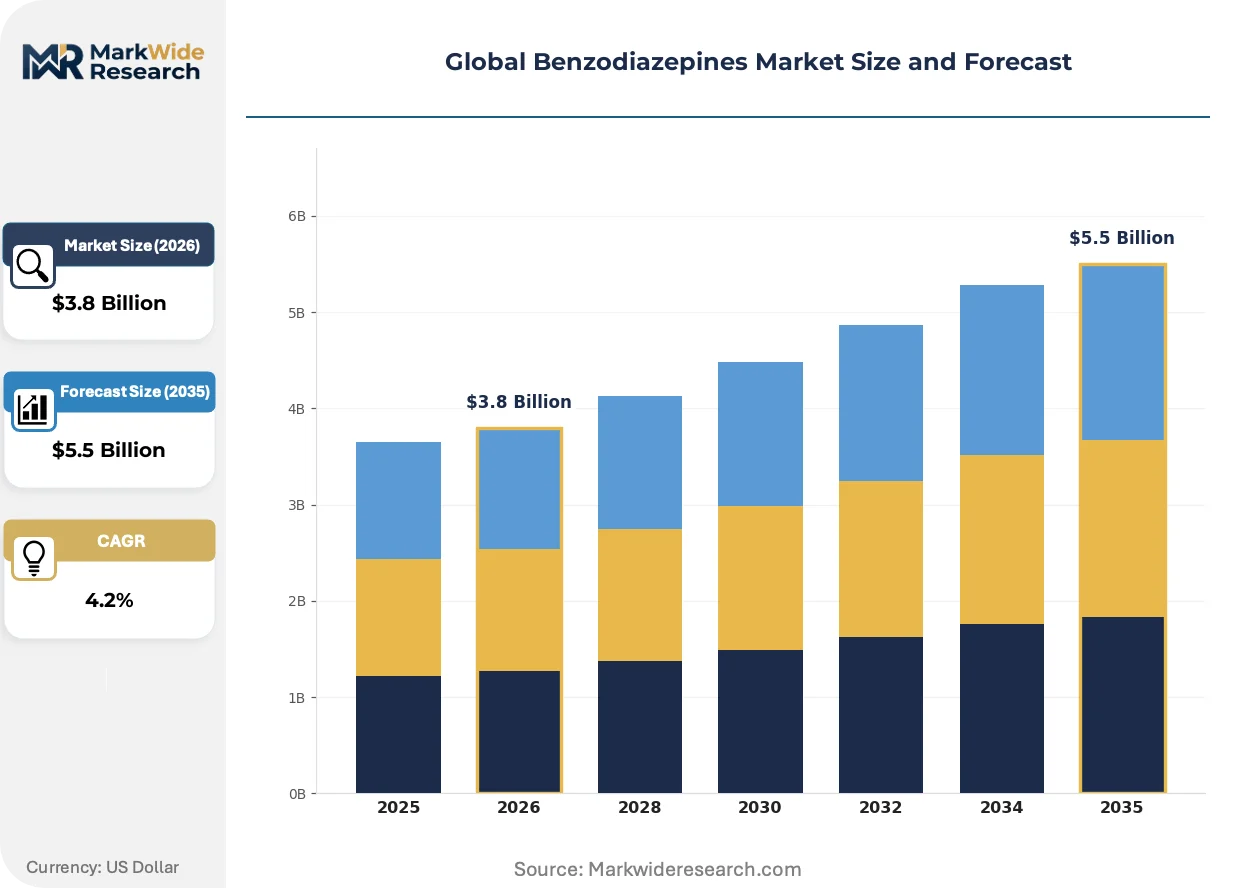
Market Dynamics
Integrated delivery networks in the United States are consolidating formularies, forcing manufacturers to defend hospital contracts through institutional sales infrastructure rather than physician detailing alone.
Growth Catalysts
- Procedural sedation protocols:Hospital systems in Germany and France are expanding benzodiazepine utilization for endoscopy suites and emergency airway management, driving parenteral volume.
- EMA pharmacovigilance frameworks:Post-market surveillance obligations under EU Good Pharmacovigilance Practices create compliance barriers that favor established suppliers with regulatory affairs scale.
- Rectal gel distribution specialization:Limited generic substitution for clonazepam and diazepam rescue therapies in epilepsy creates protected margin pools for certified distributors.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of flurazepam and temazepam precursors depends on a narrow base of Chinese and Indian intermediate suppliers, exposing formulators to input volatility.
- FDA REMS modification friction:The agency's enhanced requirements for certain Schedule IV anxiolytics impose wholesale distribution licensing burdens that compress independent pharmacy access.
- Non-benzodiazepine hypnotic substitution:Z-drugs and orexin receptor antagonists are displacing chronic insomnia prescriptions in Japan and South Korea, eroding maintenance therapy volumes.
Strategic Opportunities
- Brazilian public procurement expansion:ANVISA's hospital formulary modernization creates entry points for injectable midazolam suppliers serving the Sistema Único de Saúde network.
- Pre-hospital emergency medicine:Autoinjector formats for status epilepticus are penetrating ambulance services and military medical corps, opening device-plus-drug revenue models.
- Digital therapeutics convergence:Prescription digital therapeutics for anxiety are creating combination therapy protocols that preserve benzodiazepine positioning for acute breakthrough episodes.
Industry Challenges
- Controlled substance security infrastructure:DEA vault and tracking system compliance for Schedule IV compounds requires capital-intensive facility upgrades that strain mid-scale manufacturers.
- EU MDR technical documentation:CE marking renewal for parenteral delivery devices demands clinical evidence packages that extend certification timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Benzodiazepines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diazepam, Lorazepam, Clonazepam, Alprazolam, Chlordiazepoxide Therapy Area: Anxiety Disorders, Insomnia, Epilepsy, Muscle Spasm, Alcohol Withdrawal Syndrome Route of Administration: Oral, Intramuscular, Intravenous, Rectal End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Long-Term Care Facilities |
| Companies Covered | Bausch Health Companies Inc., Amneal Pharmaceuticals LLC, Pfizer Inc., Hikma Pharmaceuticals PLC, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Viatris Inc., Aurobindo Pharma, F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Benzodiazepines Market Shifts & Advancements
Formulation engineering and regulatory architecture are the twin forces compressing development cycles and reshaping competitive access in acute care channels.
Intranasal benzodiazepine spray technology is miniaturizing. The platform delivers midazolam and diazepam through mucosal absorption for seizure rescue without intravenous access. Pediatric neurologists and school nurses are adopting these devices for outpatient epilepsy management. The technology is compressing emergency response times while bypassing hospital pharmacy control.
REACH authorization requirements for chemical substances are tightening. The European Chemicals Agency's scrutiny of benzodiazepine intermediates is forcing reformulators to document supply chain substance volumes and exposure scenarios. German and French generic manufacturers are responding by qualifying alternative synthetic routes that reduce dependence on restricted precursor categories.
Hospital purchasing organizations are consolidating therapeutic substitution authority. United States integrated delivery networks are deploying therapeutic interchange committees that override individual physician benzodiazepine preferences based on consolidated contract terms. This behavior is most visible in perioperative anesthesia departments across the Midwest and Southeast, where midazolam sourcing is narrowing to two or three approved suppliers.
Global Benzodiazepines Market Segmentation
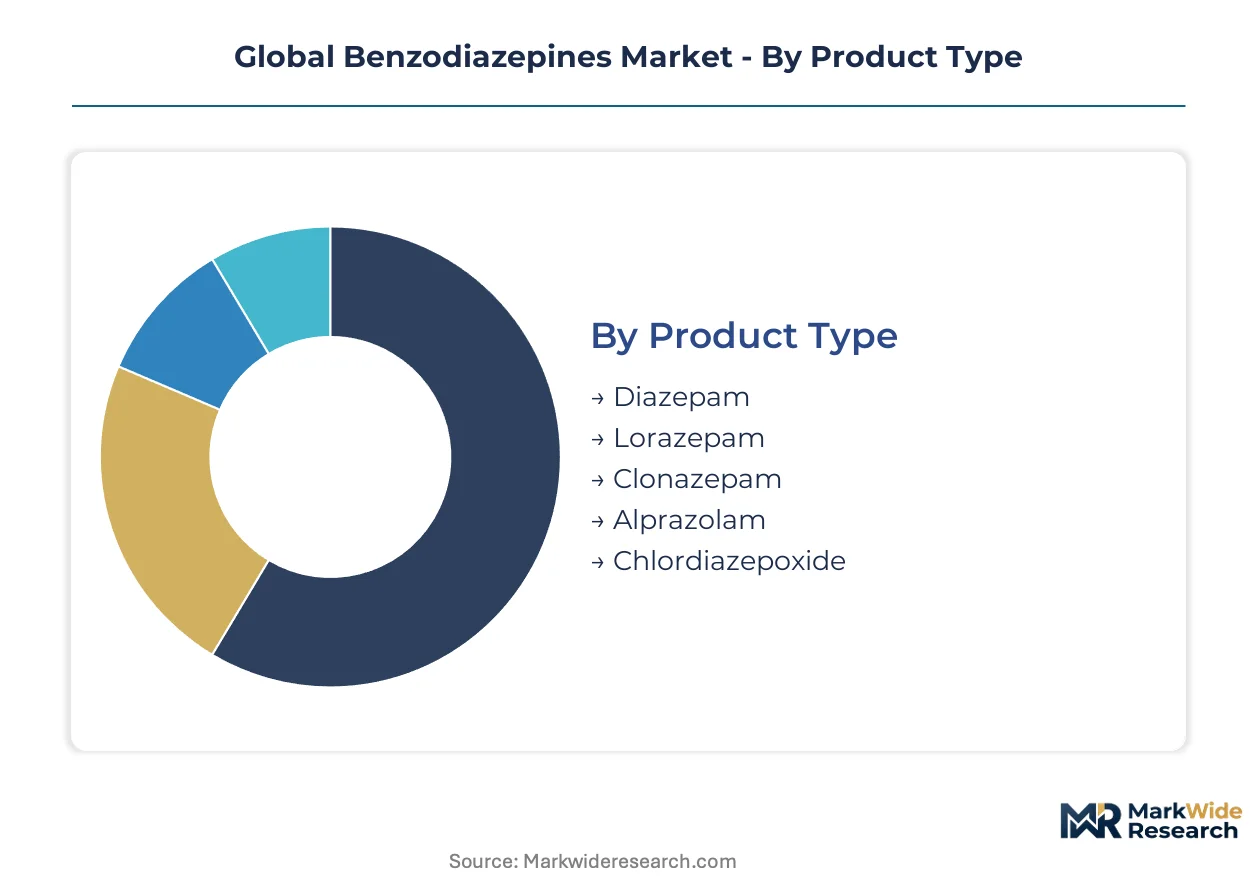
Benzodiazepine segmentation reveals fault lines where non-benzodiazepine substitutes penetrate fastest. Manufacturers must defend position segment-by-segment as Z-drugs, orexin antagonists, and digital therapeutics erode chronic maintenance prescriptions while acute care formats retain protected demand.
Product Type:
Substitution pressure varies sharply across the molecular portfolio, with short-acting anxiolytics facing the most intense competitive displacement from novel hypnotics.
- Diazepam:The prototypical 1,4-benzodiazepine with a long half-life extending to active metabolite desmethyldiazepam. Demand concentrates in emergency departments across Germany and France for alcohol withdrawal protocols and acute seizure termination, though chronic outpatient scripts erode under prescriber caution.
- Alprazolam:A triazolobenzodiazepine with rapid onset and short duration optimized for panic disorder. Prescription volume in United States integrated delivery networks contracts as FDA REMS modifications and therapeutic interchange committees restrict preferred formulary positioning.
- Lorazepam:A medium-acting compound with direct glucuronide conjugation bypassing hepatic oxidation, preferred in hepatic impairment populations.
- Clonazepam:A high-potency agent with serotonergic activity, anchoring epilepsy maintenance and rescue therapy where generic substitution faces distribution certification barriers.
- Chlordiazepoxide:The first commercial benzodiazepine, now largely relegated to alcohol detoxification protocols in veteran affairs and public hospital systems.
Diazepam anchors the volume base while alprazolam loses share at the steepest rate to non-benzodiazepine anxiolytic alternatives.
Therapy Area:
Margin pools concentrate where acute intervention necessity overrides substitution risk, separating chronic maintenance markets from protected emergency applications.
- Anxiety Disorders:Generalized anxiety and panic disorder maintenance scripts generate the largest prescription volumes globally. United States integrated delivery networks deploy therapeutic interchange committees that override physician alprazolam preferences, compressing branded positioning.
- Epilepsy:Status epilepticus rescue and chronic seizure control create specialized distribution requirements for clonazepam and diazepam rectal gel. ANVISA hospital formulary modernization in Brazil and pre-hospital autoinjector adoption in European ambulance services expand parenteral access points.
- Insomnia:Chronic hypnotic prescriptions face displacement from orexin receptor antagonists in Japan and South Korea, eroding temazepam and flurazepam maintenance volumes.
- Muscle Spasm:Acute skeletal muscle relaxation in perioperative settings sustains diazepam and lorazepam demand where rapid onset justifies intravenous administration.
- Alcohol Withdrawal Syndrome:CIWA-Ar protocol-driven hospital admissions in France and Germany generate concentrated diazepam and chlordiazepoxide utilization with limited substitution threat.
Epilepsy therapy commands the highest margin protection while insomnia applications face the most severe competitive erosion.
Route of Administration:
Delivery format determines regulatory barrier height and substitution vulnerability, with hospital-controlled parenteral formats resisting displacement.
- Intravenous:Rapid-onset delivery for perioperative anesthesia and emergency seizure control commands premium positioning in high-throughput surgical centers. CE marking renewal under EU MDR extends certification timelines, favoring established suppliers with clinical evidence packages.
- Oral:Chronic maintenance tablets and capsules dominate prescription volume but face the steepest Z-drug and digital therapeutic substitution in outpatient anxiety and insomnia markets.
- Intramuscular:Intermediate absorption kinetics serve acute agitation management in psychiatric emergency departments where oral compliance is unreliable.
- Rectal:Gel formulations for pediatric and adult epilepsy rescue require specialized distributor certification, creating limited generic substitution pools.
Oral formulations retain volume dominance while intranasal spray devices gain regulatory approvals at the fastest pace.
End User:
Purchasing authority concentration reshapes competitive access, with consolidated procurement systems overriding individual prescriber preferences.
- Hospitals:Integrated delivery networks in the United States consolidate formularies through therapeutic interchange committees, narrowing midazolam and lorazepam sourcing to contractually approved suppliers. German and French hospital systems expand benzodiazepine utilization for endoscopy suite sedation.
- Specialty Clinics:Pediatric neurology practices and epilepsy centers adopt intranasal spray technology for outpatient seizure rescue, compressing emergency response times.
- Ambulatory Surgery Centers:Freestanding procedural facilities in the United States Midwest and Southeast source midazolam through group purchasing organization contracts with limited supplier panels.
- Long-Term Care Facilities:Nursing homes face enhanced CMS oversight of antipsychotic and anxiolytic prescribing, constraining chronic benzodiazepine maintenance in elderly populations.
Hospitals concentrate procurement authority while specialty clinics expand device-plus-drug adoption most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Benelux distribution primacy for European parenteral benzodiazepine flows. German rail corridors from Frankfurt to Hamburg channel API shipments inland, while Swissmedic's Bern headquarters anchors regulatory arbitration for cross-border formulary access.
United States
Integrated delivery networks in the Midwest and Southeast consolidate midazolam procurement through therapeutic interchange committees. FDA REMS modifications for Schedule IV anxiolytics impose wholesale distribution licensing burdens that compress independent pharmacy access. The Philadelphia-Wilmington corridor hosts DEA-registered vault facilities serving hospital group purchasing organizations.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia expand benzodiazepine utilization for endoscopy suite sedation and emergency airway management. EMA pharmacovigilance obligations under EU Good Pharmacovigilance Practices drive post-market surveillance intensity for long-acting formulations. The Frankfurt-Rhine-Main cluster concentrates generic API formulation capacity for French and Benelux export.
France
CIWA-Ar protocol-driven hospital admissions in Île-de-France and Auvergne-Rhône-Alpes generate concentrated diazepam utilization for alcohol withdrawal syndrome. ANSM pharmacovigilance oversight shapes prescriber behavior for chronic anxiolytic maintenance. Lyon-based hospital purchasing coalitions negotiate consolidated lorazepam contracts for public sector formularies.
Japan
Orexin receptor antagonists displace temazepam and flurazepam maintenance prescriptions in Tokyo and Osaka metropolitan markets. PMDA scheduling reviews for Z-drug alternatives alter physician hypnotic selection patterns. The Kansai region's specialty psychiatric clinics retain benzodiazepine positioning for acute breakthrough anxiety episodes.
Brazil
ANVISA hospital formulary modernization creates entry points for injectable midazolam suppliers serving the Sistema Único de Saúde network. São Paulo's public procurement bodies consolidate parenteral sedative contracts for southeastern state hospital systems. Rio de Janeiro's emergency medicine residency programs drive training-protocol standardization for procedural sedation.
Global Benzodiazepines Market Competitive Landscape
Listed leaders compete with private specialists across institutional sales infrastructure and generic API supply scale. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with hospital-directed sales forces, mid-scale generic manufacturers with national procurement body contracts, and regional specialists with controlled-substance distribution certification. Market consolidation proceeds through therapeutic interchange committee capture and DEA vault infrastructure acquisition rather than horizontal merger.
Within the multinational tier, Pfizer Inc. and Teva Pharmaceutical Industries Ltd. exemplify divergent archetypes. Pfizer leverages hospital-directed institutional sales infrastructure to sustain formulary positioning in high-throughput surgical centers. Teva anchors portfolio presence through generic alprazolam and diazepam supply contracts with national procurement bodies across multiple geographies. Viatris Inc. occupies a position between these models, representing the post-merger integration of legacy generic platforms with branded institutional channels.
| Leading Market Players |
|---|
| Bausch Health Companies Inc. |
| Amneal Pharmaceuticals LLC |
| Pfizer Inc. |
| Hikma Pharmaceuticals PLC |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Aurobindo Pharma |
| F. Hoffmann-La Roche Ltd. |
| Others |
Supply & Pricing Matrix
CE marking renewal timelines under EU MDR gate both supply qualification and price differentiation simultaneously, extending certification cycles for parenteral delivery devices while compressing margins for manufacturers lacking clinical evidence packages. Hospital purchasing organizations exploit this regulatory bottleneck to consolidate contract awards around established suppliers with regulatory affairs scale.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between integrated delivery networks and benzodiazepine manufacturers. Three-tier pricing separates premium intravenous formulations from standard oral tablets and economy generic alprazolam. Price differentiation hinges on DEA vault certification status and formulary exclusivity duration. Cost compression in chronic maintenance segments intensifies as therapeutic interchange committees override physician brand preferences. Outpatient anxiety clinics exhibit highest price sensitivity; perioperative anesthesia departments show lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for flurazepam and temazepam precursor shipments. API synthesis draws from concentrated intermediate suppliers in India and China, with German and Swiss formulators dependent on this eastern sourcing base. Single-source vulnerability pervades the desmethyldiazepam precursor segment. Distribution runs through DEA-registered vault networks in the Philadelphia-Wilmington corridor and Rotterdam's pharmaceutical cold chain hub.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intranasal benzodiazepine spray technology is reshaping competitive positioning in epilepsy rescue therapy, creating device-plus-drug revenue models that bypass traditional hospital pharmacy control. FDA REMS modifications for Schedule IV compounds simultaneously raise compliance barriers and consolidate procurement authority.
For Market Incumbents: Secure formulary positioning in high-throughput surgical centers through institutional sales infrastructure investment rather than physician detailing alone. DEA vault facility acquisition in the Philadelphia-Wilmington corridor locks in distribution access as wholesale licensing burdens compress independent pharmacy channels. For New Entrants and Emerging Players: Differentiate on intranasal spray device technology for pediatric neurology practices and school nurse deployment. Brazilian public procurement under ANVISA hospital formulary modernization represents the most penetrable geography. Pre-hospital emergency medicine autoinjector formats offer device-plus-drug go-to-market angles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-substance security infrastructure as DEA vault compliance mandates facility upgrades. Acquisition targets should display therapeutic interchange committee capture in Midwest and Southeast integrated delivery networks. The signal to watch is EMA pharmacovigilance enforcement intensity for long-acting formulations.| Strategic Initiative | Industry Significance |
|---|---|
| DEA Vault Infrastructure Acquisition | Locks in wholesale distribution licensing for Schedule IV compounds amid REMS modification friction. |
| Intranasal Spray Regulatory Submission | Opens pediatric neurology and pre-hospital emergency medicine channels outside hospital pharmacy control. |
| Therapeutic Interchange Committee Capture | Secures preferred formulary positioning in consolidated United States integrated delivery networks. |
| EU MDR Clinical Evidence Package Investment | Accelerates CE marking renewal timelines for parenteral delivery devices against 18-24 month delays. |
| Brazilian Public Procurement Body Contracting | Establishes presence in ANVISA hospital formulary modernization for Sistema Único de Saúde network access. |
Research Methodology
A spread of perspectives from formulary directors, hospital procurement managers, regulatory affairs leads, and epilepsy center clinicians converged on the working assumptions shaping demand projections. Secondary validation drew from FDA REMS documentation, EMA pharmacovigilance databases, ClinicalTrials.gov intervention records, and integrated delivery network contract disclosure filings. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical spending estimates across the analysis window.
Segmentation dimensions modeled include molecular portfolio stratification, therapy area margin pools, route of administration regulatory barriers, and end-user purchasing authority concentration. CAGRs were derived from iterative reconciliation of historical prescription trends with projected therapeutic substitution patterns. Forecast inputs incorporated FDA scheduling review timelines and EMA post-market surveillance intensity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained REMS modification trajectories or abrupt EMA enforcement shifts would require recalibration. Forecasts reflect documented assumptions regarding therapeutic interchange committee proliferation and intranasal device regulatory approval velocity. Practitioners should keep alternative scenarios live as orexin antagonist substitution rates and Brazilian public procurement modernization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Vaginal Ring Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Botulinum Toxin Market
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market