
 Complex Injectable Market | 2026-2036
Complex Injectable Market Size, Share, and Industry Trends Forecast 2026-2036
Complex Injectable Market Outlook
Aseptic formulation expertise is unwinding capacity constraints across sterile manufacturing networks. Pfizer Inc leverages integrated biologics capabilities to sustain large-scale fill-finish operations for monoclonal antibodies. Fresenius Kabi anchors European supply through specialized parenteral production infrastructure. Bristol-Myers Squibb Company differentiates via concentrated investment in oncology injectable portfolios.
Complex injectables comprise sterile drug products requiring advanced formulation science, including liposomal encapsulation, sustained-release depots, or nanoparticle suspensions, manufactured under aseptic conditions with stringent particulate control. These products deliver biologics, peptides, or small molecules directly into systemic circulation or targeted tissue compartments for conditions where oral bioavailability proves inadequate. Monoclonal antibodies command the largest value pool within product type segmentation due to high per-dose pricing and chronic administration patterns. Intravenous delivery mode dominates current volume, though subcutaneous formulations are gaining fastest as self-administration protocols expand. Oncology leads therapy area allocation, with autoimmune disorders representing the next significant demand cluster.
FDA enforces Current Good Manufacturing Practice for sterile drug products under 21 CFR 211, while EMA's Annex 1 revision mandates enhanced contamination control strategies for aseptic processing. ISO 14644 cleanroom classifications and USP <797> compounding standards further constrain facility design and operational qualification. Stakeholders must monitor regulatory divergence between FDA's Quality by Design expectations and EMA's evolving biosimilar guidance, as compliance strategy choices will determine market access speed and manufacturing investment location.
Market Dynamics
Aseptic processing complexity is concentrating manufacturing capability among facilities capable of ISO 5 cleanroom operations and isolator-based filling lines, locking out mid-scale competitors from high-value sterile product segments.
Growth Catalysts
- FDA Quality by Design Framework:The agency's QbD expectations for process analytical technology integration are rewarding early adopters with accelerated approval pathways for complex sterile products.
- Subcutaneous formulation science:Advances in high-concentration protein stabilization and viscosity reduction are enabling self-administration protocols that expand addressable patient populations beyond infusion centers.
- Japan:PMDA's structured consultation pathways for biosimilar development are attracting fill-finish investment to Kansai and Greater Tokyo pharmaceutical clusters.
Market Restraints
- Single-use system supply concentration:Bioprocess bag and tubing assembly production concentrates among German and US suppliers, creating vulnerability to polymer resin allocation disruptions.
- Technical limitation:Liposomal encapsulation scale-up remains constrained by microfluidic mixing reproducibility above 200-liter batch sizes.
- Regulatory friction:Divergent FDA and EMA expectations for biosimilar immunogenicity assessment protocols force parallel development tracks that extend qualification timelines.
Strategic Opportunities
- Germany:Underdeveloped domestic capacity for antibody-drug conjugate fill-finish creates white space for specialized CDMO investment in Baden-Württemberg.
- Regulatory tailwind:EMA's Annex 1 revision on contamination control strategies is mandating isolator technology upgrades that favor greenfield facility designs over retrofit constraints.
- Technology convergence:Integration of continuous bioprocessing with aseptic filling lines is collapsing batch cycle times for monoclonal antibody production.
Industry Challenges
- Aseptic operator certification:ISO 14644-7 compliant gowning and behavioral qualification programs face 18-month training pipelines that constrain workforce scaling.
- Capex intensity:Restricted access barrier systems and robotic filling platforms require capital deployment exceeding standard small-molecule sterile facilities by factors of three to four.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complex Injectable Market |
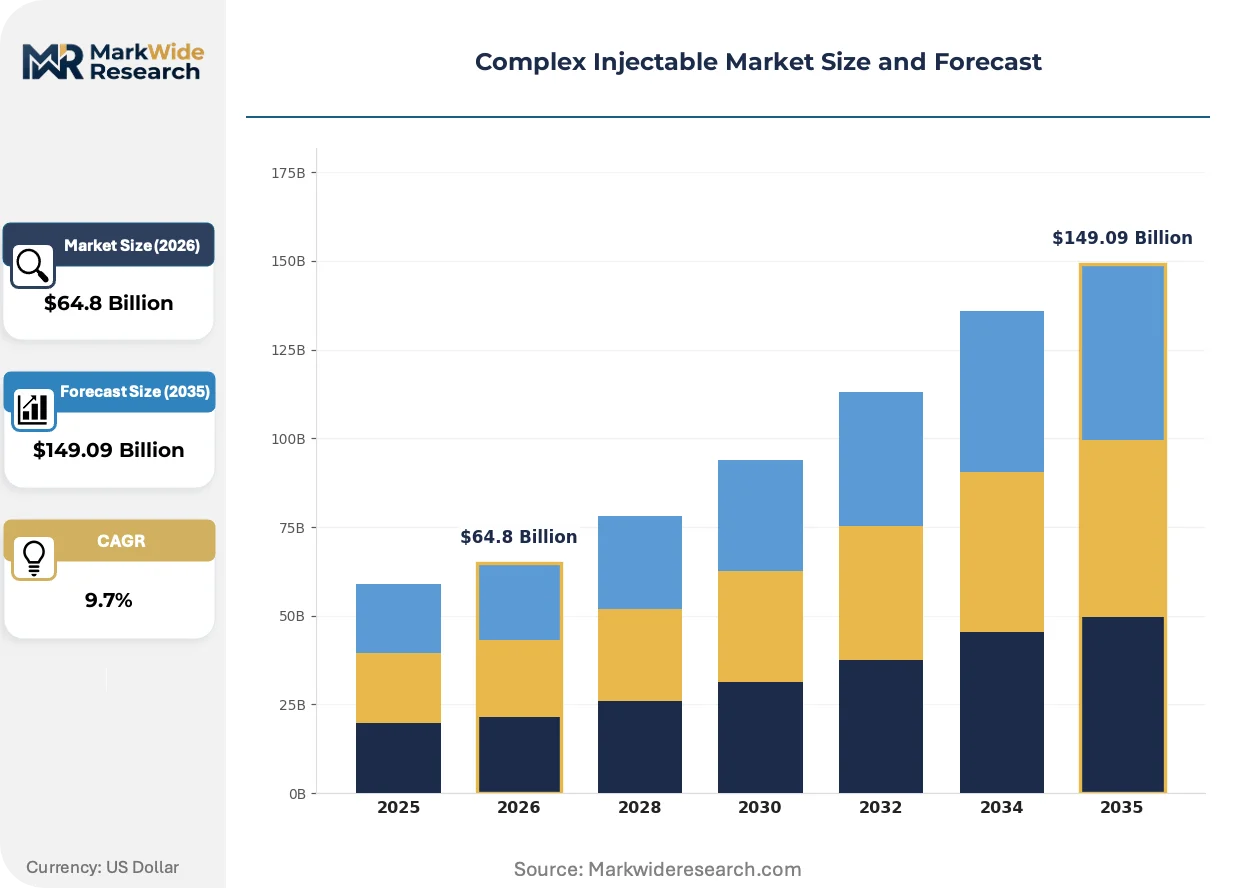
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $149.09 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Recombinant Proteins, Peptides Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Cardiovascular Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Intra-articular End User: Hospitals, Clinics, Home Care, Research Laboratories |
| Companies Covered | Pfizer Inc, AbbVie Inc, Bristol-Myers Squibb Company, Novartis AG, Fresenius Kabi, Teva Pharmaceutical Industries Ltd, Hikma Pharmaceuticals, Takeda Pharmaceutical Company Limited, Amgen Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complex Injectable Market Strategic Shifts
Platform standardization across monoclonal antibody modalities is compressing process development timelines while isolator-based filling technology is displacing conventional cleanroom operations.
Ready-to-use container closure systems are supplanting traditional vial-washing and depyrogenation workflows. Contract manufacturers in the United States and Germany are adopting these pre-sterilized formats to reduce line clearance times and eliminate glass particulate risks. This shift is compressing batch turnaround cycles and enabling multi-product facility scheduling that was previously uneconomical.
EMA's Annex 1 revision on sterile medicinal products is mandating enhanced contamination control strategies including rapid microbial detection methods and barrier isolation for all Grade A interventions. Fill-finish operators are responding by retrofitting legacy cleanrooms or constructing isolator-based greenfield lines, with oncology biologics manufacturers facing the steepest compliance deadlines due to patient population vulnerability.
Hospital procurement of complex injectables is consolidating through centralized pharmacy and therapeutics committees that negotiate sole-source agreements for high-volume oncology protocols. This concentration is displacing traditional distributor-mediated purchasing across integrated delivery networks in the United States, with similar committee structures emerging in German university hospital systems.
Complex Injectable Market Segmentation
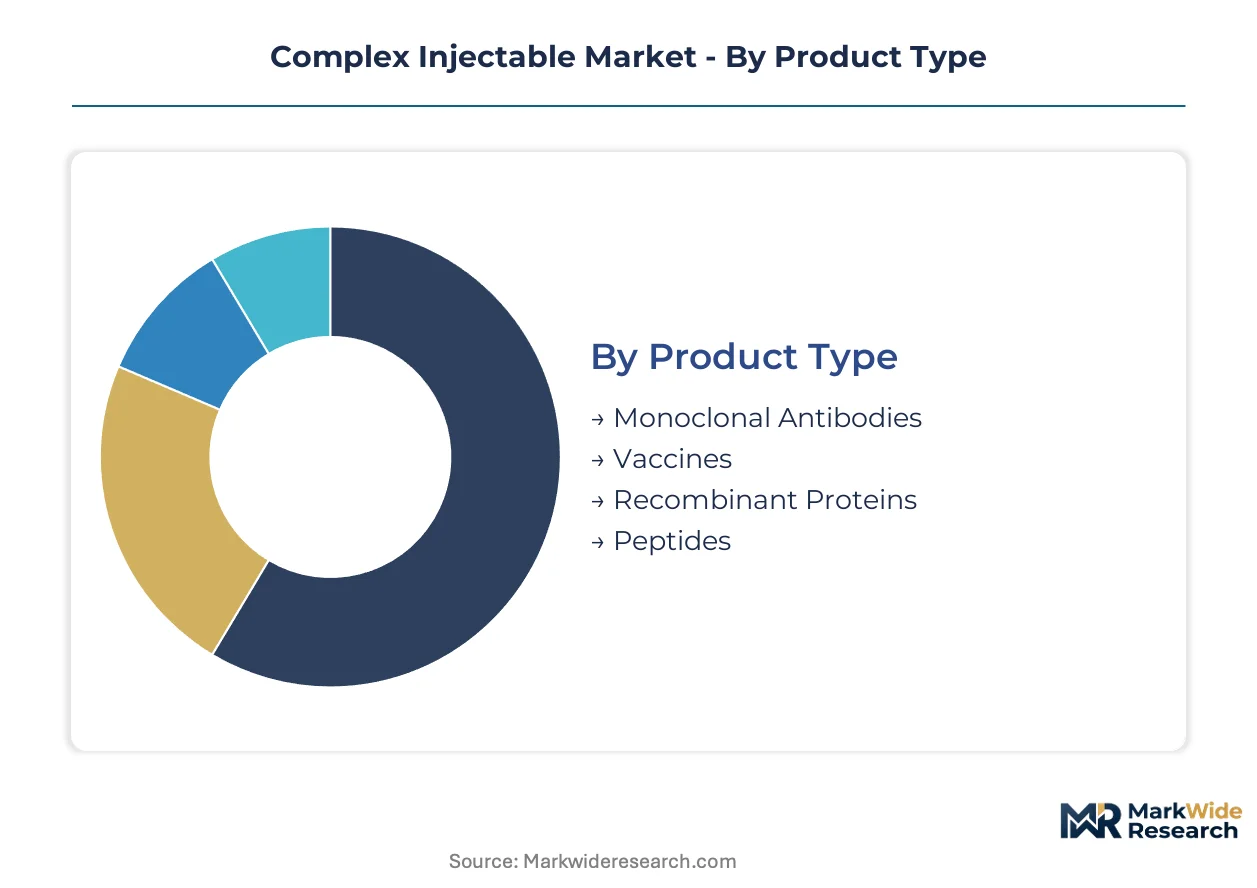
Segmentation in complex injectables determines manufacturing configuration, regulatory pathway, and distribution economics. Each dimension carries distinct margin profiles and capability requirements that shape competitive positioning.
Product Type:
Channel mix varies sharply: monoclonal antibodies and recombinant proteins flow predominantly through hospital infusion centers and specialty pharmacy networks, while vaccines and peptides distribute more broadly through retail clinics and public health channels.
- Monoclonal Antibodies:Large-molecule biologics requiring cold-chain distribution and specialized handling infrastructure. Demand concentrates in United States oncology centers where per-dose pricing supports dedicated logistics investment and chronic administration patterns create recurring revenue streams.
- Vaccines:Immunological preparations spanning preventive and therapeutic applications with distinct formulation stability challenges. Procurement centralizes through government tenders in Germany and Japan, where national immunization programs negotiate multi-year supply agreements that favor scale manufacturers.
- Recombinant Proteins:Engineered therapeutic proteins produced via cell culture systems.
- Peptides:Short-chain amino acid sequences with unique stability and delivery considerations.
By volume, vaccines lead through mass immunization programs. By growth pace, monoclonal antibodies are climbing the fastest on oncology expansion.
Therapy Area:
Cost tier stratification separates these segments: oncology commands premium pricing with limited substitution elasticity, while cardiovascular faces steeper generic pressure and infectious diseases operates on volume-based procurement.
- Oncology:Cancer therapeutics including cytotoxic agents, targeted therapies, and immuno-oncology combinations. United States academic medical centers drive demand concentration, with FDA accelerated approval pathways rewarding breakthrough designations that compress development timelines.
- Autoimmune Disorders:Chronic inflammatory condition management through immunomodulatory therapy. German rheumatology clinics represent the next significant demand cluster as subcutaneous self-administration protocols expand patient access beyond infusion centers.
- Infectious Diseases:Antimicrobial and antiviral parenteral therapies.
- Cardiovascular:Acute and chronic cardiac condition interventions.
Oncology generates the highest revenue per patient. Autoimmune disorders are expanding most quickly on self-administration adoption.
Delivery Mode:
Customer type alignment distinguishes administration settings: intravenous delivery ties to hospital-based care, while subcutaneous and intramuscular routes enable clinic and home care migration.
- Intravenous:Direct vascular administration requiring clinical supervision and infusion infrastructure. Hospital systems in Japan maintain dominant procurement share, with PMDA stability requirements for diluted biologics reinforcing centralized preparation protocols.
- Subcutaneous:Tissue-layer injection enabling patient self-administration with appropriate device support. United States specialty pharmacies are gaining fastest as high-concentration protein formulations reduce injection volume and viscosity challenges.
- Intramuscular:Deep muscle tissue delivery for depot formulations.
- Intra-articular:Joint-space injection for localized therapeutic effect.
Intravenous dominates current procedure volume. Subcutaneous is gaining share fastest on home care expansion.
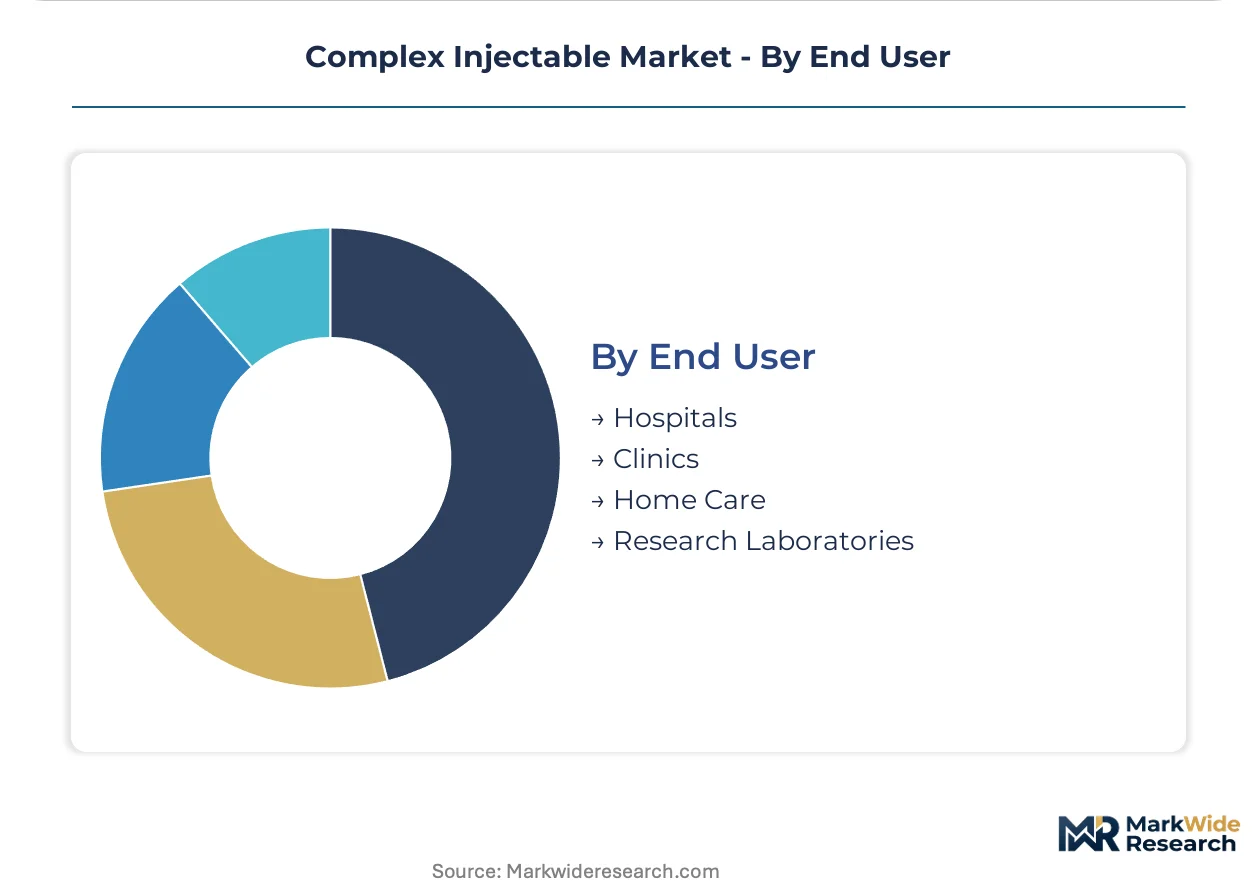
End User:
Supply concentration varies by care setting: hospitals integrate vertically into pharmacy operations, while home care depends on specialized distribution intermediaries with cold-chain credentials.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees. United States health systems are consolidating procurement through sole-source agreements that displace traditional distributor relationships for high-volume oncology protocols.
- Home Care:Patient-directed administration with nursing support or self-injection protocols. German ambulatory care networks are expanding fastest as statutory health insurance reimbursement frameworks adapt to outpatient biologic delivery.
- Clinics:Outpatient facilities with limited infusion capacity.
- Research Laboratories:Clinical trial and investigational product sites.
Hospitals command the largest procurement scale. Home care shows the steepest expansion trajectory on patient preference and cost containment pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Quality by Design framework anchors United States regulatory expectations, while EMA and PMDA shape parallel compliance architectures across Germany and Japan. Demand concentrates where sterile manufacturing infrastructure and specialized aseptic processing capabilities have achieved critical mass.
United States
Oncology infusion centers and specialty pharmacy networks drive procurement concentration. FDA's 21 CFR 211 enforcement and accelerated approval pathways reward early QbD adopters. Greater Boston and San Francisco Bay Area biotech clusters host fill-finish operations for monoclonal antibodies.
Germany
University hospital systems and statutory health insurance reimbursement frameworks expand outpatient biologic delivery. EMA's Annex 1 revision mandates isolator technology upgrades. Baden-Württemberg and North Rhine-Westphalia pharmaceutical corridors attract antibody-drug conjugate manufacturing investment.
Japan
PMDA structured consultation pathways for biosimilar development concentrate demand in Kansai and Greater Tokyo clusters. National health insurance pricing mechanisms favor domestic sterile production. Osaka-Tokyo pharmaceutical belt expands fill-finish capacity for high-concentration protein formulations.
United Kingdom
NHS centralized procurement and specialized pharmacy committees consolidate oncology injectable purchasing. MHRA alignment with EMA contamination control standards shapes facility investment. London-Oxford-Cambridge life sciences corridor maintains clinical trial and early-phase manufacturing presence.
Switzerland
Swissmedic's stringent aseptic processing requirements and bilateral recognition agreements with EMA attract premium sterile manufacturing. Basel-Zurich pharmaceutical hub hosts specialized parenteral production for biologics requiring complex formulation science.
Complex Injectable Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the complex injectable supply base. Large-cap integrated biopharmaceutical companies dominate monoclonal antibody portfolios through captive fill-finish networks. Mid-scale specialists concentrate in peptide and liposomal formulation segments where batch complexity limits scale economies. Competitive dynamics center on isolator technology deployment and multi-product facility scheduling flexibility.
Among integrated biopharmaceutical operators, Pfizer Inc and Bristol-Myers Squibb Company represent the scale-driven archetype with large-volume sterile manufacturing infrastructure. Fresenius Kabi occupies a specialized position within European parenteral production, anchoring supply chain resilience for hospital-system procurement. These three entities exemplify distinct competitive positioning: integrated biologics capabilities, oncology portfolio concentration, and regional fill-finish specialization respectively.
| Leading Market Players |
|---|
| Pfizer Inc |
| AbbVie Inc |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Fresenius Kabi |
| Teva Pharmaceutical Industries Ltd |
| Hikma Pharmaceuticals |
| Takeda Pharmaceutical Company Limited |
| Amgen Inc |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between hospital systems and sterile manufacturers lock in multi-year supply access while anchoring price visibility against raw material volatility. These contracts concentrate procurement power among United States integrated delivery networks and German university hospital systems, compressing spot-market participation for high-volume oncology biologics.
Pricing Analysis
United States per-dose pricing for monoclonal antibodies runs 40-60% above German statutory reimbursement levels, reflecting divergent payer architectures and FDA accelerated approval premiums. The dominant structure is contract-based long-term offtake with volume-tiered rebates, where price differentiation hinges on cold-chain certification grade and geographic delivery cost. Pricing pressure stems from biosimilar entry into reference product categories, with hospital pharmacy and therapeutics committees exhibiting highest price sensitivity through sole-source negotiation leverage. Specialty pharmacies show lowest sensitivity due to limited substitution options for high-concentration protein formulations.
Supply Chain Analysis
Inventory cycles for single-use bioprocess assemblies stretch 12-16 weeks, exposing fill-finish operators to polymer resin allocation disruptions. Supply concentrates in Germany and the United States for bioprocess bags and tubing, while Japan and Switzerland anchor specialized isolator component production. The network draws from pharmaceutical-grade silicone resin, gamma-irradiation services, and pre-sterilized container closure systems. Single-source vulnerability concentrates around German suppliers for multi-layer film extrusion. Distribution runs through hospital central pharmacies and specialty pharmacy networks with validated cold-chain credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The complex injectable market functions as a regulatory entrenchment story, where FDA 21 CFR 211 compliance and EMA Annex 1 certification create switching costs that lock hospital buyers into qualified supplier relationships.
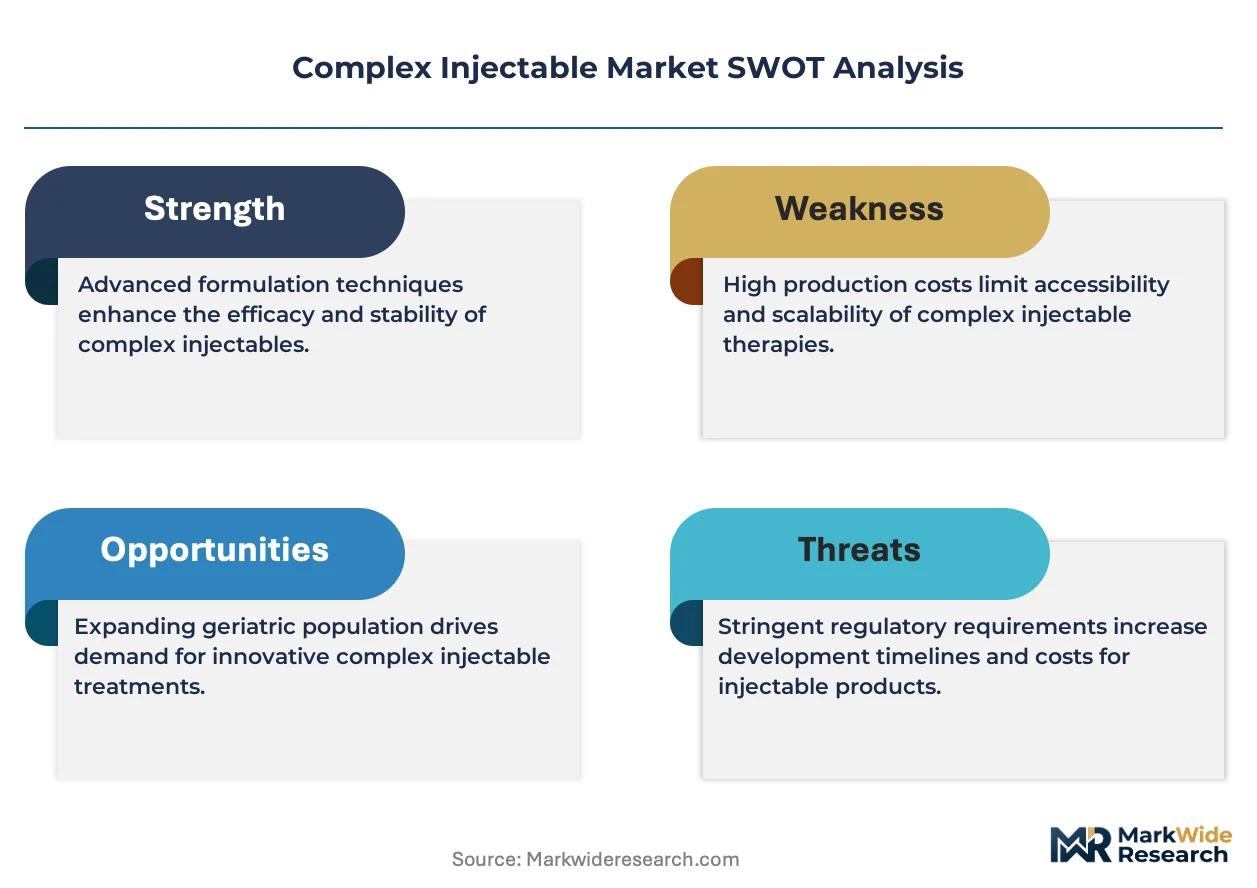
For Market Incumbents: Fortify isolator technology deployment across United States and German manufacturing footprints to preempt EMA contamination control deadlines. Expand backward integration into single-use assembly production to mitigate German supplier concentration risk. Prioritize capacity addition in Baden-Württemberg for antibody-drug conjugate fill-finish, where domestic capacity scarcity limits competitor entry. For New Entrants and Emerging Players: FDA Quality by Design fast-track consultation represents the most penetrable regulatory pathway for subcutaneous formulation specialists targeting United States specialty pharmacy channels. White space concentrates in high-concentration protein stabilization services for autoimmune disorder portfolios, where viscosity reduction expertise commands premium positioning. Target German ambulatory care networks through statutory health insurance reimbursement framework navigation as the go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CDMO operators with multi-year hospital system contracts and isolator-based facility assets. Long-term viability across the analysis window favors acquisition targets with captive biologics capabilities and regulatory approval track records in both FDA and EMA jurisdictions. Watch FDA biosimilar guidance harmonization progress as the inflection signal for portfolio reallocation toward reference product competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | EMA Annex 1 mandates barrier isolation for Grade A interventions, favoring greenfield construction over retrofit constraints. |
| Backward Integration into Single-Use Systems | Captive supply of bioprocess bags reduces vulnerability to German polymer resin allocation disruptions. |
| Subcutaneous Formulation Development | High-concentration protein stabilization expands addressable populations beyond infusion centers into United States specialty pharmacy channels. |
| Quality by Design Regulatory Submission | FDA process analytical technology integration rewards early adopters with accelerated approval pathways for sterile products. |
| Multi-Product Facility Scheduling | Ready-to-use container closure systems compress batch turnaround cycles and enable previously uneconomical product mix flexibility. |
Study Parameters
Operator-level perspectives from sterile manufacturing directors, hospital pharmacy and therapeutics committee chairs, regulatory affairs leads, and CDMO business development executives anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 21 CFR 211 guidance documents, EMA Annex 1 revision drafts, USP compounding standards, and ISO 14644 cleanroom classification protocols. Bottom-up facility capacity assessments and top-down therapy area demand modeling enabled triangulation across independent estimation approaches.
Sensitivity analysis tested forecast robustness against biosimilar approval velocity, isolator technology adoption rates, and subcutaneous formulation penetration assumptions. The analytical framework segmented volume and value across product type, therapy area, delivery mode, and end user dimensions throughout the projection horizon. CAGRs derived from historical growth pattern analysis and forward-looking regulatory pipeline assessment, with specific inputs including monoclonal antibody development stage distributions and hospital procurement consolidation trends.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA-EMA regulatory divergence and stable polymer resin supply; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Latin America Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Narcotic Analgesics Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Antidiuretic Drugs Market