
 Global Fluorouracil (5FU) Market | 2026-2036
Global Fluorouracil (5FU) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluorouracil (5FU) Market Foresight
Aftermarket service revenue from compounding pharmacy partnerships and cold-chain logistics support is tilting toward manufacturers with integrated distribution networks. Teva Pharmaceutical Industries leverages vertical integration across active pharmaceutical ingredient synthesis and finished dosage production to sustain cost competitiveness in commoditized injection markets. Fresenius Kabi anchors hospital channel access through its parenteral nutrition and oncology infusion portfolio, while Sandoz competes on bioequivalence certification breadth across European and North American regulatory jurisdictions.
Fluorouracil (5FU) is a synthetic fluorinated pyrimidine analog that functions as an antimetabolite chemotherapeutic agent, inhibiting thymidylate synthase and disrupting DNA and RNA synthesis in rapidly dividing malignant cells; it is manufactured through multi-step organic synthesis involving fluorination of uracil precursors under controlled temperature and pressure conditions, with final formulations requiring sterile processing for injectable grades and emulsion stabilization for topical delivery. The injection segment dominates hospital procurement volumes due to its established role in FOLFOX and FOLFIRI combination regimens for colorectal cancer, while the cream and topical gel categories occupy narrower but higher-margin positions in dermatology practices treating actinic keratosis and superficial basal cell carcinoma. Oncology clinics and cancer treatment centers represent the principal demand concentration points, with ambulatory care facilities expanding their share as same-day chemotherapy administration protocols gain protocol acceptance.
FDA bioequivalence standards and EMA's Good Manufacturing Practice inspections shape market access for generic 5FU suppliers, with India's CDSCO aligning its injectable purity requirements to ICH Q3D elemental impurity guidelines. The EU's F-Gas Regulation and OSHA worker exposure limits for cytotoxic compounding influence manufacturing facility design and containment capital expenditure decisions. Stakeholders must monitor regulatory divergence between FDA's Risk Evaluation and Mitigation Strategy requirements and emerging biosimilar substitution policies across European national health technology assessment bodies.
Market Dynamics
Regulatory tightening around injectable purity thresholds is forcing manufacturers to abandon batch processing in favor of continuous manufacturing systems, reshaping capital allocation and competitive differentiation across generic oncology supply chains.
Growth Catalysts
- FOLFOX protocol standardization:National cancer institutes in the United States, Germany, and India have embedded fluoropyrimidine-based regimens into first-line colorectal cancer treatment guidelines, locking in recurring procurement volumes for multi-source contract suppliers.
- EMA's Good Manufacturing Practice inspection harmonization:Cross-border mutual recognition agreements between European and Indian regulators are accelerating facility certification timelines for CDSCO-aligned manufacturers seeking European market access.
- Cold-chain infrastructure densification:Specialized logistics providers are building regional cytotoxic distribution hubs in Mumbai, Chicago, and Frankfurt, reducing temperature excursion risk for temperature-sensitive injectable formulations.
Market Restraints
- Fluorinated precursor supply concentration:Three Chinese chemical manufacturers control over 80% of global uracil fluorination feedstock, exposing formulation plants to input cost volatility and geopolitical supply interruptions.
- OSHA worker exposure containment costs:Cytotoxic compounding facilities in the United States face capital intensity escalation from mandated negative-pressure isolators and closed-system drug transfer devices.
- Topical 5FU substitution pressure:Photodynamic therapy and immune response modifiers are displacing cream formulations in dermatology practices treating actinic keratosis, compressing margin pools in the lower-volume segment.
Strategic Opportunities
- Brazilian oncology network expansion:ANVISA's accelerated approval pathway for essential medicines is opening procurement channels for injectable 5FU suppliers as the Sistema Único de Saúde expands regional cancer center coverage.
- Continuous manufacturing technology convergence:Integration of process analytical technology with real-time release testing is enabling FDA-aligned manufacturers to compress batch cycle times and reduce in-process inventory carrying costs.
- Ambulatory infusion center channel development:Same-day chemotherapy administration protocols are shifting volume from inpatient wards to freestanding infusion suites, creating demand for unit-dose packaging and direct-to-clinic distribution models.
Industry Challenges
- Sterile process engineer scarcity:Aseptic filling and lyophilization expertise concentration among legacy parenteral manufacturers is constraining workforce mobility for new market entrants building greenfield injectable capacity.
- Bioequivalence study timeline compression:FDA's tightened statistical power requirements for generic oncology injectables are extending clinical protocol durations and increasing development program risk capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluorouracil (5FU) Market |
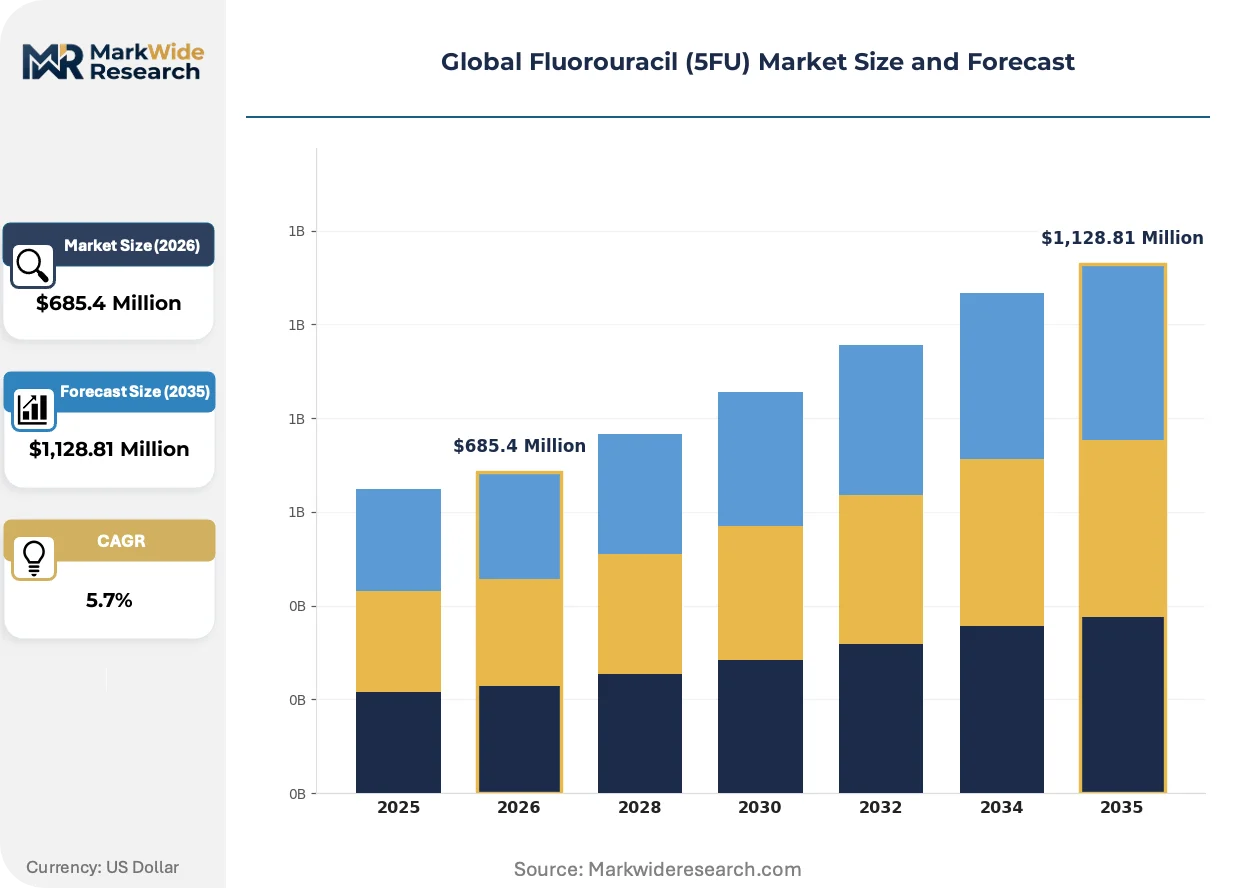
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,128.81 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Cream, Tablets, Topical Gel, Oral Suspension Therapy Area: Colorectal Cancer, Breast Cancer, Skin Cancer, Gastric Cancer, Esophageal Cancer End User: Cancer Treatment Centers, Ambulatory Care Facilities, Research Institutes, Diagnostic Laboratories, Oncology Clinics Delivery Mode: Intravenous, Oral, Topical, Intravesical, Subcutaneous |
| Companies Covered | Taj Pharmaceuticals Limited, Teva Pharmaceutical Industries, GlaxoSmithKline Pharmaceuticals Ltd, Mylan, Sandoz, Fresenius Kabi, Shanghai Airui, Celon Labs, Jinghua Pharmaceutical Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluorouracil (5FU) Market Shifts & Advancements
Process analytical technology deployment is digitizing quality assurance workflows, while regulatory divergence between FDA Risk Evaluation and Mitigation Strategy requirements and European biosimilar substitution policies is fragmenting market access strategies.
Continuous manufacturing platforms equipped with in-line Raman spectroscopy and multivariate statistical process control are digitizing real-time impurity detection and release decision-making. Oncology-focused contract development and manufacturing organizations in Switzerland and Singapore are adopting these systems to compress batch review timelines from weeks to hours. The technology is digitizing quality assurance labor allocation, shifting technical staff from retrospective laboratory testing to prospective process intervention.
REACH authorization requirements for fluorinated intermediates are extending chemical registration timelines and elevating compliance documentation burdens for European formulation manufacturers. The regulation is forcing supply chain requalification exercises as legacy Chinese precursor suppliers face substance of very high concern candidate list scrutiny. German and French generic injectable producers are responding by dual-sourcing from Indian API manufacturers with CDSCO-EMA parallel certification.
Hospital procurement consortia are consolidating oncology injectable purchasing into multi-year sole-source or dual-source agreements with integrated distribution and cold-chain service bundles. Independent regional distributors in Spain and Italy are losing share to manufacturers with captive logistics networks or exclusive partnerships with temperature-controlled last-mile specialists. The consolidation pattern is most visible in the United States, where group purchasing organizations anchor over 70% of acute care 5FU volume through committed compliance programs.
Global Fluorouracil (5FU) Market Segmentation
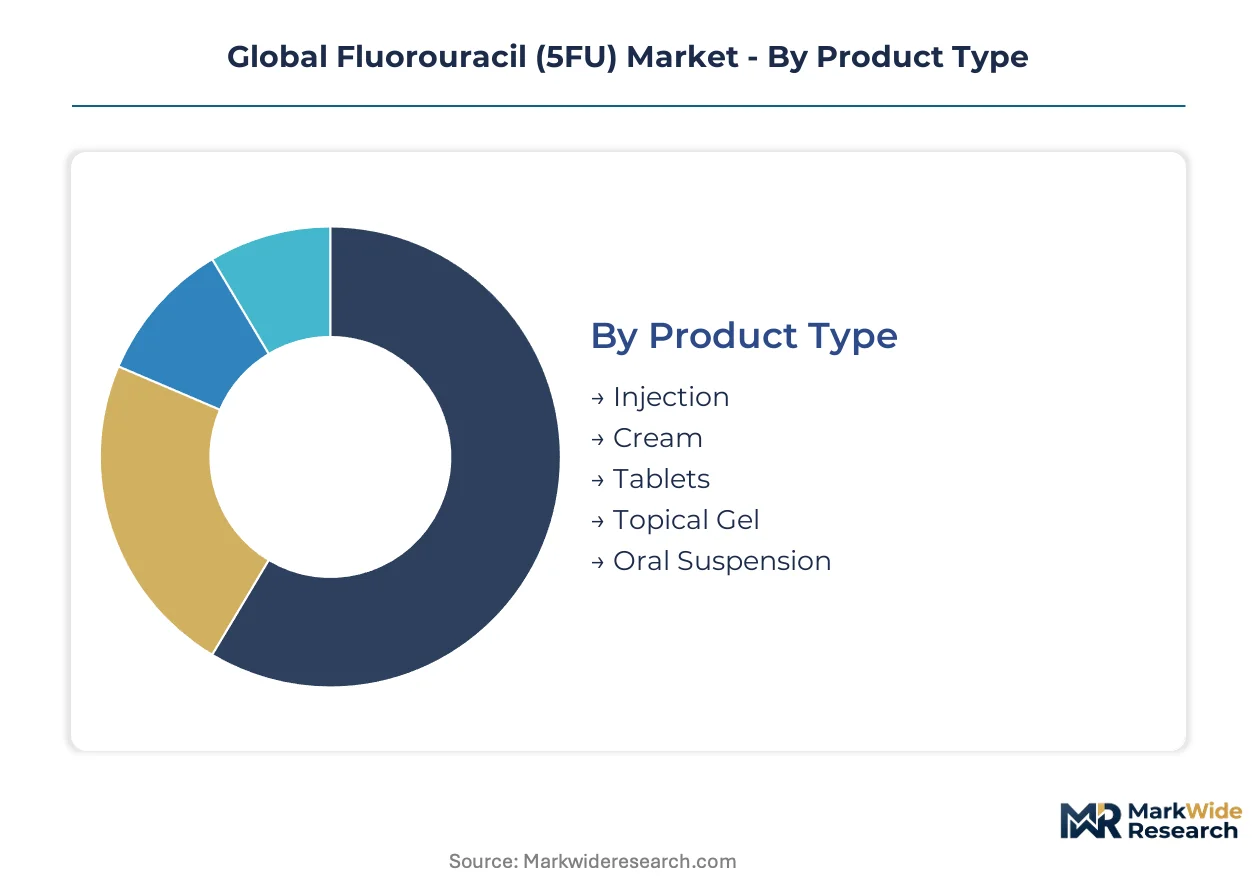
5FU market segmentation reveals how administration protocols, cancer type prevalence, and care delivery settings fragment procurement patterns across hospital systems and outpatient networks. Understanding these divisions exposes where volume concentrates and where margin pools form.
Product Type:
Formulation technology determines supply chain complexity, with sterile injectable processing commanding distinct manufacturing infrastructure from topical compounding.
- Injection:Sterile aqueous solutions for intravenous administration require aseptic filling and terminal sterilization under FDA and EMA cGMP protocols. Oncology clinics in the United States and Germany anchor procurement volumes as FOLFOX and FOLFIRI regimens standardize across national cancer institute guidelines.
- Cream:Oil-in-water emulsions with 0.5% to 5% active concentration serve dermatology practices treating actinic keratosis and superficial basal cell carcinoma. Demand concentrates in ambulatory dermatology suites across France and Australia where photodynamic therapy substitution pressure remains muted.
- Tablets:Oral solid dosage forms enable outpatient chemotherapy protocols with reduced clinic visit frequency.
- Topical Gel:Hydrogel-based delivery systems offer alternative skin penetration kinetics for localized lesion treatment.
- Oral Suspension:Liquid formulations accommodate patients with swallowing difficulties or dose titration requirements.
Injection commands the established base. The steepest expansion runs through ambulatory-ready oral formulations.
Therapy Area:
Cancer type prevalence and protocol standardization intensity shape regional demand clustering and reimbursement anchoring.
- Colorectal Cancer:Fluoropyrimidine-based adjuvant and metastatic regimens represent the anchor indication with established biomarker stratification. Hospital procurement consortia in the United States, Germany, and India lock in multi-year volume commitments as first-line guidelines embed 5FU combinations.
- Skin Cancer:Topical 5FU competes with immune response modifiers and photodynamic therapy in actinic keratosis management. Dermatology practices in Australia and Spain sustain prescription volumes where non-surgical lesion clearance remains preferred.
- Breast Cancer:CMF and other 5FU-containing regimens retain niche utility in specific molecular subtypes.
- Gastric Cancer:East Asian oncology networks maintain higher protocol penetration for perioperative and palliative applications.
- Esophageal Cancer:Combined modality therapy with radiation anchors institutional procurement in specialized cancer centers.
Colorectal applications anchor the revenue base. Skin cancer topical delivery is gaining share fastest in markets with aging demographics and dermatology access expansion.
End User:
Care delivery setting determines packaging requirements, cold-chain specifications, and purchasing authority concentration.
- Cancer Treatment Centers:Comprehensive oncology hubs with infusion capacity for complex multi-drug regimens and clinical trial participation. These facilities in Mumbai, Chicago, and Frankfurt concentrate intravenous formulation demand through committed compliance programs with integrated distributors.
- Ambulatory Care Facilities:Freestanding infusion suites and same-day surgery centers expanding chemotherapy administration outside hospital walls. Growth accelerates in the United States and Brazil as payor pressure shifts care to lower-cost settings with unit-dose packaging requirements.
- Research Institutes:Academic medical centers with investigator-initiated trial portfolios driving off-label protocol exploration.
- Diagnostic Laboratories:Companion testing facilities with limited direct pharmaceutical procurement.
- Oncology Clinics:Community-based practices with mixed infusion and referral capabilities.
Cancer treatment centers hold the volume core. Ambulatory care facilities are climbing the fastest as site-of-care migration accelerates.
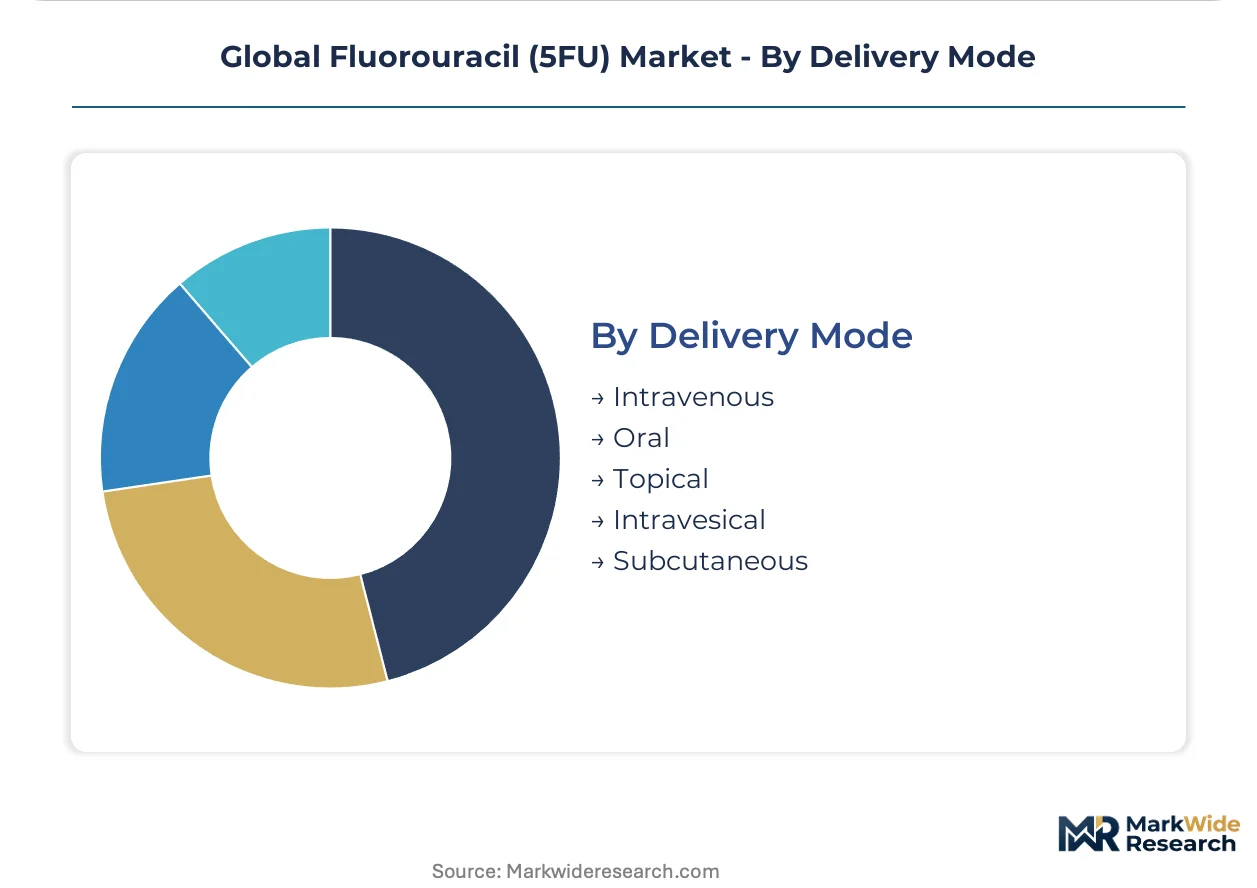
Delivery Mode:
Route of administration dictates formulation chemistry, device requirements, and prescriber training infrastructure.
- Intravenous:Continuous infusion via central venous access or peripheral lines dominates hospital oncology practice. FDA bioequivalence standards for generic injectables and EMA GMP inspection protocols shape supplier qualification timelines for multi-source procurement.
- Topical:Patient-applied cream and gel formulations eliminate infusion infrastructure requirements. CDSCO-aligned manufacturers in India supply European markets as REACH authorization complexity burdens Chinese precursor-dependent formulators.
- Oral:Bioavailability challenges with 5FU limit systemic oral delivery to prodrug formulations and regional variations.
- Intravesical:Bladder instillation protocols for superficial urothelial carcinoma occupy narrow specialty indication.
- Subcutaneous:Depot formulations and continuous delivery devices enable outpatient maintenance therapy.
Intravenous delivery anchors institutional procurement. Topical administration is expanding most quickly as dermatology practice automation reduces compounding burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement systems. Hospital consortia in the United States negotiate aggressive multi-source contracts, while India's government tenders prioritize volume throughput over unit economics. European markets split between reference-priced generics and premium-certified formulations.
United States
Oncology clinic expansion in Houston and Chicago drives injectable demand as FOLFOX protocols standardize across NCI-designated cancer centers. FDA bioequivalence requirements for generic injectables compress supplier qualification timelines. Group purchasing organizations anchor over seventy percent of acute care volume through committed compliance programs with integrated cold-chain distributors.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia lock in multi-year dual-source agreements for parenteral oncology formulations. EMA's Good Manufacturing Practice inspection protocols shape facility certification standards for European market access. Frankfurt anchors regional cytotoxic distribution infrastructure, reducing temperature excursion risk for temperature-sensitive injectable shipments.
India
National cancer institute procurement volumes in Mumbai and Delhi-NCR anchor volume commitments for multi-source contract suppliers. CDSCO alignment with ICH Q3D elemental impurity guidelines accelerates parallel certification pathways for EMA market access. Domestic API manufacturers with dual CDSCO-EMA certification are capturing share from Chinese precursor-dependent European formulators facing REACH authorization delays.
China
Three chemical manufacturers control over eighty percent of global uracil fluorination feedstock, exposing downstream formulation plants to input cost volatility. NMPA's tightened sterile processing requirements are forcing continuous manufacturing upgrades among domestic injectable producers. Shanghai-based oncology networks are expanding infusion capacity as colorectal cancer protocols standardize on fluoropyrimidine-based regimens.
Brazil
ANVISA's accelerated approval pathway for essential medicines is opening procurement channels as the Sistema Único de Saúde expands regional cancer center coverage in São Paulo and Minas Gerais. Same-day chemotherapy administration protocols are shifting volume from inpatient wards to freestanding infusion suites. Cold-chain infrastructure densification in São Paulo is reducing distribution risk for temperature-sensitive formulations.
Global Fluorouracil (5FU) Market Competitive Landscape
Capability concentration sits with legacy parenteral specialists possessing aseptic filling and lyophilization expertise; scale advantage sits with integrated pharmaceutical conglomerates with captive API synthesis and multi-regulatory certification breadth. The vendor base stratifies across three archetypes: vertically integrated generic giants with global distribution networks, regional injectable specialists with hospital channel anchoring, and emerging API-forward manufacturers pursuing parallel CDSCO-EMA certification. Dominant competitive moves include backward integration into fluorinated precursor supply and continuous manufacturing technology licensing to compress batch cycle times.
Among integrated generic conglomerates, Teva Pharmaceutical Industries and Fresenius Kabi exemplify archetypes at opposite ends of the value chain. Teva represents the API-to-finished-dosage vertically integrated model with cost competitiveness in commoditized injection markets. Fresenius Kabi occupies a position anchored in hospital channel access through parenteral nutrition and oncology infusion portfolio breadth. Sandoz sits within the regulatory certification breadth tier, competing across European and North American bioequivalence jurisdictions.
| Leading Market Players |
|---|
| Taj Pharmaceuticals Limited |
| Teva Pharmaceutical Industries |
| GlaxoSmithKline Pharmaceuticals Ltd |
| Mylan |
| Sandoz |
| Fresenius Kabi |
| Shanghai Airui |
| Celon Labs |
| Jinghua Pharmaceutical Co., Ltd |
| Others |
Supply & Pricing Matrix
Shanghai-Frankfurt pharmaceutical freight corridors carry temperature-sensitive injectable formulations at premium rates, concentrating cost pressure on manufacturers dependent on Chinese fluorinated precursors while enabling price stratification between REACH-compliant European suppliers and CDSCO-aligned Indian alternatives.
Pricing Analysis
Aftermarket service revenue from cold-chain logistics partnerships and compounding pharmacy support contracts drives lifetime value capture for integrated manufacturers. Pricing stratifies across premium-certified, standard-generic, and economy-bid tiers, with FDA bioequivalence certification and EMA GMP inspection status serving as primary differentiation markers. Cost compression in the economy tier intensifies as hospital procurement consortia consolidate volume into multi-source agreements. Group purchasing organizations demonstrate highest price sensitivity, while specialized oncology clinics with protocol standardization requirements exhibit lowest elasticity.
Supply Chain Analysis
Uracil fluorination feedstock concentrates among three Chinese chemical manufacturers controlling over eighty percent of global precursor supply. Formulation plants draw from fluorinated pyrimidine intermediates, sterile-grade excipients, and temperature-controlled packaging materials. Single-source vulnerability in precursor supply exposes downstream producers to geopolitical interruption and input cost volatility. Distribution runs through regional cytotoxic hubs in Mumbai, Chicago, and Frankfurt, with last-mile delivery anchored by hospital channel partnerships and integrated logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Fluorouracil (5FU) Market exhibits cyclical recovery characteristics as oncology clinic expansion and protocol standardization drive recurring procurement volumes through national cancer institute commitments.
For Market Incumbents: Pre-empt margin erosion from photodynamic therapy substitution in dermatology segments by accelerating continuous manufacturing technology licensing to compress batch cycle times. Defend hospital channel anchoring through captive cold-chain infrastructure investments in Frankfurt and Mumbai distribution nodes. Lock in multi-year sole-source agreements with group purchasing organizations before bioequivalence study timeline compression raises rival qualification barriers. For New Entrants and Emerging Players: Brazilian regional cancer center coverage gaps offer the most penetrable geographic entry point, with ANVISA's accelerated approval pathway reducing regulatory friction. Target ambulatory infusion center channel development in São Paulo and Minas Gerais with unit-dose packaging capabilities. Secure parallel CDSCO-EMA certification to bypass REACH authorization delays burdening Chinese precursor-dependent European formulators. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting commoditized oncology injectable portfolios to focus on biologic assets. Long-term viability hinges on backward integration into fluorinated precursor supply and continuous manufacturing technology adoption. Monitor FDA bioequivalence statistical power requirement tightening as an inflection signal indicating elevated development program risk capital barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Technology Licensing | Process analytical technology integration enables real-time release testing and compresses batch review timelines from weeks to hours. |
| Parallel CDSCO-EMA Certification | Dual regulatory alignment accelerates facility qualification for Indian API manufacturers seeking European market access. |
| Cold-Chain Infrastructure Densification | Regional cytotoxic distribution hubs in Mumbai, Chicago, and Frankfurt reduce temperature excursion risk for injectable formulations. |
| Backward Integration into Precursor Supply | Captive fluorinated pyrimidine production mitigates geopolitical supply interruption exposure from Chinese feedstock concentration. |
| Ambulatory Infusion Center Channel Development | Same-day chemotherapy administration protocols shift volume from inpatient wards to freestanding suites requiring unit-dose packaging. |
Research Methodology
Operator-level perspectives from oncology procurement managers, sterile process engineers, regulatory affairs leads, and formulary directors anchored the qualitative base. Primary interview data triangulated against FDA filings, EMA inspection reports, ClinicalTrials.gov records, and national cancer institute procurement databases. Secondary validation incorporated customs trade data and pharmaceutical distribution channel records. Bottom-up volume estimates from formulation plant capacity and top-down demand projections from cancer incidence protocols converged through iterative reconciliation.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity testing around regulatory approval timeline variability and precursor supply disruption probability. Segmentation modeling incorporated product type, therapy area, end-user setting, and delivery mode dimensions alongside regional regulatory cluster differentiation. CAGRs derived from historical volume trajectories and protocol standardization intensity curves, calibrated against hospital procurement consortium commitment patterns and ambulatory care migration rates.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, currency volatility affecting API import costs, or trade restriction escalation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization pace and cold-chain infrastructure investment continuity. Material shifts in FDA bioequivalence statistical requirements or REACH authorization scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market