
 Oncology Small Molecule Drugs Market | 2026-2036
Oncology Small Molecule Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Oncology Small Molecule Drugs Market Outlook
Modular oral dosing regimens is decoupling treatment administration from infusion center dependency, expanding patient access to cancer therapy outside traditional hospital settings. Roche leverages its portfolio breadth across kinase inhibitors and hormonal agents to sustain leadership in breast and lung cancer indications. Novartis anchors its competitive position through manufacturing scale in tyrosine kinase inhibitor production. AstraZeneca differentiates via targeted therapy specialization in lung cancer segments.
Oncology small molecule drugs are synthetic chemical compounds, typically below 900 daltons in molecular weight, designed to penetrate cell membranes and modulate intracellular signaling pathways implicated in malignant transformation; these agents function by interrupting oncogenic protein function, inducing apoptosis, or blocking angiogenic signals essential for tumor survival. Tyrosine kinase inhibitors command substantial margin pools due to targeted efficacy profiles and premium positioning in precision oncology. Chemotherapy agents retain volume leadership across therapy areas but face substitution pressure from targeted alternatives. Oral delivery mode segments are expanding fastest as pharmaceutical formulation science enables bioavailable alternatives to intravenous administration.
FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compress development timelines and reshape competitive entry dynamics for novel molecular entities. ISO quality management standards and national pharmacopeial requirements govern manufacturing consistency and batch release protocols across production networks. Stakeholders must monitor regulatory science convergence between FDA, EMA, and China's NMPA as alignment on biomarker-driven approval criteria determines market access speed for next-generation kinase inhibitors.
Market Dynamics
FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compress development timelines and reshape competitive entry dynamics for novel molecular entities.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy designation compresses clinical development timelines from standard protocols. EMA conditional marketing authorization enables earlier patient access pending confirmatory data.
- Hospital Oral Chemotherapy Expansion:Oncology departments across the United States, China, and Germany are expanding oral chemotherapy protocols that decouple treatment from infusion center dependency.
- Precision Oncology Biomarker Adoption:Companion diagnostic integration with tyrosine kinase inhibitors enables patient stratification and expands addressable populations for targeted therapy segments.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing concentrates in China and India, creating geopolitical exposure and quality consistency risks for multinational sponsors.
- Reimbursement Compression:Payer cost-containment policies in Germany and reference pricing mechanisms across European markets erode net pricing power for established kinase inhibitors.
- Generic Substitution Pressure:Patent cliffs for major chemotherapy agents accelerate commoditization in volume-leading therapy areas, compressing margin pools for originator molecules.
Strategic Opportunities
- Underserved Rural Access:Oral formulation expansion creates white space in United States rural markets where infusion center infrastructure remains sparse and travel burdens limit patient adherence.
- Regulatory Science Harmonization:Convergence between FDA, EMA, and China's NMPA on biomarker-driven approval criteria accelerates multi-territory launch sequencing for next-generation inhibitors.
- Home Administration Models:Remote patient monitoring technology integration with oral regimens enables hospital-at-home reimbursement pathways previously restricted to parenteral therapy.
Industry Challenges
- Specialized Formulation Talent Scarcity:Bioavailability engineering for oral kinase inhibitors requires rare expertise in pharmaceutical formulation science that concentrates at limited contract development organizations.
- Multi-Territory Compliance Complexity:ISO quality management standards, FDA current good manufacturing practice, and national pharmacopeial requirements create divergent batch release protocols across production networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncology Small Molecule Drugs Market |
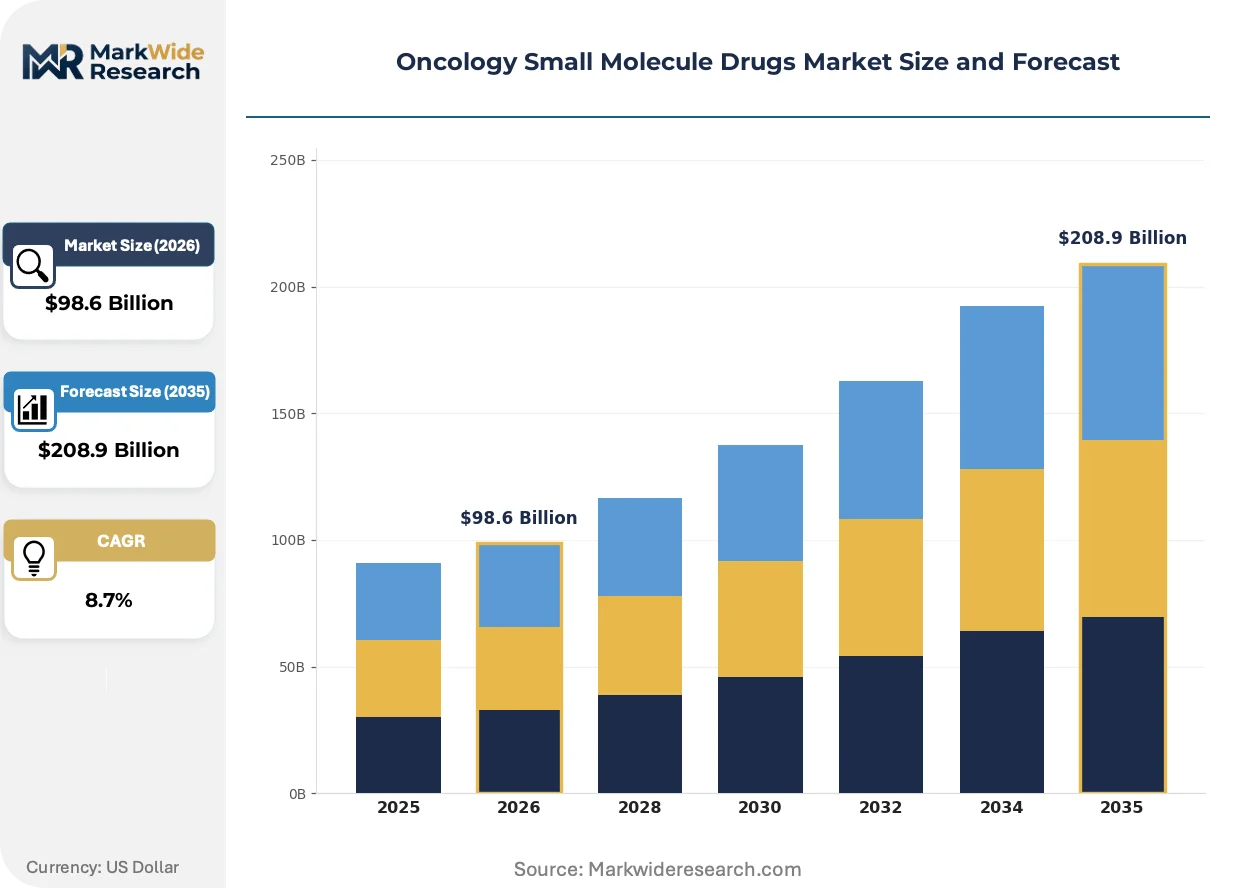
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tyrosine Kinase Inhibitors, Chemotherapy Agents, Hormonal Agents, Immune Checkpoint Inhibitors Therapy Area: Breast Cancer, Lung Cancer, Prostate Cancer, Lymphoma End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Settings Delivery Mode: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | Roche, Merck & Co., Novartis, AstraZeneca, Johnson & Johnson, Sanofi, Eli Lilly, Pfizer, Bristol Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncology Small Molecule Drugs Market Strategic Shifts
Artificial intelligence-driven target identification and decentralized clinical trial execution are compressing discovery-to-approval timelines and reshaping how oncology small molecules reach patients.
Fragment-based drug design is converging with cryo-electron microscopy structural biology to enable rational optimization of kinase inhibitor binding kinetics. Biotechnology sponsors and large pharmaceutical developers are adopting these platforms at accelerating pace for lung and breast cancer programs. This convergence is compressing lead optimization cycles from multi-year timelines to eighteen-month trajectories for validated targets.
EMA's adaptive pathway framework and FDA's Project Orbis initiative create synchronized multi-agency review procedures for oncology therapeutics. These mechanisms enable simultaneous regulatory submissions across the United States, European Union, Japan, and Canada. Small molecule developers with global commercial infrastructure capture first-mover advantage in competitive kinase inhibitor categories through coordinated approval sequencing.
Hospital procurement consortia in Germany and group purchasing organizations across United States health systems are consolidating purchasing power for oral oncology agents. Traditional wholesale distribution through specialty pharmacy channels faces disintermediation pressure from direct manufacturer-to-provider contracting models. This consolidation concentrates volume allocation decisions among fewer formulary gatekeepers, intensifying price competition for mature therapy areas.
Oncology Small Molecule Drugs Market Segmentation
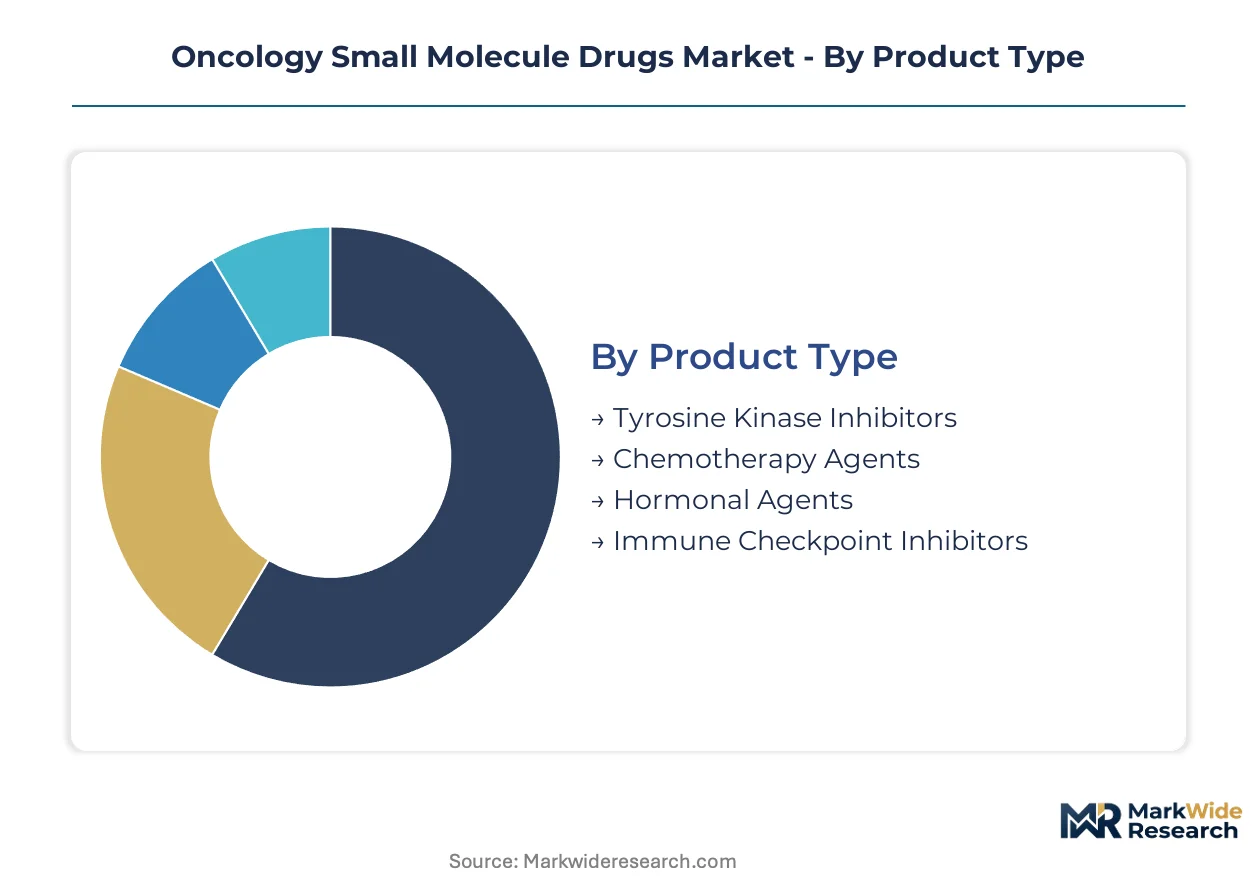
Segmentation in oncology small molecules reveals how therapeutic innovation, administration convenience, and care setting migration reshape commercial priorities. Distinct performance profiles across product types and delivery modes determine pricing power, reimbursement pathways, and manufacturing investment allocation.
Product Type:
Upgrade cycles from cytotoxic chemotherapy toward precision-targeted alternatives redefine portfolio composition across major pharmaceutical developers.
- Tyrosine Kinase Inhibitors:Synthetic compounds below 900 daltons selectively interrupt oncogenic signaling cascades. Demand concentrates in United States academic medical centers and German hospital networks where companion diagnostic infrastructure enables biomarker-driven patient stratification.
- Chemotherapy Agents:Cytotoxic alkylating agents and antimetabolites retain volume leadership across lymphoma and breast cancer protocols. Procurement concentrates in Chinese public hospital systems where cost-containment policies favor established generic alternatives over novel targeted therapies.
- Hormonal Agents:Selective estrogen receptor modulators and androgen deprivation compounds serve breast and prostate cancer maintenance regimens.
- Immune Checkpoint Inhibitors:Small molecule alternatives to biologic checkpoint blockers remain investigational but attract pipeline investment from sponsors seeking oral administration advantages.
Volume placements concentrate in Chemotherapy Agents; the faster expansion belongs to Tyrosine Kinase Inhibitors.
Therapy Area:
Cost tier differentiation separates premium-priced targeted therapies from commoditized cytotoxic regimens across major malignancy categories.
- Breast Cancer:CDK4/6 inhibitors and PI3K pathway antagonists command premium positioning in hormone receptor-positive subpopulations. German oncology consortia and United States specialty pharmacies drive demand concentration for oral endocrine combinations.
- Lung Cancer:EGFR, ALK, and ROS1 inhibitors anchor precision medicine adoption where liquid biopsy accessibility expands addressable populations. Chinese tertiary hospitals and United States community oncology practices represent parallel demand centers with divergent reimbursement constraints.
- Prostate Cancer:Androgen receptor signaling inhibitors and PARP inhibitors serve castration-resistant disease progression.
- Lymphoma:BTK inhibitors and BCL-2 antagonists displace chemotherapy backbones in indolent and aggressive subtypes.
Revenue concentration sits with Lung Cancer; Prostate Cancer applications are climbing the fastest.
End User:
Customer type migration from institutional administration toward patient-directed consumption reconfigures distribution infrastructure and compliance requirements.
- Hospitals:Inpatient oncology departments and infusion centers retain control over parenteral chemotherapy administration. United States health systems and Chinese provincial hospitals anchor procurement volume where formulary committees negotiate manufacturer access agreements.
- Oncology Clinics:Ambulatory infusion centers and physician office-based practices concentrate intravenous therapy delivery. German office-based oncology practices and United States community cancer centers represent distinct regulatory environments for outpatient drug administration.
- Research Institutions:Academic medical centers and comprehensive cancer centers conduct early-phase clinical trials and investigator-initiated studies.
- Homecare Settings:Oral regimen expansion enables remote administration with telemedicine monitoring support.
Procurement volume aggregates in Hospitals; Homecare Settings demonstrate the steepest expansion trajectory.
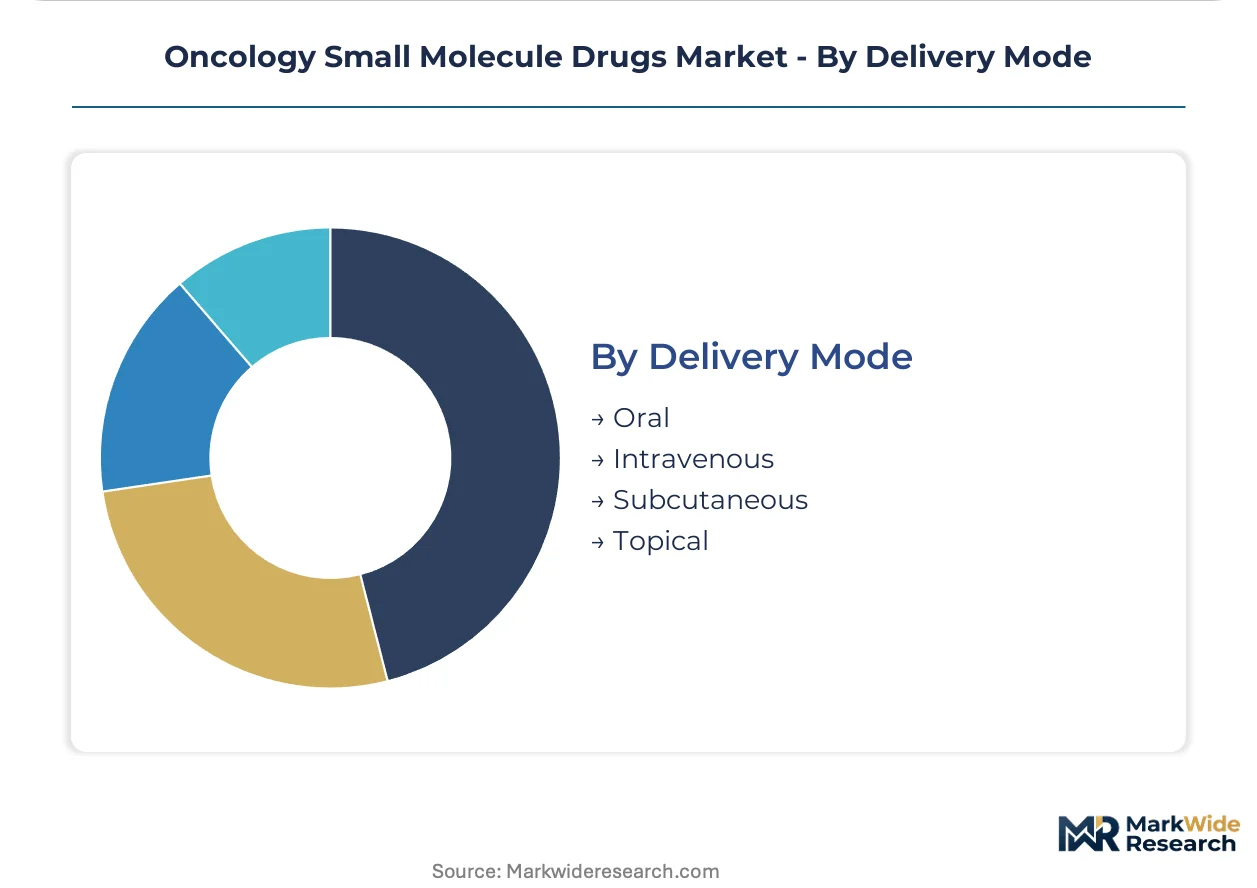
Delivery Mode:
Supply concentration in oral formulation development creates competitive differentiation as pharmaceutical engineering overcomes bioavailability barriers for kinase inhibitors.
- Oral:Tablet and capsule formulations eliminate infusion center dependency and enable decentralized treatment administration. United States rural markets and Chinese county-level hospitals represent underserved populations where oral access expands geographic reach.
- Intravenous:Parenteral administration retains necessity for cytotoxic agents with poor gastrointestinal tolerability. Hospital-based pharmacy operations in Germany and United States academic centers maintain infrastructure for sterile compounding and infusion delivery.
- Subcutaneous:Self-administered injection alternatives reduce healthcare utilization for selected hormonal and supportive care agents.
- Topical:Localized delivery for cutaneous lymphoma and palliative skin lesion management occupies niche positioning.
Installed base dominates Intravenous administration; Oral delivery is gaining share fastest across new product launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing concentrates in China and India while consumption centers cluster in the United States, Germany, and Japan. This production-consumption divide creates supply chain exposure that shapes procurement strategies across oncology drug developers.
United States
FDA breakthrough therapy designation accelerates clinical development timelines for kinase inhibitors targeting lung and breast cancer. The Inflation Reduction Act introduces Medicare price negotiation mechanisms that compress net pricing power for established oral oncology agents. Boston and San Francisco anchor biotech clusters where fragment-based drug design platforms converge with cryo-electron microscopy capabilities.
China
NMPA priority review pathways enable domestic sponsors to compress approval timelines for innovative tyrosine kinase inhibitors. National reimbursement drug list updates expand patient access to targeted therapies in provincial hospital systems. Shanghai and Suzhou concentrate contract development and manufacturing organizations that serve multinational pharmaceutical sponsors seeking cost-competitive API sourcing.
Germany
EMA conditional marketing authorization frameworks enable earlier patient access to novel molecular entities pending confirmatory trial data. Hospital procurement consortia consolidate purchasing power for oral chemotherapy protocols across Bavaria and North Rhine-Westphalia. Heidelberg and Munich anchor precision oncology networks where companion diagnostic infrastructure enables biomarker-driven patient stratification.
Japan
PMDA sakigake designation system compresses regulatory review timelines for breakthrough oncology therapeutics. National health insurance price listing procedures determine reimbursement access for targeted therapy segments in academic medical centers. Tokyo and Osaka concentrate pharmaceutical R&D operations where kinase inhibitor programs target EGFR-mutant lung cancer subpopulations.
India
CDSCO accelerated approval pathways enable earlier market entry for generic oncology small molecules meeting bioequivalence standards. Production-linked incentive schemes for active pharmaceutical ingredients attract capital investment in Gujarat and Maharashtra manufacturing zones. Hyderabad and Ahmedabad anchor formulation development clusters that supply oral chemotherapy agents to emerging markets across Africa and Southeast Asia.
Oncology Small Molecule Drugs Market Competitive Environment
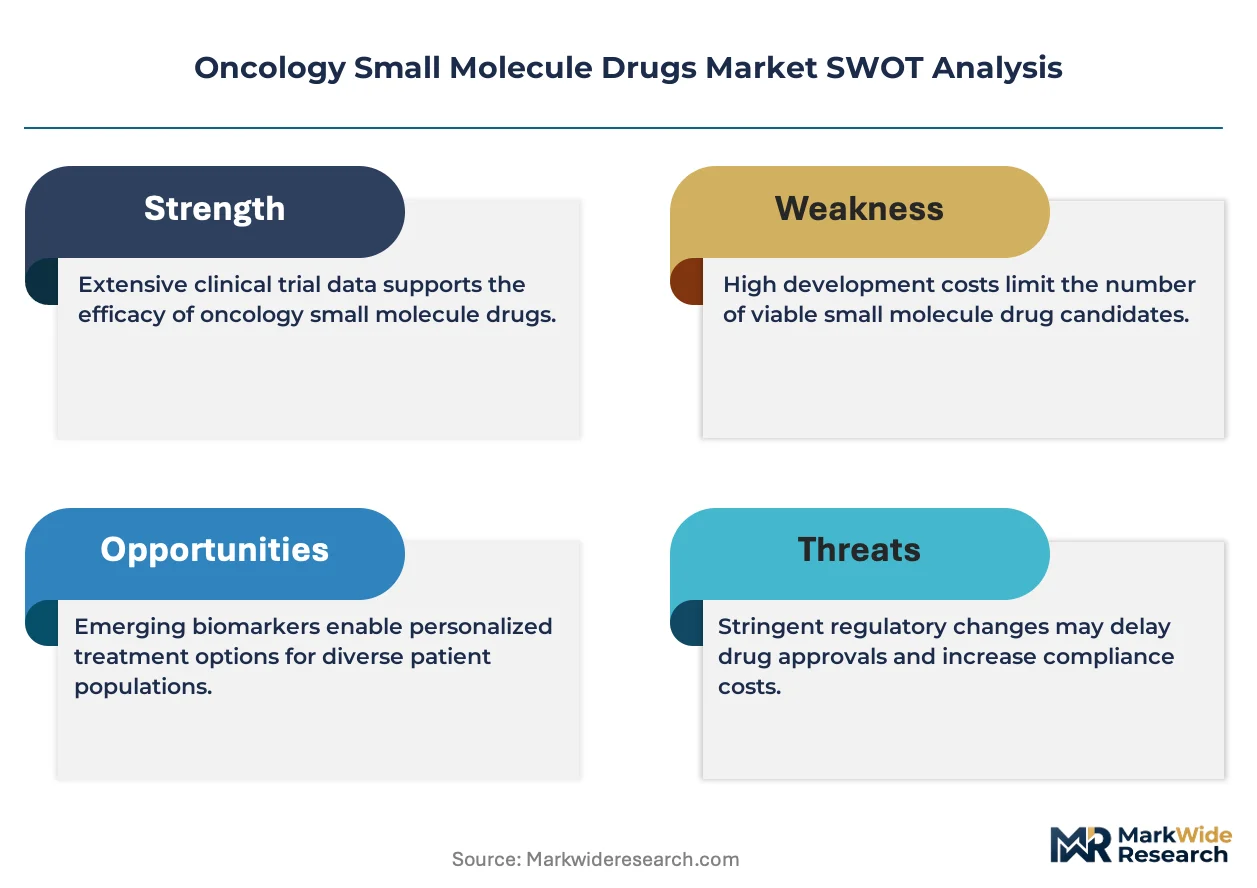
The competitive structure tilts toward diversified pharmaceutical conglomerates with broad oncology portfolios spanning kinase inhibitors, hormonal agents, and cytotoxic chemotherapy. Market concentration remains moderate with tiered positioning between global innovators and regional generic specialists. Two archetypes dominate: integrated innovators with end-to-end discovery-to-commercialization capabilities, and formulation-focused players leveraging cost-competitive manufacturing scale. Competitive moves center on portfolio diversification into adjacent therapy areas and strategic partnerships for companion diagnostic co-development.
Among Swiss-based pharmaceutical conglomerates, Roche and Novartis occupy positions exemplifying the integrated innovator archetype through breadth across targeted therapy segments. AstraZeneca represents the targeted specialization vector with concentration in precision oncology indications. Bristol Myers Squibb anchors the immuno-oncology convergence strategy where small molecule programs complement biologic checkpoint inhibitors.
| Leading Market Players |
|---|
| Roche |
| Merck & Co. |
| Novartis |
| AstraZeneca |
| Johnson & Johnson |
| Sanofi |
| Eli Lilly |
| Pfizer |
| Bristol Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
EMA's adaptive pathway framework and FDA's Project Orbis initiative gates qualified supply access for premium-tier kinase inhibitors by mandating synchronized multi-agency review capabilities. Manufacturers lacking regulatory science infrastructure face exclusion from premium pricing tiers reserved for sponsors with coordinated approval sequencing across United States, European Union, and Japan.
Pricing Analysis
Price erosion across established chemotherapy agents traces to patent cliff expirations and generic substitution acceleration in Chinese public hospital systems. Three-tier pricing structure across originator premium, licensed standard, and generic economy levels separates Roche and Novartis portfolios from Indian CDSCO-approved alternatives. Cost-down pressure on mature kinase inhibitors intensifies as German hospital procurement consortia consolidate volume allocation decisions. Community oncology practices in United States rural markets exhibit highest price sensitivity; academic medical centers with research funding show lowest.
Supply Chain Analysis
Direct-to-hospital specialty pharmacy channels handle high-value oral oncology demand while wholesale distributors manage generic chemotherapy volume. Active pharmaceutical ingredient manufacturing concentrates in China and India, with formulation development clustering in United States and Germany. Supply chains draw from specialized starting materials including tyrosine kinase scaffolds, cytotoxic alkylating precursors, and hormonal steroid backbones. Single-source vulnerability in cryo-electron microscopy structural biology services creates bottleneck risk for rational drug design programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tyrosine kinase inhibitor platforms are displacing cytotoxic chemotherapy backbones across lung and breast cancer protocols, compressing legacy manufacturing asset values while elevating precision oncology capabilities.
For Market Incumbents: Lock in companion diagnostic co-development partnerships to defend biomarker-driven patient stratification moats against emerging biosimilar entrants. Deepen backward integration into active pharmaceutical ingredient production across India and China to offset tariff exposure and quality consistency risks. Prioritize ISO quality management certification investments that accelerate batch release protocols across multi-territory production networks.
For New Entrants and Emerging Players: Fragment-based drug design capabilities offer technology-first wedge positioning against established high-throughput screening incumbents. Target United States rural markets where infusion center scarcity creates white space for oral formulation expansion. Pursue hospital-at-home reimbursement pathway development as differentiated go-to-market angle.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation frequency is the leading indicator that precision oncology platform valuations will detach from traditional pharmaceutical multiples. Five-to-ten year viability favors sponsors with integrated discovery-to-commercialization infrastructure over pure-play formulation developers. Monitor EMA conditional marketing authorization grant rates as inflection signal for European market access speed.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Biomarker integration with kinase inhibitors enables patient stratification and expands addressable populations. |
| Manufacturing Scale-Up in API Production | Capacity expansion in Indian and Chinese zones reduces geopolitical exposure for multinational sponsors. |
| Regulatory Science Harmonization | Alignment between FDA, EMA, and NMPA accelerates multi-territory launch sequencing for novel inhibitors. |
| Oral Formulation Engineering Investment | Bioavailability advancement decouples treatment from infusion center dependency in underserved regions. |
| Home Administration Model Development | Remote monitoring integration enables hospital-at-home reimbursement previously restricted to parenteral therapy. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this oncology small molecule drugs market assessment. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation validated segment estimates.
Data-stream reconciliation across treatment line, dosage form, administration route, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from patient volume projections, pricing trajectory assumptions, and therapy substitution elasticity estimates across the projection horizon. Forecast inputs incorporated companion diagnostic adoption curves and oral chemotherapy protocol expansion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement policy shifts or API supply disruption scenarios. Periodic stress-testing of base assumptions is recommended given concentration risk in China-India manufacturing zones and evolving Medicare price negotiation mechanics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market