
 Unit-Dose Respiratory Medications Market | 2026-2036
Unit-Dose Respiratory Medications Market Size, Share, and Industry Trends Forecast 2026-2036
Unit-Dose Respiratory Medications Market Analytics
Homecare settings is recalibrating demand patterns for unit-dose respiratory therapies as patients shift from institutional administration to self-managed inhalation regimens. GSK plc anchors its position through sustained R&D intensity in dry-powder inhaler platforms. AstraZeneca competes by leveraging biologic-naive patient access programs across ambulatory networks. Pfizer Inc. dominates manufacturing scale for corticosteroid unit-dose formats supplied to hospital formularies.
Unit-dose respiratory medications comprise pre-measured, single-administration pharmaceutical formulations delivered via inhalation devices with specified particle size distributions, typically engineered for mass median aerodynamic diameters between one and five micrometers to optimize pulmonary deposition. These products serve the primary commercial purpose of eliminating dosing variability, reducing contamination risk, and ensuring therapeutic consistency across acute and chronic obstructive pulmonary conditions. Inhalers lead product type segments due to established reimbursement pathways and patient familiarity, while nebulizers capture fastest-growing status in pediatric and geriatric populations requiring assisted delivery. Powder delivery mode occupies concentrated margin pools where formulation complexity creates technical barriers to generic substitution.
The FDA maintains stringent bioequivalence requirements for abbreviated new drug applications referencing unit-dose inhalation products, while the EMA enforces MDR device-drug combination rules that extend market access timelines. ISO 20072 standards govern in vitro testing protocols for orally inhaled products, directly shaping development costs and regional filing strategies. Stakeholders must monitor evolving pharmacopeial harmonization between USP and EP methodologies for delivered dose uniformity, as divergence in these standards determines where multi-region launches prove economically viable.
Market Dynamics
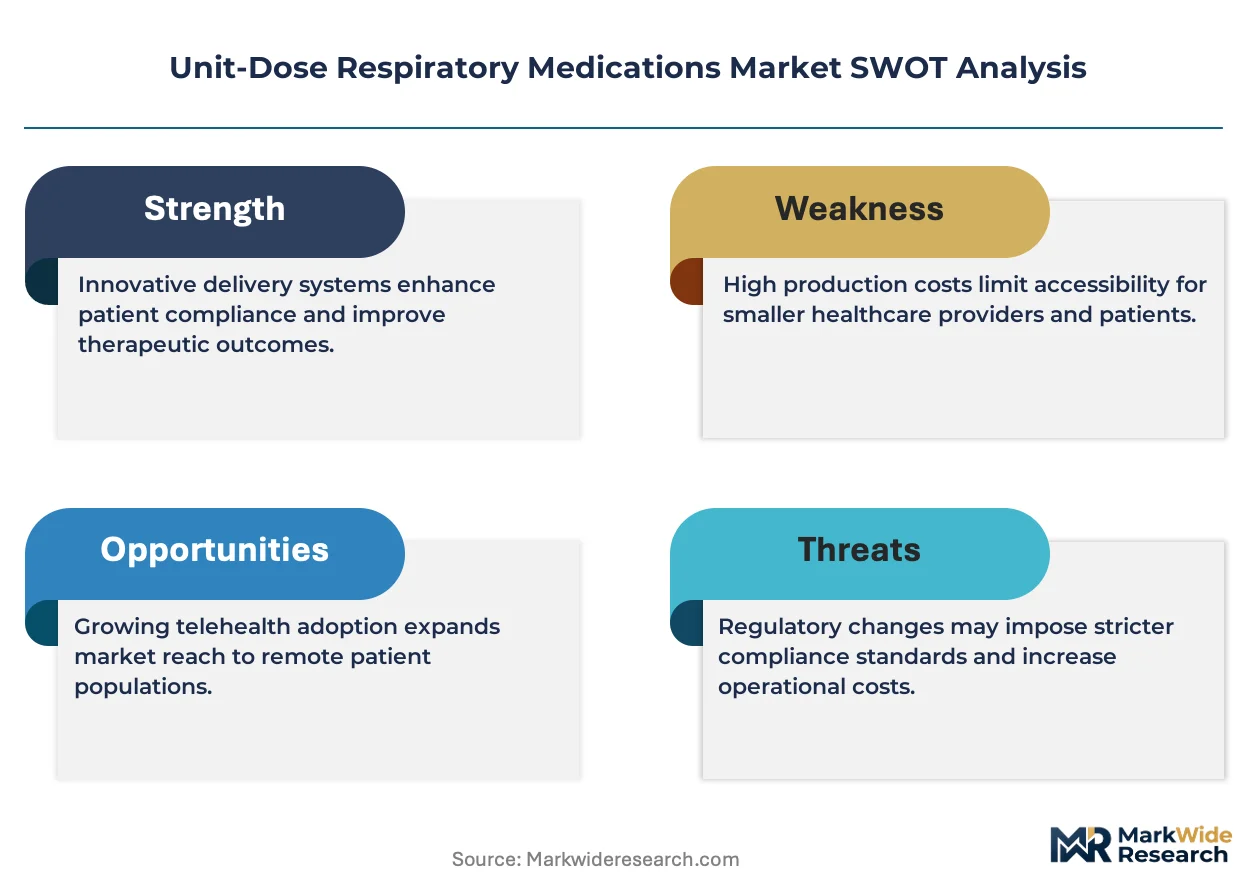
The FDA's tightened bioequivalence standards for abbreviated new drug applications referencing inhalation products are forcing reformulation investments and extending development timelines across the generic pipeline. This regulatory compression is redrawing competitive moats around established dry-powder and metered-dose platforms.
Growth Catalysts
- Homecare Migration:Patients in the United States, Germany, and Japan are shifting from institutional administration to self-managed inhalation regimens, expanding addressable volume for pre-metered therapies.
- EMA MDR Enforcement:The Medical Device Regulation's device-drug combination rules extend market access timelines for competitors, protecting incumbent positions through compliance complexity.
- Particle Engineering:Advances in spray-drying and jet-milling technologies are enabling tighter mass median aerodynamic diameter control, improving pulmonary deposition rates for corticosteroid and bronchodilator formulations.
Market Restraints
- API Concentration Risk:Active pharmaceutical ingredient supply for inhaled corticosteroids concentrates among Indian and Chinese contract manufacturers, exposing formulators to geopolitical friction and import disruption.
- Device Development Costs:ISO 20072 in vitro testing protocols and clinical endpoint studies for novel inhaler platforms demand capital outlays exceeding $150 million per program, excluding post-approval pharmacovigilance commitments.
- Generic Substitution Limits:The FDA's stringent bioequivalence requirements for locally-acting respiratory products block automatic pharmacy-level substitution, constraining price erosion and volume expansion for follow-on entrants.
Strategic Opportunities
- Pediatric Nebulizer Expansion:Japan's aging population and Germany's pediatric asthma prevalence create demand for breath-actuated nebulizer systems requiring minimal patient coordination.
- Biologic-Device Convergence:Monoclonal antibody formulations for severe asthma are migrating from subcutaneous injection to inhaled delivery, opening formulation partnerships between biotech developers and inhalation platform specialists.
- Reimbursement Pathway Innovation:Outcome-based contracting for chronic obstructive pulmonary disease management in United States Medicare Advantage plans rewards adherence-monitoring inhalers with preferred formulary placement.
Industry Challenges
- Inhaler Engineering Talent Scarcity:The specialized skill set combining fluid dynamics, materials science, and pharmaceutical formulation resides in a narrow cohort of professionals concentrated in Switzerland, the United Kingdom, and Massachusetts.
- Legacy Device Integration:Hospital formularies maintain substantial installed bases of proprietary nebulizer systems, creating switching friction for next-generation connected inhalers requiring IT infrastructure overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unit-Dose Respiratory Medications Market |
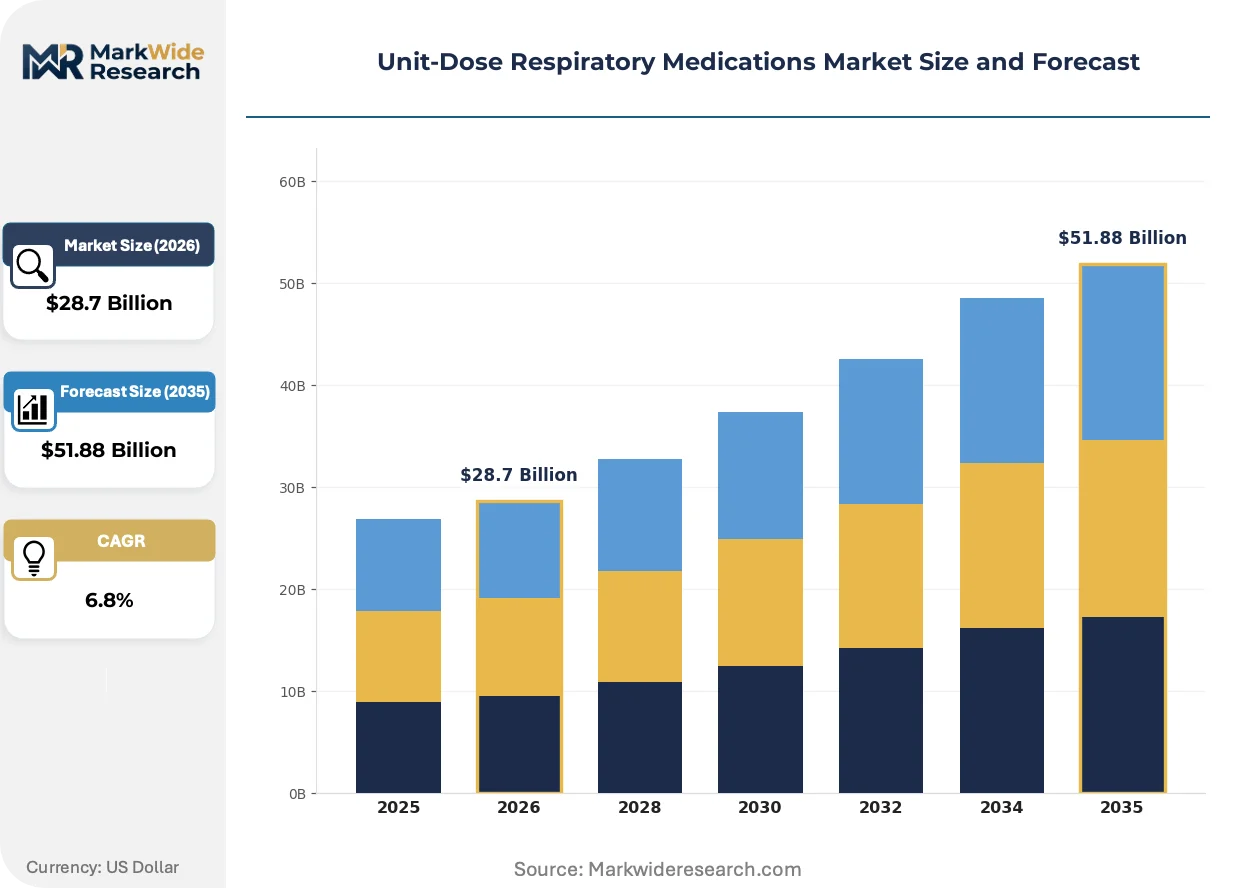
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Spacers, MDI Delivery Mode: Aerosol, Liquid, Powder, Gas End User: Hospitals, Clinics, Homecare, Pharmacies Approval Status: Approved, Under Review, Withdrawn, Others |
| Companies Covered | Pfizer Inc., GSK plc, AstraZeneca, Novartis AG, Teva Pharmaceutical Industries Ltd., Boehringer Ingelheim International GmbH, Merck & Co., Inc., Catalent Inc., Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unit-Dose Respiratory Medications Market Evolving Landscape
Connected inhalation platforms and particle engineering advances are compressing development cycles while expanding therapeutic possibilities beyond traditional small-molecule bronchodilators. These shifts are redefining how manufacturers capture value across the respiratory care continuum.
Digital dose-counters and Bluetooth-enabled adherence trackers are modularizing the inhaler into a data-generating node within remote patient monitoring ecosystems. Homecare providers in the United States are deploying these devices to reduce hospitalization rates among chronic obstructive pulmonary disease populations. The technology is modularizing reimbursement structures, separating device hardware from software analytics and clinical coaching services.
The EMA's MDR device-drug combination enforcement is extending technical documentation requirements for inhaler platforms marketed in Germany, France, and Italy. Manufacturers must now demonstrate clinical evidence for the specific device-drug pairing rather than referencing historical platform data. Pediatric and geriatric nebulizer segments face the steepest compliance burden, with notified body queue times stretching eighteen to twenty-four months.
Hospital procurement committees are consolidating respiratory therapy purchasing around single-platform contracts that bundle devices, disposables, and clinical training. This concentration is displacing fragmented multi-vendor arrangements in United States academic medical centers and German hospital networks. The shift is most visible in integrated delivery networks where pharmacy and respiratory therapy departments report to unified supply chain leadership.
Unit-Dose Respiratory Medications Market Segmentation
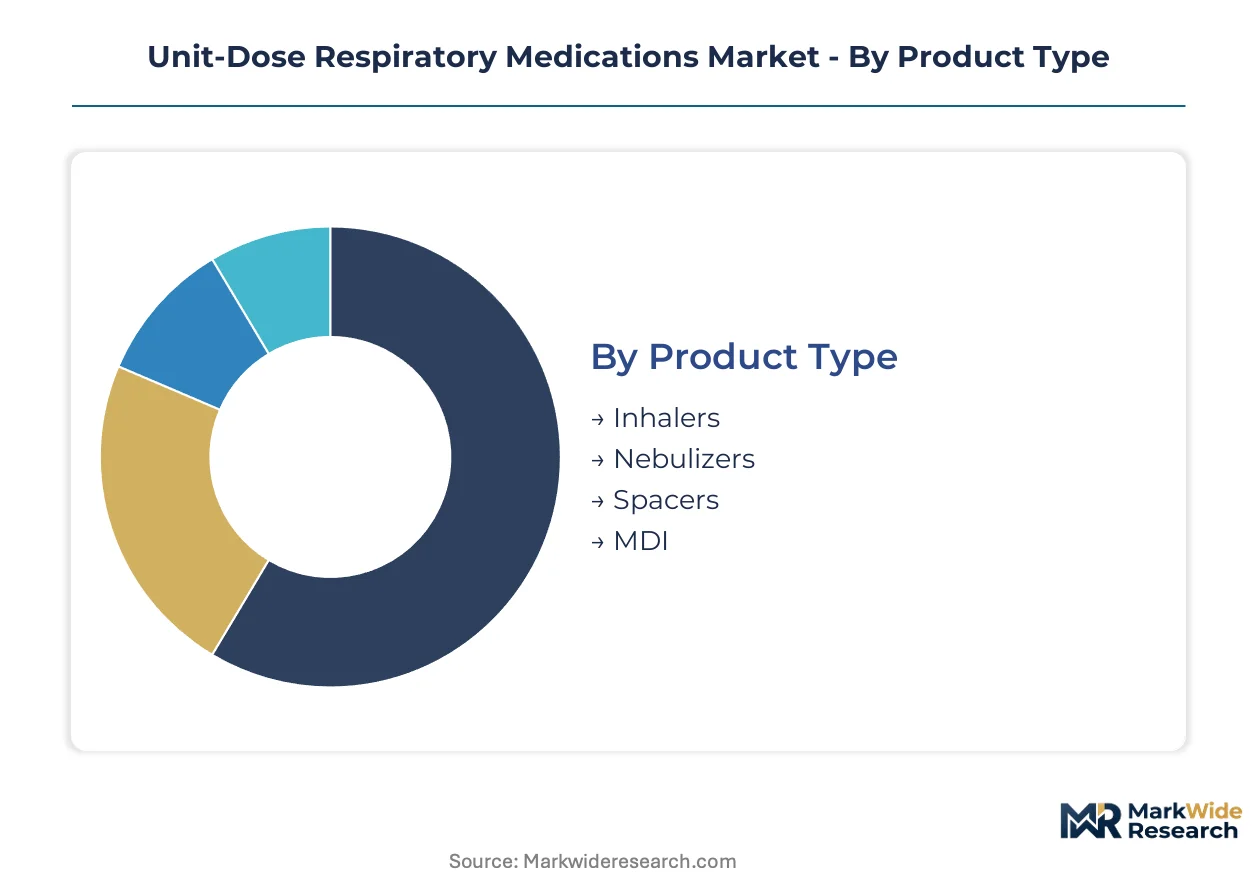
Segmentation in unit-dose respiratory medications reveals how formulation complexity, delivery physics, and care setting economics create distinct margin pools. Understanding these divisions exposes where technical barriers protect pricing power versus where commoditization pressures concentrate.
Product Type:
Inhalers command volume leadership through decades of patient familiarity and streamlined reimbursement, while nebulizers capture premium positioning in specialized populations requiring assisted delivery.
- Inhalers:Dry-powder and metered-dose platforms dominate ambulatory prescribing in the United States and Germany, where pharmacy benefit structures favor self-administered devices with established bioequivalence pathways. The installed base of proprietary designs creates switching friction for hospital formularies.
- Nebulizers:Compressor and mesh systems serve pediatric and geriatric patients in Japan's aging care facilities, where breath coordination limitations demand passive aerosol generation. Higher device costs and disposables consumption sustain elevated per-treatment economics compared to handheld alternatives.
- Spacers:Valved holding chambers improve lung deposition coordination for MDI-dependent populations in German pediatric asthma protocols, reducing oropharyngeal deposition of corticosteroid formulations.
- MDI:Pressurized metered-dose inhalers face propellant transition pressures under EU F-Gas Regulation, forcing hydrofluoroalkane reformulation investments across European manufacturing networks.
Today's leader: Inhalers. Tomorrow's challenger: Nebulizers.
Delivery Mode:
Physical state at administration determines formulation stability requirements, pulmonary deposition efficiency, and the capital intensity of manufacturing infrastructure.
- Aerosol:Suspension and solution formulations for nebulization require controlled particle engineering to achieve mass median aerodynamic diameters between one and five micrometers, with spray-drying technologies commanding specialized manufacturing footprints in Switzerland and Massachusetts.
- Liquid:Unit-dose vials and ampoules for nebulizer reservoirs serve acute care settings in United States hospitals, where single-use sterility eliminates cross-contamination risks in respiratory therapy departments.
- Powder:Micronized drug-carrier agglomerates for dry-powder inhalers occupy concentrated margin pools where lactose blend uniformity and moisture protection create technical barriers to generic substitution under FDA bioequivalence standards.
- Gas:Heliox and therapeutic gas mixtures for severe bronchospasm delivery remain confined to institutional settings with specialized ventilation infrastructure, limiting addressable volume despite premium per-dose pricing.
Powder and aerosol modalities concentrate proprietary value; liquid formats face greater price transparency in hospital procurement.
End User:
Care setting economics drive device selection, with reimbursement intensity declining from institutional administration toward patient-managed home therapy.
- Hospitals:Integrated delivery networks in the United States consolidate respiratory therapy purchasing around single-platform contracts bundling devices, disposables, and clinical training, displacing fragmented multi-vendor arrangements.
- Clinics:Pulmonology and allergy practices in Germany serve as gatekeepers for biologic-naive patient access programs, influencing device selection through prescriber familiarity and sample availability.
- Homecare:Medicare Advantage plans in the United States deploy connected inhalers with adherence monitoring to reduce chronic obstructive pulmonary disease hospitalization rates, separating device hardware from software analytics reimbursement.
- Pharmacies:Retail dispensing in Japan faces automatic substitution limits for locally-acting respiratory products, preserving originator volume despite generic availability for systemic medications.
Homecare channels are expanding most quickly; hospital concentration protects incumbent positions through contract lock-in.
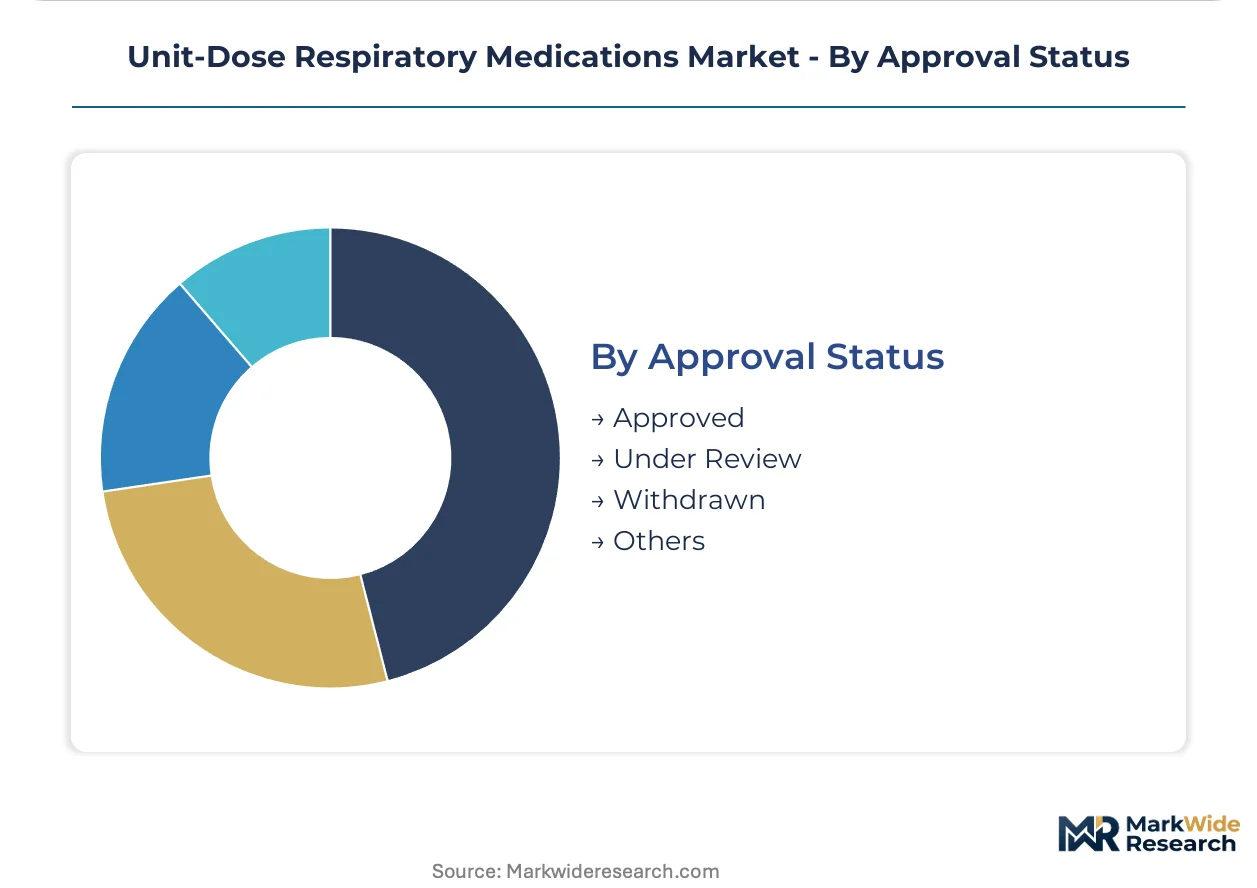
Approval Status:
Regulatory positioning determines market access velocity, with EMA MDR enforcement extending timelines for device-drug combinations relative to standalone pharmaceutical pathways.
- Approved:Established inhaler platforms with historical clinical evidence benefit from grandfathered regulatory positions, though EMA device-drug combination rules now demand specific pairing documentation rather than platform referencing.
- Under Review:Novel nebulizer systems and connected inhaler platforms face eighteen-to-twenty-four month notified body queue times in Germany, France, and Italy, compressing effective patent life for formulation-device pairings.
- Withdrawn:Products failing post-approval pharmacovigilance commitments or manufacturing quality standards create market openings for remaining suppliers, particularly in corticosteroid categories with concentrated API sourcing.
- Others:Compassionate use and emergency access pathways serve severe asthma populations in Japan with unmet need, generating real-world evidence that supports subsequent formal approval applications.
Approved status dominates current revenue; under-review pipeline concentration shapes competitive dynamics through 2035.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts anchors the global inhalation device engineering cluster, with Switzerland and the United Kingdom hosting specialized particle engineering capabilities. The United States, Germany, and Japan concentrate commercial demand through aging demographics and chronic respiratory disease prevalence.
United States
Medicare Advantage plans deploy connected inhalers with adherence monitoring to reduce chronic obstructive pulmonary disease hospitalization rates. The FDA maintains stringent bioequivalence requirements for abbreviated new drug applications referencing locally-acting respiratory products. Greater Boston hosts concentrated dry-powder inhaler R&D operations where fluid dynamics and materials science expertise co-locates with pharmaceutical formulation teams.
Germany
Pulmonology and allergy practices serve as gatekeepers for biologic-naive patient access programs, influencing device selection through prescriber familiarity. The EMA enforces MDR device-drug combination rules that extend market access timelines and demand specific pairing documentation. Bavaria and Baden-Württemberg concentrate notified body technical reviews, with queue times stretching eighteen to twenty-four months for novel nebulizer systems.
Japan
Aging care facilities drive demand for breath-actuated nebulizer systems requiring minimal patient coordination among geriatric populations. The PMDA oversees pharmacovigilance commitments for inhaled corticosteroid formulations with concentrated API sourcing exposure. The Kanto region around Tokyo hosts pharmaceutical distribution networks that preserve originator volume despite automatic substitution limits for systemic medications.
Switzerland
Spray-drying and jet-milling technologies for controlled particle engineering command specialized manufacturing footprints serving global respiratory formulators. Swissmedic aligns with EMA MDR enforcement for device-drug combinations marketed across European markets. The Basel-Zurich corridor concentrates inhalation platform specialists whose expertise spans fluid dynamics, materials science, and pharmaceutical formulation disciplines.
United Kingdom
The MHRA operates under retained EU MDR alignment for device-drug combination approvals while pursuing independent pharmacopeial harmonization strategies. London and the Southeast anchor clinical trial networks for novel inhalation platforms targeting severe asthma populations. Manufacturing operations in the Midlands supply unit-dose corticosteroid formats to hospital formularies under consolidated single-platform procurement contracts.
Unit-Dose Respiratory Medications Market Competitive Landscape
Regulatory compliance investments dominate the current landscape as EMA MDR enforcement and FDA bioequivalence standards extend development timelines and protect incumbent positions. The market structure concentrates around established pharmaceutical conglomerates with historical device platforms and specialized contract manufacturing organizations. Three archetypes prevail: originator pharmaceutical companies with proprietary inhaler designs, generic formulators navigating abbreviated approval pathways, and platform specialists engineering particle technologies. Competitive moves center on portfolio diversification into connected inhalation devices and strategic partnerships bridging biologic formulations with pulmonary delivery capabilities.
Within the originator pharmaceutical tier, GSK plc and AstraZeneca exemplify sustained R&D intensity in dry-powder platforms, while Pfizer Inc. occupies a position anchoring manufacturing scale for corticosteroid unit-dose formats supplied to hospital formularies. These companies represent the integrated archetype combining proprietary device engineering with formulation expertise and established reimbursement pathways.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GSK plc |
| AstraZeneca |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Catalent Inc. |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
API cost indices for inhaled corticosteroids cascade through formulation tiers, compressing margins for generic dry-powder inhalers while insulating originator platforms with device-drug combination protections. The EMA MDR enforcement and FDA bioequivalence standards amplify this stratification by extending development timelines and concentrating pricing power among incumbents with established regulatory dossiers.
Pricing Analysis
Input-cost pass-through from Indian and Chinese API suppliers intensifies price compression in liquid nebulizer formats where formulation barriers remain lowest. Three-tier pricing structure across premium connected inhalers, standard dry-powder devices, and economy nebulizer systems reflects certification grade and after-sales service bundling. Pricing pressure stems from hospital procurement consolidation around single-platform contracts in United States integrated delivery networks. Retail pharmacy channels in Japan exhibit lowest price sensitivity due to automatic substitution limits for locally-acting respiratory products.
Supply Chain Analysis
Regional distribution centers in Switzerland, Massachusetts, and the United Kingdom anchor hub-and-spoke patterns for finished inhaler devices serving European and North American markets. Active pharmaceutical ingredient production concentrates in India and China, with spray-drying equipment and precision milling components sourced from Switzerland and Germany. Single-source vulnerability in corticosteroid API supply exposes formulators to geopolitical friction and import disruption. Distribution runs through hospital GPO contracts in the United States, pharmacy networks in Germany, and aging care facility procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA MDR device-drug combination enforcement and FDA bioequivalence standards continuously extend competitive moats around established platforms.
For Market Incumbents: Hedge API concentration risk through backward integration into Indian contract manufacturing or dual-sourcing arrangements with secondary Chinese suppliers. Defend connected inhaler margins by embedding adherence-monitoring software into Medicare Advantage reimbursement pathways before patent cliff pressures intensify for legacy corticosteroid formulations. For New Entrants and Emerging Players: Enter via pediatric nebulizer segments in Germany and Japan where breath-actuated designs face lower switching friction against installed hospital bases. Target white-space in biologic-device convergence partnerships, positioning spray-drying capabilities as the bridge between monoclonal antibody developers and pulmonary delivery specialists. For Investors and Strategic Acquirers: Asymmetric upside sits with platform specialists combining particle engineering expertise with regulatory affairs capabilities spanning FDA and EMA jurisdictions. Long-term viability favors acquisition targets with captive supply relationships for micronized APIs and established notified body rapport in Bavaria or Baden-Württemberg. Watch for inflection signals in compassionate use pathway expansion for severe asthma populations in Japan.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | EMA notified body queue times of eighteen to twenty-four months protect incumbent positions through compliance barriers. |
| Connected Inhaler Platform Launch | Medicare Advantage outcome-based contracting rewards adherence-monitoring devices with preferred formulary placement. |
| Particle Engineering Partnership | Spray-drying specialists in Switzerland enable monoclonal antibody migration from injection to pulmonary delivery. |
| API Supply Diversification | Dual-sourcing from Indian and Chinese contract manufacturers reduces geopolitical exposure for corticosteroid formulations. |
| Pediatric Nebulizer System Development | Breath-actuated designs address coordination limitations in Germany's pediatric asthma and Japan's geriatric care facilities. |
Research Methodology
Bottom-up homecare setting modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at inhaler platform developers, formulary directors at United States hospital systems, procurement managers at German integrated delivery networks, and particle engineering specialists in Switzerland informed demand-side assumptions. Secondary validation drew from FDA ANDA filings, EMA MDR submission databases, ClinicalTrials.gov protocols, and ISO 20072 testing standard documentation. Cross-referencing bottom-up patient population estimates with top-down API consumption data from Indian and Chinese customs records anchored volume triangulation.
Historical trendline analysis of dry-powder inhaler adoption curves and nebulizer utilization patterns established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end-user care setting, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating EMA MDR timeline extensions and FDA bioequivalence pathway friction. Forecast inputs incorporated pharmacopeial harmonization progress between USP and EP delivered dose uniformity standards.
Inputs from EMA notified body queue databases and FDA ANDA approval tracking were available through the study window; gaps in real-time API pricing from Indian contract manufacturers introduce uncertainty bands around cost-pass-through assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Complement-Targeted Therapeutics Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Adamantane Antiviral Drugs Market