
 Power Battery Management System Market | 2026-2036
Power Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Power Battery Management System Market Outlook
Silicon carbide is restructuring thermal management economics across high-voltage battery architectures. Infineon Technologies leverages its SiC foundry investments to anchor premium traction inverter-BMS integration. Panasonic competes through cylindrical cell expertise and tight coupling with automotive OEM qualification cycles. CATL dominates cell-to-pack designs that eliminate module-level hardware, compressing BMS component counts.
A Power Battery Management System governs electrochemical cell arrays through voltage, current, and temperature telemetry with balancing actuation, typically operating across 400–800 VDC bus architectures in traction applications. Its primary purpose is to maximize usable energy capacity while preventing thermal runaway propagation and enforcing cycle-life boundaries under dynamic load profiles. Battery Control Modules capture the highest margin pools where ASIL-D functional safety certification creates qualification barriers for new entrants. Energy Management Systems are gaining fastest in commercial fleet deployments where cloud-connected degradation tracking enables residual value optimization. Solid-State technology segments command development priority despite manufacturing immaturity, given their compatibility with simplified sensing requirements.
The EPA tailpipe standards and NHTSA battery safety protocols in the United States are mandating cell-level fault detection latency below 100 milliseconds, forcing silicon migration in acquisition circuits. China's MIIT dual carbon goals and GB/T 34014 BMS communication standards are accelerating domestic substitution of imported analog front-ends. ECE R100 in Europe and UN GTR 20 harmonization are converging thermal propagation test requirements, compressing design cycles for multi-market platforms. Stakeholders must monitor solid-state electrolyte maturity signals and pre-position ASIL-D toolchain investments before qualification windows close on next-generation architectures.
Market Dynamics
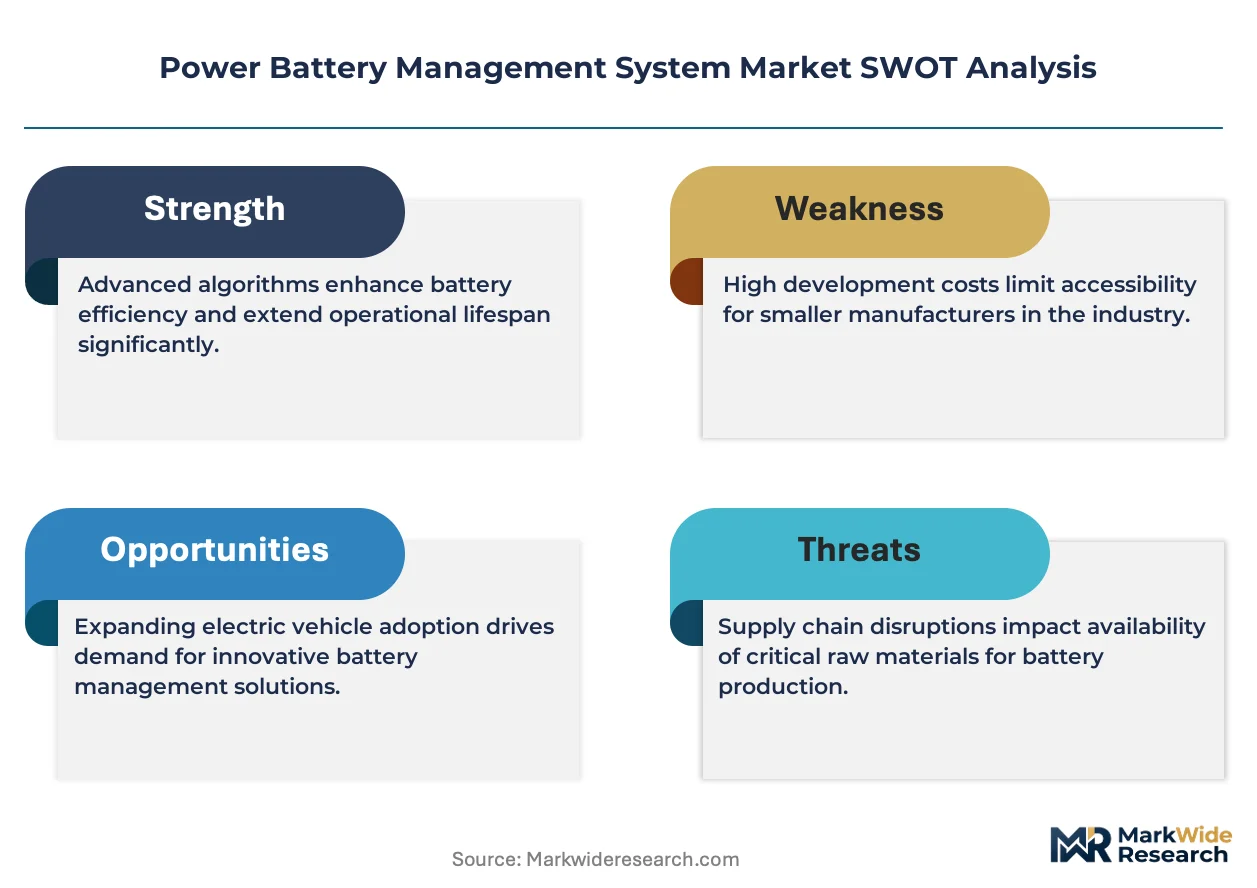
Silicon carbide power electronics and cell-to-pack architectures are compressing thermal management overhead while forcing ASIL-D toolchain investments across the supplier base.
Growth Catalysts
- GB/T 34014 BMS Communication Standards:China's MIIT mandates accelerate domestic substitution of imported analog front-ends, creating captive demand for local control module suppliers.
- Silicon Carbide Traction Inverters:Automotive OEMs in Germany are integrating SiC-based power stages with battery management platforms to reduce switching losses and thermal mass.
- Commercial Fleet Telemetry:Cloud-connected degradation tracking in Jiangsu and Guangdong provinces enables residual value optimization, pulling Energy Management System deployments.
Market Restraints
- ASIL-D Certification Barriers:Functional safety qualification timelines and toolchain costs lock new entrants out of Battery Control Module margin pools.
- Solid-State Electrolyte Immaturity:Manufacturing yield gaps in sulfide and oxide chemistries delay simplified sensing architectures promised for next-generation platforms.
- Analog Front-End Concentration:Import dependency for high-voltage acquisition circuits exposes supply chains to geopolitical friction and allocation risk.
Strategic Opportunities
- ECE R100 Harmonization:Converged thermal propagation test requirements across Europe compress design cycles for multi-market platforms, favoring modular BMS suppliers.
- Cell-to-Pack Architecture Migration:Elimination of module-level hardware in Chinese cell factories reduces component counts and opens tier-2 sensing opportunities.
- Second-Life Battery Tracking:Cloud-based state-of-health monitoring for stationary storage creates aftermarket software revenue streams.
Industry Challenges
- Functional Safety Engineering Scarcity:ASIL-D certified firmware architects and systems engineers command premium compensation, constraining R&D scaling.
- Multi-Chemistry Validation Burden:NCM, LFP, and solid-state cell variants require parallel qualification tracks, fragmenting test resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Battery Management System Market |
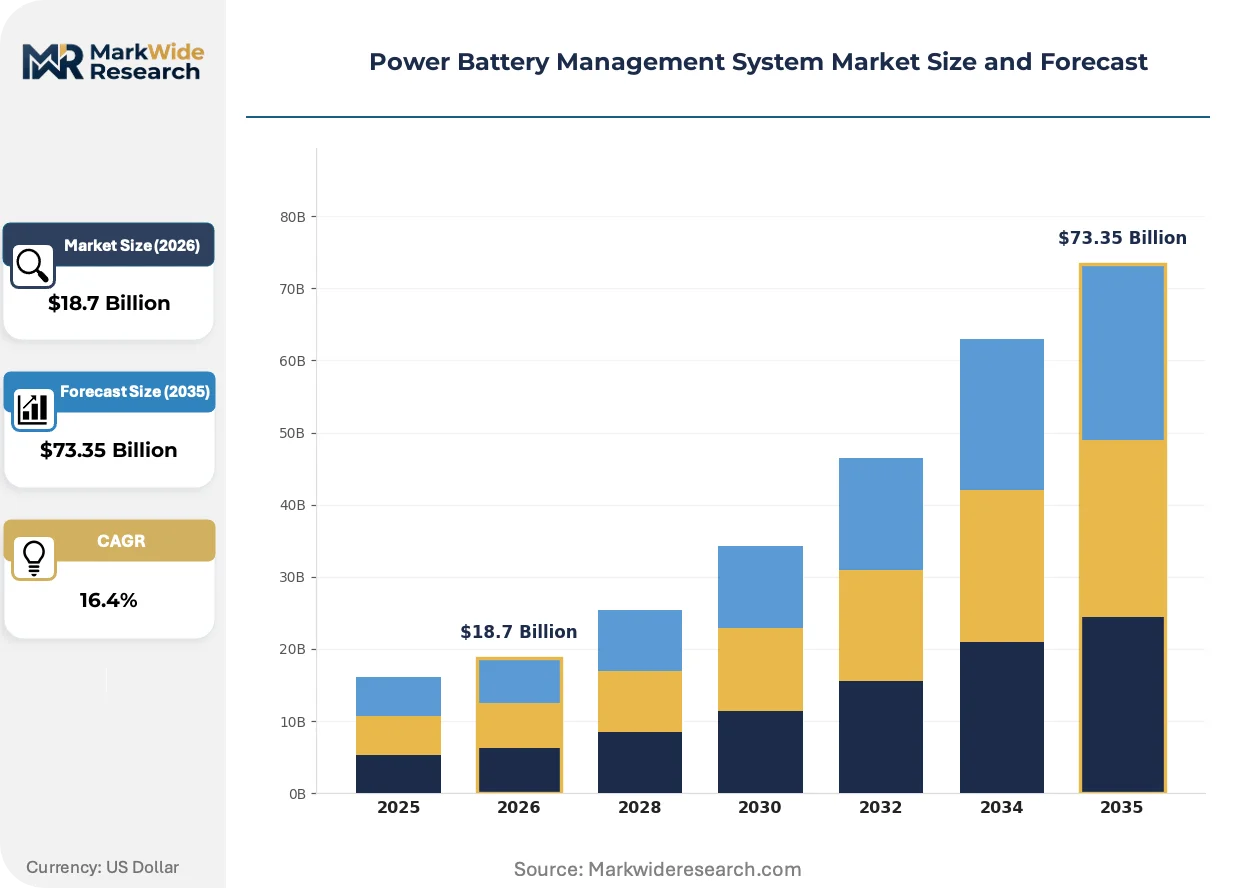
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Board Chargers, Energy Management Systems, Battery Control Modules, Battery Monitors End User: Automotive OEMs, Industrial Users, Renewable Energy Providers, Commercial Fleet Operators Technology: Li-ion, NiMH, Lead-Acid, Solid-State Installation: Embedded, Standalone, Integrated, Retrofit |
| Companies Covered | Panasonic, CATL, Texas Instruments, Bosch, Renesas Electronics, NXP Semiconductors, LG Chem, Infineon Technologies, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Battery Management System Market Strategic Shifts
Electrification mandates and silicon carbide maturation are restructuring how battery control electronics integrate with powertrain architectures.
Cell-to-pack topology is unifying voltage sensing and balancing functions at the cell level, eliminating intermediate module controllers. Tier-1 suppliers in Germany and China are adopting this architecture for 800 VDC platforms to reduce wiring harness mass. The technology is unifying thermal and electrical management into single substrate designs, compressing bill-of-materials overhead by removing discrete harness connectors.
EPA tailpipe standards and NHTSA battery safety protocols in the United States mandate cell-level fault detection latency below 100 milliseconds. This forces silicon migration in acquisition circuits and accelerates edge-computing investments at the Battery Control Module layer. High-voltage passenger vehicle segments face the steepest compliance cost escalation.
Fleet operators are consolidating procurement around vertically integrated platform providers who bundle hardware, cloud analytics, and residual value guarantees. This displaces discrete component sourcing for commercial vehicle deployments. The pattern is most visible in China's Jiangsu province, where logistics operators negotiate total-cost-of-ownership contracts spanning battery life cycles.
Power Battery Management System Market Segmentation
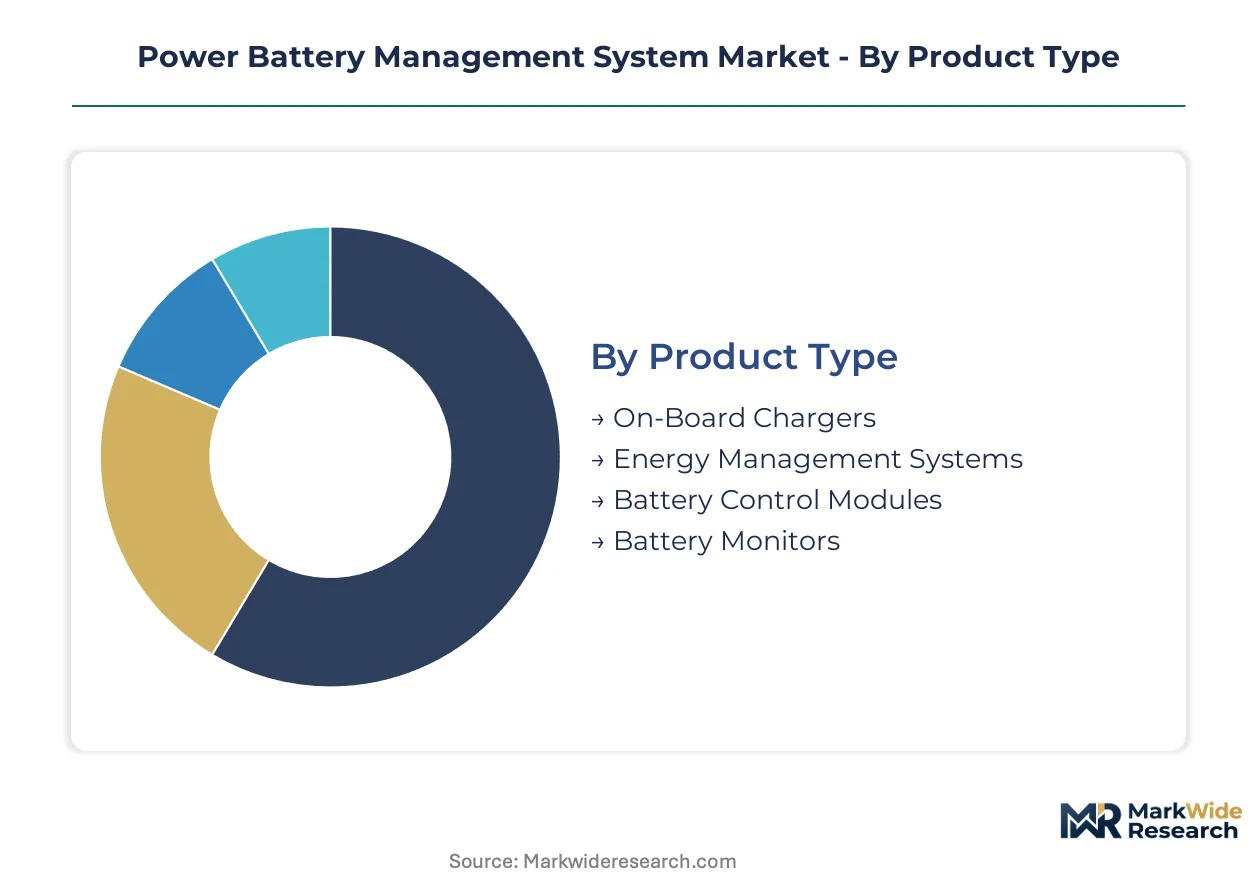
Segmentation in battery management systems reveals how voltage architectures, safety certification tiers, and integration depth fragment procurement decisions across automotive and stationary applications. Suppliers must align product roadmaps with the specific telemetry density and functional safety requirements of each segment cluster.
Product Type:
Voltage handling specifications and ASIL certification requirements differentiate margin pools across hardware categories.
- Battery Control Modules:These units execute cell balancing, state estimation, and fault isolation through ASIL-D certified firmware. German automotive OEMs concentrate procurement here for 800 VDC traction platforms, where functional safety qualification creates supplier lock-in.
- Energy Management Systems:Cloud-connected platforms aggregate fleet-level degradation data to optimize residual value. Commercial fleet operators in Jiangsu province are consolidating procurement around these systems for total-cost-of-ownership contracts.
- On-Board Chargers:AC/DC conversion stages with integrated BMS communication interfaces for plug-in hybrid architectures.
- Battery Monitors:Distributed voltage and temperature sensing nodes with CAN or wireless backhaul for simplified cell-to-pack designs.
Mature deployment sits with Battery Control Modules. Newer deployment is concentrated in Energy Management Systems.
End User:
Procurement scale and integration depth separate volume-driven automotive contracts from specialized industrial deployments.
- Automotive OEMs:Tier-1 suppliers qualify integrated BMS-inverter platforms through multi-year vehicle programs. China's MIIT dual carbon goals and GB/T 34014 standards are accelerating domestic substitution of imported analog front-ends in these supply chains.
- Commercial Fleet Operators:Logistics providers negotiate battery lifecycle contracts with cloud-based state-of-health guarantees. Guangdong province operators are pioneering this procurement model for electric heavy-duty trucks.
- Industrial Users:Forklift and material handling equipment manufacturers sourcing CAN-based monitoring for lead-acid replacement cycles.
- Renewable Energy Providers:Utility-scale storage integrators requiring multi-chemistry compatibility for grid stabilization services.
Volume concentration rests with Automotive OEMs. Fastest expansion is occurring in Commercial Fleet Operators.
Technology:
Electrochemical characteristics dictate sensing architecture complexity and thermal management overhead.
- Li-ion:NCM and LFP variants dominate current production with established voltage-temperature correlation models for state-of-charge estimation.
- Solid-State:Sulfide and oxide electrolytes promise simplified sensing due to reduced thermal runaway risk, though manufacturing yield gaps delay volume deployment. Development priority remains high given compatibility with 800 VDC architectures.
- NiMH:Hybrid vehicle residual demand requiring robust overcharge protection algorithms.
- Lead-Acid:Starter battery replacement in commercial vehicle auxiliary systems with basic voltage threshold monitoring.
Production maturity centers on Li-ion. Technology transition investment is flowing into Solid-State.
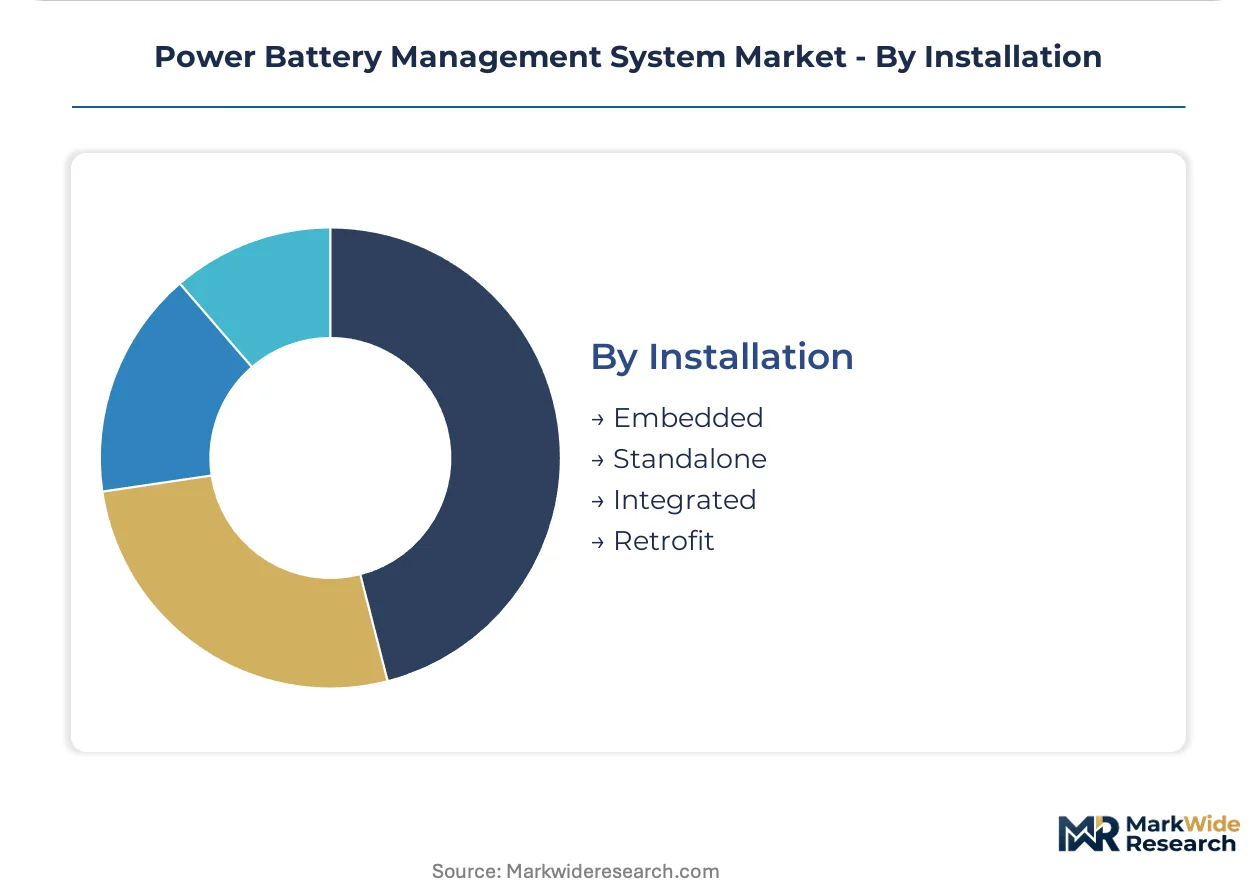
Installation:
Physical integration mode determines wiring harness mass and thermal management coupling efficiency.
- Embedded:BMS electronics mounted directly on cell terminals or pack enclosures, eliminating discrete harness connectors. Cell-to-pack architectures in Chinese factories are standardizing this approach.
- Integrated:Traction inverter and BMS control sharing power electronics substrates, reducing switching losses through silicon carbide power stages.
- Standalone:Remotely mounted control units for retrofit applications or service replacement scenarios.
- Retrofit:Aftermarket monitoring systems for second-life battery tracking in stationary storage deployments.
Design standardization favors Embedded configurations. Aftermarket opportunity is building in Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volume for integrated battery control platforms, while Germany and the United States shape regulatory frameworks that cascade through supplier qualification requirements.
China
MIIT dual carbon goals and GB/T 34014 BMS communication standards accelerate domestic substitution of imported analog front-ends. Cell-to-pack architectures dominate new capacity builds in Jiangsu and Guangdong provinces, where logistics operators negotiate total-cost-of-ownership contracts spanning battery life cycles.
Germany
Automotive OEMs integrate silicon carbide power stages with battery management platforms to reduce switching losses. ECE R100 harmonization with UN GTR 20 converges thermal propagation test requirements, compressing design cycles for multi-market qualification programs.
United States
EPA tailpipe standards and NHTSA battery safety protocols mandate cell-level fault detection latency below 100 milliseconds. Silicon migration in acquisition circuits accelerates edge-computing investments at the Battery Control Module layer for high-voltage passenger platforms.
Japan
METI industrial policy supports solid-state electrolyte development through public-private research consortia. Cylindrical cell expertise maintains tight coupling with automotive OEM qualification cycles, preserving established supply relationships.
South Korea
MFDS-aligned functional safety certification requirements mirror automotive export destination standards. Domestic battery producers advance cell-to-pack designs for 800 VDC architectures, reducing module-level hardware dependency.
Power Battery Management System Market Competitive Environment
Strategic partnerships dominate the current landscape as tier-1 suppliers anchor integrated BMS-inverter platforms through multi-year vehicle programs. The supplier base organizes around three archetypes: semiconductor foundries with silicon carbide investments, battery cell manufacturers with captive control electronics, and discrete component specialists with ASIL-D toolchain capabilities. M&A activity concentrates in analog front-end assets, while capacity expansion targets cell-to-pack sensing module production.
Within the semiconductor tier, Infineon Technologies and Texas Instruments occupy positions defined by power electronics substrate integration. Panasonic exemplifies the cell manufacturer archetype through cylindrical cell expertise. CATL anchors the battery producer segment with cell-to-pack designs that eliminate module-level hardware. Bosch represents the tier-1 systems integrator position, spanning hardware qualification and automotive OEM program management.
| Leading Market Players |
|---|
| Panasonic |
| CATL |
| Texas Instruments |
| Bosch |
| Renesas Electronics |
| NXP Semiconductors |
| LG Chem |
| Infineon Technologies |
| Analog Devices |
| Others |
Value Chain & Pricing Dynamics
Cell-to-pack architecture migration simultaneously compresses bill-of-materials overhead and concentrates procurement leverage among Chinese cell manufacturers who internalize sensing module production. ASIL-D certification barriers lock tier-2 suppliers out of Battery Control Module margin pools while silicon carbide substrate integration reshapes cost economics for 800 VDC platforms.
Pricing Analysis
Volume concentration in Battery Control Modules contrasts with margin capture in Energy Management Systems where cloud-connected degradation tracking commands premium pricing. Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and uncertified economy levels reflects functional safety qualification depth. Pricing pressure stems from domestic substitution mandates under China's GB/T 34014 standards accelerating local analog front-end production. Commercial fleet operators in Jiangsu province exhibit highest price sensitivity through total-cost-of-ownership contract negotiations, while German automotive OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Analog front-end supply rests on concentrated semiconductor fabrication in Taiwan, South Korea, and Germany where high-voltage acquisition circuit production is anchored. Silicon carbide substrates, ASIL-D certified microcontrollers, and precision voltage sensing ICs constitute critical input dependencies. Single-source vulnerability in SiC wafer supply exposes tier-1 integrators to allocation risk during automotive OEM capacity ramps. Distribution runs through tier-1 systems integrators who bundle hardware qualification with multi-year vehicle program management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over analog front-end supply and ASIL-D toolchain capabilities determines competitive position. Players are pursuing backward integration into high-voltage sensing semiconductor assets to defend margin pools.
For Market Incumbents: Acquire analog front-end semiconductor assets to secure high-voltage acquisition circuit supply against allocation risk. Deepen captive production of cell-to-pack sensing modules in Jiangsu and Guangdong manufacturing clusters. Lock in multi-year automotive OEM qualification cycles before solid-state electrolyte maturity opens architecture redesign windows. For New Entrants and Emerging Players: Begin with tier-2 sensing module opportunities opened by cell-to-pack hardware elimination in Chinese cell factories. Target aftermarket retrofit deployments for second-life battery tracking where ASIL-D barriers do not apply. Pursue cloud analytics partnerships with commercial fleet operators seeking residual value optimization without full platform integration. For Investors and Strategic Acquirers: Exit pathways concentrate in semiconductor foundry acquisitions and tier-1 systems integrator rollup strategies. Long-term viability hinges on positioning before solid-state chemistry migration closes qualification windows on next-generation architectures. Watch sulfide electrolyte manufacturing yield breakthroughs as the inflection signal for sensing architecture simplification.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Toolchain Acquisition | Infineon and NXP consolidate functional safety firmware capabilities to lock automotive OEM qualification cycles. |
| Cell-to-Pack Sensing Module Expansion | CATL and BYD internalize voltage acquisition production in Jiangsu factories to compress component counts. |
| Solid-State Electrolyte Partnership | Panasonic and Toyota anchor sulfide chemistry development through METI-supported research consortia. |
| Cloud Fleet Analytics Platform Launch | Commercial operators in Guangdong deploy degradation tracking for electric heavy-duty truck residual value guarantees. |
| SiC Substrate Integration Investment | Bosch merges traction inverter and BMS control electronics to reduce switching losses in 800 VDC architectures. |
Study Parameters
Document review covered automotive OEM technical specifications, MIIT regulatory filings, and SEC supplier disclosures, complemented by interviews with tier-1 procurement directors, BMS firmware architects, and commercial fleet operations managers. Secondary sources included GB/T standard documentation, ECE R100 harmonization texts, and NHTSA battery safety protocol amendments. Bottom-up cell shipment data triangulated against top-down vehicle production forecasts across the analysis window.
Historical volume trajectories cross-referenced against expert panel inputs on solid-state electrolyte maturity timelines and SiC adoption curves. Segmentation modeling spanned voltage architecture, ASIL certification tier, installation mode, and end-user procurement pattern. CAGRs derived from unit economics analysis of cell-to-pack hardware elimination and cloud-connected service attach rates.
Solid-state manufacturing yield gaps, ASIL-D certification timeline extensions, and analog front-end supply allocation constraints are the dominant revision risks to projection assumptions. A concentrated set of electrolyte chemistry and semiconductor supply triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
North America Battery Management System Market
Battery Management System
US Energy Storage Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Global Power Management System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Battery Energy Management System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
United States Rechargeable Battery Market