
 Asia-Pacific Automotive Battery Thermal Management System Market | 2026-2036
Asia-Pacific Automotive Battery Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Battery Thermal Management System Market Analytics
GB/T 31467.3 battery abuse testing is unwinding supplier eligibility across the Asia-Pacific thermal management landscape. Denso Corporation leverages its compressor integration depth to anchor Japanese OEM programs. Robert Bosch competes through its smart valve architecture for liquid-cooled packs. Hanon Systems specializes in refrigerant-based cooling loops for Korean battery plants.
Automotive battery thermal management systems regulate cell temperature through liquid coolant circulation, refrigerant loops, or phase change materials to prevent thermal runaway and optimize charge acceptance. Liquid cooling dominates product type configurations due to energy density requirements in NCM and LFP cell formats. Active systems lead technology adoption where ambient temperatures exceed design thresholds, while hybrid systems are gaining traction in cost-sensitive electric bus deployments across India and Southeast Asia. Passenger vehicles channel the largest end user volume, though commercial vehicle fleets are shifting toward service-contract thermal monitoring to extend pack life.
China's MIIT enforces GB standards that mandate coolant isolation and fire suppression integration in battery enclosures. India's BIS is drafting thermal propagation test protocols aligned with AIS 156 amendments for electric two-wheelers and light commercial vehicles. Japan's METI subsidizes solid-state battery development with companion thermal management qualification requirements. Stakeholders must track which certification cycles each national regulator accelerates or delays, as these gates determine supplier qualification timelines and factory utilization rates across the region.
Market Dynamics
China's MIIT enforcement of GB/T 31467.3 battery abuse testing is compressing supplier qualification timelines while Indian electric bus fleets are scaling active liquid cooling procurement. This regulatory tightening intersects with manufacturing corridor concentration in Jiangsu and Guangdong provinces.
Growth Catalysts
- GB standards tightening:China's MIIT mandates coolant isolation and fire suppression integration in battery enclosures, disqualifying legacy passive cooling architectures from new vehicle platforms.
- Electric bus fleet scaling:State transport utilities in India and Thailand are issuing multi-year thermal management service contracts for liquid-cooled NCM and LFP packs.
- Refrigerant loop specialization:Korean battery plants are specifying R-1234yf-based cooling circuits for high-C-rate fast-charging stations, pulling component demand toward active refrigeration architectures.
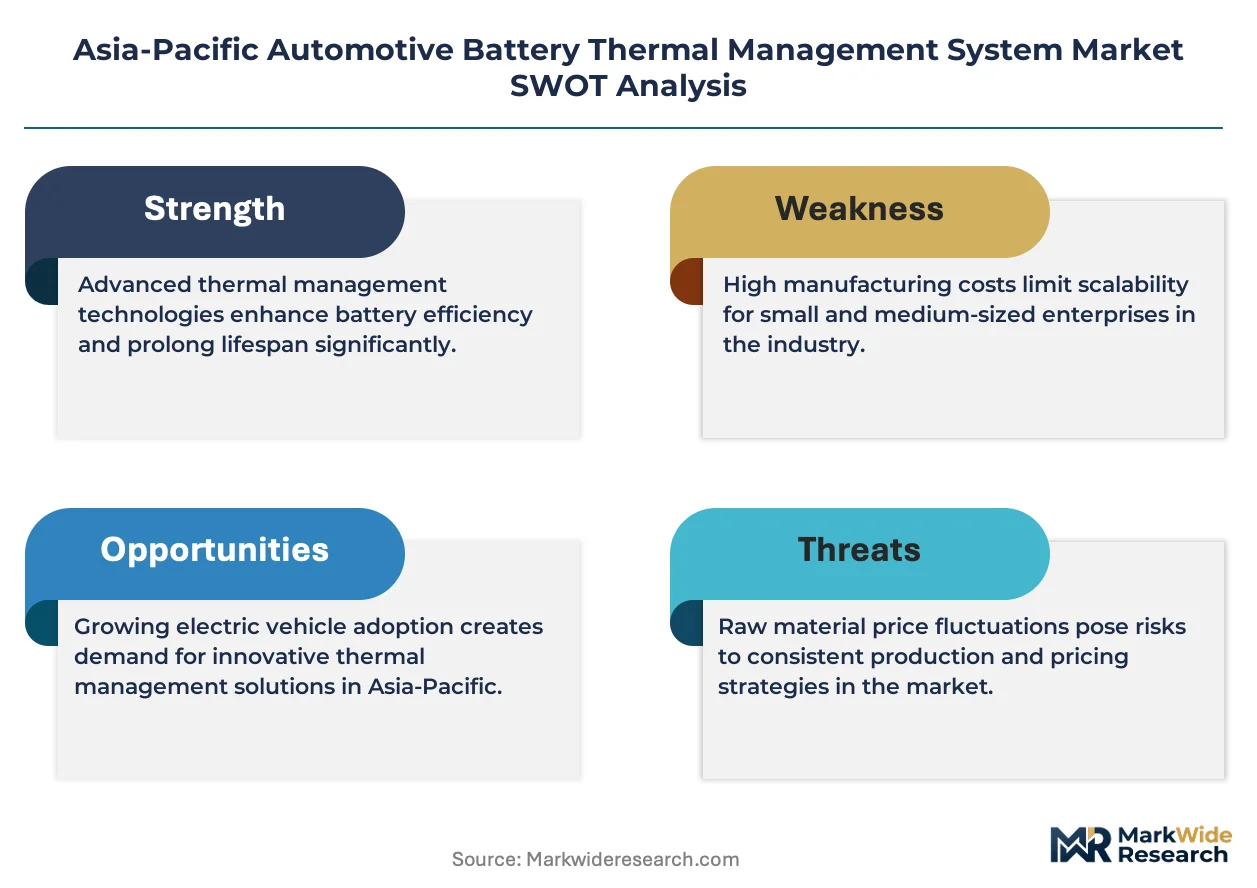
Market Restraints
- Coolant fluid cost volatility:Dielectric fluid prices fluctuate with fluorochemical feedstock availability, squeezing margin on liquid-cooled pack assemblies.
- Supply concentration in Jiangsu:Pump and valve subcomponent manufacturing clusters in eastern China create single-point vulnerability for tier-two thermal system integrators.
- Phase change material substitution:PCM passive cooling threatens active system penetration in cost-sensitive electric two-wheeler segments across Vietnam and Indonesia.
Strategic Opportunities
- Indian electric two-wheeler underpenetration:AIS 156 amendment drafts for thermal propagation testing create first-mover advantage for qualified active cooling suppliers in the sub-5kWh segment.
- Japan METI solid-state subsidy:Companion thermal management qualification requirements for solid-state cell formats open new specification windows for next-generation heat spreader materials.
- Service-contract channel emergence:Fleet operators in Australia and Singapore are unbundling thermal monitoring from vehicle purchase, creating recurring revenue streams for predictive maintenance platforms.
Industry Challenges
- Thermal simulation talent scarcity:CFD modeling expertise for cell-level thermal runaway prediction remains concentrated among automotive OEM engineering centers, constraining tier-one supplier design velocity.
- GB/T certification timeline compression:Accelerated abuse testing cycles are forcing parallel validation tracks that strain prototype build capacity.
- Legacy refrigerant infrastructure:Southeast Asian service networks lack R-1234yf handling certification, complicating aftermarket expansion for Korean-spec cooling loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Battery Thermal Management System Market |
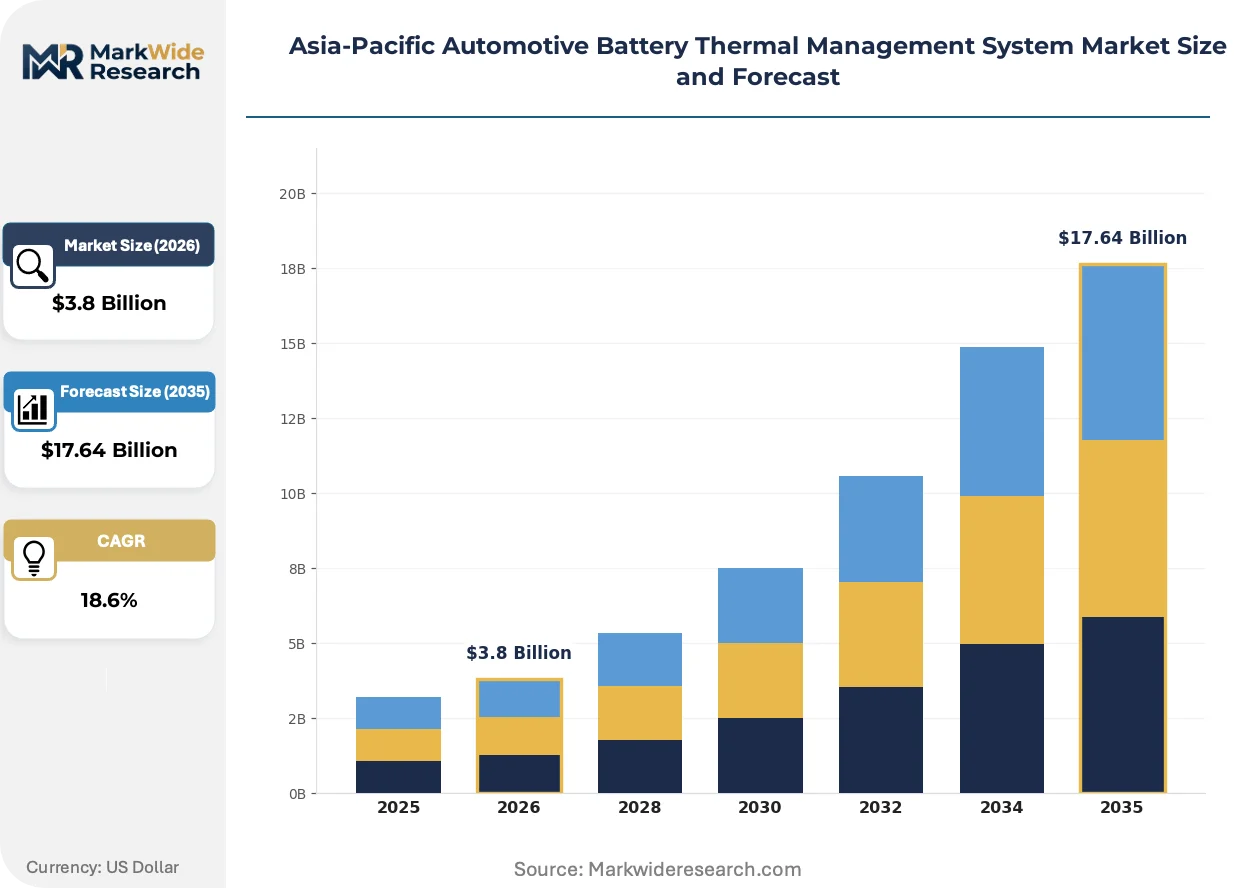
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cooling, Air Cooling, Phase Change Materials, Thermoelectric Cooling Technology: Active Systems, Passive Systems, Hybrid Systems, Smart Controls Vehicle Type: Passenger Vehicles, Commercial Vehicles, Electric Buses, Two-Wheelers End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Denso Corporation, Continental AG, Robert Bosch, Hanon Systems, Valeo SA, Mahle GmbH, LG Chem, Samsung SDI, Panasonic Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Battery Thermal Management System Market Evolving Landscape
Active thermal management architectures are fragmenting across multiple cooling modalities as cell chemistry diversity and fast-charging power levels multiply design requirements. This specialization is pulling the supply base away from standardized platform solutions.
Immersion cooling using engineered dielectric fluids is fragmenting competitive positioning in the high-performance electric vehicle segment. Premium passenger car platforms in China and Korea are adopting submerged cell architectures for 4C+ charging capability. This modality is fragmenting the incumbent liquid cold plate supply chain by eliminating channel-based heat exchangers entirely.
China's GB standards evolution is mandating redundant coolant isolation valves and fire suppression integration in battery enclosures. MIIT enforcement timelines are compressing from 18-month to 12-month qualification cycles. Commercial vehicle OEMs in India are accelerating local supplier partnerships to meet parallel BIS thermal propagation protocols.
Fleet procurement departments are unbundling thermal system monitoring from vehicle capital expenditure, signing multi-year service contracts with guaranteed cell temperature performance. Electric bus operators in Thailand and Vietnam are leading this shift toward outcome-based thermal management. This contractual innovation is most visible where state transport utilities face budget constraints but require extended pack lifecycle warranties.
Asia-Pacific Automotive Battery Thermal Management System Market Segmentation
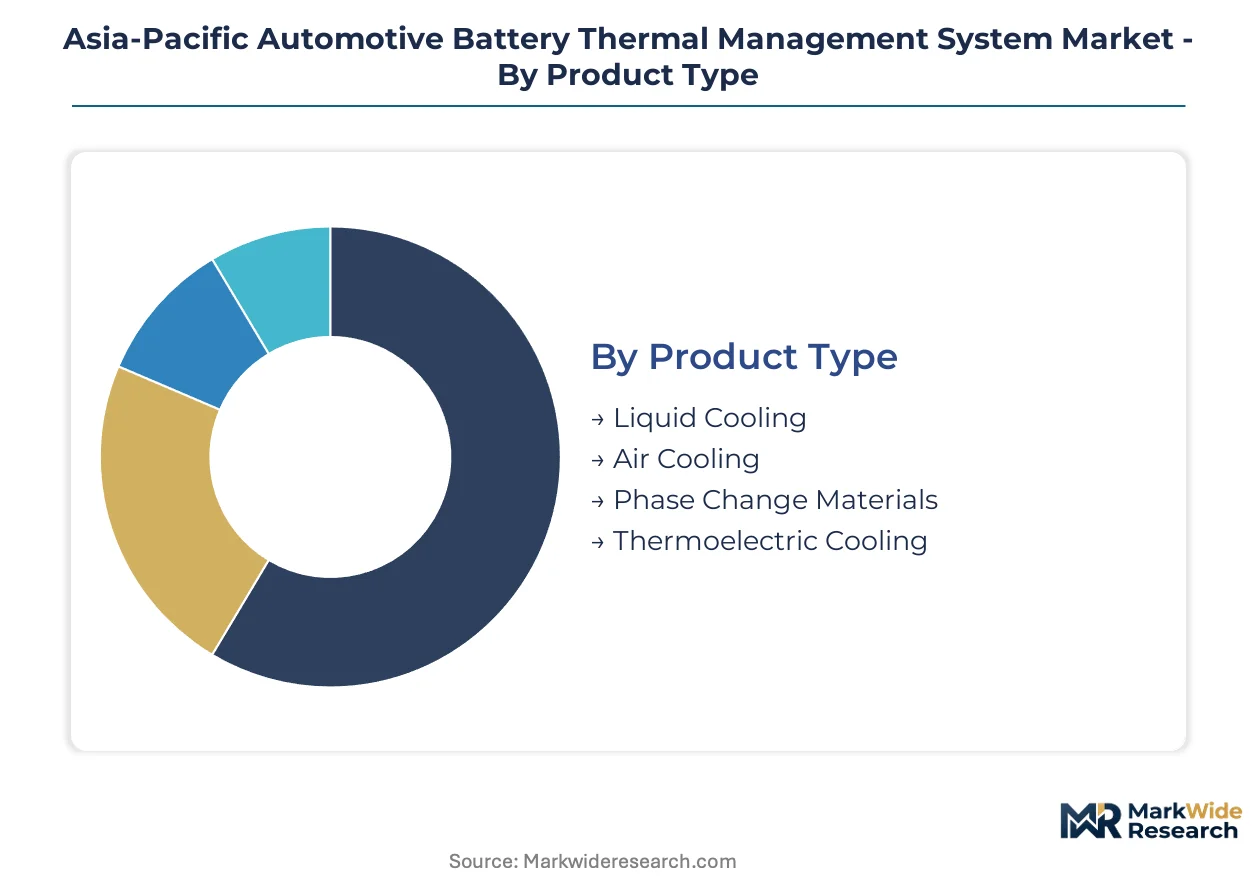
Thermal management procurement patterns diverge sharply across cooling modalities and vehicle electrification tiers. Segment boundaries determine qualification timelines, margin capture, and supplier positioning against tightening GB standards and BIS protocols.
Product Type:
Margin pools concentrate in liquid-cooled assemblies where dielectric fluid specifications and fire suppression integration command premium pricing against passive alternatives.
- Liquid Cooling:Circulates glycol-water mixtures or engineered dielectrics through cold plates or immersion baths to extract heat from NCM and LFP cell formats. Chinese OEMs in Jiangsu and Guangdong manufacturing corridors specify redundant coolant isolation valves under MIIT's GB/T 31467.3 enforcement.
- Air Cooling:Forces ambient air across finned heat exchangers or battery pack surfaces, suited to low-C-rate applications with relaxed thermal budgets. Cost-sensitive electric two-wheeler producers in Vietnam and Indonesia favor this modality where PCM substitution threatens active system penetration.
- Phase Change Materials:Paraffin or salt hydrate compounds absorb latent heat at constant temperature during thermal spikes. Korean battery plants specify PCM layers as backup protection in hybrid architectures.
- Thermoelectric Cooling:Peltier modules provide precise spot cooling for battery management system electronics and localized hot zones. Japanese solid-state battery pilots integrate thermoelectric elements for cell-level temperature uniformity.
The dominant share belongs to Liquid Cooling, while Phase Change Materials is closing the gap fastest as hybrid architectures proliferate.
Technology:
Adoption velocity tracks ambient temperature exposure and fleet duty cycle intensity across tropical Southeast Asia and temperate East Asian climates.
- Active Systems:Powered refrigeration loops, pumps, and compressors maintain cell temperatures below ambient thresholds. Indian electric bus fleets in Delhi and Mumbai are scaling active liquid cooling procurement through multi-year service contracts.
- Passive Systems:Conductive heat spreaders and natural convection eliminate parasitic power draw. Indonesian and Vietnamese two-wheeler assemblers specify passive cooling to hit sub-$1,000 retail price points.
- Hybrid Systems:Combine passive base cooling with active peak-load supplementation. Thai state transport utilities favor hybrid architectures for electric bus deployments balancing capital constraints against warranty requirements.
- Smart Controls:Model-predictive algorithms adjust cooling intensity based on charge rate, ambient conditions, and cell aging telemetry. Australian fleet operators unbundle smart thermal monitoring into standalone predictive maintenance contracts.
Active Systems retains the largest installed base, though Hybrid Systems is expanding most quickly in cost-constrained commercial vehicle segments.
Vehicle Type:
Specification complexity escalates with vehicle mass, battery capacity, and thermal runaway consequence severity.
- Passenger Vehicles:Premium platforms in China and Korea adopt immersion cooling for 4C+ fast-charging capability. Passenger car OEMs specify submerged cell architectures that eliminate traditional channel-based heat exchangers entirely.
- Commercial Vehicles:Light trucks and delivery vans in India face pending BIS thermal propagation protocols under AIS 156 amendments. Commercial vehicle OEMs are accelerating local supplier partnerships to meet parallel qualification tracks.
- Electric Buses:High-capacity NCM and LFP packs require continuous active cooling during rapid charge cycles. Thai and Vietnamese state utilities are pioneering outcome-based thermal management service contracts with guaranteed cell temperature performance.
- Two-Wheelers:Sub-5kWh packs in India face imminent thermal propagation testing requirements. AIS 156 amendment drafts create first-mover advantage for qualified active cooling suppliers in this underpenetrated segment.
Passenger Vehicles channels the highest absolute revenue, while Electric Buses demonstrates the steepest expansion trajectory driven by fleet electrification mandates.
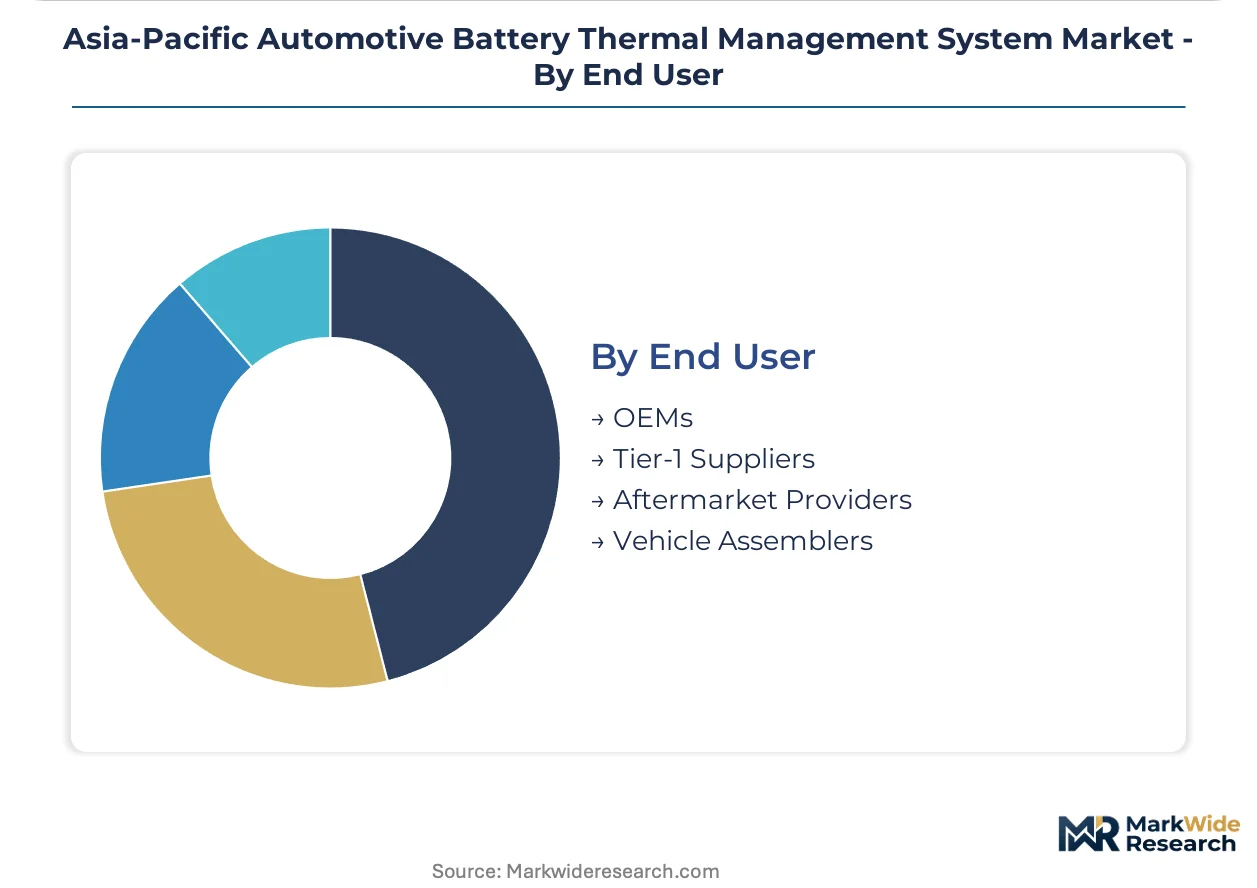
End User:
Procurement authority is fragmenting as fleet operators unbundle thermal monitoring from vehicle purchase and battery plants bring cooling loop specification in-house.
- OEMs:Vehicle manufacturers retain design authority for integrated thermal architectures. Chinese OEMs enforce GB standard compliance through direct supplier qualification of pump and valve subcomponent vendors.
- Tier-1 Suppliers:System integrators assemble cooling modules from purchased subcomponents. Tier-one suppliers face compressed prototype build capacity as MIIT accelerates certification cycles from eighteen to twelve months.
- Aftermarket Providers:Service networks maintain and retrofit thermal management hardware. Southeast Asian aftermarket channels lack R-1234yf handling certification, complicating expansion for Korean-spec cooling loops.
- Vehicle Assemblers:Contract manufacturers without full OEM status source pre-integrated battery and thermal packages. Indian electric bus assemblers rely on imported active cooling modules from Chinese tier-one suppliers.
OEMs dominate specification authority, though Aftermarket Providers is gaining share fastest as predictive maintenance platforms capture recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement departments and battery plant engineering teams drive specification authority across the Asia-Pacific region, with regulatory enforcement timelines compressing supplier qualification cycles in manufacturing-intensive corridors.
China
MIIT's GB/T 31467.3 battery abuse testing mandates coolant isolation and fire suppression integration in battery enclosures, disqualifying legacy passive cooling architectures from new vehicle platforms. Manufacturing gravity concentrates in Jiangsu and Guangdong provinces, where pump and valve subcomponent clusters create single-point vulnerability for tier-two thermal system integrators facing accelerated eighteen-to-twelve-month certification cycles.
India
State transport utilities in Delhi and Mumbai are issuing multi-year thermal management service contracts for liquid-cooled NCM and LFP packs in electric bus fleets. BIS is drafting thermal propagation test protocols aligned with AIS 156 amendments for electric two-wheelers and light commercial vehicles. Tamil Nadu and Maharashtra manufacturing corridors are accelerating local supplier partnerships to meet parallel qualification tracks for pending regulatory enforcement.
Japan
METI subsidizes solid-state battery development with companion thermal management qualification requirements, opening specification windows for next-generation heat spreader materials. Premium passenger car platforms adopt thermoelectric cooling elements for cell-level temperature uniformity in solid-state pilots. Kanto and Kansai industrial belts concentrate thermal simulation talent and CFD modeling expertise for cell-level thermal runaway prediction.
South Korea
Korean battery plants specify R-1234yf-based cooling circuits for high-C-rate fast-charging stations, pulling component demand toward active refrigeration architectures. Refrigerant-based cooling loop specialists anchor supply relationships with domestic cell manufacturers expanding capacity for export markets. Busan-Ulsan and Seoul Capital Area clusters dominate high-performance thermal system integration for premium EV platforms targeting 4C+ charging capability.
Thailand
State transport utilities face budget constraints but require extended pack lifecycle warranties, pioneering outcome-based thermal management service contracts with guaranteed cell temperature performance. Hybrid active-passive architectures dominate electric bus deployments balancing capital constraints against warranty requirements. Eastern Economic Corridor manufacturing zones are attracting tier-one thermal system integrators seeking proximity to ASEAN fleet electrification mandates.
Asia-Pacific Automotive Battery Thermal Management System Market Competitive Landscape
Player mix skews toward diversified automotive component conglomerates with compressor integration depth and refrigerant loop specialization. Market structure exhibits moderate consolidation around incumbent thermal engineering specialists with established OEM program relationships. Three strategic archetypes dominate competitive positioning: integrated compressor-chiller manufacturers, smart valve architecture providers, and refrigerant-based cooling loop specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers race to meet compressed GB certification timelines.
Within the diversified conglomerate tier, Denso Corporation and Robert Bosch occupy anchor positions across Japanese and European OEM programs respectively. Hanon Systems exemplifies the refrigerant specialization archetype serving Korean battery plant specifications. These three entities represent distinct competitive vectors—compressor integration depth, smart valve architecture, and refrigerant loop engineering—that define the current supply base structure.
| Leading Market Players |
|---|
| Denso Corporation |
| Continental AG |
| Robert Bosch |
| Hanon Systems |
| Valeo SA |
| Mahle GmbH |
| LG Chem |
| Samsung SDI |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
Multi-year thermal management service contracts with state transport utilities in Thailand and Vietnam lock in both supply access and price visibility for active liquid cooling modules, insulating tier-one integrators from spot-market dielectric fluid volatility while compressing margin flexibility for tier-two assemblers.
Pricing Analysis
Cost-plus contracts indexed to fluorochemical feedstock benchmarks dominate procurement between Korean battery plants and refrigerant loop specialists. Pricing stratifies across GB/T 31467.3-certified premium assemblies, standard active cooling modules, and economy passive architectures for two-wheelers. Cost compression in the economy tier intensifies as Indonesian assemblers substitute phase change materials for liquid cooling. State transport utilities exhibit lowest price sensitivity given warranty requirements, while Vietnamese two-wheeler OEMs face acute margin pressure.
Supply Chain Analysis
Inventory buffers for dielectric fluids and R-1234yf refrigerant have compressed to six-to-eight week cycles across Jiangsu and Guangdong manufacturing corridors. Pump and valve subcomponent production concentrates in eastern China, South Korea, and Japan, drawing from fluorochemical feedstocks and precision-machined aluminum castings. Single-source vulnerability in Jiangsu pump clusters creates exposure to MIIT certification timeline disruptions. Distribution runs through OEM-direct channels for passenger vehicles and tier-one integrators for commercial fleet retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cooling modalities and regulatory certification tiers creates niche entry points as electric bus fleets unbundle thermal monitoring from vehicle purchase and solid-state battery pilots demand next-generation heat spreader materials.
For Market Incumbents: Secure backward integration into dielectric fluid formulation to defend margin against fluorochemical price volatility. Anchor compressor-chiller manufacturing capacity in Busan-Ulsan clusters to capture Korean battery plant expansion. Accelerate GB/T 31467.3 parallel validation tracks before MIIT compresses certification cycles further. For New Entrants and Emerging Players: BIS thermal propagation fast-tracks for electric two-wheelers under AIS 156 amendments offer qualification arbitrage against established Chinese suppliers. Target Indian sub-5kWh active cooling segments where incumbent penetration remains shallow. Lead with predictive maintenance software bundled into hardware contracts to differentiate from commodity module providers. For Investors and Strategic Acquirers: Capital is best deployed toward refrigerant-based cooling loop specialists with established Korean cell manufacturer relationships and CFD modeling capabilities for solid-state thermal qualification. Long-term viability hinges on positioning for next-generation immersion cooling architectures displacing channel-based heat exchangers. Watch for METI solid-state subsidy disbursement acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T 31467.3 Certification Fast-Track | MIIT enforcement disqualifies legacy passive architectures from new vehicle platforms. |
| Dielectric Fluid Backward Integration | In-house formulation secures margin against fluorochemical feedstock volatility. |
| Immersive Cooling Pilot Investment | Premium Chinese and Korean OEMs adopt submerged cell architectures for 4C+ charging. |
| Outcome-Based Service Contract Launch | Thai state utilities pioneer guaranteed cell temperature performance warranties. |
| Solid-State Heat Spreader R&D Partnership | METI subsidies open specification windows for next-generation thermal materials. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-one thermal system procurement leads, battery plant engineering directors, and fleet maintenance managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against MIIT regulatory filings, BIS draft standards, customs trade data for pump and valve subcomponents, and vehicle production databases. Bottom-up module shipment estimates triangulated against top-down battery capacity deployment projections.
Sensitivity analysis tested forecast robustness across dielectric fluid price scenarios, GB certification timeline compression rates, and electric bus fleet electrification trajectories over the projection horizon. Segmentation dimensions modeled include cooling modality, technology tier, vehicle class, and regional regulatory cluster. CAGRs derived from installed base evolution and replacement cycle analysis, with inputs from cell chemistry adoption curves and fast-charging infrastructure buildout.
Decision-makers should treat outputs as directional under base assumptions of sustained MIIT enforcement and AIS 156 finalization; material deviation in subsidy disbursement or refrigerant phase-out schedules would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
US Energy Storage Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
Power Battery Management System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Battery Management System (BMS) Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
United States Rechargeable Battery Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
Battery Energy Management System Market
Battery Management System
EV Battery Management Market