
 Solid Electrolyte for Lithium Ion Battery Market | 2026-2036
Solid Electrolyte for Lithium Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Electrolyte for Lithium Ion Battery Market Insights
A shortage of electrochemists with solid-state battery experience is reorganizing how manufacturers staff pilot production lines. Solid Power leverages its sulfide electrolyte expertise to anchor partnerships with North American automotive OEMs. CATL sustains manufacturing scale advantages through in-house ceramic electrolyte processing. QuantumScape specializes in lithium-metal anode integration with garnet-type separators, competing on energy density benchmarks rather than cost alone.
Solid electrolyte for lithium ion battery denotes an ion-conductive ceramic, glass, or polymer medium that replaces flammable liquid electrolytes, typically achieving lithium-ion conductivity above 10⁻³ S/cm at room temperature while eliminating thermal runaway risks in high-voltage cells. The primary purpose is enabling next-generation lithium-metal anodes and safer high-energy cells for transportation and stationary storage. Sulfide materials dominate current pilot production due to superior ionic conductivity, though garnet structures occupy premium applications requiring oxidative stability against high-voltage cathodes. Polymer electrolytes lead in thin-film consumer electronics where processing simplicity outweighs absolute performance. Bulk form factors capture the largest addressable volume as automotive OEMs target cell-level cost parity with conventional lithium-ion packs.
FDA guidelines for medical device batteries, EPA hazardous substance rules, and China's GB/T standards for power battery safety collectively shape product certification pathways and market access timelines. The EU Battery Regulation and REACH compliance requirements are forcing electrolyte suppliers to document material provenance and recyclability before European automotive OEMs qualify new cell designs. Stakeholders must monitor which electrolyte chemistry achieves automotive qualification first, as this will lock in supply chain relationships and patent licensing structures for the subsequent decade.
Market Dynamics
The transition from liquid to solid electrolyte architectures is compressing qualification timelines as automotive OEMs demand cell-level validation data before committing to platform integration. This pressure is reorganizing R&D spending toward pilot-scale manufacturing rather than laboratory-scale materials discovery.
Growth Catalysts
- China's GB/T battery safety standards:Mandatory thermal runaway propagation tests are disqualifying conventional liquid-electrolyte designs from premium vehicle platforms, redirecting procurement toward ceramic and sulfide alternatives.
- German automotive cluster concentration:Stuttgart and Munich-based OEMs are co-locating solid-state engineering teams with electrolyte developers, accelerating feedback loops between materials specification and pack integration.
- Lithium-metal anode compatibility:Solid electrolytes enable anode architectures that liquid systems cannot accommodate, unlocking energy density thresholds required for extended-range electric vehicle segments.
Market Restraints
- Sulfide raw material concentration:Germanium and arsenic refining capacity clusters in East Asian supply chains, creating geographic single-point-of-failure exposure for sulfide electrolyte producers.
- Dry room capex intensity:Sulfide processing requires sub-ppm moisture environments, inflating facility construction costs versus conventional lithium-ion cell manufacturing.
- Interfacial impedance limitations:Ceramic-electrolyte-to-cathode contact resistance remains above target thresholds for high-power applications, restricting addressable market segments.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives are attracting sulfide electrolyte joint ventures targeting two-wheeler and three-wheeler electrification.
- Stationary storage convergence:Solid-state designs are penetrating grid-scale applications where cycle life and thermal stability outweigh upfront cost sensitivity.
- EU Battery Regulation material provenance:Documentation requirements for recyclability and carbon footprint are favoring European-based electrolyte producers in OEM qualification processes.
Industry Challenges
- Electrochemist talent scarcity:Solid-state battery expertise resides in fewer than two dozen academic laboratories globally, forcing manufacturers to recruit from semiconductor and fuel cell adjacent fields.
- Automotive qualification timeline compression:OEMs demand 15-year service life validation in 24-month windows, straining accelerated testing protocols for emerging electrolyte chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Electrolyte for Lithium Ion Battery Market |
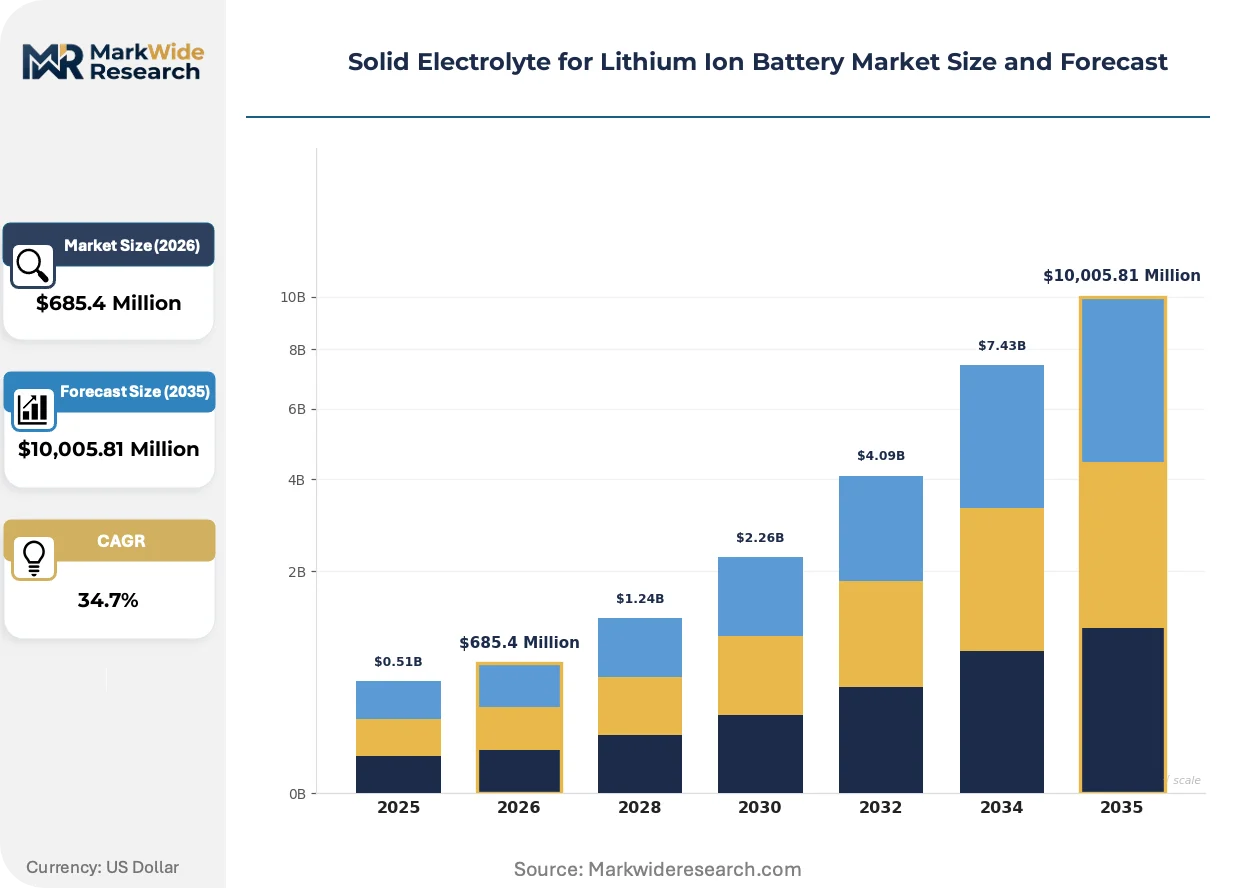
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $10,005.81 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: NASICON, Garnet, Sulfide, Polymer Application: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Grid Storage Form Factor: Thin Film, Bulk, Composite, Nanocomposite End User: Automotive OEMs, Electronics Manufacturers, Energy Providers, Research Institutions |
| Companies Covered | LG Energy Solution, BYD, CATL, ProLogium Technology, NIO, Solid Power, Samsung SDI, WeLion, QuantumScape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Electrolyte for Lithium Ion Battery Market Trends and Innovations
Materials processing innovations are collapsing the cost gap between laboratory-grade and production-grade solid electrolytes. Three converging developments are restructuring competitive positioning in cell manufacturing.
Sulfide electrolyte synthesis is decomposing legacy wet-chemical processing into mechanochemical and vapor-phase routes that eliminate solvent recovery costs. Korean materials suppliers are scaling these methods for automotive qualification batches. The shift is compressing capital requirements for entry-level production capacity by eliminating solvent handling infrastructure.
REACH registration requirements for novel sulfide compositions are forcing electrolyte developers to submit toxicity dossiers before European automotive procurement teams can qualify new suppliers. The regulation is delaying market entry for Asian producers lacking EU-based registration expertise. Battery cell manufacturers are responding by pre-qualifying European-registered electrolyte sources during platform development phases.
Automotive OEMs are consolidating supplier relationships around electrolyte-cathode-anode system integrators rather than discrete materials vendors. Tier-one battery manufacturers are absorbing electrolyte development responsibilities previously held by materials specialists. Germany and Japan exhibit the most pronounced consolidation, with OEMs reducing qualified supplier lists from twelve to three per platform generation.
Solid Electrolyte for Lithium Ion Battery Market Segmentation
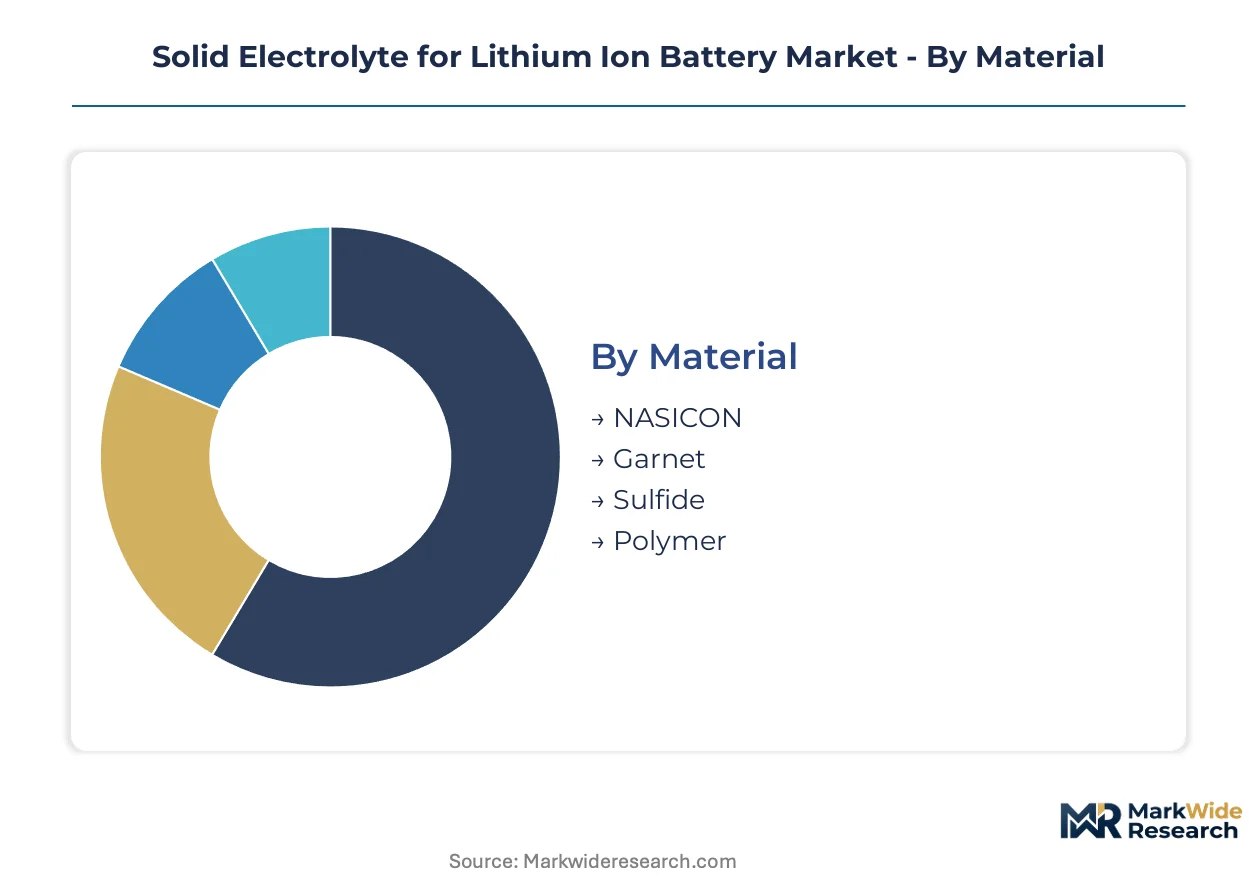
Solid electrolyte procurement channels diverge sharply by material chemistry and end-use performance requirements. Automotive qualification pathways favor bulk sulfide and garnet architectures, while electronics manufacturers source thin-film polymer through specialized coating suppliers.
Material:
Sulfide electrolytes flow through dedicated chemical processing channels requiring moisture-controlled logistics, while polymer materials distribute through conventional film extrusion networks.
- Sulfide:Lithium thiophosphate compositions achieve ionic conductivity exceeding liquid electrolyte benchmarks at room temperature. Pilot production lines in Germany and South Korea are scaling mechanochemical synthesis for automotive cell qualification. Korean materials suppliers dominate current sulfide precursor refining capacity.
- Garnet:Lithium lanthanum zirconium oxide structures withstand oxidative degradation against high-voltage cathode chemistries. European OEMs concentrate procurement around Stuttgart-based developers for premium extended-range vehicle platforms. Solid Power and QuantumScape anchor garnet supply relationships with North American automotive partners.
- NASICON:Sodium superionic conductor frameworks offer cost advantages through earth-abundant precursor availability.
- Polymer:Polyethylene oxide and polyvinylidene fluoride matrices enable ambient-temperature processing for wearable device batteries.
Sulfide dominates installed base. Garnet is where expansion concentrates.
Application:
Cost tier separation distinguishes automotive cell procurement from consumer electronics sourcing, with grid storage occupying a mid-tier validation pathway.
- Electric Vehicles:Solid-state cell designs target 800-kilometer range thresholds through lithium-metal anode integration. German automotive clusters around Stuttgart and Munich co-locate engineering teams with electrolyte developers to compress qualification timelines. CATL and Solid Power anchor sulfide supply agreements with North American and European OEMs.
- Grid Storage:Stationary applications prioritize cycle life and thermal stability over energy density metrics. Chinese state grid operators are piloting ceramic electrolyte systems for megawatt-hour installations under GB/T safety standards. Cycle life targets exceed 15,000 cycles for grid-scale deployment.
- Consumer Electronics:Thin-film polymer electrolytes enable flexible form factors for wearable devices.
- Renewable Energy Storage:Solid-state architectures address intermittency buffering for solar and wind generation assets.
Electric vehicles command premium pricing tiers. Grid storage is climbing the fastest.
Form Factor:
Volume concentration separates automotive bulk procurement from electronics thin-film sourcing, with composite architectures emerging for hybrid performance requirements.
- Bulk:Pressed ceramic and sintered sulfide pellets target cylindrical and prismatic cell geometries for automotive packs. Stuttgart-based OEMs specify bulk garnet dimensions exceeding 100-micron thickness for mechanical robustness during cell assembly. Dry room processing requirements inflate capital intensity for bulk sulfide manufacturing.
- Thin Film:Sub-50-micron polymer and ceramic layers enable microbattery architectures for medical implants and smart cards. Japanese electronics manufacturers source vapor-deposited lithium phosphorus oxynitride through specialized coating equipment suppliers. Processing simplicity outweighs absolute ionic conductivity in this segment.
- Composite:Ceramic-polymer hybrid structures balance mechanical flexibility with ionic transport performance.
- Nanocomposite:Dispersed ceramic fillers within polymer matrices target intermediate conductivity and processing temperature regimes.
Bulk dominates installed base. Thin film is where expansion concentrates.
End User:
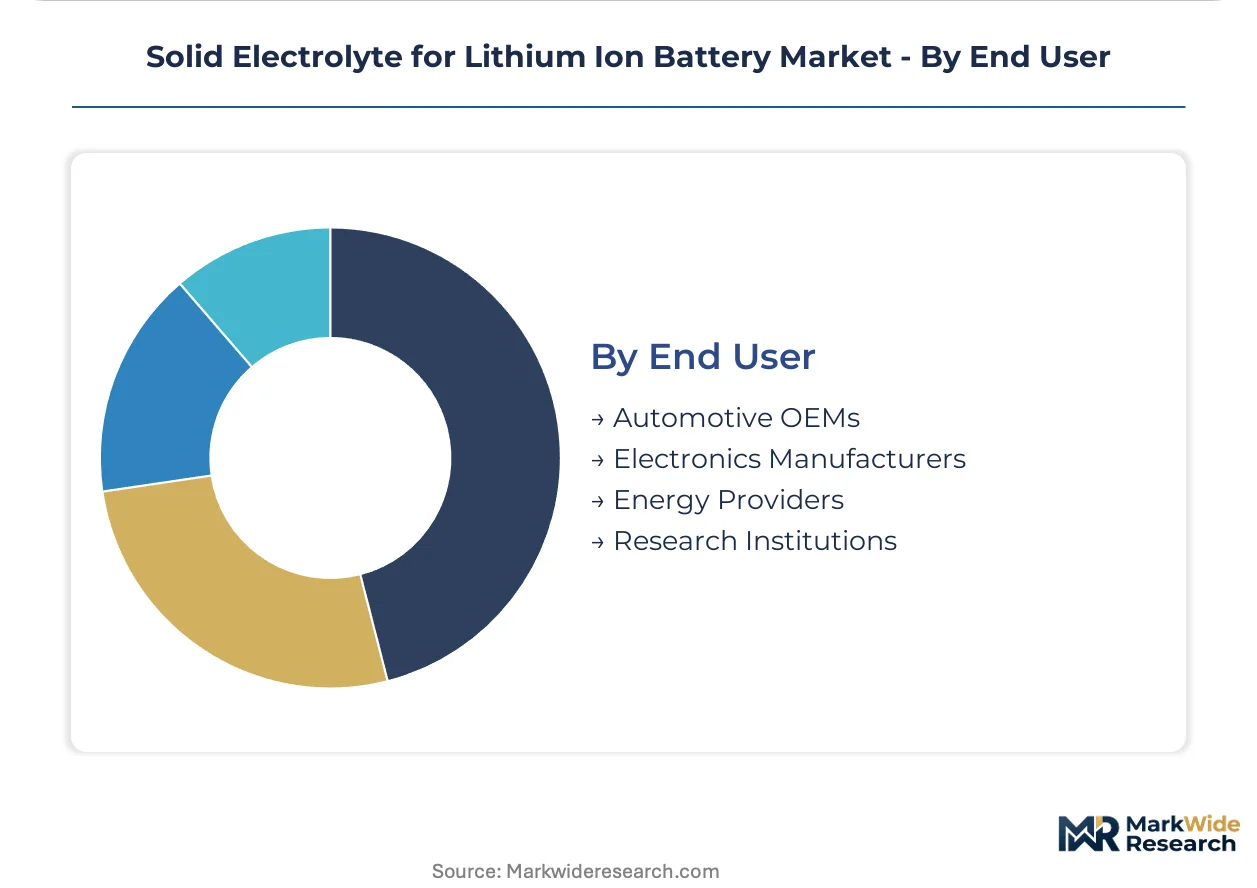
Customer type determines specification stringency, with automotive OEMs imposing 15-year service life validation that research institutions bypass entirely.
- Automotive OEMs:Cell-level qualification protocols demand thermal runaway propagation resistance under GB/T and UN 38.3 test regimes. BMW, Volkswagen, and Ford have reduced qualified electrolyte supplier lists from twelve to three per platform generation. OEMs are absorbing electrolyte development responsibilities previously held by discrete materials vendors.
- Energy Providers:State grid operators and independent power producers evaluate solid-state systems for frequency regulation and peak shaving applications. China's State Grid Corporation is piloting sulfide electrolyte installations under dual carbon policy mandates. Cycle economics favor 20-year asset lifetimes over upfront capital minimization.
- Electronics Manufacturers:Consumer device OEMs prioritize manufacturing throughput and form factor flexibility.
- Research Institutions:Academic and national laboratory programs advance novel electrolyte compositions without production scale constraints.
Automotive OEMs dominate installed base. Energy providers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for battery safety anchor the dominant geography, with MIIT regulations and dual carbon goals accelerating solid-state adoption across automotive platforms.
China
CATL and BYD dominate sulfide electrolyte pilot production for electric vehicle integration. GB/T battery safety standards mandate thermal runaway propagation resistance, disqualifying liquid-electrolyte designs from premium platforms. The Yangtze River Delta hosts concentrated cell manufacturing around Ningde and Shenzhen engineering centers.
Germany
BMW and Volkswagen procurement teams co-locate solid-state engineering with electrolyte developers in Stuttgart and Munich. KBA vehicle certification requirements impose 15-year service life validation on new cell architectures. Baden-Württemberg's automotive cluster compresses feedback loops between materials specification and pack integration.
United States
Solid Power and QuantumScape anchor garnet-type electrolyte development for North American OEM partnerships. NHTSA safety guidelines and IRA domestic content provisions shape qualification timelines. The Mountain West region hosts dry room processing facilities for sulfide manufacturing scale-up.
South Korea
LG Energy Solution and Samsung SDI leverage mechanochemical synthesis routes for automotive qualification batches. MFDS chemical registration requirements and METI-aligned technical standards govern export protocols. The Seoul Capital Area concentrates precursor refining capacity for lithium thiophosphate compositions.
Japan
ProLogium Technology and Toyota-affiliated developers target thin-film polymer architectures for consumer electronics integration. JIS standards and METI technology roadmaps coordinate R&D subsidies with commercialization timelines. The Kansai region maintains specialized coating equipment suppliers for vapor-deposited electrolyte layers.
Solid Electrolyte for Lithium Ion Battery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in solid electrolyte supply. CATL and LG Energy Solution occupy the integrated tier with captive cell manufacturing, while sulfide and garnet specialists concentrate on materials purity and processing IP. Three archetypes dominate: automotive-qualified system integrators, materials-focused chemical processors, and thin-film coating specialists. Competitive moves center on dry room capacity expansion and cathode-electrolyte-anode system partnerships that lock in OEM platform decisions.
Within the automotive-qualified tier, Solid Power and QuantumScape exemplify North American positioning around garnet-type separators and lithium-metal anode integration. CATL represents the integrated Asian model with in-house ceramic electrolyte processing at manufacturing scale. These three anchors illustrate how geographic concentration—Colorado, California, and Fujian Province—maps to distinct technical specializations in the qualification race.
| Leading Market Players |
|---|
| LG Energy Solution |
| BYD |
| CATL |
| ProLogium Technology |
| NIO |
| Solid Power |
| Samsung SDI |
| WeLion |
| QuantumScape |
| Others |
Pricing and Supply Chain Analysis
China's GB/T battery safety standards gate both supplier qualification and price differentiation simultaneously, as automotive OEMs will not qualify electrolyte sources lacking thermal runaway propagation certification regardless of cost position. This regulatory filter compresses the qualified supplier base and enables certified producers to command premium positioning over uncertified competitors.
Pricing Analysis
Long-term offtake contracts dominate automotive procurement, with spot markets confined to pilot-scale batch transactions and research quantities. Three-tier pricing structure across automotive-qualified, industrial-grade, and research-grade certification levels separates contract values. Cost compression in sulfide electrolyte tiers is intensifying because Korean mechanochemical synthesis routes are eliminating solvent recovery overhead. Grid storage operators exhibit highest price sensitivity, while premium EV platforms prioritize energy density benchmarks over unit economics.
Supply Chain Analysis
Port congestion on Busan-to-Hamburg trade lanes inflates inbound logistics costs for Germanium and arsenic precursors refined in East Asian facilities. Supply concentrates in China, South Korea, and Japan for lithium thiophosphate and garnet precursor processing. The chain draws from concentrated Germanium refining capacity, lithium carbonate from South American salares, and rare earth lanthanum streams. Single-source vulnerability runs through Korean precursor suppliers dominating automotive qualification batches. Distribution runs through moisture-controlled dedicated chemical logistics networks rather than conventional battery material channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid electrolyte incumbents face substitution defense against silicon-anode liquid cell architectures that are achieving comparable energy density at lower capital intensity. The threat demands strategic repositioning around safety certification moats and lithium-metal anode integration capabilities that liquid systems cannot replicate.
For Market Incumbents: Shield automotive platform relationships by locking in cathode-electrolyte-anode system partnerships before OEM supplier consolidation completes. Prioritize dry room capacity expansion in Stuttgart-adjacent locations to compress feedback loops with German automotive qualification teams. Backward integration into Germanium precursor refining mitigates East Asian supply concentration exposure.
For New Entrants and Emerging Players: After-sales technical service for solid-state cell integration represents a service-layer gap where incumbents under-serve mid-tier automotive programs. Target India's PLI scheme jurisdictions for sulfide electrolyte joint ventures serving two-wheeler electrification demand. Pursue white-label manufacturing partnerships with European-registered materials suppliers to bypass REACH registration delays.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dry room processing infrastructure as sub-ppm moisture requirements become standard. Long-term viability centers on electrolyte-cathode-anode system integrators rather than discrete materials specialists. Watch for automotive OEM qualification timeline compression as the inflection signal indicating which chemistry achieves platform lock-in.
| Strategic Initiative | Industry Significance |
|---|---|
| Dry Room Capacity Expansion | Sub-ppm moisture processing enables sulfide electrolyte qualification under GB/T standards. |
| Cathode-Electrolyte-Anode System Partnership | Integrated cell architectures lock in OEM platform decisions before supplier consolidation finalizes. |
| Mechanochemical Synthesis Scale-Up | Solvent-free processing routes compress capital requirements for entry-level production capacity. |
| REACH Registration Completion | European toxicity dossiers unblock procurement pathways for Stuttgart and Munich-based OEMs. |
| Lithium-Metal Anode Integration | Garnet-type separators enable energy density thresholds required for extended-range EV segments. |
Research Methodology
Cross-validation between primary fieldwork with solid-state battery manufacturers and secondary trade data anchors the qualitative findings. The study combines interviews with electrochemist R&D directors, automotive OEM platform engineers, dry room facility operators, and chemical precursor procurement leads with validation against customs records, MIIT production disclosures, and KBA vehicle certification databases. Bottom-up cell production estimates and top-down automotive demand projections provide triangulation checks.
Sensitivity analysis around lithium-metal anode adoption rates and dry room capex inflation informs the analytical framework across the projection horizon. Segmentation dimensions include material chemistry tier, form factor specification, end-use application, and regional regulatory cluster. CAGRs derive from installed base growth curves adjusted for automotive qualification timeline compression. Forecast inputs incorporate GB/T safety standard enforcement schedules and EU Battery Regulation material provenance documentation requirements.
Underlying assumptions cover sustained automotive OEM commitment to solid-state platform development, with deviation risk concentrated in silicon-anode liquid cell performance breakthroughs. Forecasts reflect these conditions with acknowledgment that chemistry-agnostic battery strategies at major OEMs could revise demand trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Manganese Oxide Battery Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Thin Film Battery Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Solid-State Battery Market