
 Europe Electric Vehicle Battery Management System Market | 2026-2036
Europe Electric Vehicle Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Battery Management System Market Foresight
Commercial fleet electrification is repositioning BMS procurement priorities across Europe. Robert Bosch GmbH leverages its integrated powertrain division to anchor German OEM supply chains. Continental AG sustains R&D intensity in wireless cell-monitoring architectures. Infineon Technologies AG dominates silicon-carbide gate driver integration for high-voltage battery packs.
An electric vehicle battery management system is an electronic controller that monitors cell voltage, temperature, and state-of-charge across lithium-ion arrays to prevent thermal runaway and optimize cycle life. Modular architectures are capturing share as OEMs demand scalable pack designs across vehicle classes. OEM direct sourcing is concentrating procurement power and compressing margins for Tier-1 intermediaries. Distributed BMS topologies are gaining traction in premium platforms requiring granular cell-level diagnostics.
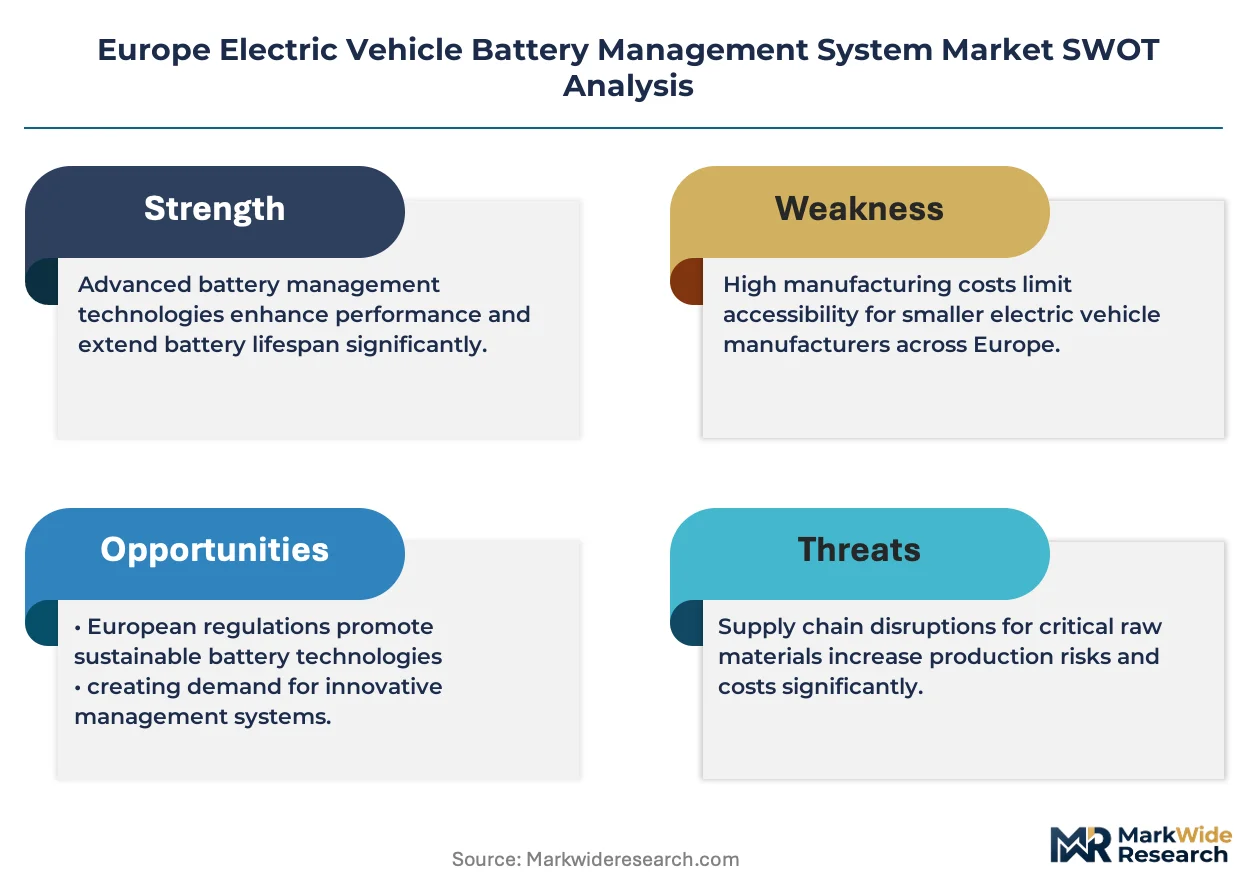
The EU Battery Regulation mandates passport traceability and recycled content thresholds that reshape BMS data architecture requirements. ECE R100 and EMA safety frameworks enforce cell-level fault detection standards that filter non-compliant suppliers from European tenders. Stakeholders must monitor delegated act timelines for carbon intensity disclosure rules that will determine qualified supplier status.
Market Dynamics
The EU Battery Regulation and ECE R100 safety protocols are compressing supplier qualification timelines while OEM platform consolidation concentrates procurement power among German, French, and Dutch vehicle manufacturers.
Growth Catalysts
- EU Battery Regulation passport mandates:Traceability requirements are forcing BMS architecture upgrades across European cell factories, creating replacement demand for legacy monitoring systems.
- Commercial fleet electrification:Logistics operators in the Netherlands and Germany are specifying intelligent thermal-runaway detection as standard equipment in heavy-duty procurement tenders.
- Silicon-carbide gate driver integration:High-voltage pack designs above 800V are accelerating adoption of advanced semiconductor architectures for faster switching and reduced heat dissipation.
Market Restraints
- Cell-level monitoring accuracy thresholds:ECE R100 fault detection standards are disqualifying suppliers lacking ASIL-D certification, reducing qualified vendor pools.
- Lithium supply concentration:European BMS manufacturers remain dependent on processed cathode materials from concentrated Asian refining corridors, exposing margin volatility.
- Wireless cell-monitoring technical limitations:Electromagnetic interference in dense pack configurations constrains signal reliability below the granularity premium platforms demand.
Strategic Opportunities
- Poland and Hungary battery plant corridors:Greenfield cell factories in these markets lack established BMS supplier relationships, creating first-mover positioning windows.
- Second-life stationary storage applications:Retired automotive packs require repurposed management systems, opening aftermarket revenue streams for diagnostic software providers.
- CSRD carbon intensity disclosure rules:Delegated acts under the Corporate Sustainability Reporting Directive will advantage suppliers with embedded lifecycle tracking capabilities.
Industry Challenges
- Functional safety engineering talent scarcity:ASIL-D certified firmware developers command premium compensation, constraining R&D scaling for mid-tier suppliers.
- Pack-platform integration complexity:OEM direct sourcing models compress Tier-1 margins while requiring simultaneous engineering support across multiple vehicle programs.
- Recycled content verification timelines:EU Battery Regulation thresholds for recovered lithium and cobalt lack harmonized testing protocols, delaying product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Battery Management System Market |
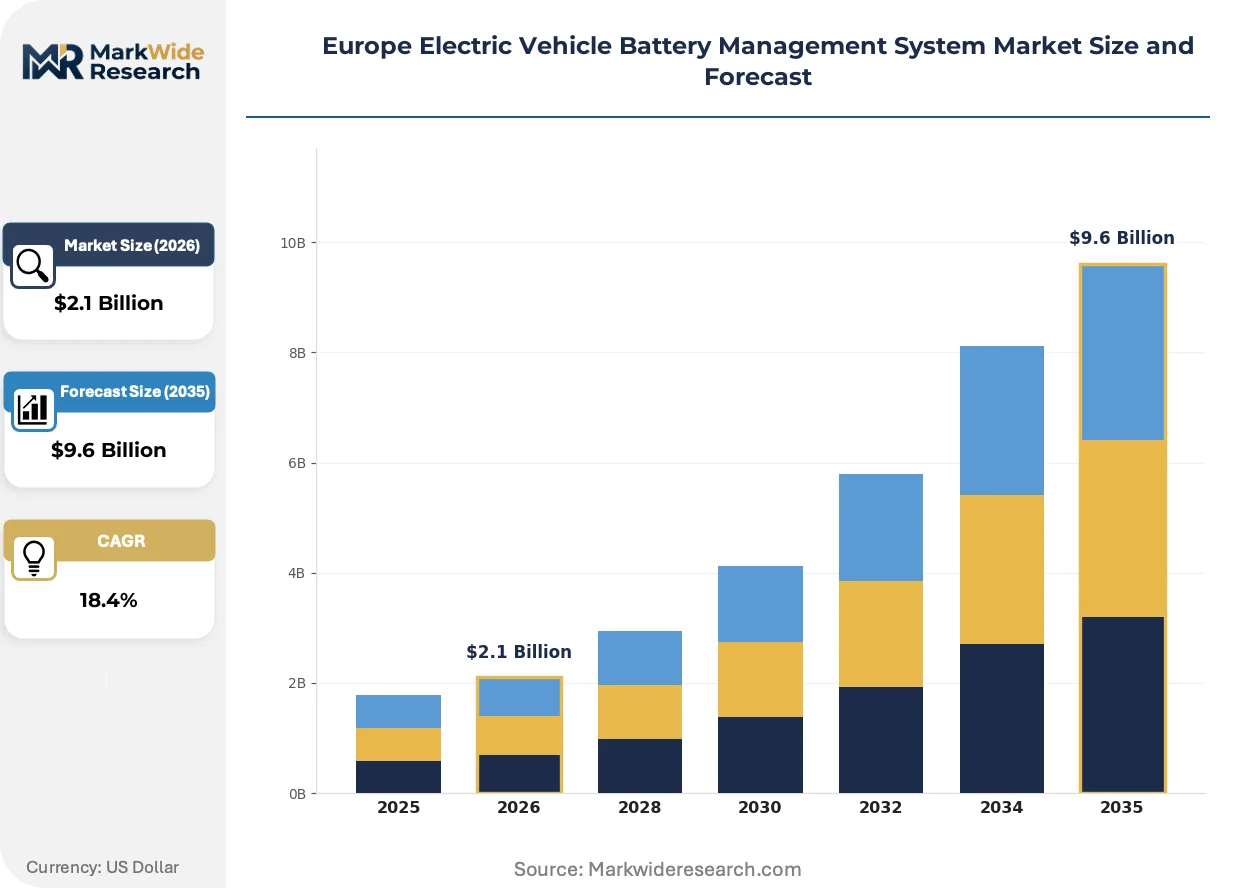
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.6 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized, Modular, Distributed, On-board Technology: Li-ion, Li-polymer, Nickel-Metal Hydride, Supercapacitors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Installation: Integrated, Retrofitted, Pre-installed, Custom-built |
| Companies Covered | Robert Bosch GmbH, Continental AG, Infineon Technologies AG, Analog Devices, Inc., LG Energy Solution, NXP Semiconductors, Denso Corporation, Panasonic Holdings Corporation, Eberspächer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Battery Management System Market Shifts & Advancements
Intelligent diagnostics and wireless architectures are displacing conventional wired monitoring topologies across European premium platforms, while regulatory disclosure mandates reshape data infrastructure investments.
Distributed BMS topologies with cell-level microcontrollers are expanding into premium passenger EV architectures. German and French OEMs are mandating granular temperature and voltage telemetry for thermal-runaway prediction. This granularity is expanding into warranty risk models and insurance underwriting frameworks, compressing acceptance of centralized master-slave designs.
REACH substance restrictions and EU Battery Regulation delegated acts are tightening hazardous material documentation requirements. Industrial consequence includes mandatory supply chain disclosure systems that BMS firmware must support through embedded material passports. Pack manufacturers serving Swedish and Danish markets are responding with blockchain-anchored traceability modules.
Fleet operators are consolidating vendor relationships around full-lifecycle service agreements. Direct OEM procurement teams are displacing traditional Tier-1 intermediaries in contract negotiations for high-voltage platforms. This concentration is most visible in German commercial vehicle electrification programs, where logistics groups specify BMS performance guarantees spanning fifteen-year operational horizons.
Europe Electric Vehicle Battery Management System Market Segmentation
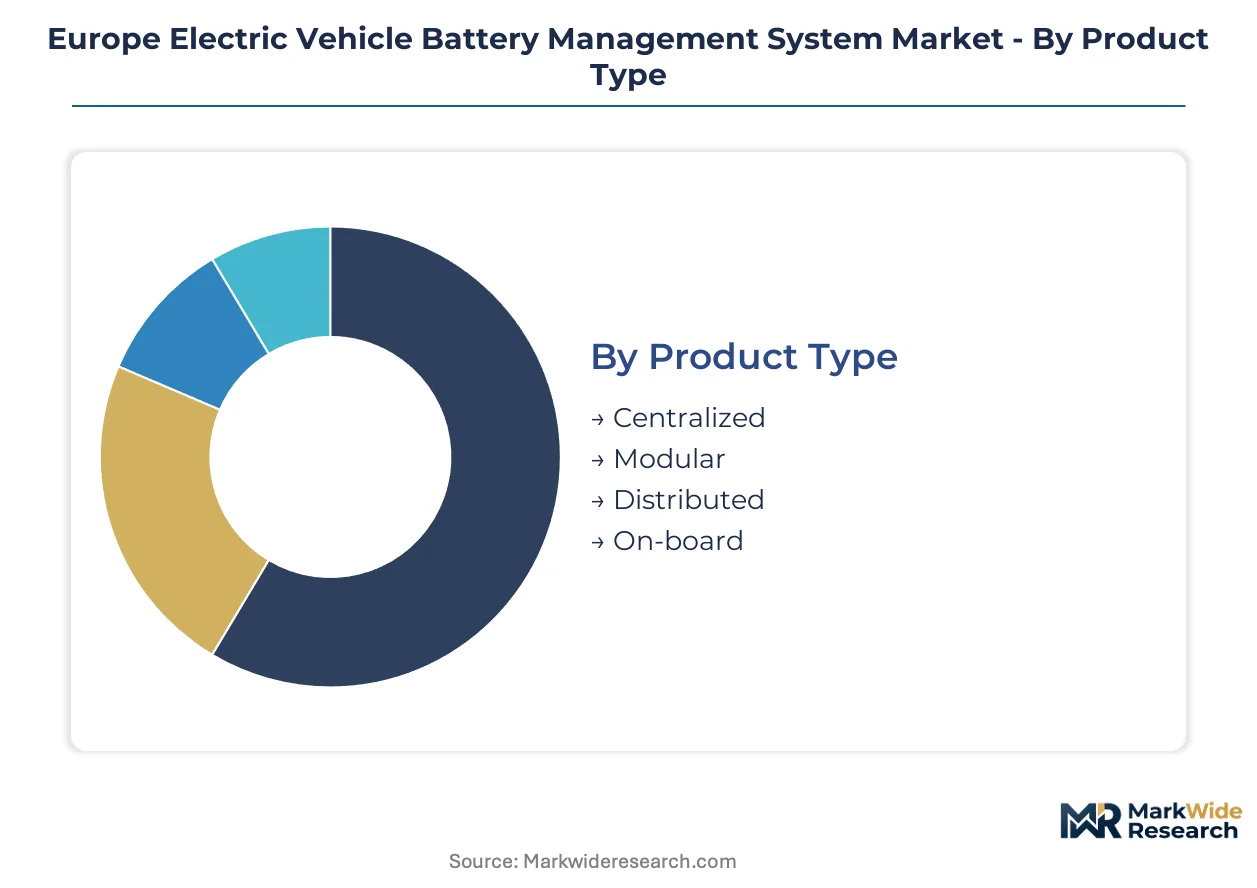
BMS architectures diverge sharply across European EV platforms based on voltage class and thermal management sophistication. Procurement patterns in Germany, France, and the Netherlands reveal distinct preferences for integration depth and supplier relationships that reshape segment boundaries.
Product Type:
Volume concentration favors centralized architectures for mass-market platforms, while premium positioning drives distributed topology premiums.
- Centralized:Single master controller aggregates cell data through wired harnesses to slave modules. German volume OEMs specify this architecture for compact and mid-size platforms where cost minimization outweighs diagnostic granularity.
- Modular:Master-slave configurations with swappable sub-assemblies enable pack scaling across vehicle classes without full redesign. French OEMs mandate modular BMS for multi-platform battery contracts spanning passenger and light commercial vehicles.
- Distributed:Cell-level microcontrollers with independent processing enable millisecond thermal-runaway detection. Dutch fleet operators specify distributed topologies for heavy-duty electric trucks operating at 800V and above.
- On-board:Compact units integrated directly into cell modules reduce wiring mass and assembly complexity. Hungarian battery plant corridors favor on-board BMS for automated pack assembly lines.
Today's leader: Centralized. Tomorrow's challenger: Distributed.
Technology:
Cathode chemistry selection determines BMS voltage sensing ranges and balancing algorithms across European cell factories.
- Li-ion:NMC and LFP variants dominate European passenger EV production. BMS firmware must accommodate distinct voltage plateaus and thermal profiles, with LFP systems requiring more precise state-of-charge estimation due to flat discharge curves.
- Li-polymer:Pouch cell formats in premium German platforms enable packaging flexibility but demand enhanced swelling detection through pressure-sensitive monitoring circuits.
- Nickel-Metal Hydride:Legacy hybrid architectures retain Ni-MH packs for cost-sensitive applications. Toyota and Stellantis mild-hybrid programs in France specify simplified BMS with reduced cell-count monitoring.
- Supercapacitors:Hybrid energy storage for regenerative braking buffers requires specialized charge-discharge rate management. Polish bus manufacturers integrate supercapacitor BMS for trolleybus and electric coach kinetic energy recovery.
Li-ion commands current procurement volumes. Li-polymer is climbing the fastest in premium platform specifications.
End User:
Direct OEM sourcing is compressing Tier-1 intermediary margins while fleet operators consolidate around lifecycle service agreements.
- OEMs:Volkswagen, BMW, and Renault conduct direct BMS procurement for proprietary pack designs. In-house firmware development teams specify ASIL-D certified architectures with embedded EU Battery Regulation passport capabilities.
- Tier-1 Suppliers:Bosch and Continental retain BMS integration roles where OEMs lack high-voltage electronics expertise. Margin pressure intensifies as OEMs internalize master controller design while outsourcing slave module production.
- Aftermarket Providers:Diagnostic tool vendors and refurbished pack specialists serve second-life stationary storage applications. CSRD disclosure requirements create demand for lifecycle tracking software retrofits.
- Fleet Operators:Dutch logistics groups and German municipal bus fleets specify BMS performance guarantees spanning fifteen-year operational horizons. Procurement tenders mandate predictive maintenance APIs and remote firmware update capabilities.
OEMs anchor present revenue concentration. Fleet operators represent the steepest expansion trajectory for service-anchored contracts.
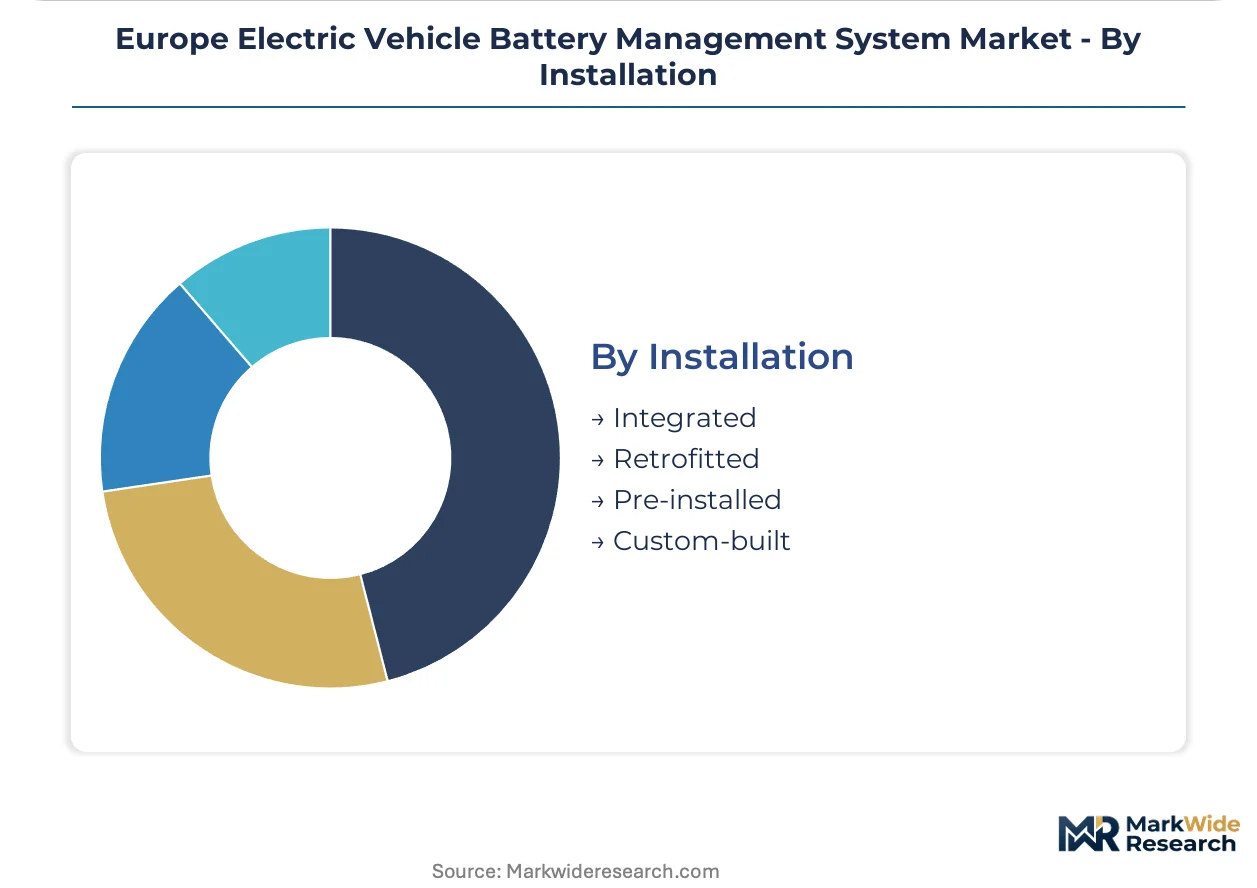
Installation:
Integration depth correlates with vehicle platform maturity and regulatory qualification timelines.
- Integrated:BMS hardware co-designed with pack mechanical structure dominates new European EV architectures. Cell-to-pack designs eliminate module housings and require BMS sensors embedded during cell stacking.
- Retrofitted:Legacy fleet conversions and range-extender installations drive aftermarket BMS demand. ECE R100 compliance certification limits viable suppliers for retrofitted high-voltage systems.
- Pre-installed:Battery-swapping networks in the Netherlands specify standardized BMS interfaces for automated pack exchange. NIO and Ample compatibility protocols influence BMS communication architecture choices.
- Custom-built:Low-volume specialty vehicle manufacturers commission bespoke BMS for unique pack geometries. Motorsport and construction equipment electrification programs in Italy and the UK require custom thermal management algorithms.
Integrated installations dominate greenfield programs. Pre-installed architectures are gaining share fastest in swapping infrastructure corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is redistributing BMS production across European manufacturing corridors as OEMs seek jurisdictions with streamlined regulatory pathways and qualified engineering talent pools.
Germany
Volkswagen Group and BMW anchor BMS procurement through proprietary pack designs requiring ASIL-D certified architectures. The KBA enforces ECE R100 compliance timelines that compress supplier qualification windows. Stuttgart and Munich engineering clusters concentrate firmware development for intelligent thermal-runaway detection systems.
France
Renault and Stellantis mandate modular BMS configurations spanning passenger and light commercial vehicle platforms. ANSM coordinates with EU Battery Regulation delegated acts on carbon intensity disclosure protocols. The Paris-Saclay and Lyon corridors host cell-to-pack assembly lines integrating on-board BMS for automated production.
Netherlands
Dutch logistics operators specify distributed BMS topologies for heavy-duty electric trucks operating at 800V and above. REACH substance restrictions drive hazardous material documentation through blockchain-anchored traceability modules. Eindhoven and Rotterdam battery-swapping infrastructure corridors demand standardized BMS interfaces for automated pack exchange.
Poland
Greenfield cell factories in Lower Silesia and Masovia lack established BMS supplier relationships, creating first-mover positioning windows for qualified vendors. The country's national industrial regulator aligns with EU Battery Regulation passport mandates for traceability architecture upgrades. Katowice and Warsaw manufacturing zones attract BMS module assembly investments serving German OEM supply chains.
Hungary
Automated pack assembly lines in Győr and Debrecen favor on-board BMS integration to reduce wiring mass and assembly complexity. The central bank's investment promotion frameworks support high-voltage electronics manufacturing. Samsung SDI and CATL cell factories drive localized demand for BMS hardware co-designed with pack mechanical structures.
Europe Electric Vehicle Battery Management System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM direct sourcing concentrating procurement power among integrated powertrain divisions and semiconductor specialists. The vendor base organizes around three strategic archetypes: diversified automotive suppliers with embedded electronics expertise, pure-play semiconductor designers focused on gate driver integration, and battery cell manufacturers extending into pack management systems. Competitive moves center on backward integration into firmware development and strategic partnerships for wireless cell-monitoring architectures.
Among German diversified suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated powertrain archetype, anchoring OEM supply relationships through full-system capabilities. Infineon Technologies AG occupies the semiconductor specialist tier, representing silicon-carbide gate driver integration for high-voltage pack designs above 800V.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Infineon Technologies AG |
| Analog Devices, Inc. |
| LG Energy Solution |
| NXP Semiconductors |
| Denso Corporation |
| Panasonic Holdings Corporation |
| Eberspächer |
| Others |
Supply & Pricing Matrix
OEM direct sourcing mandates for ASIL-D certified architectures are compressing Tier-1 intermediary margins and forcing suppliers to absorb firmware development costs. This procurement concentration reshapes how BMS vendors price across centralized, modular, and distributed topology tiers.
Pricing Analysis
Direct-to-OEM contract structures dominate European BMS procurement, with master controller designs commanding premium positioning over outsourced slave module production. Price differentiation hinges on functional safety certification grade and volume scale, with ASIL-D validated firmware attracting substantial premiums over ASIL-B alternatives. Pricing pressure stems from cell manufacturers internalizing BMS design while outsourcing hardware assembly. Fleet operators demonstrate lowest price sensitivity due to fifteen-year performance guarantees, whereas aftermarket retrofit providers face acute cost compression.
Supply Chain Analysis
EU Battery Regulation domestic-content mandates and carbon intensity disclosure rules are reshaping sourcing decisions across European cell factory corridors. Semiconductor inputs draw from Taiwan, South Korea, and Germany, while processed cathode materials rest on Chinese and South Korean refining capacity. Lithium supply concentration creates single-source vulnerability for European pack manufacturers. Distribution runs through OEM captive procurement teams and Tier-1 system integrators with embedded electronics expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Electric Vehicle Battery Management System Market operates as a regulatory compounder where EU Battery Regulation passport mandates and ECE R100 safety protocols continuously upgrade replacement demand.
For Market Incumbents: Deploy firmware talent retention programs to counter ASIL-D certified developer scarcity constraining R&D scaling. Deepen backward integration into silicon-carbide gate driver design to defend margin position against semiconductor specialists. Consolidate around wireless cell-monitoring architecture partnerships before technical reliability thresholds mature. For New Entrants and Emerging Players: Capture greenfield positioning windows in Polish and Hungarian battery plant corridors lacking established supplier relationships. Target aftermarket second-life stationary storage applications requiring repurposed diagnostic software. Pursue fleet operator direct relationships bypassing OEM procurement concentration through predictive maintenance API offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play BMS firmware specialists holding embedded EU Battery Regulation passport capabilities. Long-term viability centers on suppliers with lifecycle tracking software aligned to CSRD carbon intensity disclosure rules. Watch delegated act timelines for recycled content verification protocols as inflection indicator for qualified supplier status.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | ECE R100 compliance filters non-certified vendors from German and French OEM tenders. |
| Wireless Cell-Monitoring R&D Partnership | Electromagnetic interference resolution unlocks distributed topology premiums in Dutch heavy-duty fleets. |
| Poland/Hungary Manufacturing Footprint | Greenfield cell factories in Lower Silesia and Győr lack established BMS supplier relationships. |
| Lifecycle Tracking Software Development | CSRD disclosure rules advantage suppliers with embedded carbon intensity monitoring capabilities. |
| Second-Life Storage Diagnostics Platform | Retired automotive packs require repurposed management systems opening aftermarket revenue streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with BMS platform engineers, Tier-1 supplier procurement leads, OEM firmware development directors, and fleet operator technical specifications managers with secondary validation against EU Battery Regulation delegated acts, ECE R100 technical documentation, KBA and ANSM regulatory filings, and IHS Markit vehicle production databases. Bottom-up cell factory capacity modeling and top-down OEM platform electrification targets were triangulated to establish market sizing boundaries.
Segment-weighting approaches distributed volume and value across product type, technology, end user, and installation dimensions, with vehicle class and voltage architecture treated as cross-cutting modifiers. CAGRs were derived from slope analysis of OEM platform rollout schedules and cell factory commissioning timelines, incorporating silicon-carbide adoption curves and thermal-runaway detection penetration rates as industry-specific demand drivers across the projection horizon.
Regulatory timeline delays, wireless architecture technical failures, and lithium supply disruptions are the dominant revision risks that could compress or extend forecast trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Energy Storage Systems Market
Battery Management System
US Energy Storage Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Energy Storage Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
EV Battery Management Market
Battery Management System
United States Rechargeable Battery Market
Battery Management System
Distributed Energy Storage System Market
Battery Management System
North America Battery Management System Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market
Battery Management System
Energy Storage System (ESS) Battery Market