
 United States Rechargeable Battery Market | 2026-2036
United States Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Rechargeable Battery Market Intelligence
UL 1973 certification for stationary battery systems is reorganizing supplier eligibility for grid-scale projects in the United States. Tesla, Inc. leverages its Nevada-based cell production to anchor utility-scale storage deployments. Panasonic Energy of North America sustains cylindrical cell output for automotive partners through its Kansas operations. LG Energy Solution competes across pouch and prismatic formats for Detroit-area EV programs.
Rechargeable batteries in the United States encompass electrochemical storage devices engineered for multiple charge-discharge cycles, with lithium-ion cells utilizing nickel-manganese-cobalt or lithium-iron-phosphate cathodes achieving energy densities above 250 Wh/kg for transportation applications. These systems power electric mobility, stabilize renewable generation, and sustain portable electronics through controlled ion transfer between anode and cathode materials. The lithium-ion product type captures dominant share across automotive and energy storage applications where cycle life and fast-charge capability command premium positioning. Lead-acid retains cost-driven utility in industrial backup power despite limited energy density. The energy storage application segment expands fastest as utilities procure four-hour duration systems for solar and wind integration.
The Inflation Reduction Act, EPA emissions standards, and NHTSA fuel economy rules collectively mandate domestic battery content and accelerate electrification timelines for vehicle and stationary applications. IRA production credits require North American assembly and qualifying critical mineral sourcing, reshaping where manufacturers locate cathode active material and cell production. State-level public utility commissions in California, Texas, and New York impose interconnection standards that favor certified battery systems for grid participation. Stakeholders must track how evolving domestic content thresholds and state procurement mandates alter qualification requirements for cell suppliers and system integrators.
Market Dynamics
The Inflation Reduction Act's domestic content thresholds are restructuring supplier qualification across the United States rechargeable battery supply chain, forcing cathode active material and cell production to relocate toward Michigan, Tennessee, and Nevada assembly corridors.
Growth Catalysts
- IRA Production Credits:North American assembly mandates and critical mineral sourcing rules are pulling cathode precursor and separator manufacturing into domestic facilities.
- NHTSA Fuel Economy Standards:Stringent fleet efficiency targets are compressing electrification timelines for light-duty and commercial vehicle platforms.
- Grid-Scale Storage Procurement:Four-hour duration lithium-ion systems for solar and wind integration are commanding utility capital allocation across Texas, California, and New York interconnection queues.
Market Restraints
- Cobalt and Nickel Price Volatility:Cathode metal cost swings are compressing cell producer margins and complicating long-term offtake contracting.
- East Asian Supply Concentration:Separator and electrolyte additive production remains concentrated in South Korea and Japan, creating single-source vulnerability.
- Technical Limitation:Fast-charge degradation in nickel-manganese-cobalt cells is constraining commercial fleet uptime requirements.
Strategic Opportunities
- Second-Life Automotive Packs:Retired EV batteries are repurposing into stationary storage for commercial and industrial backup power applications.
- Solid-State Convergence:Sulfide electrolyte and silicon anode integration is opening pathways for energy density above 400 Wh/kg in aviation and defense segments.
- Direct State Procurement Mandates:California CPUC resource adequacy requirements and New York storage targets are creating guaranteed offtake channels for certified systems.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Cell design and manufacturing process engineers are in acute shortage across the Great Lakes and Southeast production corridors.
- UL 1973 Certification Timelines:Stationary system safety validation is extending project development cycles by 8-14 months for grid-scale deployments.
- Legacy Grid Integration Complexity:Four-hour battery systems require sophisticated inverter and control hardware coordination with aging utility infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Rechargeable Battery Market |
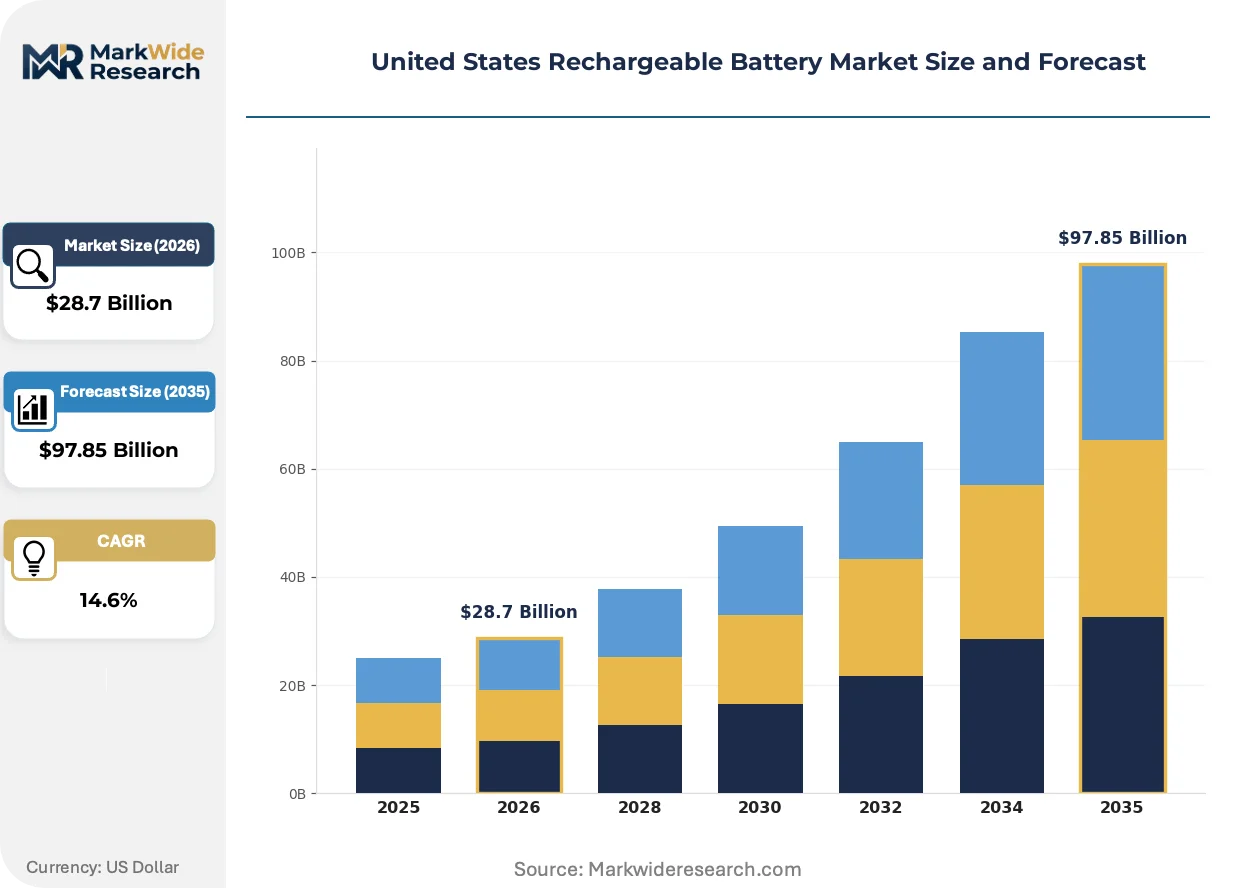
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $97.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Flow Application: Consumer Electronics, Automotive, Industrial, Energy Storage End User: Households, OEMs, Retailers, Utilities Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Samsung SDI, AESC, Tesla, Inc., Envision AESC, SK Battery America, Panasonic Energy of North America, SK On, Ford, LG Energy Solution, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Rechargeable Battery Market Strategic Shifts & Innovations
Cell chemistry evolution and domestic manufacturing localization are compressing supply chain configurations while reshaping competitive qualification requirements across automotive and utility procurement channels.
Solid-state battery architecture utilizing sulfide-based electrolytes is miniaturizing thermal management hardware requirements while enabling higher voltage operation. Automotive OEMs in the Detroit corridor are piloting these cells for 2028 platform integration. The technology is compressing pack-level volume and weight constraints for electric pickup and SUV segments.
The Inflation Reduction Act's phased domestic content thresholds are forcing cathode precursor and active material producers to establish North American refining capacity. IRA-compliant supply chains now require qualifying critical mineral extraction or processing within the United States or free trade agreement partners. Cell suppliers are responding by joint-venturing with mining and chemical processing partners in Nevada and the Great Lakes region.
Utility procurement departments are consolidating supplier rosters around vertically integrated cell-to-system providers capable of meeting state-level interconnection standards. Texas ERCOT and California ISO markets are favoring vendors with in-house module assembly and software control platforms. This concentration is visible most acutely in four-hour duration solar-plus-storage tenders where single-source accountability reduces project development risk.
United States Rechargeable Battery Market Segmentation
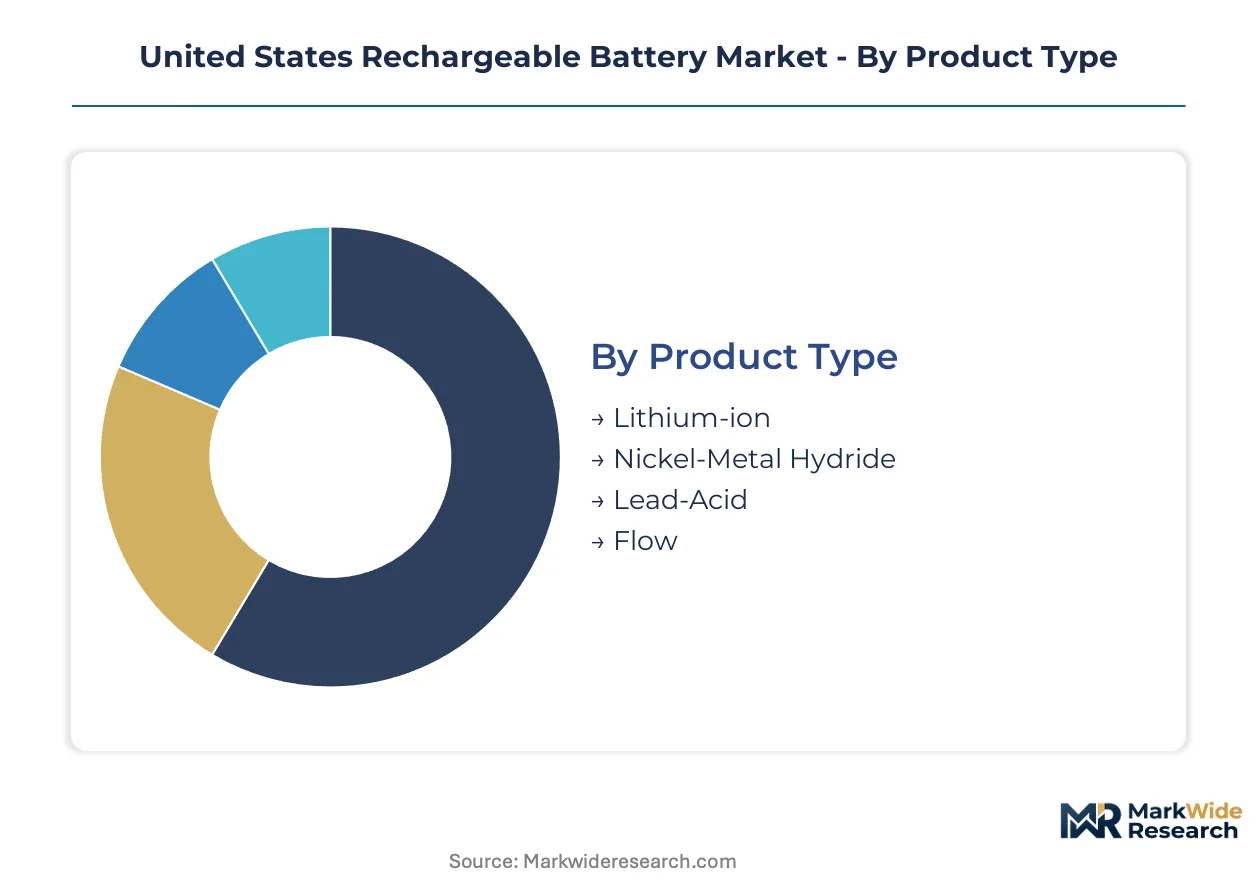
Segmentation reveals how IRA domestic content rules and state-level procurement mandates are concentrating demand across distinct technology tiers and customer channels. Each dimension exposes different qualification barriers and margin structures for suppliers competing across automotive, grid-scale, and consumer applications.
Product Type:
Domestic production clusters around lithium-ion formats serving Michigan and Tennessee automotive corridors, while lead-acid retains cost-driven industrial demand with minimal export orientation.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate cathodes dominate automotive and energy storage applications with energy densities above 250 Wh/kg. Michigan EV assembly plants and Nevada cell production anchor demand as IRA credits pull cathode active material sourcing into North American facilities.
- Lead-Acid:Mature flooded and absorbed glass mat designs serve industrial backup power and commercial fleet starting applications. Cost sensitivity constrains this segment to domestic replacement cycles with limited penetration in electrified transportation platforms.
- Nickel-Metal Hydride:Toyota and Honda hybrid programs in Kentucky and Indiana sustain modest cylindrical cell demand for power-split hybrid architectures.
- Flow:Vanadium and zinc-bromide chemistries target multi-hour utility storage in California and Texas markets where duration requirements exceed lithium-ion economics.
Lithium-ion commands the established base. The steepest expansion runs through flow batteries as utilities procure eight-hour duration systems for solar integration.
Application:
Cost tiers separate premium automotive qualification from commoditized consumer electronics procurement, with grid-scale storage occupying an intermediate margin band.
- Automotive:Light-duty EV platforms and commercial electrification programs in Detroit, Tennessee, and California drive cell qualification cycles lasting 24-36 months. NHTSA fuel economy standards compress OEM electrification timelines while IRA assembly mandates reshape supplier geography.
- Energy Storage:Four-hour duration lithium-ion systems integrate with Texas ERCOT and California ISO interconnection queues for solar and wind firming. CPUC resource adequacy requirements and New York storage targets create guaranteed offtake channels for UL 1973 certified systems.
- Consumer Electronics:Smartphone, laptop, and power tool applications source cylindrical and pouch cells through established Asian supply chains with limited domestic content compliance pressure.
- Industrial:Forklift motive power, telecom backup, and material handling equipment favor lead-acid cost structures in warehousing corridors across Ohio and Pennsylvania.
Automotive applications absorb the highest volume concentration. Energy storage is climbing the fastest as utility procurement departments consolidate supplier rosters around vertically integrated providers.
End User:
Volume concentration tilts toward institutional procurement with stringent certification requirements, while household demand fragments across retail channels.
- OEMs:Detroit-area automakers and energy storage integrators impose cell-level qualification protocols and long-term offtake contracts. Domestic content thresholds force cathode precursor joint ventures with Nevada and Great Lakes chemical processors.
- Utilities:Public utility commissions in California, Texas, and New York mandate certified battery systems for grid participation, favoring vendors with in-house module assembly and software control platforms.
- Retailers:Consumer electronics and automotive aftermarket channels distribute replacement batteries through national chains with limited technical specification leverage.
- Households:Residential solar-plus-storage adoption concentrates in California, Hawaii, and Northeast states with net metering reforms and state incentive programs.
OEM procurement commands qualification intensity and contract scale. Utility direct contracting is expanding most quickly as interconnection standards tighten.
Distribution Channel:
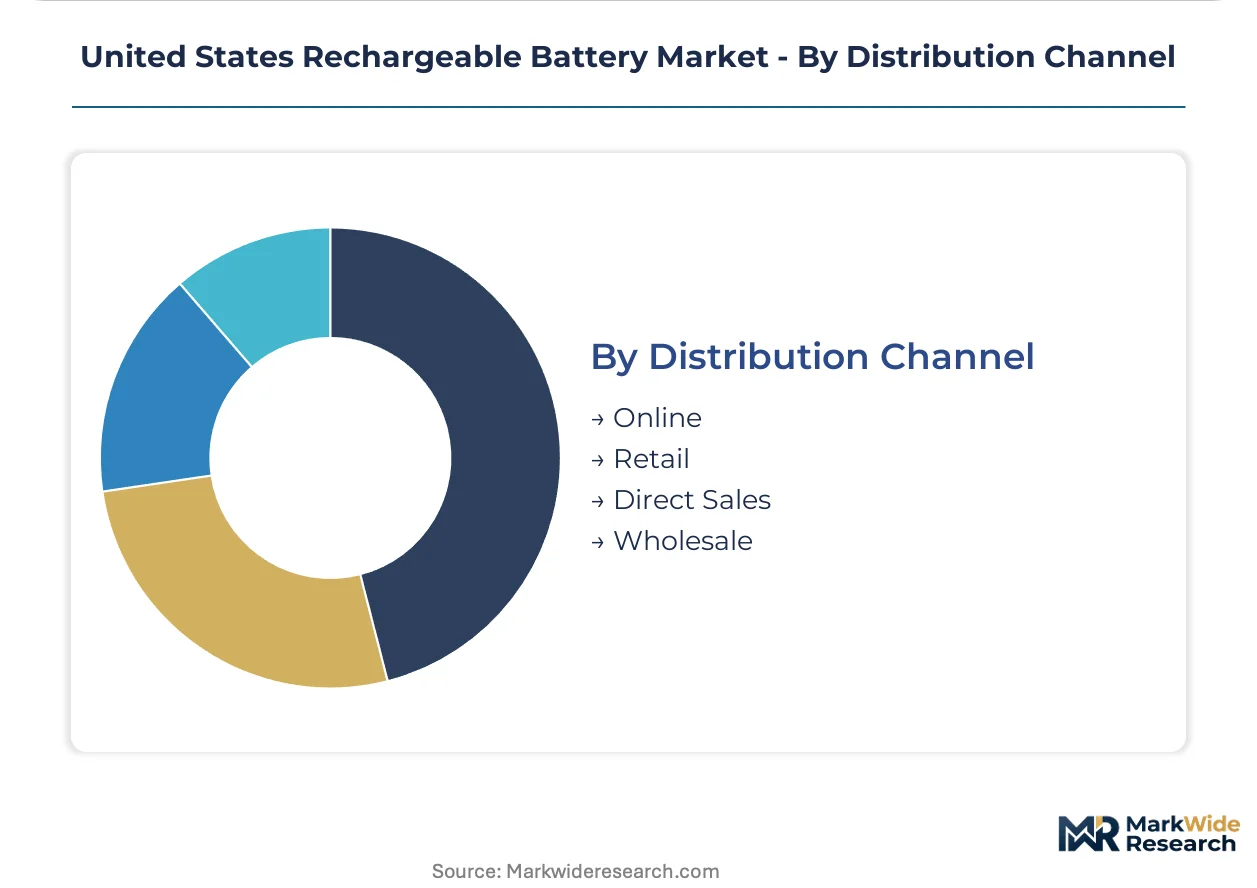
Customer type determines channel selection, with direct sales dominating high-volume institutional procurement and online channels fragmenting consumer access.
- Direct Sales:Automotive OEMs and utility procurement departments negotiate multi-year supply agreements with cell producers and system integrators. This channel captures the highest margin tier through technical collaboration and joint development programs.
- Wholesale:Industrial distributors and electrical supply houses serve commercial and industrial backup power applications with lead-acid and lithium-ion product lines.
- Online:E-commerce platforms and manufacturer-direct portals reach residential energy storage and consumer electronics replacement markets with standardized product configurations.
- Retail:Big-box automotive and electronics chains distribute consumer batteries with limited technical support and price-driven selection criteria.
Direct sales anchor the highest-value transactions. Online channels are scaling fastest as residential storage adopters research and purchase systems through digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's domestic content thresholds are redistributing cell and pack assembly capacity toward automaker-proximate corridors, with state-level procurement mandates accelerating deployment in renewable-rich interconnection zones.
Michigan
Detroit-area OEM electrification programs and battery joint ventures anchor North American lithium-ion demand. NHTSA fuel economy standards compress platform development timelines while IRA assembly credits pull cathode active material suppliers into the Great Lakes region. The state hosts concentrated cell-to-pack integration facilities serving light-duty and commercial vehicle programs.
Tennessee
Automotive OEM battery plants and energy storage system assembly operations cluster near Nashville and Chattanooga logistics corridors. State economic development incentives supplement federal production credits for facilities meeting domestic content thresholds. The region supplies cylindrical and prismatic cells to Southeast vehicle assembly plants.
Nevada
Lithium extraction operations and cathode precursor processing anchor the state's battery materials vertical. Tesla's Gigafactory cell production and utility-scale storage deployments concentrate near Reno-Sparks industrial zones. The region supplies IRA-compliant critical minerals to Michigan and Tennessee assembly corridors.
California
CPUC resource adequacy requirements and solar-plus-storage procurement mandates drive four-hour duration system demand. UL 1973 certification requirements filter supplier eligibility for grid participation in CAISO markets. The state leads residential energy storage adoption through net metering reform incentives.
Texas
ERCOT interconnection queues and renewable curtailment economics favor four-hour lithium-ion systems for solar and wind firming. ERCOT market rules and PUCT interconnection standards favor vendors with in-house control platforms. The state hosts utility-scale storage deployments serving coastal and West Texas renewable zones.
United States Rechargeable Battery Market Key Industry Players
Player mix skews toward Asian-headquartered cell producers with North American joint ventures and domestic OEM-affiliated battery operations. Market structure concentrates around cylindrical and prismatic format specialists serving automotive qualification cycles. Three archetypes dominate: integrated cell-to-system providers, cathode-active-material joint ventures, and OEM-captive assembly operations. Capacity expansion and strategic partnerships constitute the primary competitive moves as firms secure IRA-compliant supply chains.
Among Korea-based cell producers, SK Battery America and LG Energy Solution occupy positions within the automotive supply tier. SK On represents the cylindrical format specialist archetype through its joint venture structures. Tesla, Inc. anchors the integrated cell-to-system provider category with Nevada-based production and utility-scale deployment capabilities. Panasonic Energy of North America exemplifies the Japan-based cylindrical cell fabricator serving OEM programs through Kansas operations.
| Leading Market Players |
|---|
| Samsung SDI |
| AESC |
| Tesla, Inc. |
| Envision AESC |
| SK Battery America |
| Panasonic Energy of North America |
| SK On |
| Ford |
| LG Energy Solution |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty-day cathode precursor lead times from East Asian refiners concentrate pricing power with integrated cell producers possessing captive North American material streams, while spot cobalt and nickel volatility compresses margins for non-integrated assemblers serving IRA-compliant automotive programs.
Pricing Analysis
Certification level creates the primary spread across stationary storage procurement, with UL 1973 validation commanding fifteen to twenty percent premiums over uncertified alternatives in California CPUC and Texas ERCOT interconnection queues. Contract-based long-term offtake dominates automotive supply tiers, where OEM qualification cycles and IRA domestic content thresholds anchor pricing to cathode active material sourcing geography. Cost compression in nickel-manganese-cobalt cells intensifies because cobalt price volatility and Korean-Japanese separator import dependencies erode producer margins. Commercial fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, while utility procurement departments prioritize certified system availability over unit economics.
Supply Chain Analysis
Port congestion along the Shanghai-Long Beach trade lane elevates inbound logistics costs for separator and electrolyte additive shipments, compressing margins for non-integrated pack assemblers dependent on East Asian chemical inputs. Cathode active material production concentrates in China, South Korea, and Japan, with IRA critical mineral rules forcing joint ventures in Nevada and the Great Lakes region. Cell manufacturing draws from lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks, with DRC cobalt and Chilean lithium anchoring upstream exposure. Single-source vulnerability in Korean separator production creates structural risk for US-based cell producers. Distribution runs through direct OEM supply agreements for automotive volumes, with wholesale electrical distributors serving industrial backup power applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery lifecycle management services and predictive analytics subscriptions are expanding faster than hardware shipments, creating recurring revenue layers that improve customer stickiness and margin stability across utility and commercial fleet segments.
For Market Incumbents: Secure captive cathode precursor capacity through Nevada or Great Lakes joint ventures before IRA domestic content thresholds tighten, insulating margin structures from Korean-Japanese separator import volatility while locking in OEM qualification slots for Detroit and Tennessee automotive programs. For New Entrants and Emerging Players: UL 1973 fast-track certification pathways offer the most penetrable entry point into California and Texas utility procurement rosters, where vertically integrated system providers face capacity constraints and state mandates guarantee offtake for certified four-hour duration deployments. For Investors and Strategic Acquirers: Long-term, this sits as a materials-captive infrastructure play because IRA production credits and critical mineral rules are reshaping competitive advantage toward upstream control, with the inflection signal to watch being cathode active material plant commissioning announcements in free trade agreement countries.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Active Material Joint Venture | IRA compliance hinges on North American precursor processing, locking in OEM qualification. |
| UL 1973 Certification Investment | California CPUC and Texas PUCT interconnection standards filter non-certified competitors from grid-scale procurement. |
| Second-Life Pack Integration | Retired EV batteries repurposed for commercial backup power extend asset value and service attach opportunities. |
| Solid-State Pilot Line Deployment | Sulfide electrolyte prototypes target 2028 automotive platform integration in Detroit corridor programs. |
| Direct Utility Contracting Channel | ERCOT and CAISO market participation favors vendors with in-house control software and module assembly. |
Research Approach
Cross-validation between primary interviews with cell manufacturing executives, utility procurement officers, and cathode chemical processing specialists and secondary analysis of EIA storage deployment databases, FERC interconnection filings, and SEC battery producer disclosures anchors the qualitative findings, with bottom-up capacity build-up triangulated against top-down IRA credit absorption modeling.
Sensitivity analysis across cobalt price bands, IRA domestic content threshold phase-ins, and NHTSA fuel economy standard stringency scenarios frames the analytical approach, with segmentation dimensions spanning lithium-ion format type, application tier, and end-user procurement channel over the projection horizon, deriving CAGRs from cell production capacity announcements and utility storage interconnection queue data.
Underlying assumptions cover IRA credit continuity, East Asian separator supply stability, and OEM electrification timeline adherence, with deviation risk concentrated in critical mineral price spikes and electrochemical engineering talent scarcity across Great Lakes and Southeast production corridors; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
US Energy Storage Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
Battery Management Market
Battery Management System
Energy Storage Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Power Battery Management System Market
Battery Management System
Global Power Management System Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
Automotive Battery Management System Market