
 Argentina Renewable Energy Market | 2026-2036
Argentina Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Renewable Energy Market Outlook
Lithium-ion battery storage is shifting the economics of grid-scale renewable dispatch in Argentina. Central Puerto SA leverages its integrated thermal-renewable fleet to sustain round-the-clock supply contracts. Enel Green Power anchors its position through dedicated wind farms in Chubut and Buenos Aires provinces. Genneia SA specializes in distributed solar generation for commercial off-takers.
Argentina renewable energy encompasses electricity generation systems that harness wind, solar, biomass, and hydro resources through turbines, photovoltaic arrays, combustion chambers, and run-of-river installations with typical capacity factors ranging from 25% to 55%. These installations feed into the national SADI grid or serve isolated demand pockets, displacing imported fossil fuels and reducing seasonal hydro vulnerability. Wind technology dominates installed capacity in southern Patagonia where mean wind speeds exceed eight meters per second at hub height. Solar power claims the fastest expansion trajectory across the high-irradiance provinces of San Juan, San Luis, and Mendoza. Biomass occupies a mature niche serving sugar mill cogeneration and forestry residue plants in Mesopotamia.
The Secretariat of Energy administers the RenovAr and MATER auction mechanisms that dictate offtake pricing and project commissioning schedules for private developers. The Argentine central bank and tax authority enforce transfer pricing and import duty frameworks affecting equipment procurement from Asia and Europe. Law 27.191 mandates that large consumers source twenty percent of demand from renewable sources, creating compliance-driven procurement. Stakeholders must monitor auction round timing, currency convertibility guarantees, and transmission bottleneck resolution in the western corridor.
Market Dynamics
Grid-scale battery storage is rewriting dispatch economics for Argentine renewable developers, compressing price spreads between peak and off-peak hours while enabling firm supply contracts that previously required thermal backup.
Growth Catalysts
- Law 27.191 mandate:Large consumers must source twenty percent of demand from renewable sources, creating compliance-driven procurement pipelines for wind and solar developers.
- RenovAr auction mechanism:The Secretariat of Energy's competitive bidding framework provides long-term offtake pricing certainty that unlocks project finance from domestic and international lenders.
- Patagonian wind resource concentration:Mean wind speeds exceeding eight meters per second at hub height in Chubut and Santa Cruz provinces deliver capacity factors above forty-five percent, lowering levelized costs.
Market Restraints
- Currency convertibility risk:Central Bank restrictions on foreign exchange repatriation create hedging costs that inflate project equity returns requirements.
- Western transmission bottleneck:Insufficient high-voltage capacity between the Cuyo solar belt and Buenos Aires demand centers forces curtailment during peak generation periods.
- Imported equipment dependency:Solar modules and wind turbines sourced from Asia face import duty volatility under Argentina's shifting trade policy framework.
Strategic Opportunities
- Agro-industrial distributed generation:San Juan and Mendoza wineries and olive processors seek behind-the-meter solar to offset rising grid tariffs and diesel generator costs.
- Green hydrogen pilot zones:The Secretariat of Energy's proposed regulatory sandbox in Patagonia targets wind-to-hydrogen export projects leveraging existing port infrastructure.
- MATER distributed auction:Smaller-scale renewable tenders for sub-five-megawatt projects open participation to commercial and industrial offtakers previously excluded from RenovAr.
Industry Challenges
- Grid code compliance timelines:New renewable interconnects face protracted testing protocols by the wholesale electricity market administrator, delaying commercial operation dates.
- Specialized EPC contractor scarcity:Limited domestic engineering-procurement-construction capacity for utility-scale battery integration forces reliance on imported technical labor.
- Land tenure complexity:Provincial-level environmental impact assessment variability and indigenous consultation requirements extend permitting cycles in northern provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Renewable Energy Market |
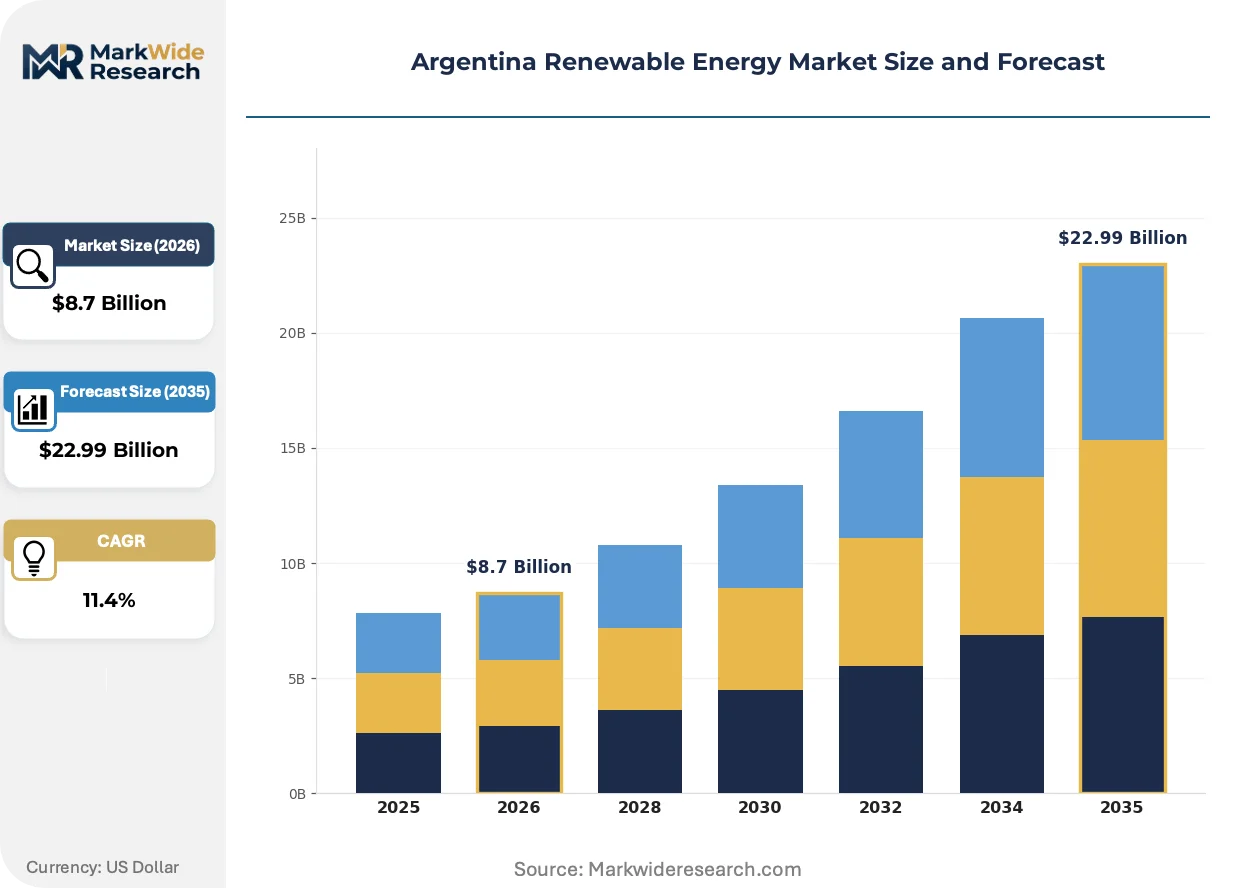
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wind, Solar, Biomass, Hydro Energy Source: Solar Power, Wind Energy, Geothermal, Ocean Energy Application: Power Generation, Heating, Transportation, Industrial Use End User: Residential, Commercial, Industrial, Agricultural |
| Companies Covered | Central Puerto SA, Enel Green Power, Genneia SA, 360 Energy SA, Acciona Energía, YPF Luz, AES Argentina Generación, Neoen Argentina, Pampa Energía SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Renewable Energy Market Strategic Shifts
Technology convergence and procurement model evolution are compressing development timelines while shifting risk allocation between developers, offtakers, and grid operators across Argentina's renewable value chain.
Bifacial photovoltaic modules paired with single-axis tracking is rewriting solar yield assumptions in the Cuyo region. Agro-industrial buyers in San Luis and Mendoza provinces are deploying these configurations to maximize generation per hectare of land under lease. The technology is compressing the payback period for commercial solar investments below six years in high-irradiance zones.
Law 27.191 enforcement tightening by the Secretariat of Energy is accelerating large-consumer compliance procurement. Industrial offtakers in Buenos Aires and Córdoba provinces now face audit requirements for renewable sourcing documentation. The mandate is forcing cement, steel, and chemical manufacturers into direct power purchase agreements rather than relying on renewable energy certificates alone.
Corporate buyers are consolidating procurement through aggregated auction participation. Groups of mid-sized manufacturers in Rosario and Tucumán are pooling demand to meet RenovAr minimum bid thresholds previously accessible only to utilities. This aggregation is visible most acutely in the food processing sector, where cooperative buying structures reduce transaction costs and improve negotiating leverage against developers.
Argentina Renewable Energy Market Segmentation
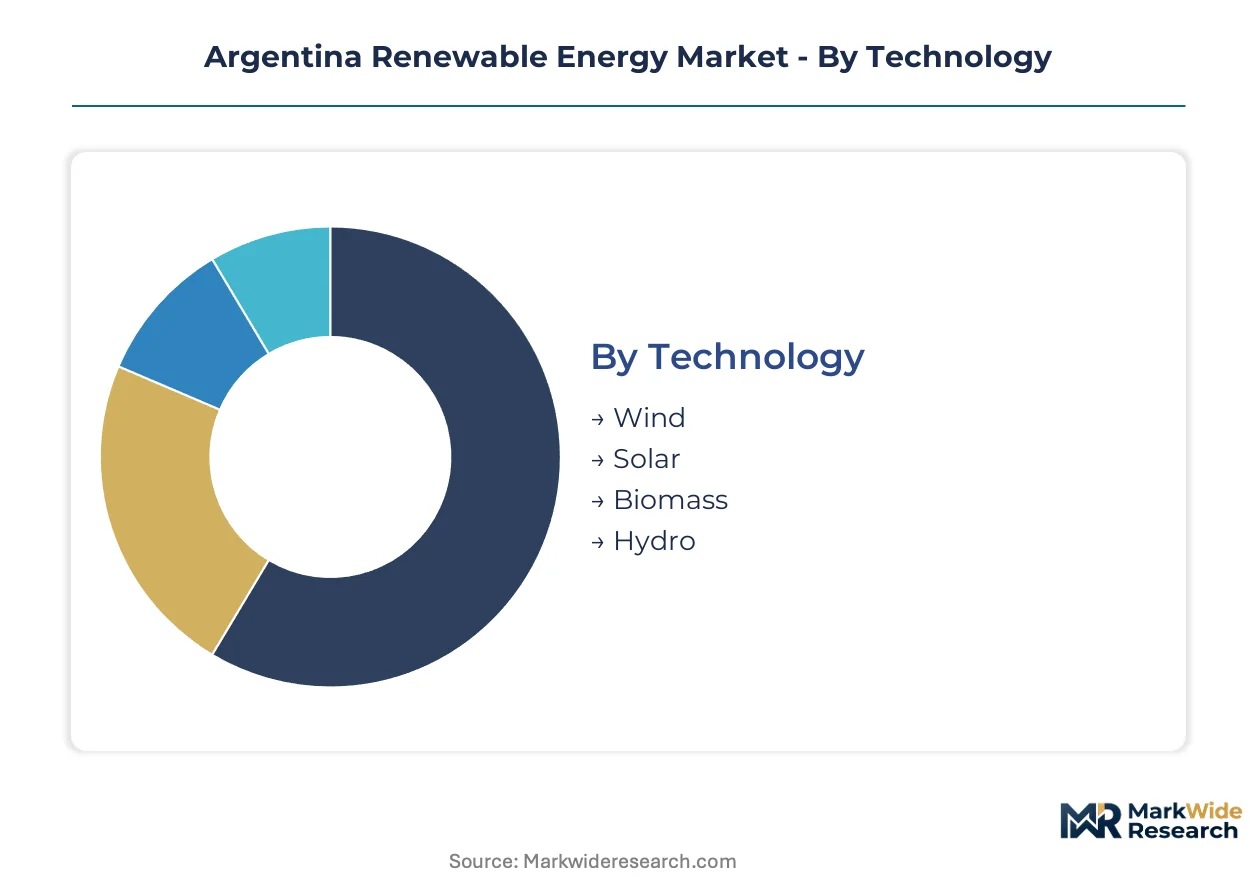
Argentina's renewable energy market fragments across technology maturity, resource geography, and offtaker sophistication. Each segmentation axis reveals distinct investment timelines, financing structures, and regulatory touchpoints that shape developer strategy.
Technology:
Standardized turbine and panel designs dominate procurement, while bespoke integration solutions address grid-specific constraints.
- Wind:Horizontal-axis turbines rated 2-3 MW anchor capacity additions in Chubut and Santa Cruz provinces. Patagonian wind farms feed the SADI grid through 500 kV trunk lines, with capacity factors above forty-five percent attracting long-term power purchase agreements from aluminum smelters and mining operators.
- Solar:Crystalline silicon photovoltaic arrays with single-axis tracking maximize yield across the Cuyo solar belt. Mendoza and San Juan provinces concentrate agro-industrial deployments where wineries and olive processors offset diesel generator costs during harvest seasons.
- Biomass:Bagasse cogeneration systems serve sugar mills in Tucumán and Jujuy with mature operational profiles.
- Hydro:Run-of-river installations in the Andean footholds provide baseload complement to intermittent wind and solar.
Leading the category by volume: Wind. Growing fastest: Solar.
Energy Source:
Resource concentration in specific provinces dictates supply chain configuration and transmission investment priorities.
- Solar Power:Photovoltaic and concentrated solar thermal systems harness irradiance levels exceeding 2,000 kWh/m² annually in western provinces. Distributed deployments behind agricultural meters accelerate as Law 27.191 compliance deadlines approach.
- Wind Energy:Onshore turbines exploit the Patagonian wind corridor's consistent resource. Offshore exploration remains pre-commercial given port infrastructure limitations.
- Geothermal:Low-enthalpy resources in the Puna region support direct heating applications.
- Ocean Energy:Tidal and wave technologies occupy experimental status along the Atlantic coast.
Dominant by installed capacity: Wind Energy. Steepest expansion trajectory: Solar Power.
Application:
Revenue stability varies sharply across applications, with grid-connected generation commanding lower risk premiums than behind-the-meter thermal substitution.
- Power Generation:Grid-scale wind and solar farms bid into the wholesale electricity market under RenovAr auction contracts. Firm supply obligations drive battery storage co-location to manage dispatch commitments.
- Heating:Biomass boilers and solar thermal collectors serve industrial process heat in food processing and textile sectors.
- Transportation:Biofuel blending mandates create demand for agricultural residue conversion.
- Industrial Use:Captive renewable generation reduces exposure to grid tariff volatility for cement and steel manufacturers.
Highest revenue concentration: Power Generation. Fastest policy-driven expansion: Industrial Use.
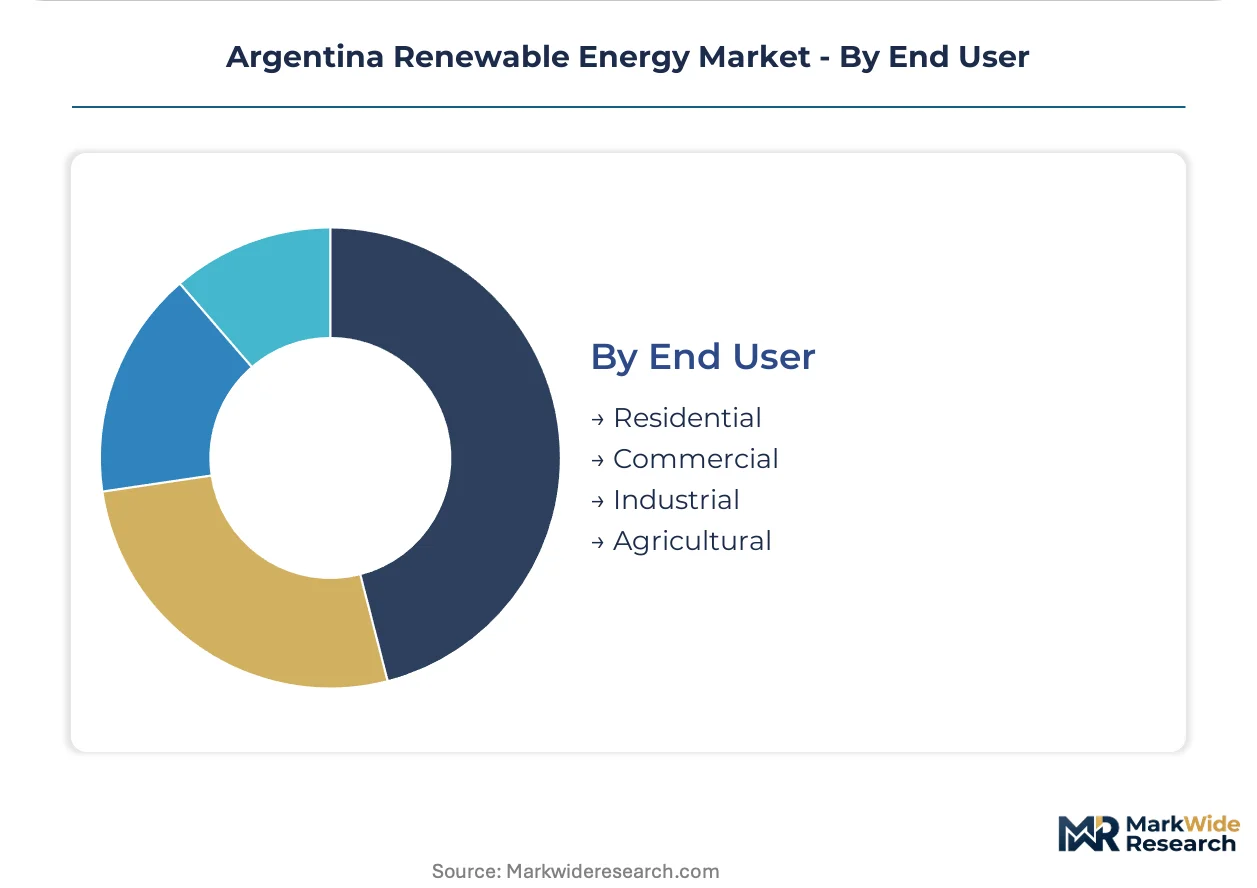
End User:
Procurement sophistication and contract scale diverge sharply across customer categories, with industrial offtakers driving aggregated auction participation.
- Residential:Distributed solar net metering programs in Buenos Aires and Córdoba provinces enable rooftop deployment. Financing constraints limit penetration to higher-income households without specialized credit products.
- Commercial:Mid-sized enterprises in Rosario and Tucumán pool demand through cooperative buying structures. Food processors and cold storage operators prioritize behind-the-meter solar to stabilize operating costs.
- Industrial:Large consumers face mandatory twenty percent renewable sourcing under Law 27.191. Cement, steel, and chemical manufacturers execute direct power purchase agreements with RenovAr-winning developers.
- Agricultural:San Juan and Mendoza wineries deploy bifacial tracking systems to maximize generation per hectare. Irrigation pumping loads align solar production profiles with demand peaks.
Largest contract volumes: Industrial. Gaining share fastest: Agricultural.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for renewable electricity concentrates in Argentina's agro-industrial provinces and mining corridors, with provincial governments competing to attract clean energy investment through tax abatements and streamlined permitting.
Buenos Aires Province
Industrial load centers in La Plata and Bahía Blanca drive procurement of firm renewable supply for petrochemical and steel plants. The provincial energy ministry coordinates with the national Secretariat of Energy on transmission expansion timelines. Developers cluster around the 500 kV trunk lines serving the Greater Buenos Aires metropolitan zone.
Chubut Province
Aluminum smelters and mining operators anchor offtake demand for Patagonian wind farms with capacity factors exceeding forty-five percent. Provincial authorities administer land use permits for wind turbine corridors. The Puerto Madryn industrial zone hosts grid connection infrastructure serving the Atlantic coastal wind belt.
Mendoza Province
Wineries and olive processors deploy bifacial solar tracking systems to offset irrigation pumping costs and diesel generator reliance. The provincial renewable energy law mandates net metering standards for agricultural distributed generation. The Uco Valley and Maipú districts concentrate behind-the-meter solar installations.
San Juan Province
High-irradiance conditions exceeding 2,000 kWh/m² annually attract utility-scale solar developers targeting mining sector procurement. The provincial government offers accelerated depreciation for renewable equipment purchases. The Calingasta and Iglesia valleys host the densest concentration of photovoltaic arrays in the Cuyo region.
Santa Cruz Province
Wind-to-hydrogen pilot zones leverage world-class wind resources and Atlantic port access for export-oriented green fuel projects. The Secretariat of Energy's regulatory sandbox framework targets this province for first-mover hydrogen infrastructure. Río Gallegos serves as the logistics hub for equipment staging and maritime export.
Argentina Renewable Energy Market Competitive Environment
Portfolio diversification dominates the current landscape as integrated utilities and independent power producers reposition around hybrid renewable-thermal offerings. The competitive structure splits between legacy generators with captive transmission access and pure-play developers dependent on auction outcomes. Three archetypes define positioning: vertically integrated incumbents controlling grid interconnection points, specialized renewable developers with project finance expertise, and international utilities importing capital structures from European parent companies. M&A activity and strategic partnerships constitute the primary competitive vectors.
Among integrated Argentine generators, Central Puerto SA and Pampa Energía SA exemplify the incumbent archetype leveraging existing thermal fleet synergies. Enel Green Power and AES Argentina Generación represent international utility subsidiaries deploying parent-company balance sheet capacity. These six entities anchor the competitive field without exhaustive enumeration.
| Leading Market Players |
|---|
| Central Puerto SA |
| Enel Green Power |
| Genneia SA |
| 360 Energy SA |
| Acciona Energía |
| YPF Luz |
| AES Argentina Generación |
| Neoen Argentina |
| Pampa Energía SA |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion battery cell costs cascade through Argentine renewable project economics, compressing developer margins at the EPC tier while enabling premium pricing for firm dispatch contracts downstream to mining and industrial offtakers.
Pricing Analysis
Volume procurement through RenovAr auction rounds commands thin developer margins against long-term offtake certainty, while bilateral corporate power purchase agreements with Law 27.191-mandated buyers capture pricing premiums tied to firm supply obligations and renewable energy certificate bundling. Price differentiation rests on technology performance guarantees and grid code compliance certification tiers, with battery-integrated solar projects commanding spreads above pure intermittent generation. Cost compression in module supply chains is intensifying as Chinese manufacturers compete for Argentine market share, squeezing EPC contractors who lack backward integration into component sourcing. Agricultural offtakers in San Juan and Mendoza provinces exhibit acute price sensitivity due to commodity revenue volatility, whereas aluminum smelters and mining operators in Chubut accept premium pricing for 24/7 renewable supply.
Supply Chain Analysis
Freight costs from Shanghai and Rotterdam ports to Buenos Aires and Puerto Madryn dictate total landed cost structures for photovoltaic modules and wind turbine nacelles, with ocean rates and Argentine import duty volatility amplifying project budget uncertainty. Equipment sourcing concentrates in China for crystalline silicon panels and in Spain and Denmark for wind turbine assemblies, with inverter and battery management systems drawing from German and South Korean suppliers. Raw material dependencies span polysilicon, rare-earth magnets, and lithium carbonate feedstock from Chilean and Australian extraction operations. Single-source vulnerability in high-voltage transformer manufacturing creates bottleneck risk for grid interconnection timelines. Distribution runs through bonded warehouse staging in Buenos Aires Province before final-mile deployment to Patagonian wind corridors and Cuyo solar belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's renewable energy sector sits at a technology-transition inflection where lithium-ion battery storage is displacing gas turbine peakers as the preferred firming resource for grid-scale solar and wind developers.
For Market Incumbents: Deploy hybrid project development capabilities that co-locate battery storage with existing wind and solar assets to capture premium pricing for dispatchable renewable supply contracts. Central Puerto SA and Pampa Energía SA should accelerate backward integration into battery system integration to defend margin position against pure-play storage developers entering through MATER auction participation. Currency hedging structures and local equipment assembly partnerships mitigate foreign exchange repatriation risk that threatens project equity returns. For New Entrants and Emerging Players: Begin with distributed solar aggregation for agricultural offtakers in Mendoza and San Juan provinces, where Law 27.191 compliance deadlines and diesel generator displacement economics create immediate procurement urgency. Cooperative buying structures among wineries and olive processors offer the most penetrable entry path, with behind-the-meter bifacial tracking systems delivering six-year payback periods that bypass transmission interconnection queues choking utility-scale development. For Investors and Strategic Acquirers: RenovAr auction round closures clearing below historical price floors are the leading indicator that developer distress and consolidation opportunities are accelerating across the Argentine market. Target acquisition profiles should emphasize EPC contractors with battery integration expertise and land-positioned project pipelines in the Patagonian wind corridor, where capacity factors above forty-five percent sustain long-term offtake viability. Monitor Secretariat of Energy announcements on MATER auction timing and currency convertibility guarantee structures as inflection signals for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Grid-scale battery co-location with Patagonian wind farms captures premium firm supply contracts from aluminum smelters. |
| Power Purchase Agreement | Direct corporate procurement with Law 27.191-mandated cement and steel manufacturers locks in long-term revenue stability. |
| Technology Licensing | Bifacial tracking system IP partnerships accelerate agro-industrial distributed generation deployment in Cuyo provinces. |
| Backward Integration into Storage | In-house battery system integration reduces EPC contractor dependency and compresses project development timelines. |
| Green Certification Program | Renewable energy certificate bundling with firm supply contracts differentiates offerings in RenovAr auction rounds. |
Study Parameters
Multi-period observation of RenovAr auction clearing prices, project commissioning timelines, and currency hedging cost structures anchored the trend analysis, supplemented by interviews with utility planning officers at CAMMESA, IPP project developers active in Chubut and Mendoza provinces, EPC contractors specializing in battery integration, and grid operators managing the western transmission corridor. Secondary validation drew from Secretariat of Energy auction documentation, Argentine central bank foreign exchange regulations, IEA renewable energy market reports, and project finance databases tracking Latin American power sector investment. Bottom-up project-level capacity addition forecasts were triangulated against top-down national renewable penetration targets under Law 27.191.
Segment-weighting across technology type, resource geography, and offtaker category shaped the analytical framework, with wind, solar, and battery storage capacity modeled separately through the projection horizon. Cuyo solar belt irradiance profiles and Patagonian wind speed distributions informed capacity factor assumptions, while regulatory framework segmentation captured RenovAr, MATER, and bilateral contract pathways. CAGRs were derived from installed capacity buildout trajectories and average project sizes by technology, with currency convertibility risk premiums and transmission bottleneck resolution timelines as key forecast inputs.
Underlying measurement precision varies by segment; utility-scale wind and solar with RenovAr offtake contracts carry tighter precision than distributed generation and green hydrogen pilot projects where regulatory sandboxes remain undefined. Forecasts reflect assumptions on auction round frequency, foreign exchange repatriation policy stability, and western corridor transmission expansion schedules that could materially revise outlooks if Secretariat of Energy priorities shift. Stakeholders should weight assumptions against their own operating context and risk tolerance for Argentine macroeconomic volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
North America IoT in Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Portugal Renewable Energy Market