
 Lithium-Ion UPS System Market | 2026-2036
Lithium-Ion UPS System Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion UPS System Market Insights
Remote monitoring and predictive maintenance subscription layers is broadening what UPS vendors monetize beyond hardware shipments. Schneider Electric leverages its EcoStruxure platform to anchor recurring revenue streams across enterprise accounts. Eaton Corporation sustains competitive positioning through specialized lithium-ion safety architectures for critical power applications. Vertiv Group Corp. differentiates via edge-computing UPS configurations that integrate thermal and power management.
A lithium-ion UPS system stores electrical energy in lithium iron phosphate or nickel manganese cobalt oxide cells and delivers conditioned, uninterrupted power through inverter and rectifier circuits operating at 380–480 V three-phase input. These systems serve mission-critical loads where power quality failures risk data loss, equipment damage, or operational downtime. Online topology dominates product type segments due to zero transfer time and superior harmonic filtering demanded by hyperscale data centers. Edge deployment represents the fastest-growing configuration as distributed AI inference and retail digitalization push compute closer to consumption points. Above 20 kVA capacity bands concentrate margin pools because engineering complexity and site-specific integration requirements limit commoditization.
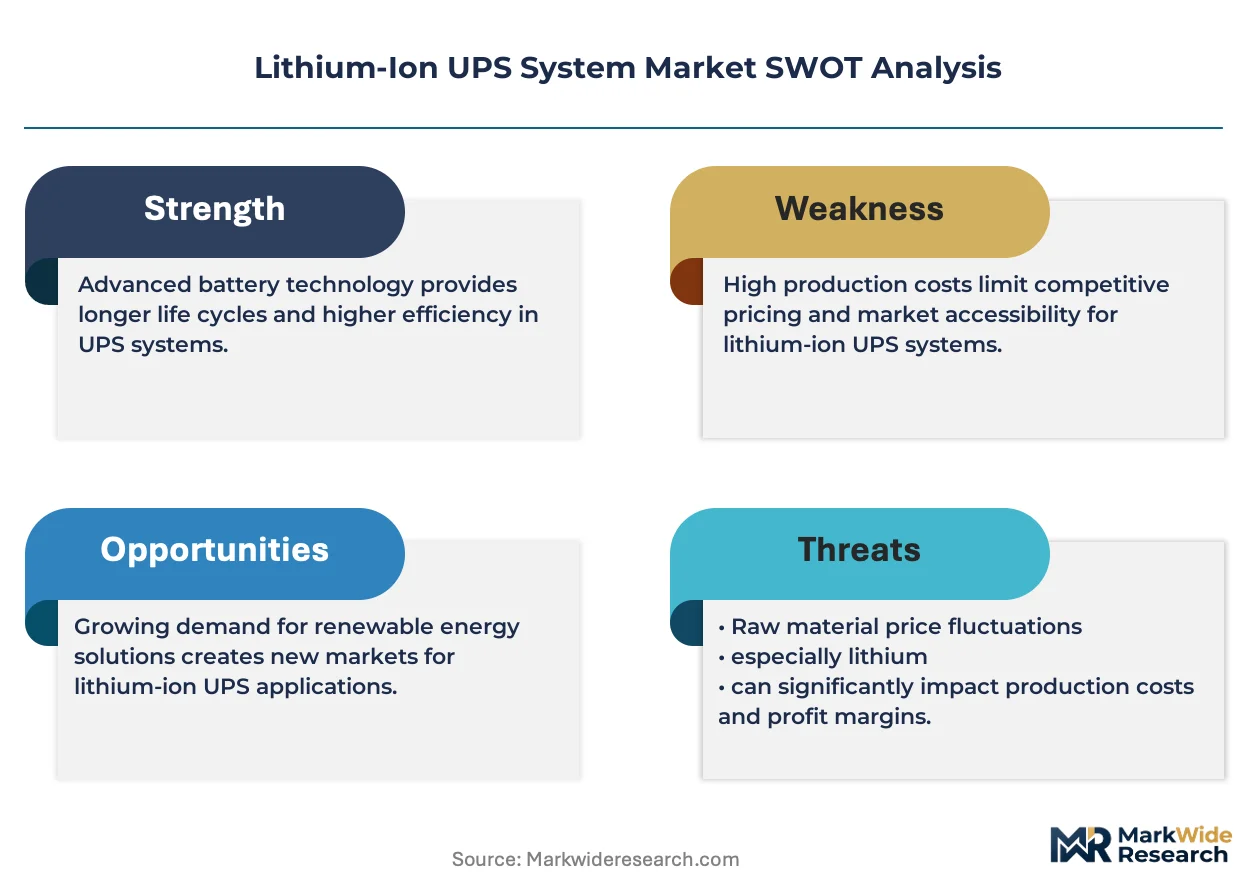
NFPA 855 in the United States mandates thermal runaway containment and fire suppression for lithium-ion battery installations above specified energy thresholds, directly shaping product design and facility engineering costs. EU Green Deal battery passport regulations and CE marking under the MDR framework enforce supply chain traceability and circularity obligations for systems sold across European member states. Stakeholders must monitor evolving fire codes and carbon accounting rules to determine whether to regionalize manufacturing or absorb compliance premiums through pricing.
Market Dynamics
Hyperscale data center operators are systematically retiring valve-regulated lead-acid battery fleets and consolidating procurement around lithium-ion architectures, compressing vendor selection cycles and elevating fire safety engineering to a primary purchase criterion.
Growth Catalysts
- NFPA 855 thermal runaway mandates:United States fire codes now require gas detection and suppression systems for lithium-ion installations above 50 kWh, forcing facility upgrades that favor factory-integrated UPS-battery enclosures over site-assembled configurations.
- Hyperscale cloud procurement:Amazon Web Services, Microsoft Azure, and Google Cloud are specifying 10-15 year design life and remote monitoring APIs as standard terms in multi-megawatt RFPs, pulling Tier-1 vendors into service-contract revenue models.
- Lithium iron phosphate chemistry maturation:Cell-to-pack architectures from CATL and BYD are collapsing cost premiums versus lead-acid to under 20% at system level while delivering 3x cycle life.
Market Restraints
- Cathode active material concentration:Nickel manganese cobalt oxide supply chains concentrate in Democratic Republic of Congo for cobalt and Indonesia for nickel, exposing OEMs to ESG audit pressure and forced labor disclosure requirements under EU Green Deal battery passports.
- Fire suppression capex burden:NFPA 855 compliance adds $150,000-$400,000 per megawatt-hour of installed capacity for aerosol or clean agent systems, eroding total cost of ownership advantages in retrofit installations.
- Lead-acid residual installed base:Approximately 40% of data center UPS capacity globally still runs on flooded or VRLA batteries with 3-5 year replacement cycles, creating procurement inertia and stranded asset risk for operators.
Strategic Opportunities
- Edge computing micro-UPS:Distributed AI inference nodes in retail, manufacturing, and telecom require 5-20 kVA lithium-ion systems with integrated thermal management, a segment where incumbent data center vendors have limited footprint.
- EU battery passport compliance services:The EU Green Deal mandates digital product passports tracing carbon intensity, recycled content, and supply chain due diligence by 2027, creating software and certification revenue streams for vendors with traceability infrastructure.
- Second-life battery integration:Retired electric vehicle lithium-ion packs are entering stationary storage refurbishment pipelines, enabling UPS vendors to source cells at 30-40% of virgin material cost for non-critical backup applications.
Industry Challenges
- Thermal runaway containment engineering:Cell-level propagation testing under UL 9540A requires 6-12 month validation cycles, compressing product launch timelines and demanding dedicated fire modeling capabilities that few vendors possess in-house.
- Legacy SCADA integration:Industrial facilities with 1990s-era building management systems require protocol translation gateways to accept lithium-ion UPS telemetry, extending commissioning timelines and eroding margin on sub-100 kVA installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion UPS System Market |
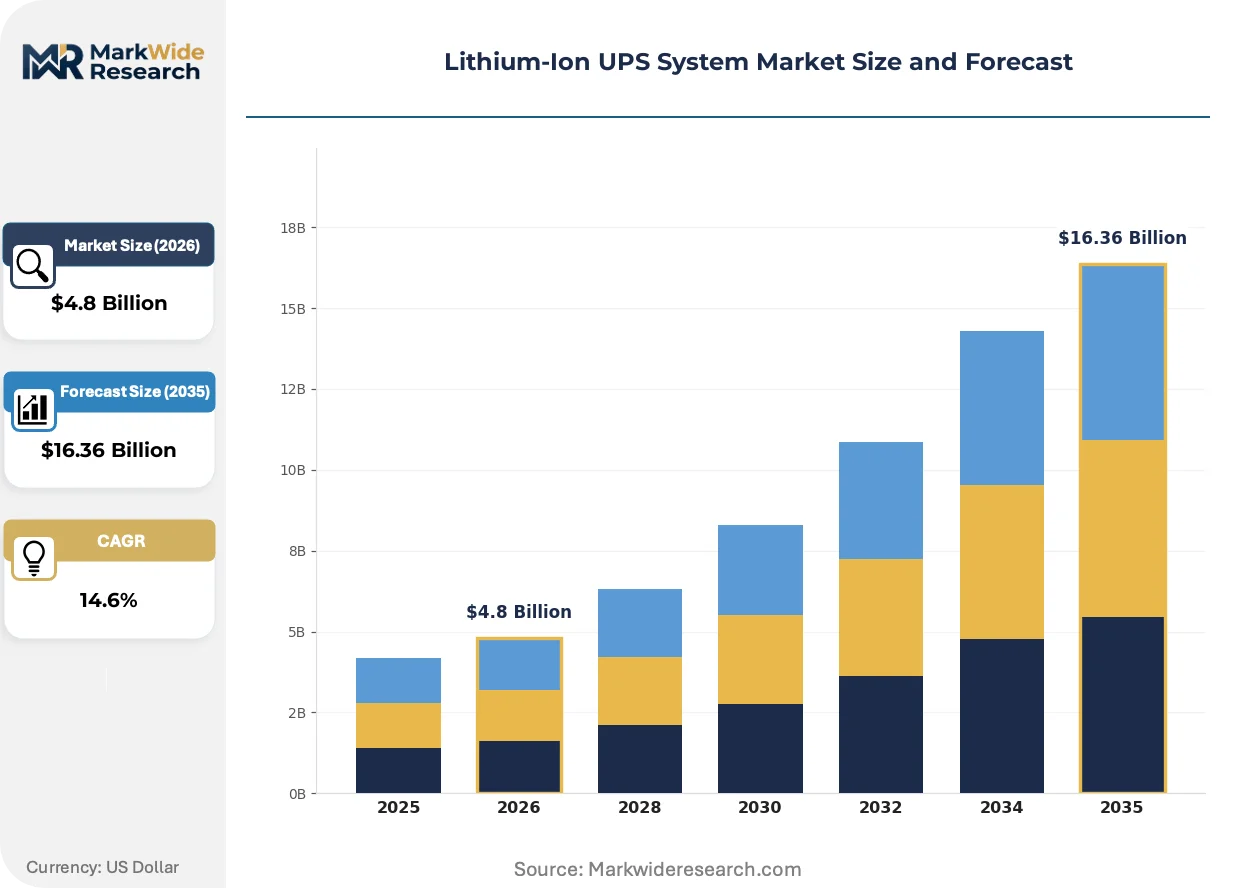
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Online, Offline, Line-Interactive, Modular End User: Data Centers, Telecommunications, Healthcare, Industrial Deployment: On-Premises, Cloud, Hybrid, Edge Capacity: 1-5 kVA, 6-10 kVA, 11-20 kVA, Above 20 kVA |
| Companies Covered | Schneider Electric, Eaton Corporation, Vertiv Group Corp., Delta Electronics, ABB Ltd., Emerson Electric Co., Exide Industries, East Penn Manufacturing, GS Yuasa International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion UPS System Market Trends and Innovations
Modular power architecture is fragmenting the traditional monolithic UPS design paradigm, enabling capacity scaling in 50-250 kW increments that match cloud workload variability. This shift is compressing procurement decision cycles and rewiring vendor-customer relationships around firmware subscription rather than hardware replacement.
Solid-state transformer technology is decentralizing power conversion stages within data center white space, replacing conventional 480V distribution with medium-voltage direct current feeds that eliminate multiple AC-DC conversion losses. Microsoft and Google are piloting 1,500V DC architectures in new hyperscale campuses, collapsing copper conductor mass by 30-40% and enabling rack-level battery integration that shortens power path length. This topology is decentralizing the UPS function from a centralized plant to distributed cabinet-level units, compressing fault domains and complicating traditional service dispatch models.
EU Green Deal battery passport regulations are mandating supply chain traceability and carbon intensity disclosure for lithium-ion systems placed on European markets, forcing vendors to deploy blockchain-anchored documentation platforms. The industrial consequence is a bifurcation between vendors with vertically controlled cell supply chains and those dependent on merchant market procurement. Systems above 2 kWh capacity face the strictest documentation requirements, pushing European data center operators to favor vendors with captive recycling partnerships and auditable mine-to-manufacturing records.
Power-as-a-service contracting is displacing capital purchase models for edge computing deployments, with telecom and retail operators preferring fixed monthly fees covering hardware, installation, monitoring, and end-of-life recycling. Eaton and Schneider Electric are structuring 7-10 year service agreements that bundle lithium-ion UPS with thermal management and remote diagnostics, capturing recurring revenue streams that hardware margins alone cannot sustain. This shift is most visible in Germany and France, where energy-as-a-service regulatory frameworks and compressed IT refresh cycles accelerate outsourcing of critical power infrastructure ownership.
Lithium-Ion UPS System Market Segmentation
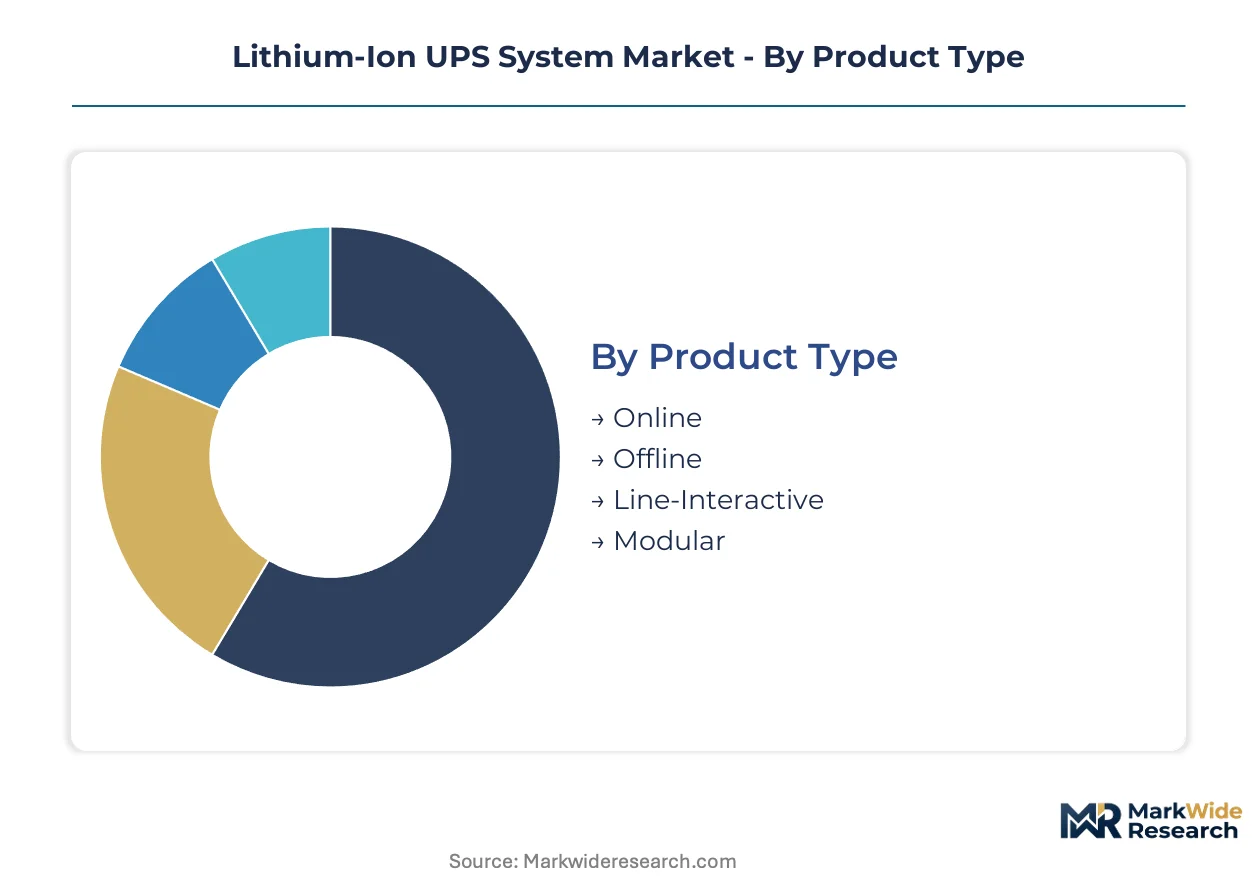
Segmentation in the lithium-ion UPS market determines which fire safety certifications apply, where engineering margins concentrate, and how vendors structure service contracts. Buyers select configurations based on transfer time tolerances, load criticality, and facility retrofit constraints rather than upfront cost alone.
Product Type:
Certification burdens diverge sharply across topologies, with online double-conversion systems facing UL 1778 and IEC 62040-3 validation cycles that offline units bypass entirely.
- Online:Continuous AC-DC-AC conversion eliminates transfer time and delivers harmonic filtering essential for hyperscale data center servers. Amazon Web Services and Microsoft Azure specify online topology in multi-megawatt procurement contracts, pulling Tier-1 vendors into 10-year service agreements.
- Modular:Hot-swappable 50-250 kW power modules enable capacity scaling without full system replacement, matching cloud workload variability. NFPA 855 factory-integrated enclosures dominate this segment as site-assembled configurations face extended fire suppression validation timelines.
- Offline:Standby operation switches to battery only during outages, sacrificing zero-transfer guarantees for 15-20% lower capital cost. Small retail and office deployments in cost-sensitive Indian and Southeast Asian markets absorb this trade-off.
- Line-Interactive:Voltage regulation through tap-changing transformers handles sags and surges without full conversion, suiting telecom base stations with moderate power quality tolerance. 5G infrastructure rollouts in China and Brazil drive procurement volumes.
Online systems sit at the top of the volume ranking, with modular configurations climbing the fastest as hyperscale operators prioritize scalable procurement.
End User:
Cost tiers separate mission-critical applications where downtime carries financial or human consequences from industrial settings where backup duration matters more than transfer speed.
- Data Centers:Hyperscale cloud campuses and colocation facilities demand 99.999% availability, driving specification of lithium iron phosphate chemistry with 15-year design life. NFPA 855 gas detection and aerosol suppression systems add $150,000-$400,000 per megawatt-hour, embedding fire engineering into total cost of ownership calculations.
- Telecommunications:5G base stations and central office switches require compact, thermally resilient units for outdoor cabinet deployment. China's MIIT mandates backup duration standards that favor lithium-ion energy density over legacy lead-acid footprints.
- Healthcare:MRI machines and surgical suites require UPS isolation from line disturbances per IEC 60601-1-2 medical device standards. EU MDR framework and FDA 510(k) pathways impose electromagnetic compatibility validation that extends product launch timelines.
- Industrial:Manufacturing lines and process control systems prioritize ride-through capability for voltage sags over harmonic precision. Legacy SCADA integration challenges compress margins on sub-100 kVA installations in facilities with 1990s-era building management systems.
Data centers command the highest absolute spending, with telecommunications expanding most quickly on 5G infrastructure deployment.
Deployment:
Customer type determines whether procurement flows through capital budgets, operating expenditure contracts, or managed service agreements with end-of-life recycling obligations.
- On-Premises:Enterprise-owned facilities in financial services and healthcare verticals retain direct control over critical power architecture. NFPA 855 compliance drives preference for factory-integrated UPS-battery enclosures with pre-validated thermal runaway containment.
- Edge:Distributed AI inference nodes and retail digitalization push compute closer to consumption points, requiring 5-20 kVA systems with integrated thermal management. Power-as-a-service contracting displaces capital purchase models, with Eaton and Schneider Electric structuring 7-10 year agreements bundling hardware, monitoring, and recycling.
- Cloud:Hyperscale operators specify remote monitoring APIs and 10-15 year design life as standard RFP terms, compressing vendor selection cycles around firmware subscription revenue rather than hardware replacement. Germany and France lead outsourcing adoption under energy-as-a-service regulatory frameworks.
- Hybrid:Mixed on-premises and colocation strategies split critical loads between owned facilities and third-party data centers, complicating unified monitoring and service dispatch logistics.
On-premises retains the largest installed base, with edge deployment gaining share fastest on distributed computing proliferation.
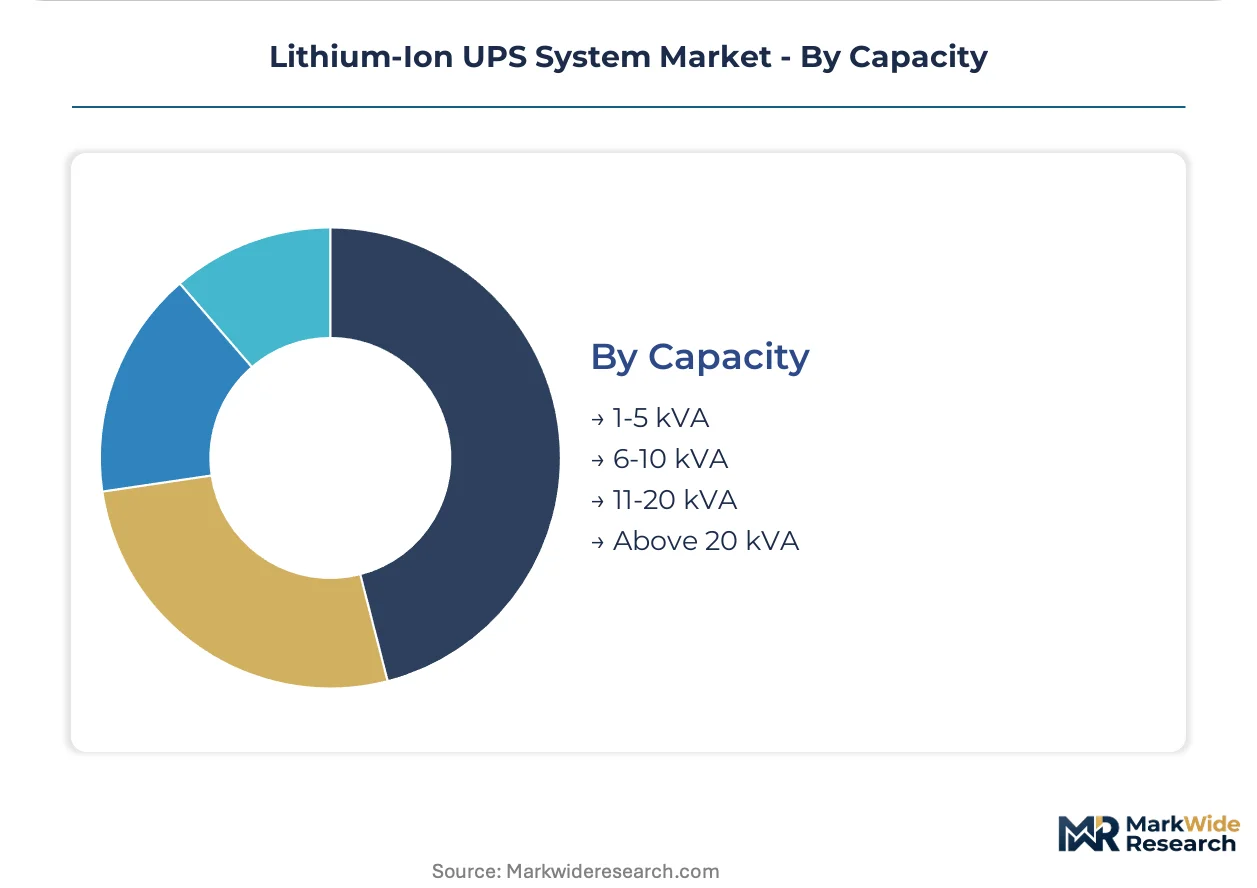
Capacity:
Supply concentration in cell-to-pack architectures from CATL and BYD collapses cost premiums most aggressively in mid-range bands where volume scale intersects with manageable fire suppression engineering.
- Above 20 kVA:Three-phase 380-480 V systems serve hyperscale data center halls and industrial process loads where engineering complexity and site-specific integration limit commoditization. Margin pools concentrate here as UL 9540A cell-level propagation testing demands 6-12 month validation cycles that few vendors possess in-house.
- 11-20 kVA:Small-to-medium data halls and telecom central offices balance scalability with footprint constraints. Lithium iron phosphate cell-to-pack architectures from Chinese suppliers collapse system-level cost premiums versus lead-acid to under 20% while delivering 3x cycle life.
- 6-10 kVA:Branch office servers and medical imaging equipment occupy a contested middle ground where lead-acid residual installed base creates procurement inertia. Approximately 40% of global UPS capacity in this band still runs on VRLA batteries with 3-5 year replacement cycles.
- 1-5 kVA:Desktop workstations and point-of-sale systems face extreme price sensitivity and limited fire suppression mandates below 50 kWh thresholds. EU Green Deal battery passport requirements above 2 kWh capacity push European procurement toward vendors with auditable mine-to-manufacturing records.
Above 20 kVA systems anchor revenue concentration, with 11-20 kVA bands expanding most quickly on lithium iron phosphate cost maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China outpaces the United States in hyperscale data center deployment velocity, while Germany enforces the strictest carbon disclosure standards for battery supply chains among major economies.
United States
Hyperscale cloud campuses in Northern Virginia, Dallas-Fort Worth, and Phoenix drive procurement volumes for megawatt-scale lithium-ion UPS systems. NFPA 855 mandates thermal runaway containment and gas detection for installations above 50 kWh, embedding fire suppression engineering into facility design specifications. Microsoft and Google pilot 1,500V DC architectures in new campuses, collapsing copper conductor mass through rack-level battery integration.
China
MIIT backup duration standards for 5G base stations favor lithium-ion energy density over legacy lead-acid footprints, accelerating fleet replacement across 3.7 million cellular sites. Dual carbon goals under the 14th Five-Year Plan impose carbon intensity benchmarks on data center power infrastructure. Yangtze River Delta hyperscale clusters in Shanghai and Jiangsu province concentrate procurement for cloud and AI training facilities.
Germany
Energy-as-a-service regulatory frameworks accelerate outsourcing of critical power infrastructure ownership to vendors bundling hardware, monitoring, and end-of-life recycling. EU Green Deal battery passport requirements enforce supply chain traceability and circularity obligations for systems placed on European markets. Frankfurt Rhine-Main data center cluster favors vendors with captive recycling partnerships and auditable mine-to-manufacturing records.
Japan
METI efficiency standards for data center power usage effectiveness elevate lithium-ion UPS specifications in Tokyo and Osaka metro facilities. JIS certification requirements for industrial battery systems extend product validation timelines compared to CE-marked equivalents. Kanto region hyperscale builds incorporate solid-state transformer pilots for medium-voltage DC distribution.
India
PLI scheme incentives for electronics manufacturing attract lithium-ion assembly investments serving domestic data center and telecom verticals. BIS safety standards for stationary battery systems tighten import requirements for non-certified equipment. Mumbai and Bangalore data center corridors drive above-20 kVA procurement as cloud operators expand local capacity.
Lithium-Ion UPS System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated power management vendors commanding premium positioning in hyperscale data center procurement while regional fabricators capture edge computing volumes through price-competitive modular offerings. The vendor base concentrates around three strategic archetypes: diversified electrical equipment conglomerates with captive battery supply chains, pure-play critical power specialists with firmware subscription revenue models, and Asian electronics manufacturers leveraging cell-to-pack cost advantages. Competitive dynamics revolve around M&A activity targeting fire safety engineering capabilities and strategic partnerships with CATL and BYD for lithium iron phosphate cell supply.
Among diversified electrical equipment conglomerates, Schneider Electric and Eaton Corporation exemplify the integrated solutions archetype, bundling lithium-ion UPS with thermal management and remote diagnostics through multi-year service agreements. Vertiv Group Corp. occupies a position within the pure-play critical power tier, differentiating through edge-computing configurations that consolidate power and thermal control. These three anchors represent distinct strategic postures: hardware-plus-services monetization, factory-integrated safety architecture, and distributed infrastructure specialization.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| Vertiv Group Corp. |
| Delta Electronics |
| ABB Ltd. |
| Emerson Electric Co. |
| Exide Industries |
| East Penn Manufacturing |
| GS Yuasa International Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud procurement mandating 10-15 year design life and remote monitoring APIs forces cell-to-pack architecture adoption, compressing vendor margins and collapsing cost premiums versus legacy lead-acid systems to under 20% at system level.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for lithium iron phosphate cell-to-pack systems. Three-tier pricing structure across premium, standard, and economy levels separates vendors with captive CATL and BYD supply agreements from merchant market dependent fabricators. Cost compression in the 11-20 kVA band is intensifying because Chinese suppliers deliver 3x cycle life at near-lead-acid economics. Small retail and office deployments in India and Southeast Asia absorb standby topology trade-offs, while hyperscale operators in Northern Virginia and Frankfurt Rhine-Main demonstrate minimal price sensitivity for factory-integrated NFPA 855 enclosures.
Supply Chain Analysis
Reverse-logistics flows for retired electric vehicle lithium-ion packs are entering stationary storage refurbishment pipelines, enabling UPS vendors to source cells at 30-40% of virgin material cost. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode active material supply drawing from Democratic Republic of Congo for cobalt and Indonesia for nickel. Single-source vulnerability in cobalt procurement exposes OEMs to ESG audit pressure under EU Green Deal battery passports. Distribution runs through direct enterprise sales for above-20 kVA systems and power-as-a-service contracting for edge deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal battery passport compliance costs in Germany and France exceed PLI scheme production incentives in India by substantial margins, redirecting vendor capital allocation toward traceability infrastructure.
For Market Incumbents: Lock in captive recycling partnerships and auditable mine-to-manufacturing records to defend against emerging pure-play critical power specialists with firmware subscription revenue models. Backward integration into lithium iron phosphate cell supply from CATL and BYD anchors cost position against merchant market dependent competitors. Factory-integrated NFPA 855 thermal runaway containment preserves margin pools in above-20 kVA installations where UL 9540A validation cycles limit new entrant participation. For New Entrants and Emerging Players: Enter via edge computing micro-UPS configurations requiring 5-20 kVA systems with integrated thermal management, where incumbent data center vendors maintain limited footprint. Distributed AI inference nodes in retail and manufacturing verticals offer the most penetrable white-space target. Power-as-a-service contracting with 7-10 year agreements bundling hardware, monitoring, and end-of-life recycling provides the strongest go-to-market angle against capital purchase inertia. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play critical power specialists possessing fire modeling capabilities and blockchain-anchored documentation platforms for EU battery passport compliance. Long-term viability over the next decade hinges on regulatory capture in traceability infrastructure rather than hardware scale alone. Fire safety engineering talent acquisition by diversified electrical equipment conglomerates signals consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU Battery Passport Compliance Platform | Blockchain-anchored documentation satisfies EU Green Deal traceability mandates for systems above 2 kWh. |
| Captive Lithium Iron Phosphate Supply Agreement | Cell-to-pack partnerships with CATL and BYD collapse cost premiums versus lead-acid to under 20%. |
| NFPA 855 Factory-Integrated Enclosure | Pre-validated thermal runaway containment accelerates procurement cycles for hyperscale cloud operators. |
| Power-as-a-Service Contracting Model | 7-10 year agreements bundling hardware and recycling displace capital purchases in Germany and France. |
| Second-Life Battery Integration Pipeline | Retired EV pack refurbishment enables 30-40% cell cost reduction for non-critical backup applications. |
Research Methodology
Bottom-up data center and telecommunications deployment modeling reconciled against top-down lithium-ion cell production tracking forms the analytical core of this study. Primary interviews with hyperscale facility engineers, fire safety consultants, procurement officers at colocation operators, and EPC contractors specialized in critical power infrastructure combined with secondary validation from MIIT backup duration standards, NFPA 855 code documentation, EU Green Deal regulatory filings, and hyperscaler capex disclosures. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of hyperscale cloud procurement patterns and lithium iron phosphate cost maturation curves informed projection assumptions across the analysis window. Segmentation dimensions modeled include product topology, end-use vertical, deployment configuration, and capacity band alongside regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for NFPA 855 compliance timeline acceleration and PLI scheme manufacturing incentives. Cell-to-pack architecture penetration and solid-state transformer pilot adoption served as key forecast inputs.
Inputs from NFPA technical committees and EU regulatory consultations were available through the study window; gaps in real-time hyperscale operator procurement data introduce uncertainty bands around edge deployment velocity estimates. Practitioners should monitor MIIT 5G infrastructure rollout announcements and UL 9540A validation cycle completion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Aluminium Ion Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Lithium-Ion Manganese Oxide Battery Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market