
 Lithium Manganate Battery Market | 2026-2036
Lithium Manganate Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Manganate Battery Market Insights
China's cathode material corridor is reshaping competitive dynamics in lithium manganate supply. CATL leverages integrated manganese sourcing to control feedstock costs across its Ningde production base. LG Energy Solution anchors premium automotive contracts through high-voltage lithium manganate formulations. Samsung SDI competes in European power tool segments with cylindrical cell designs that emphasize thermal stability.
Lithium manganate denotes a cathode material composed of lithium manganese oxide (LiMn₂O₄) with a spinel crystal structure, typically operating at nominal voltages near 3.7-4.0 V and valued for thermal stability and cost efficiency relative to nickel-cobalt alternatives. The material serves primarily as a power source for electric vehicles, grid storage systems, and portable electronics where safety tolerance outweighs energy density requirements. Standard lithium manganate dominates volume shipments for entry-level automotive packs, while high-performance lithium manganate captures margin pools in hybrid drivetrains requiring enhanced rate capability. Fast charge technology segments are gaining traction as cell makers optimize electrolyte additives to reduce manganese dissolution under elevated current loads.
China's NMPA enforces mandatory thermal runaway propagation testing for lithium manganate cells destined for passenger vehicles, while the EU Battery Regulation mandates carbon footprint disclosure and recycled content quotas that reshape material sourcing economics. Japan's METI has revised JIS standards for stationary storage batteries, tightening cycle life verification protocols that filter out lower-grade cathode suppliers. Stakeholders must monitor how divergent national certification timelines affect inventory positioning and plant qualification schedules.
Market Dynamics
China's cathode material corridor is compressing feedstock logistics costs while tightening certification timelines reshape inventory positioning across cell manufacturers. The concentration of manganese refining capacity in Jiangsu and Fujian provinces is forcing procurement officers to renegotiate long-term supply agreements ahead of NMPA thermal runaway testing deadlines.
Growth Catalysts
- EU Battery Regulation:Mandatory carbon footprint disclosure and recycled content quotas are redirecting cathode material sourcing toward certified green manganese suppliers in European automotive supply chains.
- Mid-range EV segment:Electric vehicle manufacturers are expanding lithium manganate procurement for passenger models where thermal stability tolerance outweighs energy density requirements.
- Fast charge electrolyte additives:Cell makers are optimizing formulations to reduce manganese dissolution under elevated current loads, unlocking new power tool and grid storage applications.
Market Restraints
- Manganese price volatility:Feedstock cost swings from South African and Gabonese mining operations destabilize cathode material pricing for non-integrated cell producers.
- Jiangsu-Fujian supply concentration:Overreliance on China's coastal cathode corridor creates single-point vulnerability for international battery assemblers.
- Nickel-cobalt substitution threat:High-nickel NMC formulations continue capturing premium automotive contracts where energy density dominates purchasing criteria.
Strategic Opportunities
- Stationary storage retrofit:Japan's METI-revised JIS cycle life standards are filtering out lower-grade suppliers, creating qualification gaps for certified lithium manganate providers.
- Hybrid drivetrain rate capability:High-performance lithium manganate formulations command margin pools in power-split hybrid systems requiring enhanced discharge rates.
- Direct cathode-to-cell integration:Co-located material plants and assembly facilities in Ningde-style industrial clusters are compressing working capital cycles for qualified entrants.
Industry Challenges
- Thermal runaway certification timelines:China's NMPA mandatory propagation testing protocols are extending plant qualification schedules and freezing inventory positions ahead of approval.
- Electrolyte additive IP complexity:Patent thickets around manganese dissolution inhibitors are forcing licensing negotiations that delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Manganate Battery Market |
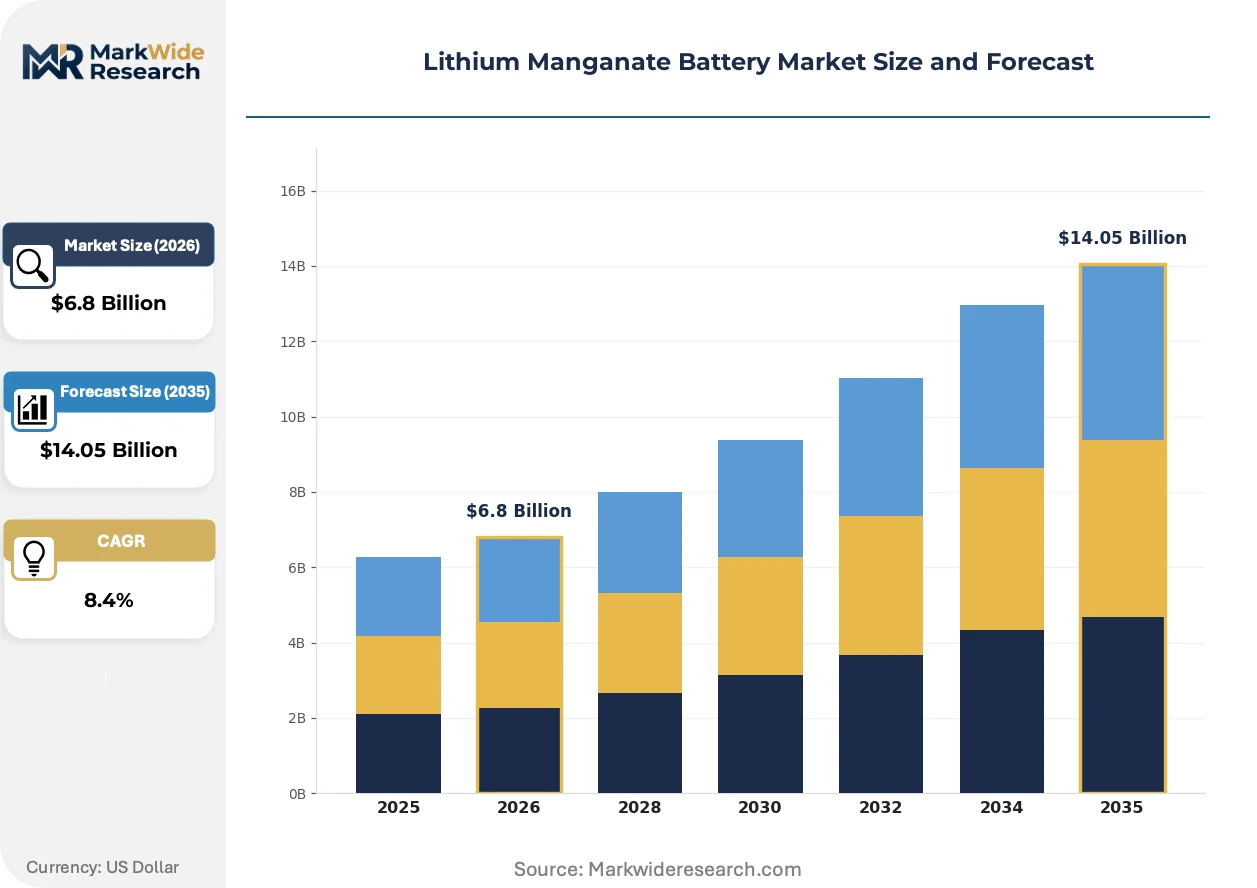
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Lithium Manganate, High-Performance Lithium Manganate, Rechargeable Lithium Manganate, Composite Lithium Manganate Industry Vertical: Automotive, Renewable Energy, Consumer Electronics, Aerospace Technology: Hybrid Technology, Fast Charge Technology, Power Management Technology, Battery Management Systems Capacity: Small Scale, Medium Scale, Large Scale, Ultra High Capacity |
| Companies Covered | Contemporary Amperex Technology Co., Limited (CATL), LG Energy Solution, Ltd., Panasonic Energy Co., Ltd., BYD Company Limited, Samsung SDI Co., Ltd., SK On Co., Ltd., Gotion High-tech Co., Ltd., CALB Group Co., Ltd., SVOLT Energy Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Manganate Battery Market Trends and Innovations
Digital twin simulation is virtualizing cell design validation workflows, compressing development cycles for lithium manganate formulations. Three distinct forces are reshaping how cathode materials advance from pilot production to scaled deployment.
Spinel-structure optimization software is virtualizing the traditional experimental screening of dopant combinations and coating architectures. Battery R&D teams at automotive OEMs are adopting these platforms to slash electrolyte-matching iterations from months to weeks. The technology is virtualizing physical prototyping requirements and reallocating capital toward high-throughput material synthesis equipment.
The EU Battery Regulation's carbon footprint disclosure mandates are forcing cathode suppliers to install blockchain-tracked material provenance systems. Industrial consequence includes mandatory third-party auditing of manganese mining emissions before cell assembly qualification. European power tool and e-bike segments are responding fastest, with procurement officers now rejecting uncertified material batches regardless of price competitiveness.
Cell makers are unbundling after-sales performance guarantees from hardware contracts, selling battery health monitoring as separate subscription services. This service-layer separation is disrupting traditional OEM-direct procurement channels and elevating fleet operators as primary decision-makers. The shift is most visible in China's electric bus and commercial van segments, where municipal tender documents now specify predictive maintenance APIs alongside cell specifications.
Lithium Manganate Battery Market Segmentation
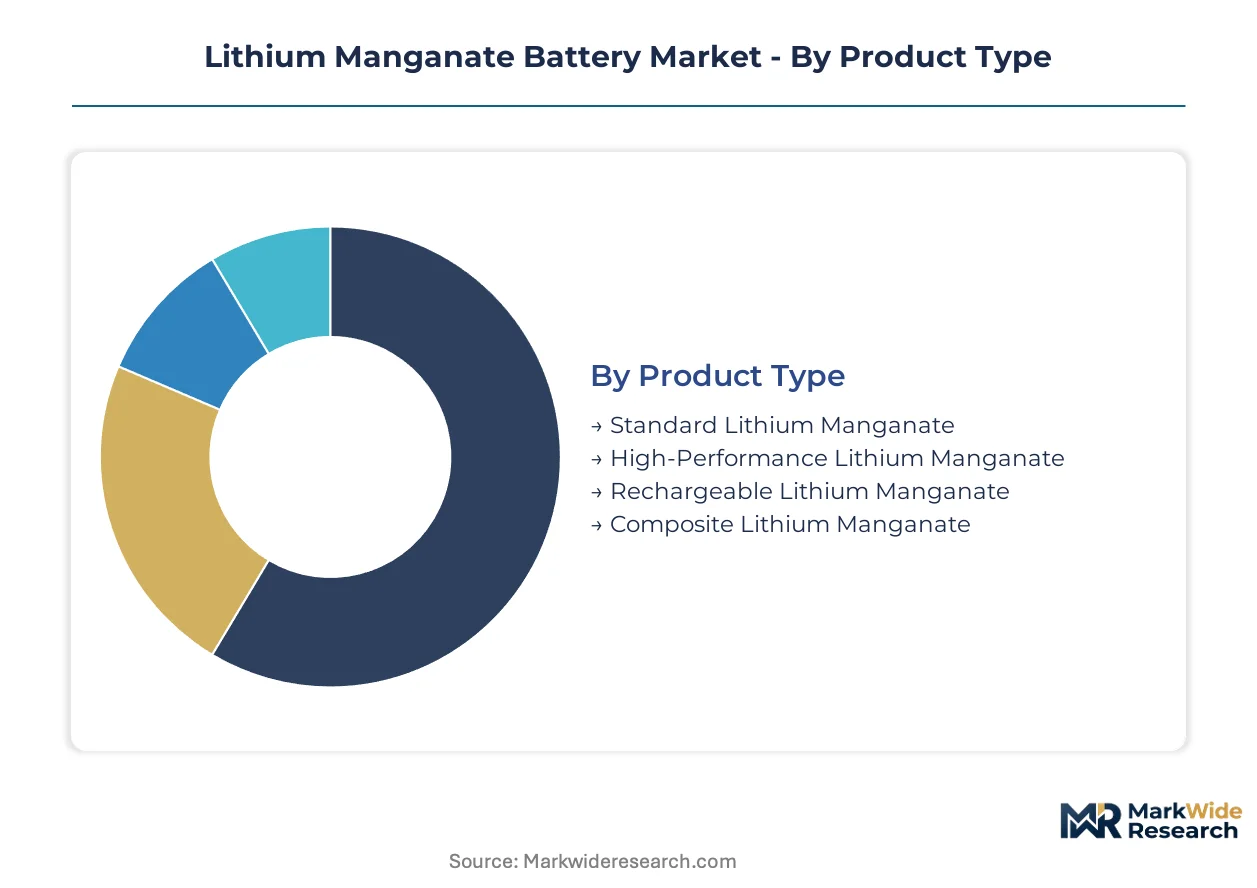
Segmentation in lithium manganate batteries determines procurement pathways, certification requirements, and after-sales service intensity. Each dimension shapes how cell makers configure warranty terms, predictive maintenance APIs, and fleet management subscriptions.
Product Type:
After-sales service intensity varies sharply across product tiers, with premium formulations commanding subscription-based health monitoring while standard grades rely on conventional warranty coverage.
- Standard Lithium Manganate:Entry-grade spinel cathodes with nominal 3.7V operation prioritize cost efficiency over energy density. Procurement concentrates in China's entry-level EV segment where NMPA thermal runaway testing mandates drive qualification costs upward for non-integrated suppliers.
- High-Performance Lithium Manganate:Doped spinel architectures with enhanced rate capability serve hybrid drivetrain applications. Demand clusters in Japan's power-split hybrid systems where METI-revised JIS cycle life standards filter out lower-grade competitors.
- Rechargeable Lithium Manganate:Cyclability-optimized formulations for portable electronics and light mobility.
- Composite Lithium Manganate:Blended cathode structures combining spinel with layered oxide components.
Standard lithium manganate holds the largest share; momentum sits with high-performance formulations.
Industry Vertical:
Application-driven cost tiers separate capital-intensive automotive contracts from price-sensitive consumer segments, reshaping how cell makers allocate R&D and qualification resources.
- Automotive:Passenger EV and commercial vehicle packs where thermal stability tolerance outweighs energy density requirements. Procurement expands for mid-range models across China's Jiangsu and Fujian production corridors.
- Renewable Energy:Grid-scale stationary storage systems requiring extended cycle life verification. Japan's METI standards tighten qualification protocols, creating entry barriers for uncertified suppliers.
- Consumer Electronics:Power tools and portable devices emphasizing cylindrical cell thermal stability.
- Aerospace:Niche applications with extreme safety margins and low volume requirements.
Automotive applications dominate volume; renewable energy storage represents the steepest expansion trajectory.
Technology:
Technology maturity determines margin structures, with established hybrid systems capturing stable returns while fast charge innovations require heavy electrolyte additive investment.
- Hybrid Technology:Power-split system integration optimized for discharge rate capability. Deployment concentrates in Japanese hybrid drivetrains where OEMs specify predictive maintenance APIs in procurement tenders.
- Fast Charge Technology:Electrolyte formulations reducing manganese dissolution under elevated current loads. Cell makers in China's Ningde-style clusters optimize additive combinations to unlock power tool and grid storage applications.
- Power Management Technology:Cell-level voltage and thermal regulation systems.
- Battery Management Systems:Pack-level monitoring and control electronics.
Hybrid technology holds the largest share; fast charge formulations are gaining share fastest.
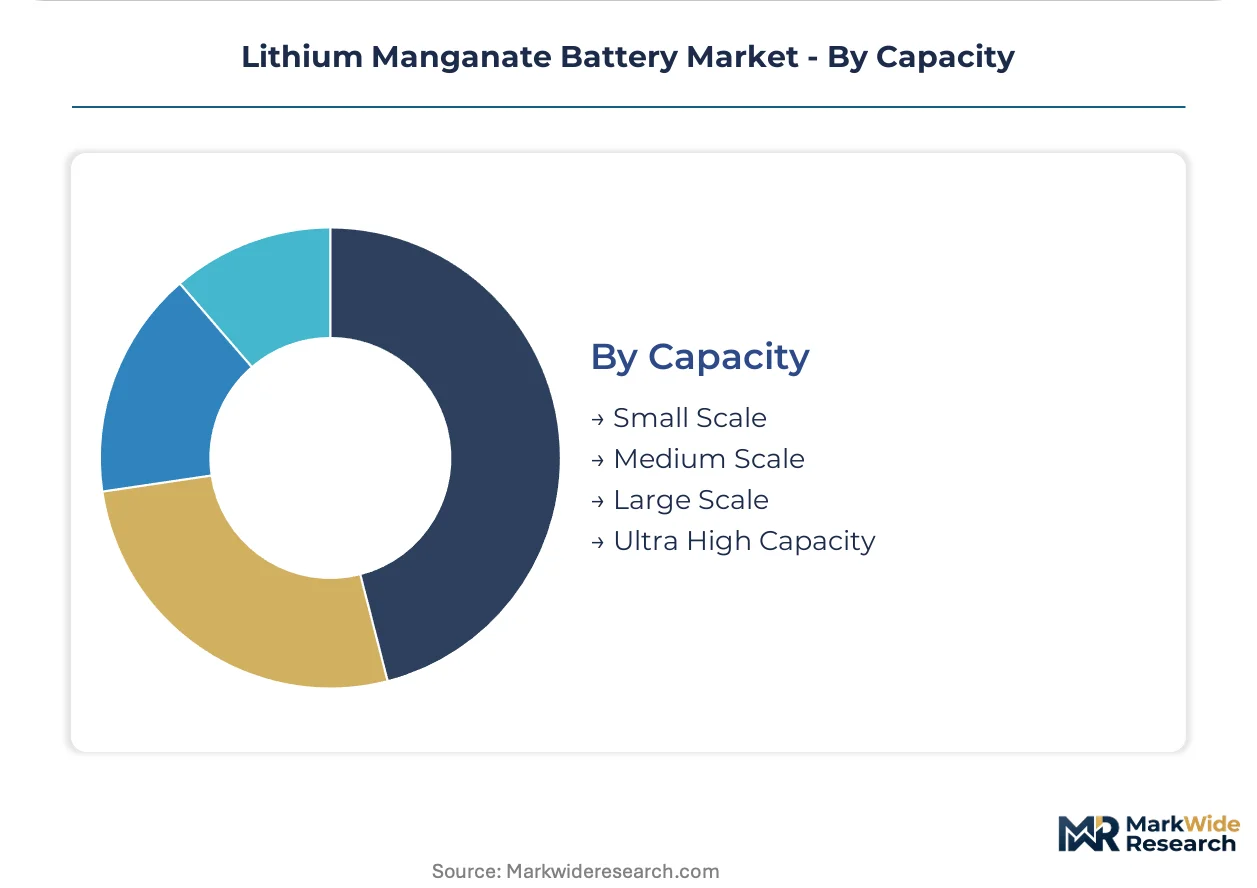
Capacity:
Scale-based customer segmentation separates municipal fleet operators with subscription-based procurement from individual consumers purchasing hardware-only contracts.
- Small Scale:Portable electronics and light power tools with cylindrical cell formats. European e-bike and power tool segments lead carbon footprint disclosure compliance under EU Battery Regulation mandates.
- Medium Scale:Commercial van and electric bus applications where China's municipal tenders specify predictive maintenance APIs alongside cell specifications.
- Large Scale:Passenger EV packs and stationary storage installations.
- Ultra High Capacity:Grid-scale and heavy commercial applications with extended warranty requirements.
Medium scale holds the largest share; small scale applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA thermal runaway testing protocols anchor China's dominant position in lithium manganate cell qualification. Manufacturing gravity clusters in coastal provinces where cathode material plants sit adjacent to cell assembly facilities.
China
Mid-range passenger EV procurement from BYD and Gotion High-tech drives lithium manganate demand across Jiangsu and Fujian provinces. NMPA mandates mandatory thermal runaway propagation testing for all cells entering passenger vehicle supply chains. The Ningde industrial cluster compresses working capital cycles through direct cathode-to-cell integration.
Japan
Power-split hybrid drivetrains from Toyota and Honda specify high-performance lithium manganate for enhanced rate capability. METI revised JIS standards for stationary storage batteries, tightening cycle life verification protocols. Kansai-based cell makers filter supplier qualifications through extended aging test requirements.
Germany
European automotive OEMs source lithium manganate for entry-level EV models where thermal stability outweighs energy density. The EU Battery Regulation mandates carbon footprint disclosure and recycled content quotas for all cell imports. Industrial demand concentrates in Baden-Württemberg where power tool manufacturers specify cylindrical cell formats.
South Korea
LG Energy Solution and Samsung SDI anchor premium automotive contracts through high-voltage lithium manganate formulations. MFDS aligns with EU-equivalent battery safety standards for export qualification. Production clusters in the Seoul Capital Area link cathode material refining to cell assembly through captive supply arrangements.
United States
Grid storage developers specify lithium manganate for stationary applications requiring extended cycle life. NHTSA and FERC guidelines influence safety documentation for utility-scale battery installations. The Pacific Northwest hosts pilot manufacturing lines testing fast-charge electrolyte formulations for power tool segments.
Lithium Manganate Battery Market Competitive Landscape
Capability concentration sits with integrated cathode producers; scale advantage sits with diversified cell manufacturers. The market structures around three tiers: integrated material-cell producers, specialized high-voltage formulators, and regional cylindrical cell specialists. Strategic archetypes include backward-integrated manganese controllers, premium automotive contract holders, and thermal stability-focused power tool suppliers. Dominant competitive moves encompass co-location of cathode plants with cell assembly facilities and electrolyte additive IP licensing negotiations.
Among China-based integrated producers, Contemporary Amperex Technology Co., Limited exemplifies the backward-integrated archetype through captive manganese sourcing. LG Energy Solution, Ltd. and Samsung SDI Co., Ltd. represent the premium-tier automotive contract model, occupying positions where high-voltage formulations command pricing power. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning within lithium manganate supply chains.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited (CATL) |
| LG Energy Solution, Ltd. |
| Panasonic Energy Co., Ltd. |
| BYD Company Limited |
| Samsung SDI Co., Ltd. |
| SK On Co., Ltd. |
| Gotion High-tech Co., Ltd. |
| CALB Group Co., Ltd. |
| SVOLT Energy Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Regulatory chokepoint concentration around NMPA thermal runaway certification timelines determines both pricing tier spreads and supply chain shape. Buyers face extended qualification schedules that freeze working capital, while sellers leverage certification scarcity to sustain margin premiums across standard and high-performance lithium manganate grades.
Pricing Analysis
Geographic price spreads between China's Jiangsu-Fujian corridor and European automotive buyers reflect contract-based long-term offtake structures with embedded carbon footprint premiums. Price differentiation separates NMPA-certified cells from uncertified alternatives, with volume scale and vertical integration status as secondary tiering factors. Cost compression in standard-grade formulations is intensifying because manganese feedstock volatility from South African and Gabonese mining operations destabilizes non-integrated producers. Municipal fleet operators in China's electric bus segment exhibit lowest price sensitivity due to bundled predictive maintenance subscriptions, while European power tool OEMs demonstrate highest sensitivity to uncertified material batches.
Supply Chain Analysis
Extended payment terms from cathode material plants to manganese refiners anchor supplier-financing dynamics across China's coastal production corridor. Geographic supply concentration centers on China, South Korea, and Japan, with raw material dependencies on manganese ore from South Africa and Gabon, electrolyte salts from domestic Chinese refiners, and separator membranes from Japanese suppliers. Single-source vulnerability runs through the Jiangsu-Fujian cathode corridor where NMPA qualification bottlenecks create inventory freeze risks. Distribution runs through direct cathode-to-cell integration in Ningde-style industrial clusters, bypassing traditional merchant material markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around municipal fleet operators and European automotive OEMs with carbon disclosure mandates, fragmenting traditional cell maker pricing authority. This shift rewards suppliers with certified green material pipelines and penalizes non-integrated competitors.
For Market Incumbents: Build electrolyte additive IP moats through licensing negotiations around manganese dissolution inhibitors. Secure backward integration into captive manganese refining in Jiangsu and Fujian provinces to neutralize feedstock volatility exposure. Defend against nickel-cobalt substitution threats by anchoring premium automotive contracts through high-voltage formulation roadmaps aligned with NMPA thermal stability requirements. For New Entrants and Emerging Players: Establish a beachhead in Japan's stationary storage retrofit segment where METI-revised JIS cycle life standards filter out incumbent suppliers. Target European power tool and e-bike segments with blockchain-tracked green manganese certification as the fastest-penetrable white space. Pursue co-location partnerships with Ningde-style industrial clusters to compress working capital cycles and bypass merchant cathode markets. For Investors and Strategic Acquirers: The market sits at a certification-scarcity phase that favors backward-integrated material producers with NMPA qualification pipelines. Long-term viability across the five-to-ten year window rests on control over green manganese sourcing and electrolyte additive patent positions. Acquisition targets should display direct cathode-to-cell integration capabilities and established thermal runaway testing protocols. Watch for NMPA approval timeline acceleration as the inflection signal that would compress qualification premiums and shift returns toward scale-efficient assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Cathode-to-Cell Integration | Ningde-style industrial clusters compress working capital cycles for qualified entrants. |
| Green Manganese Certification Program | EU Battery Regulation carbon disclosure mandates redirect procurement toward blockchain-tracked suppliers. |
| Electrolyte Additive IP Licensing | Patent positions around manganese dissolution inhibitors determine fast-charge market access. |
| NMPA Thermal Runaway Qualification | Mandatory propagation testing protocols anchor China's dominant cell certification position. |
| Hybrid Drivetrain Rate Capability Investment | Toyota and Honda procurement specifications reward high-performance spinel formulation development. |
Research Methodology
A standing panel of cathode plant operations directors, automotive OEM procurement leads, NMPA regulatory affairs specialists, and manganese trading desk analysts provided ongoing calibration throughout the study. Primary interviews with cell maker R&D directors and stationary storage project developers were cross-referenced against secondary validation from customs filings, MIIT production statistics, METI JIS standard revisions, and EU Battery Regulation implementation guidance. Bottom-up volume estimates from individual cathode material plants were reconciled with top-down automotive and grid storage demand projections.
Scenario-bracketing around manganese price volatility bands, NMPA certification timeline distributions, and nickel-cobalt substitution elasticity shaped the analytical framework across the modeling period. Segmentation dimensions included product type tier, industry vertical application, technology maturity stage, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to observed procurement expansion rates and plant capacity commissioning schedules. Forecast inputs incorporated electrolyte additive commercialization timelines and thermal runaway testing protocol evolution.
Stress conditions across South African manganese supply disruptions, NMPA approval backlog scenarios, and EU carbon border adjustment implementations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cathode material corridor concentration and hybrid drivetrain specification stability. Macroeconomic commodity shock, regulatory timeline compression, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market