
 US Electrosurgical Generators Market | 2026-2036
US Electrosurgical Generators Market Size, Share, and Industry Trends Forecast 2026-2036
US Electrosurgical Generators Market Analysis
Hospital procurement consolidation across integrated delivery networks is rebalancing vendor negotiation leverage in the US electrosurgical generators space. Medtronic leverages its broad energy platform portfolio to sustain multi-site contract wins. Stryker anchors its position through differentiated advanced energy systems for minimally invasive procedures. Johnson & Johnson competes via Ethicon's specialized vessel sealing technology leadership.
US electrosurgical generators are precision power delivery instruments that convert electrical current into controlled thermal energy at frequencies between 300 kHz and 3 MHz, enabling tissue cutting and coagulation during surgical intervention. These systems incorporate isolated output circuitry, return electrode monitoring, and adaptive impedance feedback to maintain consistent energy delivery across varying tissue conditions. Hybrid generators command premium positioning by combining monopolar and bipolar modalities within single platforms, while radiofrequency technology segments expand fastest as surgeons adopt impedance-controlled tissue ablation for orthopedic and cosmetic applications. Monopolar systems retain volume dominance in general surgery suites, though bipolar configurations capture margin pools in gynecological procedures requiring targeted hemostasis.
FDA 510(k) premarket notification requirements and IEC 60601-1 medical electrical safety standards govern device commercialization, creating compliance barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. The Centers for Medicare & Medicaid Services reimbursement frameworks for outpatient surgical procedures directly influence hospital capital equipment refresh cycles. State-level certificate-of-need regulations in jurisdictions like New York and Illinois constrain ambulatory center expansion, redirecting generator demand toward existing hospital infrastructure. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications for generator-integrated energy algorithms.
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is rebalancing vendor negotiation leverage, compressing contract margins while elevating multi-year service agreements as competitive differentiators for electrosurgical platform suppliers.
Growth Catalysts
- Ambulatory surgical center expansion:Certificate-of-need liberalization in Texas, Florida, and Arizona permits freestanding facility development, redirecting capital equipment procurement toward outpatient surgical corridors.
- FDA 510(k) clearance efficiency:Predicate device pathways for generator software updates accelerate iterative product improvement cycles without requiring full premarket approval submissions.
- Radiofrequency ablation adoption:Orthopedic and cosmetic surgery practices integrate impedance-controlled tissue ablation into procedural portfolios, expanding addressable generator applications beyond traditional cutting and coagulation.
Market Restraints
- Copper and semiconductor input volatility:Isolated output transformer and power MOSFET supply chains face pricing pressure from electronics manufacturing demand surges, squeezing hardware margins.
- IEC 60601-1-2 electromagnetic compatibility testing:Evolving immunity standards for surgical environments force redundant validation cycles, extending product launch timelines by 8-14 months for firmware-intensive platforms.
- Reusable electrode substitution:Single-use disposable pencil and forceps systems capture procedural volume in infection-sensitive settings, constraining generator attachment revenue streams.
Strategic Opportunities
- AI-integrated energy algorithms:Software-as-medical-device classifications under evolving FDA guidance create pathways for predictive tissue response modeling that differentiates premium generator tiers.
- Veterans Affairs integrated network procurement:Consolidated federal healthcare purchasing across VA medical centers offers multi-site deployment contracts with standardized service protocols.
- Hybrid modality platform development:Convergence of monopolar cutting precision with bipolar vessel sealing within single-generator architectures commands pricing premiums in minimally invasive surgery suites.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in high-frequency power electronics and surgical safety interlocks concentrates among legacy manufacturers, constraining startup R&D velocity.
- Legacy system integration complexity:Hospital OR infrastructure with decade-old electrosurgical units requires backward-compatible connectivity protocols, fragmenting software development resources across multiple hardware generations.
- Service technician certification bottlenecks:Manufacturer-authorized repair training programs limit third-party maintenance competition, extending equipment downtime during warranty transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electrosurgical Generators Market |
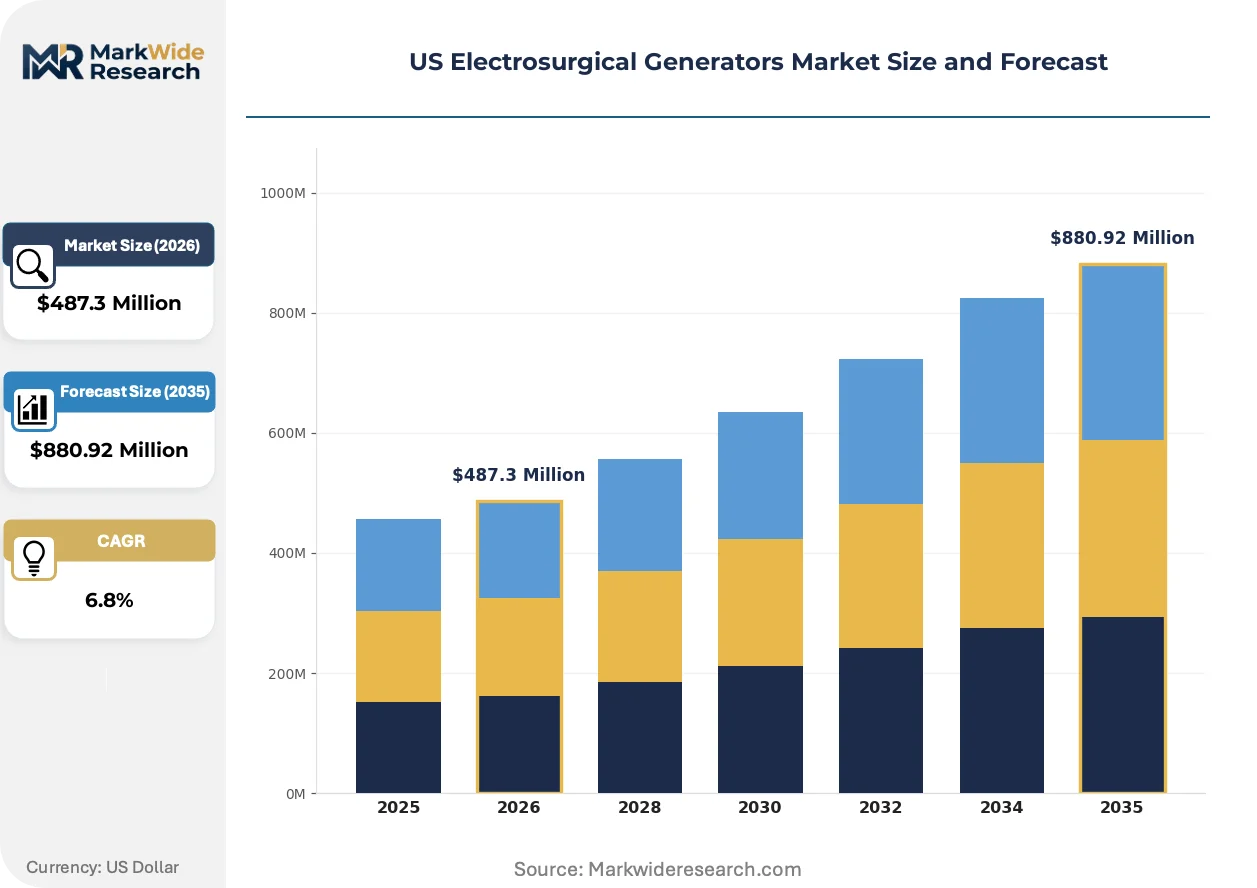
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Generators, Coagulation Generators, Hybrid Generators, Pencil Generators End User: Hospitals, Surgical Centers, Ambulatory Care Centers, Clinics Technology: Monopolar, Bipolar, Thermal, Radiofrequency Application: General Surgery, Gynecological Surgery, Orthopedic Surgery, Cosmetic Surgery |
| Companies Covered | CONMED Corporation, Integra LifeSciences, Medtronic, Stryker, B. Braun, Johnson & Johnson, Ethicon, Boston Scientific Corporation, Olympus Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electrosurgical Generators Market Emerging Trajectories
Radiofrequency energy delivery architectures are fragmenting into application-specific configurations, with impedance feedback loops and adaptive power modulation becoming baseline expectations rather than premium features across surgical specialties.
Generator hardware is modularizing around swappable radiofrequency output modules that permit intraoperative switching between cutting, coagulation, and vessel sealing modes without auxiliary equipment swaps. Ambulatory surgery centers in the Southeast and Southwest are adopting these platforms fastest, driven by space constraints and multi-specialty scheduling density. This modularity is compressing capital expenditure recovery timelines by enabling single-generator deployment across previously segregated service lines.
FDA software-as-medical-device guidance revisions are tightening validation requirements for energy algorithms that adjust output based on real-time tissue impedance measurements. Manufacturers must now document clinical performance across anatomical sites rather than generic soft-tissue models, elevating regulatory affairs staffing levels. Class II device submissions with AI-integrated feedback systems face extended review cycles, favoring established players with dedicated 510(k) predicate libraries.
Hospital procurement committees are consolidating electrosurgical platform decisions at integrated delivery network headquarters rather than individual facility levels, centralizing vendor negotiations and standardizing equipment fleets across 15-40 hospital systems. This concentration is displacing distributor-mediated sales relationships in favor of direct manufacturer contracting with enterprise-level service commitments. The shift is most visible in California and Illinois health systems, where IDN consolidation has advanced furthest.
US Electrosurgical Generators Market Segmentation
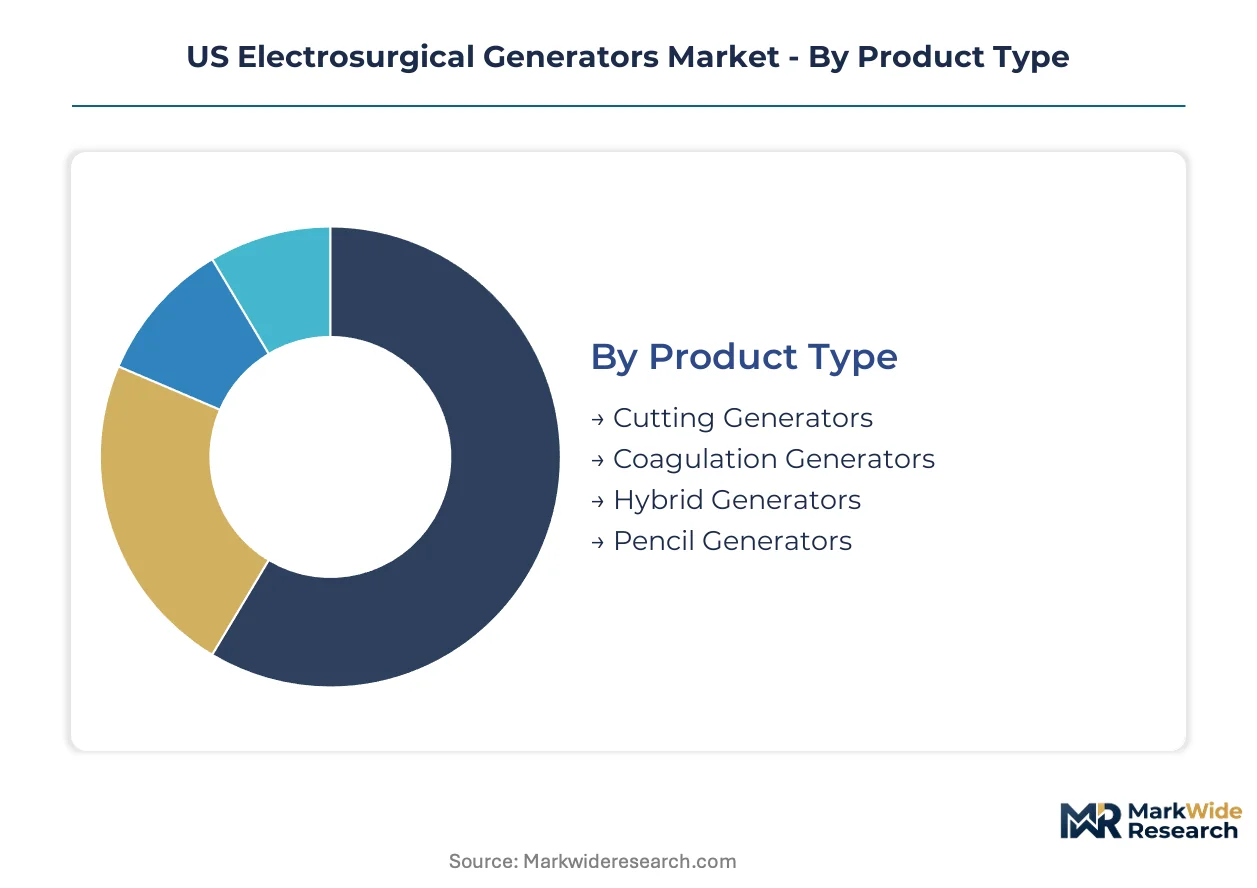
Electrosurgical generator segmentation reveals distinct procurement patterns across facility types and procedural requirements. Product architecture, energy delivery modality, and surgical application each create separate margin pools and competitive battlegrounds for manufacturers.
Product Type:
Standalone generators dominate capital budgets in high-volume surgical suites, while embedded systems integrate into robotic platforms and specialized workstations.
- Cutting Generators:High-frequency output circuits between 300-500 kHz deliver precise tissue incision with minimal thermal spread. General surgery departments in Texas and California hospital systems prioritize these units for open procedure throughput. Copper transformer costs and semiconductor supply constraints squeeze hardware margins on entry-tier models.
- Hybrid Generators:Dual-modality architectures combine monopolar cutting precision with bipolar vessel sealing within single platforms, commanding pricing premiums in minimally invasive surgery suites. Ambulatory surgical centers in Florida and Arizona adopt these fastest due to space constraints and multi-specialty scheduling density.
- Coagulation Generators:Lower-frequency modulation circuits optimized for hemostasis control in vascular tissue beds.
- Pencil Generators:Compact handheld units with integrated activation switches for physician-directed energy delivery.
Volume placements concentrate in Cutting Generators; the faster expansion belongs to Hybrid Generators.
End User:
Procurement authority is migrating toward centralized purchasing committees, reshaping vendor relationships across facility tiers.
- Hospitals:Integrated delivery networks in California, Illinois, and New York consolidate fleet standardization decisions at headquarters level, displacing distributor-mediated sales. Multi-year service agreements and enterprise-level maintenance protocols now outweigh upfront equipment pricing in vendor selection criteria. Certificate-of-need regulations in certain states constrain capital refresh cycles.
- Ambulatory Care Centers:Freestanding facilities in Texas, Florida, and Arizona drive procurement growth following CON liberalization. These centers prioritize compact hybrid platforms with rapid modality switching to maximize procedure throughput per square foot.
- Surgical Centers:Multi-specialty outpatient facilities with scheduled procedure blocks.
- Clinics:Limited-procedure settings with basic cutting and coagulation requirements.
Hospital procurement retains the largest installed base; ambulatory care centers are climbing the fastest.
Technology:
Energy delivery architectures fragment into impedance-controlled configurations with distinct safety interlock requirements.
- Monopolar:Current flows from active electrode through patient to return electrode plate, enabling deep tissue penetration for open surgical procedures. General surgery suites retain volume dominance despite thermal spread limitations. Isolated output circuitry and return electrode monitoring systems add regulatory compliance complexity.
- Radiofrequency:Impedance feedback loops and adaptive power modulation enable controlled tissue ablation for orthopedic and cosmetic applications. This segment is expanding most quickly as surgeons adopt ablation for joint procedures and dermatological resurfacing outside traditional cutting contexts.
- Bipolar:Current confined between instrument jaws reduces thermal damage to adjacent tissue.
- Thermal:Direct resistive heating elements for localized tissue effect without high-frequency current.
Monopolar systems hold the greatest procedural volume; radiofrequency platforms show the steepest expansion trajectory.
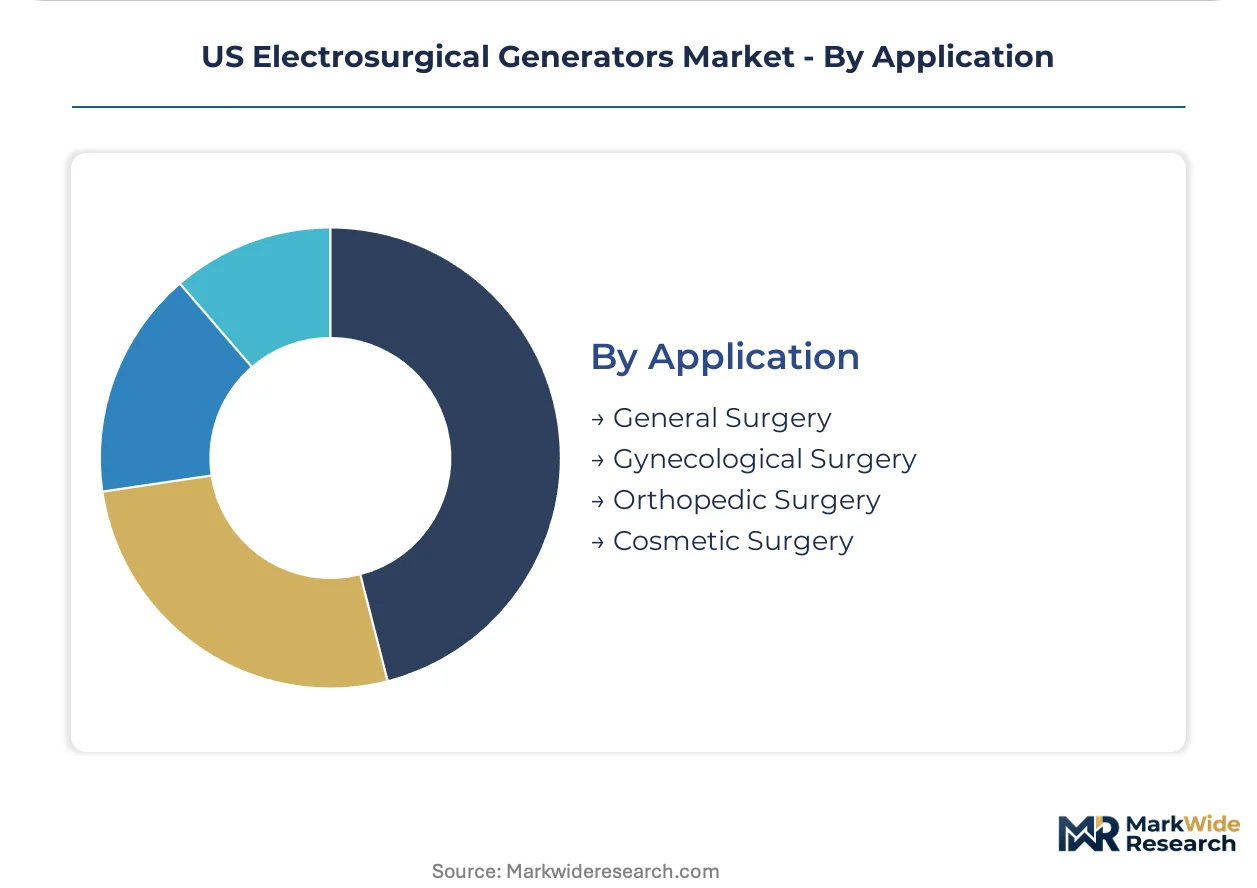
Application:
Surgical specialty requirements drive divergent specifications for energy precision, thermal spread control, and procedure duration.
- General Surgery:Open and laparoscopic procedures requiring both rapid cutting and reliable hemostasis across varied tissue densities. Hospital systems in surgical corridors prioritize generator uptime and service response guarantees over feature differentiation.
- Cosmetic Surgery:Radiofrequency ablation and precise thermal control for dermatological and aesthetic procedures. Outpatient practices in Florida and California integrate these applications fastest, expanding addressable generator demand beyond traditional surgical domains.
- Gynecological Surgery:Bipolar-dominant procedures requiring targeted vessel sealing.
- Orthopedic Surgery:Tissue ablation and hemostasis in joint and spine procedures.
General Surgery accounts for the deepest installed base; Cosmetic Surgery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement concentration across integrated delivery networks concentrates demand in Texas, California, and Florida surgical corridors. Ambulatory surgical centers in Arizona and the Southeast are expanding fastest following certificate-of-need liberalization.
Texas
Freestanding ambulatory surgical centers in Dallas-Fort Worth and Houston drive hybrid generator procurement following CON deregulation. FDA 510(k) clearance pathways enable rapid deployment of impedance-controlled platforms. The Texas Medical Center anchors multi-site standardization contracts with enterprise-level service commitments.
California
Integrated delivery networks in Los Angeles and San Francisco Bay Area consolidate fleet decisions at headquarters level, displacing distributor relationships. IEC 60601-1-2 electromagnetic compatibility standards force redundant validation cycles for firmware-intensive systems. Stanford and Cedars-Sinai health systems pioneer AI-integrated energy algorithm adoption.
Florida
Cosmetic surgery practices in Miami and Tampa integrate radiofrequency ablation into dermatological portfolios, expanding addressable applications. State-level outpatient reimbursement frameworks from CMS influence capital equipment refresh cycles. The I-4 corridor concentrates multi-specialty ambulatory center development with space-constrained hybrid platform demand.
Arizona
Phoenix and Tucson surgical corridors prioritize compact hybrid generators with rapid modality switching for procedure throughput maximization. CON liberalization permits greenfield ambulatory facility development redirecting procurement from hospital infrastructure. Banner Health and HonorHealth systems standardize equipment fleets across 15-plus facilities.
Illinois
Certificate-of-need regulations in Chicago and Cook County constrain ambulatory expansion, maintaining hospital-centric demand. CMS reimbursement frameworks for inpatient procedures sustain longer capital refresh cycles. Northwestern Medicine and Advocate Aurora anchor integrated network procurement with multi-year maintenance protocols.
US Electrosurgical Generators Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software-as-medical-device classifications for algorithmic differentiation. The vendor base concentrates among diversified medical technology conglomerates with dedicated regulatory affairs infrastructure. Three archetypes dominate: diversified energy platform suppliers, specialized vessel sealing technology developers, and surgical visualization integrators. Competitive moves center on multi-site contract consolidation and AI-integrated feedback system development.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Johnson & Johnson exemplify distinct positioning vectors. Medtronic represents the broad energy platform archetype with multi-specialty coverage. Stryker occupies the advanced energy systems position for minimally invasive applications. Johnson & Johnson anchors specialized vessel sealing technology leadership through its Ethicon subsidiary. These three conglomerates sit within the premium service tier where enterprise-level maintenance commitments outweigh upfront equipment pricing in vendor selection criteria.
| Leading Market Players |
|---|
| CONMED Corporation |
| Integra LifeSciences |
| Medtronic |
| Stryker |
| B. Braun |
| Johnson & Johnson |
| Ethicon |
| Boston Scientific Corporation |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up distributors across the US electrosurgical generator channel exercise pricing discipline through centralized procurement mandates, compressing margins for manufacturers while amplifying volume commitments that secure preferential transformer and semiconductor allocations from Asian foundries.
Pricing Analysis
Volume placements concentrate in standard-tier cutting generators while hybrid platforms capture margin premiums through dual-modality architectures. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated systems with predictive tissue modeling from basic impedance-feedback units and entry-level hardware. Pricing pressure stems from copper and power MOSFET input volatility squeezing hardware margins on economy-tier models. Ambulatory surgical centers exhibit highest price sensitivity due to capital expenditure recovery timelines, whereas integrated delivery networks prioritize enterprise service commitments over upfront equipment costs.
Supply Chain Analysis
Biomedical engineering talent scarcity in Massachusetts and Minnesota manufacturing clusters constrains domestic production scaling for firmware-intensive platforms. Isolated output transformers and power MOSFETs draw from Taiwan, China, and South Korean semiconductor foundries, while precision-wound copper components source from Mexican and domestic wire suppliers. Single-source vulnerability in advanced RF module fabrication elevates risk exposure for iterative product launches. Distribution runs through manufacturer-direct contracting with IDN headquarters, displacing traditional distributor-mediated relationships in California and Illinois health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US electrosurgical generator supply is tightening around specialized high-frequency power electronics expertise, with biomedical engineering talent scarcity propping pricing for AI-integrated platforms above standard hardware tiers.
For Market Incumbents: Extend service agreement differentiation through predictive maintenance algorithms and rapid-response technician networks to counter emerging software-as-medical-device entrants. Deepen backward integration into RF module design to reduce Taiwan foundry dependency. Fortify FDA 510(k) predicate libraries to accelerate clearance cycles for iterative energy algorithm improvements.
For New Entrants and Emerging Players: The price-point gap between premium hybrid generators and economy-tier cutting units offers white-space entry through mid-market platforms with modular RF output modules. Target Arizona and Florida ambulatory surgical centers with space-constrained, multi-specialty scheduling requirements. Pursue VA integrated network procurement standardization as a reference customer pathway.
For Investors and Strategic Acquirers: Distressed-cycle entries favor software-as-medical-device specialists with FDA clearance momentum in California regulatory corridors. Long-term viability over a 5-10 year window hinges on AI-integrated energy algorithm differentiation as impedance-controlled tissue ablation expands beyond traditional surgical applications. Watch for FDA guidance finalization on software-as-medical-device classifications as inflection signal for valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Update Pathway | Accelerates iterative energy algorithm deployment without full premarket approval submissions. |
| Hybrid Modality Platform Development | Combines monopolar cutting with bipolar vessel sealing to capture premium pricing in minimally invasive suites. |
| VA Integrated Network Procurement | Secures multi-site deployment contracts with standardized federal maintenance protocols. |
| AI-Integrated Energy Algorithm Investment | Differentiates premium tiers through predictive tissue response modeling under evolving FDA guidance. |
| Biomedical Engineering Talent Acquisition | Addresses specialized expertise scarcity constraining startup R&D velocity and firmware development. |
Methodological Framework
Independent corroboration across hospital procurement databases, GPO contract filings, and FDA 510(k) clearance records underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and ambulatory surgical center administrators combined with secondary validation from CMS reimbursement frameworks, IEC electromagnetic compatibility standards documentation, and state-level certificate-of-need regulatory filings. Bottom-up facility-level demand estimates and top-down market sizing triangulate volume and value outputs.
Comparable-period anchoring to historical capital equipment refresh cycles and ambulatory surgical center expansion trajectories structured the forecast window across the projection horizon. Segmentation modeling incorporated product architecture, energy delivery modality, surgical application, and facility type dimensions. CAGRs were derived from trend extrapolation of procurement patterns and technology adoption curves, with inputs from copper and semiconductor pricing indices, reimbursement framework evolution, and regulatory clearance timeline data.
Inputs from hospital procurement databases and FDA clearance records were available through the study window; gaps in real-time ambulatory surgical center equipment deployment data introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding CON liberalization continuation, IEC standard evolution timelines, and software-as-medical-device classification guidance finalization. Material deviation in FDA regulatory trajectory, copper and semiconductor supply disruptions, or Medicare reimbursement framework restructuring warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Netherlands Respiratory Devices Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Pannus Retraction Device Market