
 Electrosurgical Generators Market | 2026-2036
Electrosurgical Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Electrosurgical Generators Market Analysis
Platform bundling of electrosurgical generators with proprietary electrode systems and smoke evacuation hardware is hardening procurement patterns across hospital networks. Medtronic leverages its integrated surgical ecosystem to lock in long-term supply agreements with large health systems. Johnson & Johnson anchors its market presence through broad electrosurgery portfolios spanning open and laparoscopic applications. Erbe Elektromedizin specializes in precision radiofrequency platforms that dominate European surgical suites.
Electrosurgical generators are high-frequency electrical devices that deliver controlled thermal energy to cut, coagulate, or ablate tissue during surgical procedures, typically operating at frequencies between 300 kHz and 3 MHz to avoid neuromuscular stimulation while enabling precise tissue effect. Their primary purpose is to replace mechanical scalpels in both open and minimally invasive surgery, reducing blood loss and operative time across general, gynecological, and specialty procedures. Multifunctional generators now command the strongest margin pools as surgeons demand seamless switching between cutting and coagulation modes within single procedures. Radiofrequency technology leads volume shipments while bipolar configurations capture expanding share in delicate microsurgical applications where thermal spread must be minimized.
FDA 510(k) premarket notification requirements shape device design standards and commercialization timelines for manufacturers targeting the United States, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for electrosurgical platform approvals across European markets. ISO 60601-2-2 safety standards govern electromagnetic compatibility and patient leakage current limits, directly influencing generator architecture and testing protocols. Stakeholders must monitor evolving reimbursement codes for outpatient electrosurgical procedures as site-of-care shifts accelerate capital allocation decisions.
Market Dynamics
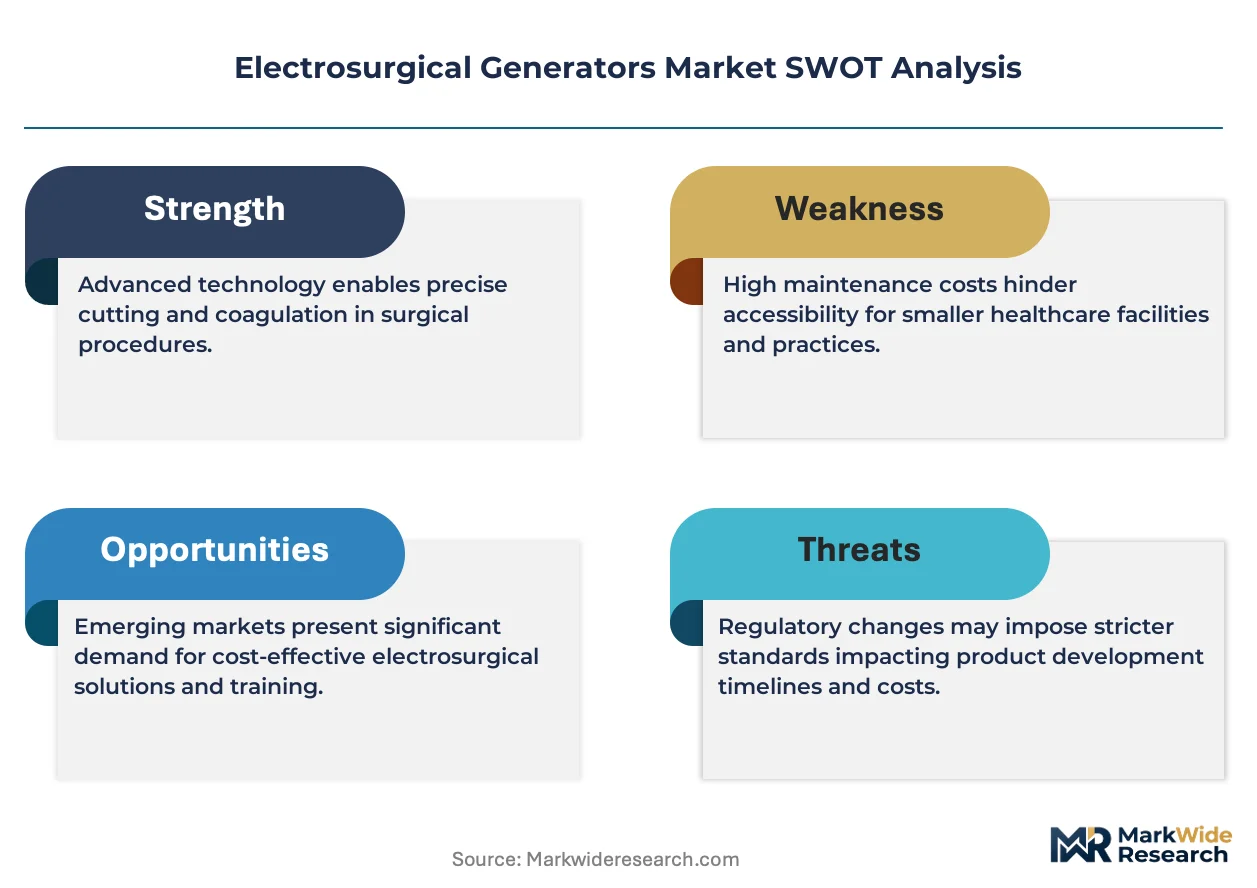
Platform bundling of electrosurgical generators with proprietary electrode systems and smoke evacuation hardware is hardening procurement patterns across hospital networks, locking buyers into integrated surgical ecosystems and compressing vendor switching flexibility.
Growth Catalysts
- Ambulatory surgical center expansion:United States outpatient procedural volumes continue rising, driving compact electrosurgical platform procurement as site-of-care shifts accelerate capital allocation toward smaller-footprint systems.
- FDA 510(k) clearance pathway:The streamlined premarket notification process accelerates product commercialization timelines for manufacturers targeting the United States, reducing regulatory friction relative to European MDR pathways.
- Radiofrequency technology advancement:Precision RF platforms now enable seamless switching between cutting and coagulation modes within single procedures, expanding multifunctional generator margins across general and specialty surgical applications.
Market Restraints
- Copper and semiconductor input volatility:Generator power electronics depend on copper windings and silicon carbide components subject to supply chain price swings, compressing manufacturer margin stability.
- European supply concentration:Erbe Elektromedizin dominates European surgical suite installations, creating vendor lock-in effects that constrain new entrant penetration in Germany, France, and Switzerland.
- Bipolar thermal spread limitations:Microsurgical applications requiring sub-millimeter precision face technical constraints from residual thermal diffusion, restricting RF platform adoption in delicate neural and ophthalmic procedures.
Strategic Opportunities
- India surgical infrastructure buildout:Government hospital modernization programs and private healthcare expansion create underpenetrated demand for mid-tier electrosurgical systems outside metropolitan tier-1 cities.
- AI-integrated energy delivery:Convergence of machine learning algorithms with real-time tissue impedance monitoring enables adaptive power modulation, differentiating next-generation platforms from conventional generators.
- Japan PMDA fast-track pathway:The Pharmaceuticals and Medical Devices Agency's priority review system for innovative surgical devices accelerates market entry timelines for novel RF and ultrasonic hybrid platforms.
Industry Challenges
- Biomedical engineer scarcity:Electrosurgical device servicing and calibration require specialized training in high-frequency electronics and patient safety protocols, constraining hospital in-house maintenance capacity.
- ISO 60601-2-2 certification timelines:Electromagnetic compatibility and patient leakage current testing protocols extend product validation cycles, delaying revenue recognition for new generator architectures.
- Legacy system integration friction:Hospital networks with installed Medtronic or Johnson & Johnson generator fleets face switching costs from incompatible proprietary electrode connectors and software protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrosurgical Generators Market |
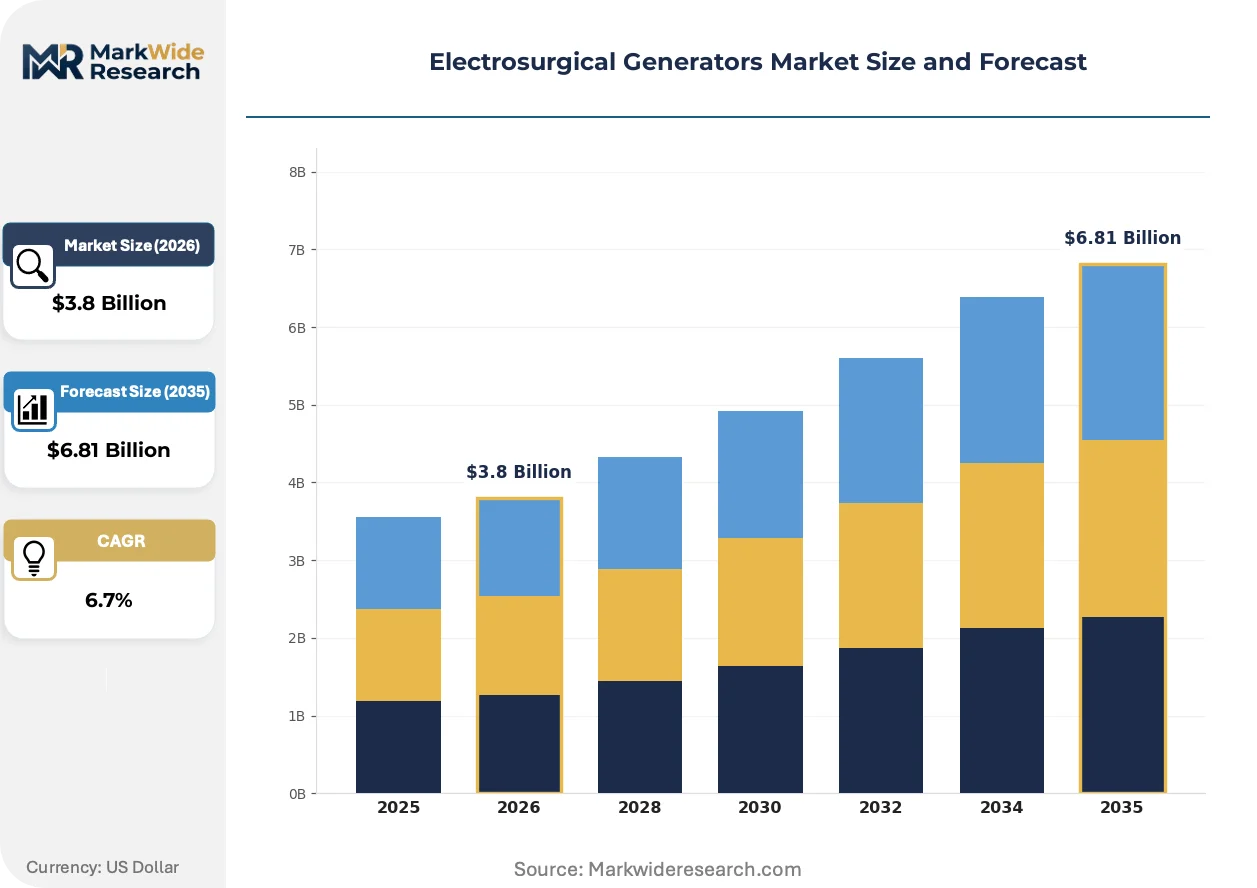
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Generators, Coagulation Generators, Vallecular Generators, Multifunctional Generators End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialized Surgical Units Technology: Radiofrequency, Bipolar, Monopolar, Laser-Assisted Application: General Surgery, Gynecological Surgery, Urological Surgery, ENT Surgery |
| Companies Covered | Medtronic, Johnson & Johnson, Olympus Corporation, CONMED Corporation, B. Braun, Erbe Elektromedizin, Stryker, Integra LifeSciences Corporation, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrosurgical Generators Market Emerging Trajectories
Adaptive energy delivery systems are displacing fixed-output generators as surgeons demand real-time tissue response optimization, while regulatory frameworks tighten electromagnetic emissions standards and procurement consolidation favors integrated platform vendors.
Impedance-feedback generators with closed-loop control systems are automating power modulation based on instantaneous tissue resistance measurements. Ambulatory surgical centers in the United States are adopting these systems at twice the rate of general hospitals. This automation is compressing operative time variability and reducing thermal injury complications in high-volume outpatient procedures.
The EU Medical Device Regulation imposes stricter clinical evidence thresholds for electrosurgical platform approvals across European markets. Manufacturers must now submit post-market surveillance data and clinical performance studies that were previously exempt under the Medical Device Directive. High-frequency generator categories with novel output waveforms face the longest review timelines, pushing some vendors toward predicate device pathways.
Hospital procurement departments now bundle generator-acquisition decisions with multi-year electrode supply contracts and preventive service agreements. Traditional capital equipment distributors are losing share to manufacturer-direct enterprise accounts teams that negotiate system-wide pricing. This pattern is most visible in United States integrated delivery networks consolidating purchasing across 10-plus facility footprints.
Electrosurgical Generators Market Segmentation
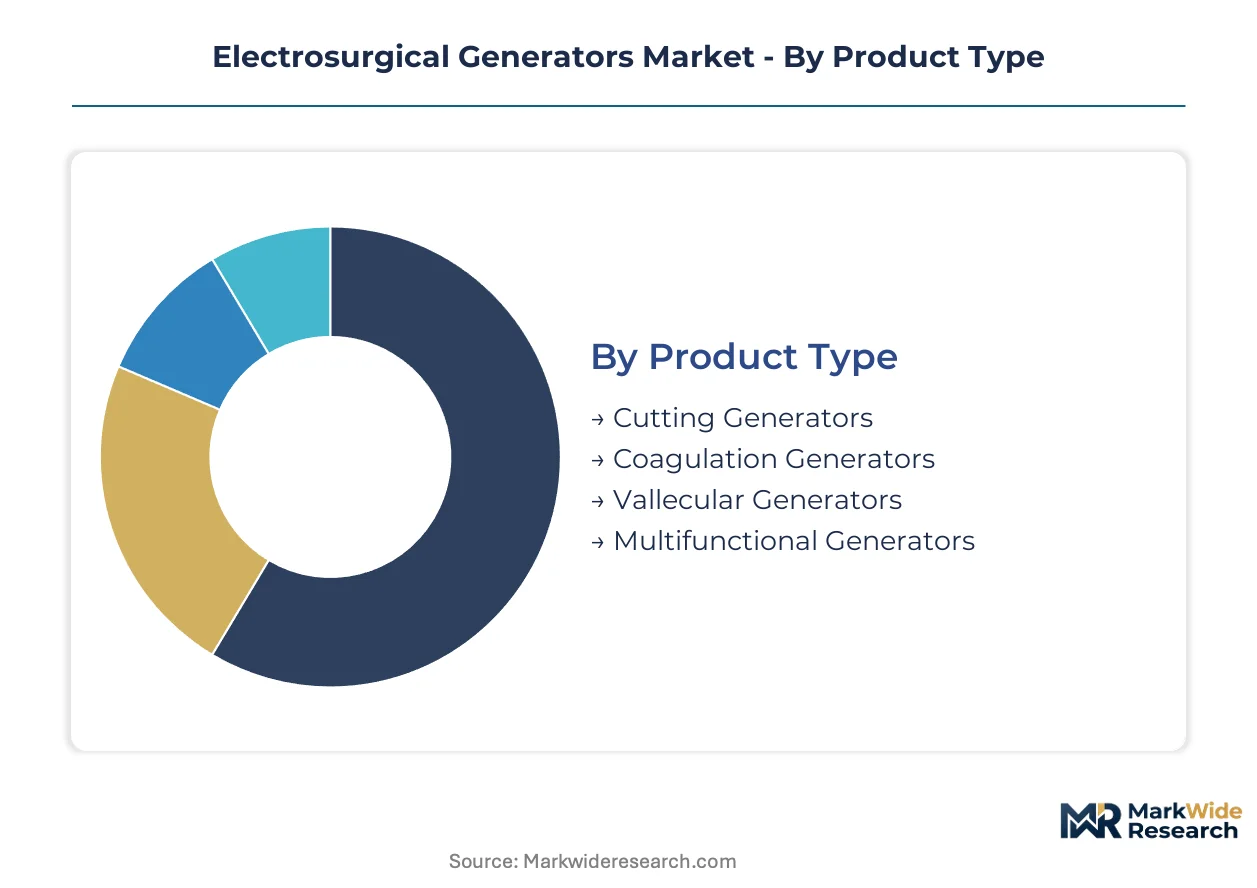
Electrosurgical generator segmentation reflects divergent procurement priorities across care settings. Technology choices determine thermal precision capabilities, while product architecture separates capital-intensive hospital installations from portable ambulatory platforms.
Product Type:
Standalone generator units dominate hospital capital budgets, while embedded modules integrate into multi-modal surgical workstations.
- Multifunctional Generators:These platforms integrate cutting, coagulation, and vessel-sealing modes within single hardware architectures. United States ambulatory surgical centers drive procurement of compact multifunctional units as outpatient procedural volumes expand and space constraints tighten.
- Cutting Generators:Dedicated high-frequency output systems optimized for tissue dissection with minimal lateral thermal damage. General surgery departments in German university hospitals specify cutting generators for open abdominal procedures where speed and precision outweigh versatility requirements.
- Coagulation Generators:Specialized units delivering pulsed or modulated current for hemostasis control.
- Vallecular Generators:Niche platforms designed for oropharyngeal and airway procedures.
Multifunctional generators lead volumes today; cutting generators are gaining share fastest in specialized surgical units seeking dedicated performance.
End User:
Procurement scale separates enterprise health system negotiations from individual facility purchases, with service agreements becoming decisive.
- Hospitals:Large inpatient facilities with 200-plus beds command the highest generator unit values through enterprise pricing. United States integrated delivery networks bundle generator acquisitions across multi-facility footprints, locking in long-term electrode supply contracts and preventive maintenance agreements.
- Ambulatory Surgical Centers:Freestanding outpatient facilities performing same-day procedures drive demand for compact, mobile generator platforms. These centers in Texas, Florida, and California are expanding procurement at twice the rate of general hospitals as site-of-care shifts accelerate.
- Clinics:Smaller procedural sites with limited surgical volumes prioritize cost containment over feature breadth.
- Specialized Surgical Units:Dedicated cardiac, neurological, or ophthalmic facilities require precision-tailored energy delivery systems.
Hospitals retain the largest installed base; ambulatory surgical centers are expanding most quickly as outpatient migration continues.
Technology:
Energy delivery modality determines thermal spread characteristics and tissue interaction physics, with bipolar configurations gaining ground in precision applications.
- Radiofrequency:Oscillating current between 300 kHz and 3 MHz enables cutting and coagulation through resistive tissue heating. RF platforms dominate general surgery installations across United States metropolitan markets, with impedance-feedback systems automating power modulation based on real-time tissue resistance measurements.
- Bipolar:Current confined between instrument jaws minimizes thermal spread to surrounding tissue. Microsurgical applications in Japanese university hospitals and Swiss neurological centers specify bipolar configurations where sub-millimeter precision is mandatory.
- Monopolar:Current flow between active electrode and dispersive return pad enables large-area tissue effect.
- Laser-Assisted:Photonic energy delivery for specialized ablation and cutting applications.
Radiofrequency technology anchors current procurement; bipolar configurations are climbing the fastest in delicate surgical specialties.
Application:
Procedure-specific energy requirements separate high-volume general surgery from specialty disciplines with unique thermal constraints.
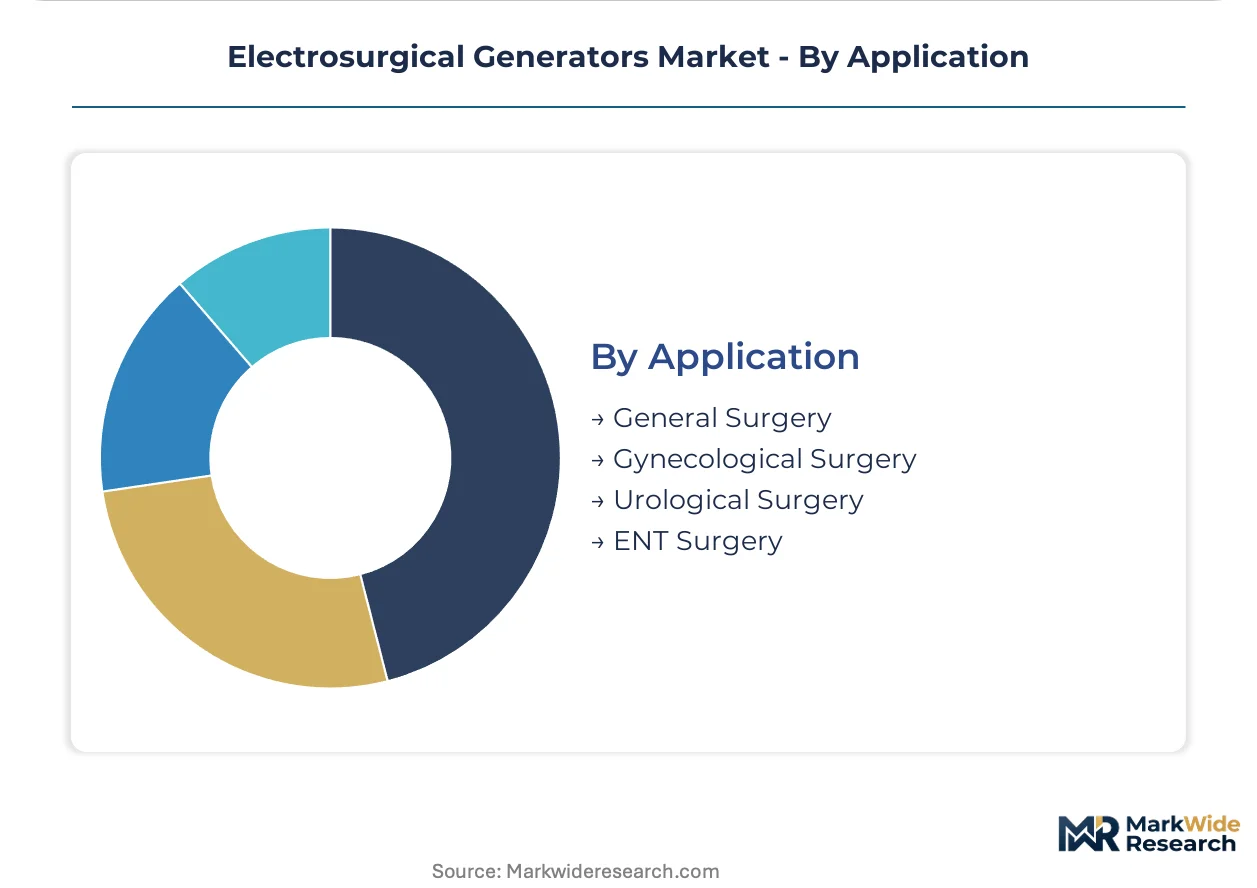
- General Surgery:Abdominal, thoracic, and soft-tissue procedures consume the broadest generator feature sets. United States community hospitals specify general surgery-optimized platforms with rapid mode-switching capabilities to accommodate diverse procedure mixes within single operating rooms.
- Gynecological Surgery:Hysterectomy, myomectomy, and laparoscopic procedures demand precise thermal control near reproductive organs. French and Italian hospital networks prioritize bipolar and advanced RF platforms for gynecological suites to minimize lateral thermal damage.
- Urological Surgery:Prostate, bladder, and renal procedures require specialized electrode configurations.
- ENT Surgery:Delicate head and neck procedures constrain allowable thermal spread to millimeter scales.
General surgery drives the highest absolute unit demand; gynecological surgery shows the steepest expansion trajectory as minimally invasive adoption deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrosurgical generator manufacturing and demand trace their modern origins to German precision engineering in the 1920s, when high-frequency current applications for surgery were first commercialized. The industry's geographic footprint now spans established surgical device clusters and emerging healthcare infrastructure buildouts across multiple continents.
United States
Ambulatory surgical centers in Texas, Florida, and California are procuring compact electrosurgical platforms at twice the rate of general hospitals as outpatient procedural volumes expand. The FDA's 510(k) premarket notification pathway accelerates commercialization timelines for manufacturers targeting this market. Minneapolis and New Haven anchor major surgical device corporate headquarters and R&D operations.
Germany
University hospitals in Tübingen and Heidelberg specify precision cutting generators for open abdominal procedures where surgical speed outweighs versatility requirements. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for platform approvals than previous directives. The Baden-Württemberg and Bavaria regions concentrate electrosurgical manufacturing expertise and precision electronics supply chains.
Japan
University hospitals in Tokyo and Osaka specify bipolar configurations for microsurgical applications where sub-millimeter precision is mandatory. The Pharmaceuticals and Medical Devices Agency's priority review system accelerates market entry timelines for novel RF and ultrasonic hybrid platforms. The Kanto and Kansai regions host the densest concentrations of advanced surgical suites and medical device distribution networks.
India
Government hospital modernization programs and private healthcare expansion create underpenetrated demand for mid-tier electrosurgical systems outside metropolitan tier-1 cities. The Central Drugs Standard Control Organization regulates device imports and domestic manufacturing quality standards. Maharashtra and Karnataka states are building surgical infrastructure in secondary cities as medical tourism and domestic procedure volumes rise.
Switzerland
Neurological centers in Zurich and Geneva require precision-tailored energy delivery systems for delicate neural procedures with minimal thermal spread. Swissmedic maintains rigorous approval standards for electrosurgical platforms entering the domestic market and influencing broader European regulatory expectations. The Zurich-West and Basel biotech clusters support adjacent surgical innovation ecosystems.
Electrosurgical Generators Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and proprietary ecosystem lock-in. The market structure consolidates around integrated platform vendors with bundled electrode and smoke evacuation offerings, while specialized RF precision manufacturers occupy defended niches. Three archetypes dominate: diversified surgical conglomerates with full portfolio coverage, precision RF specialists with European installed base advantages, and ambulatory-focused compact system providers. Competitive moves center on multi-year hospital supply contract negotiations and AI-integrated energy delivery feature differentiation.
Within the diversified surgical conglomerate tier, Medtronic and Johnson & Johnson exemplify platform bundling strategies that harden procurement patterns across hospital networks. Erbe Elektromedizin occupies a specialist position representing precision radiofrequency platform dominance in European surgical suites. These three companies anchor the competitive structure through contrasting approaches to ecosystem integration, geographic concentration, and technology specialization.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Olympus Corporation |
| CONMED Corporation |
| B. Braun |
| Erbe Elektromedizin |
| Stryker |
| Integra LifeSciences Corporation |
| Smith & Nephew |
| Others |
Supply Flow & Price Mechanics
Impedance-feedback generator architectures with closed-loop control systems are compressing production cost curves while concentrating manufacturing capability among suppliers with precision electronics expertise. This technological shift simultaneously enables tiered pricing differentiation and locks component sourcing into specialized foundry networks across Germany, Japan, and the United States.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated platforms with adaptive power modulation from fixed-output generators and refurbished legacy systems. FDA 510(k) certification tier and enterprise volume scale drive price differentiation, with ambulatory surgical centers exhibiting highest price sensitivity due to capital constraint pressures. Cost compression in mid-tier multifunctional units is intensifying because copper winding and silicon carbide component volatility feeds through to manufacturer margins.
Supply Chain Analysis
Refurbishment and remanufacturing flows for high-frequency generator power electronics create secondary supply channels that compete with new equipment procurement in price-sensitive segments. Manufacturing concentrates in Germany, Japan, and the United States, with copper windings, silicon carbide semiconductors, and precision RF components drawing from specialized foundry networks. Single-source vulnerability in semiconductor supply creates structural risk, while distribution runs through manufacturer-direct enterprise accounts teams and traditional capital equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrosurgical generator market functions as a regulatory compounder where FDA 510(k) clearance velocity and EU MDR clinical evidence thresholds directly shape competitive entry costs and incumbent pricing power.
For Market Incumbents: Anchor market position through backward integration into proprietary electrode manufacturing and captive smoke evacuation hardware production. Deepen hospital system lock-in via multi-year preventive service agreements that raise switching costs for integrated delivery networks. Defend against AI-integrated energy delivery disruptors by accelerating impedance-feedback feature deployment across installed generator fleets. For New Entrants and Emerging Players: AI-integrated adaptive power modulation offers a technology-first wedge into underserved ambulatory surgical center segments in Texas, Florida, and California. Target mid-tier multifunctional generator procurement in Indian government hospital modernization programs outside metropolitan tier-1 cities. Pursue Japan PMDA priority review pathway for novel RF-ultrasonic hybrid platforms to accelerate commercialization timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among precision RF specialists with European installed base concentration but limited AI feature integration. Long-term viability over the projection horizon favors acquisition targets with software companion development capabilities and hospital system partnership depth. Monitor FDA 510(k) submission velocity for novel output waveform generators as inflection indicator for next-generation platform adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification reduces commercialization friction relative to EU MDR pathways for United States market entry. |
| Hospital System Partnership | Enterprise pricing agreements with integrated delivery networks lock in electrode supply contracts across multi-facility footprints. |
| Software Companion Development | AI-integrated energy delivery algorithms differentiate next-generation platforms from conventional fixed-output generators. |
| CE Marking Pathway Investment | EU MDR clinical evidence preparation enables continued European market access amid stricter post-market surveillance requirements. |
| Reimbursement Strategy Alignment | Outpatient procedural code optimization accelerates ambulatory surgical center capital allocation toward compact platform procurement. |
Methodological Framework
Direct dialogue with hospital purchasing committees, biomedical engineers, GPO contracts managers, and electrosurgical device distributors grounded qualitative insights in procurement workflow realities. Secondary validation drew from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up and top-down triangulation cross-checked unit shipment estimates against enterprise pricing disclosures and regional surgical volume trends.
Bottom-up modeling segmented the analysis window by product type, technology configuration, end-user facility scale, and application specialty to isolate margin and growth rate differentials. Top-down demand estimation anchored on ambulatory surgical center expansion rates, outpatient procedural volume shifts, and capital equipment replacement cycles across United States metropolitan markets. CAGRs were derived from slope-consistent growth trajectory fitting rather than single-point extrapolation.
The model holds under stable regulatory clearance timelines and copper semiconductor supply continuity; deviation in FDA review backlogs or foundry capacity constraints would shift commercialization and pricing assumptions. Forecasts reflect documented base-case parameters for reimbursement alignment and site-of-care migration patterns. Periodic stress-testing of base assumptions is recommended given biomedical engineer scarcity and ISO 60601-2-2 certification timeline variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Needle Destroyer Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Global Pulmonary Drug Delivery Systems Market