
 Urodynamic Devices Market | 2026-2036
Urodynamic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Urodynamic Devices Market Analytics
Disposable single-use catheters is rebalancing cost structures against traditional reusable systems in the Urodynamic Devices landscape. Laborie leverages its specialized urology portfolio to dominate advanced cystometry platforms across North American hospital networks. Boston Scientific Corporation sustains R&D intensity in pelvic floor diagnostic integration, while Medtronic anchors wireless telemetry development for ambulatory urodynamic monitoring.
Urodynamic devices comprise diagnostic instrumentation that measures urine flow rate, bladder pressure, sphincter activity, and detrusor function through catheters, pressure transducers, and electromyography sensors to evaluate lower urinary tract dysfunction. Cystometry systems command the largest installed base among product types due to their essential role in pre-surgical bladder capacity assessment. Wireless technology segments are expanding fastest as clinics seek to reduce catheter-associated infection risks and improve patient mobility during extended monitoring protocols.
The FDA's Class II medical device controls and the EU Medical Device Regulation's clinical evidence requirements shape product development timelines and market access barriers for manufacturers. ISO 13485 quality management standards and IEC 60601 electrical safety specifications govern manufacturing compliance across major jurisdictions. Stakeholders must monitor reimbursement policy shifts for outpatient urodynamic testing as payers recalibrate coverage for diagnostic versus therapeutic interventions.
Market Dynamics
Wireless telemetry architectures are compressing the installed base of tethered urodynamic systems across hospital networks, forcing manufacturers to accelerate ambulatory platform development while defending service revenue from legacy equipment.
Growth Catalysts
- EU Medical Device Regulation:MDR's enhanced clinical evidence requirements for Class IIa diagnostic equipment are accelerating hospital replacement cycles for aging cystometry systems in Germany and France.
- Ambulatory surgery centers:Freestanding urology clinics in the United States are deploying compact wireless uroflowmetry units to capture outpatient diagnostic volume outside hospital cost structures.
- Pressure-sensitive microcatheters:MEMS-enabled transducer miniaturization is enabling dual-pressure synchronous measurement during extended monitoring protocols previously requiring inpatient admission.
Market Restraints
- Platinum-iridium electrode costs:Electromyography sensor fabrication depends on scarce noble metal supplies concentrated in South African and Russian refining operations.
- FDA 510(k) pathway congestion:Diagnostic urological device review timelines have extended substantially, delaying wireless platform commercialization for mid-tier manufacturers lacking predicate device strategies.
- Disposable catheter economics:Single-use pressure transducer assemblies carry per-procedure costs that challenge reimbursement rates in outpatient settings across multiple European markets.
Strategic Opportunities
- Japan's super-aged prefectures:Hokkaido and rural Honshu regions present concentrated demand for home-based urodynamic telemetry as institutional bed capacity contracts.
- Artificial intelligence convergence:Machine learning classification of detrusor pressure waveforms is enabling automated dysfunction pattern recognition without specialist interpretation.
- Telehealth reimbursement expansion:CMS remote patient monitoring codes now cover ambulatory urodynamic data transmission, creating channel economics for direct-to-clinic device deployment.
Industry Challenges
- Clinical engineering specialization:Hospital biomedical technicians lack training in wireless telemetry calibration, forcing manufacturers to absorb field service costs or risk measurement drift.
- ISO 13485 audit compression:Accelerated certification timelines for MDR transition are straining quality management system documentation capacity across mid-scale device firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urodynamic Devices Market |
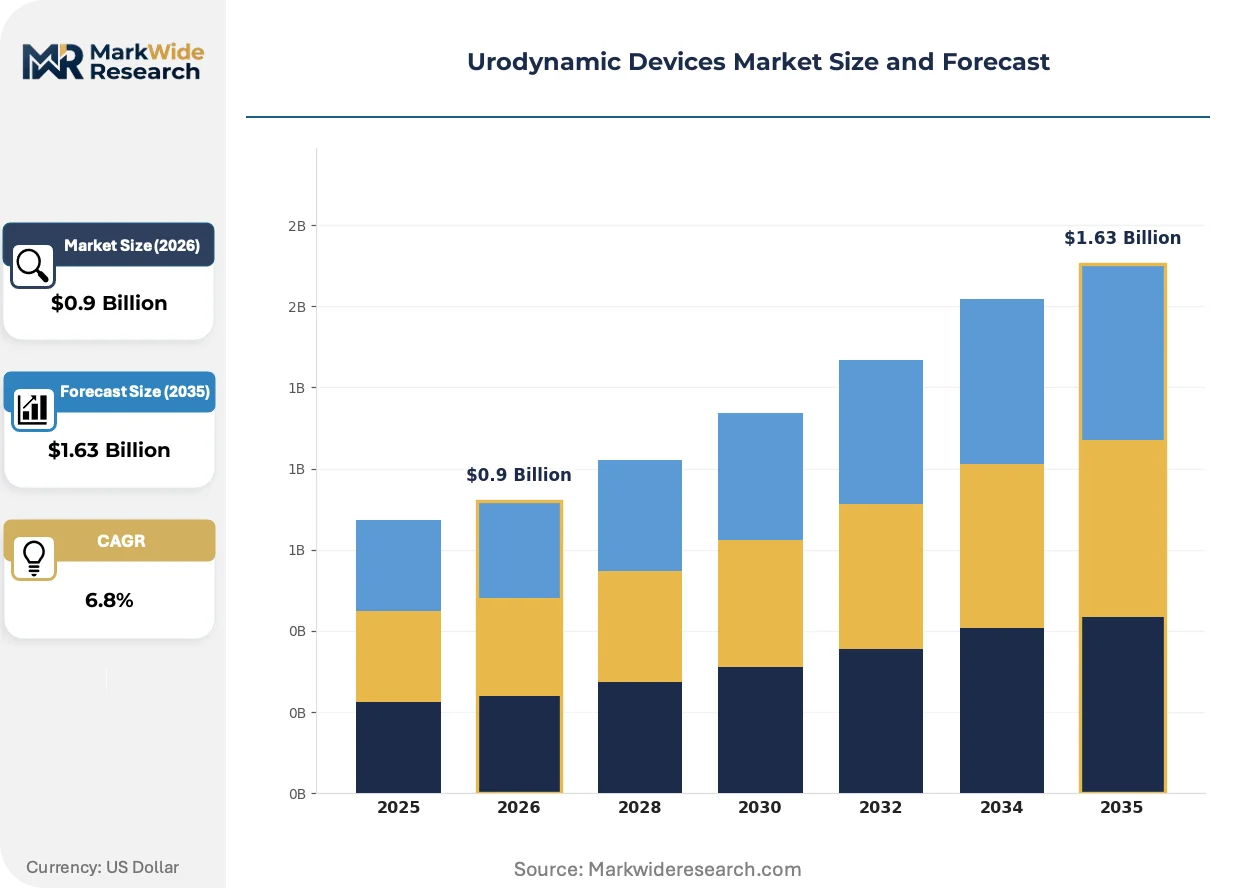
| Market Size in 2026 | $0.9 Billion |
| Market Size in 2035 | $1.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uroflowmetry, Cystometry, Electromyography, Pressure Flow Study Technology: Digital, Wireless, Automated, Manual End User: Hospitals, Clinics, Home Care, Diagnostic Centers Application: Urinary Incontinence, Pelvic Floor Disorders, Prostate Issues, Bladder Dysfunction |
| Companies Covered | Laborie, Boston Scientific Corporation, Verathon, Inc., B. Braun Melsungen AG, Medtronic, STorz Medical AG, CooperSurgical Inc., Karl Storz, Albyn Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urodynamic Devices Market Evolving Landscape
Diagnostic instrumentation is migrating from centralized hospital urology suites toward distributed ambulatory settings, compressing the traditional equipment procurement cycle and fragmenting vendor service relationships.
Bluetooth-enabled pressure transducer arrays are decentralizing urodynamic data capture from fixed hospital infrastructure toward patient-worn telemetry pods. Outpatient urology clinics in the United States are adopting these platforms within eighteen-month replacement windows. The technology is decentralizing diagnostic service delivery from inpatient wards toward home-based monitoring protocols, compressing facility fee revenue for hospital systems.
EU MDR's post-market surveillance requirements for implantable and active diagnostic devices are extending clinical follow-up obligations for urodynamic catheter manufacturers. Manufacturers must now maintain periodic safety update reports across entire product lifecycles rather than discrete pre-market submissions. Wireless cystometry platforms face the steepest compliance burden, as software-enabled devices trigger additional cybersecurity documentation requirements under Annex I.
Hospital purchasing cooperatives are consolidating urodynamic equipment procurement through multi-year sole-source agreements, displacing fragmented capital equipment bidding. Integrated delivery networks in Germany and the United States are extracting extended warranty and training bundling as contract conditions. This concentration is most visible in academic medical centers, where standardization across affiliated community hospitals has compressed secondary vendor access.
Urodynamic Devices Market Segmentation
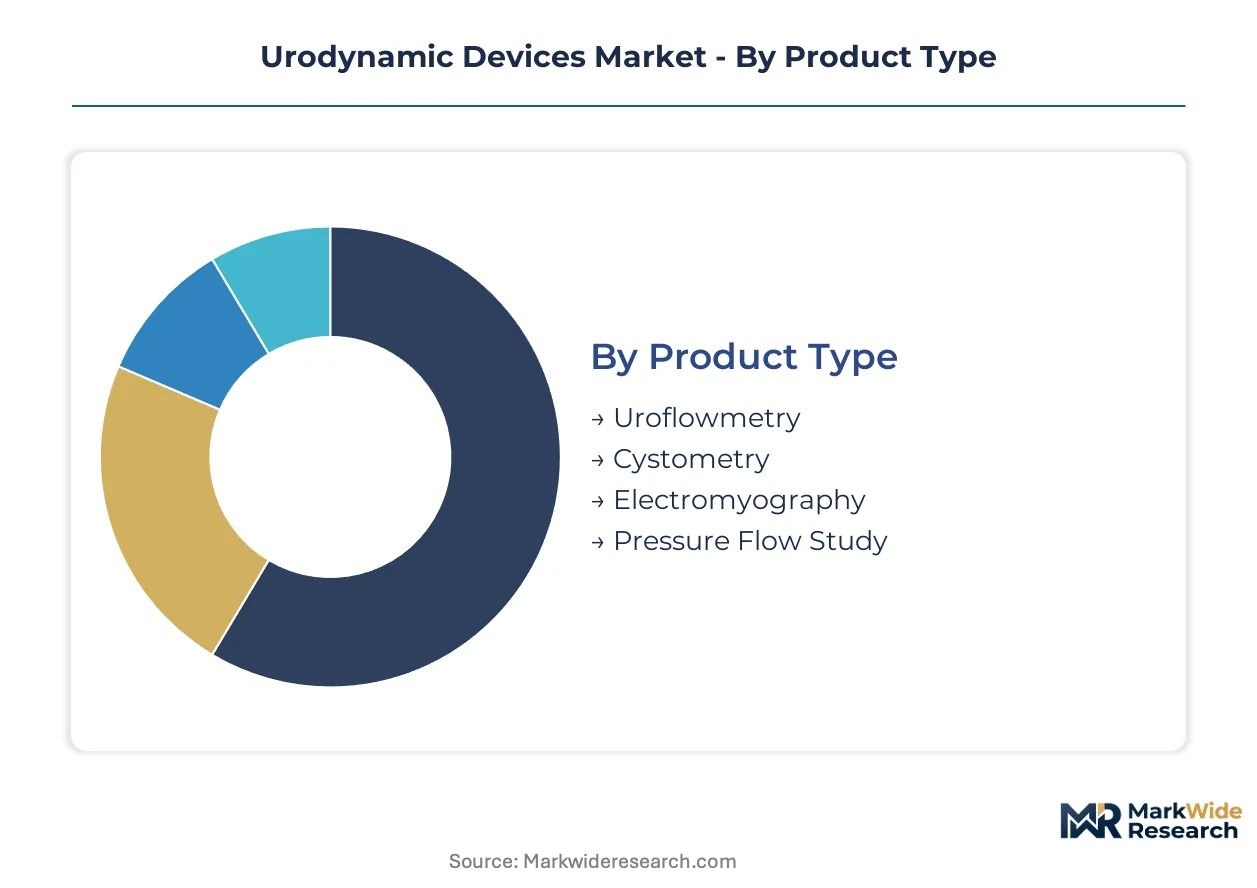
Urodynamic device segmentation reveals divergent margin profiles across measurement modalities. Product architecture and connectivity standards determine reimbursement eligibility and procurement channel access for manufacturers.
Product Type:
Volume concentration favors established hospital-installed platforms, while premium pricing attaches to integrated multi-parameter systems.
- Cystometry:Bladder pressure-volume measurement through saline infusion catheters and rectal reference sensors constitutes the diagnostic backbone for pre-surgical capacity assessment. Demand clusters in academic medical centers across Germany and the United States where complex dysfunction cases require comprehensive detrusor evaluation. MDR transition timelines are accelerating replacement cycles for aging installed bases in European hospital networks.
- Uroflowmetry:Non-invasive urine flow rate measurement via gravimetric or rotating disk sensors dominates outpatient diagnostic volume due to lower per-procedure cost and minimal technician supervision requirements. Ambulatory surgery centers in Florida and Texas deploy compact wireless units to capture urology referrals outside hospital cost structures.
- Electromyography:Sphincter muscle electrical activity recording through needle or surface electrodes.
- Pressure Flow Study:Synchronous voiding pressure and flow measurement during natural bladder emptying.
Mature deployment sits with Cystometry. Newer deployment is concentrated in Uroflowmetry.
Technology:
Connectivity architecture determines calibration protocols and cybersecurity documentation burdens under EU MDR Annex I requirements.
- Wireless:Bluetooth-enabled telemetry pods and patient-worn pressure transducer arrays eliminate tethered connections during extended monitoring protocols. Clinics in Japan's super-aged prefectures adopt these platforms for home-based dysfunction assessment as institutional bed capacity contracts. FDA 510(k) review congestion for software-enabled devices has delayed commercialization timelines for mid-tier manufacturers lacking predicate strategies.
- Digital:Computer-integrated data acquisition with automated waveform display and storage.
- Automated:Sensor-driven measurement initiation with minimal technician intervention.
- Manual:Operator-controlled catheter placement and pressure transducer calibration.
Digital systems anchor current installed capacity. Wireless platforms are climbing the fastest as infection control protocols drive catheter minimization.
End User:
Procurement authority and reimbursement coding determine device specification requirements across care settings.
- Hospitals:Centralized urology departments with dedicated cystometry suites and clinical engineering support maintain the largest installed base of multi-parameter diagnostic platforms. Integrated delivery networks in the United States extract extended warranty bundling and cross-facility standardization as contract conditions.
- Clinics:Freestanding urology practices with limited capital budgets favor compact uroflowmetry units and disposable catheter economics.
- Diagnostic Centers:Specialized outpatient facilities with high procedural throughput.
- Home Care:Patient-operated telemetry for extended monitoring outside clinical settings.
Capital equipment concentration remains with Hospitals. CMS remote patient monitoring code expansion is shifting volume toward Home Care.
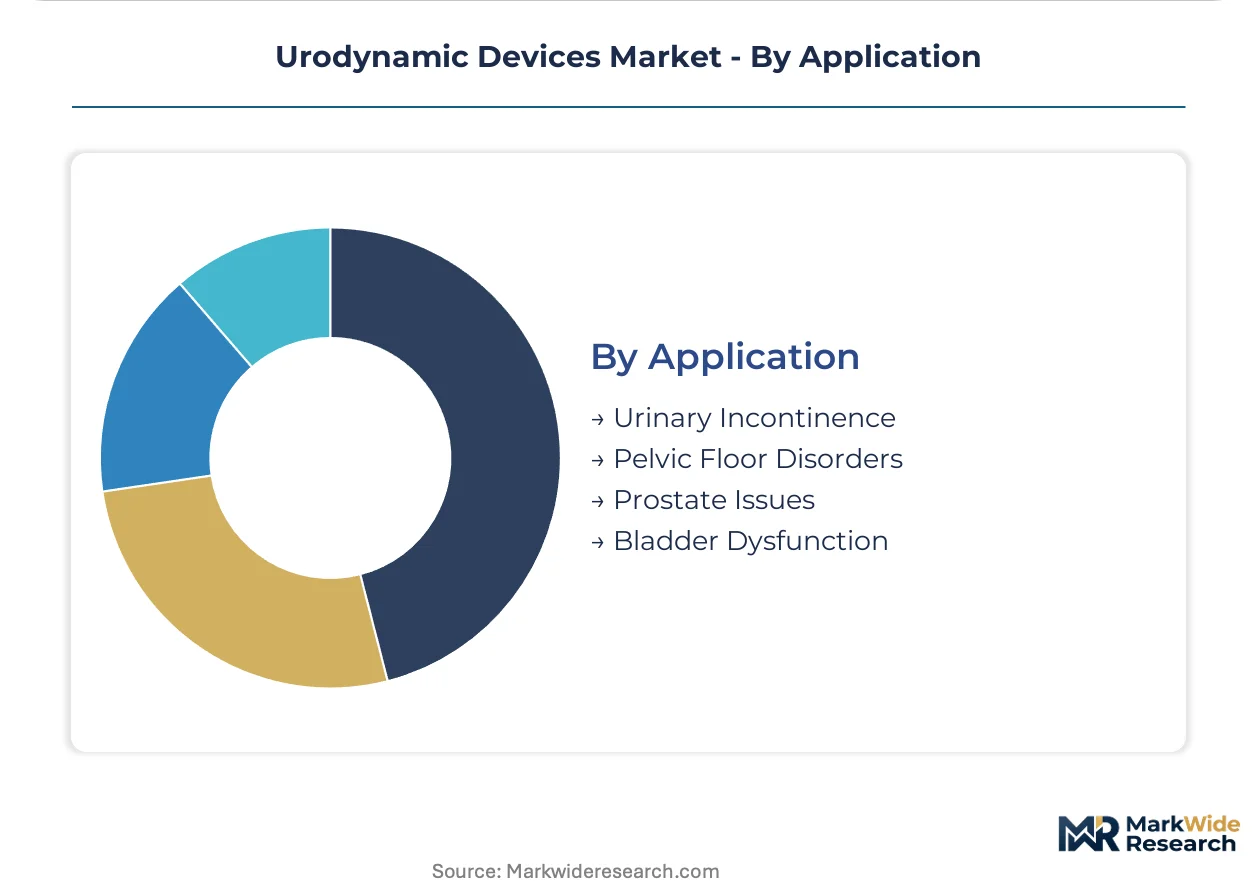
Application:
Clinical indication determines measurement protocol complexity and specialist interpretation requirements.
- Urinary Incontinence:Stress, urge, and mixed incontinence evaluation through leak point pressure measurement and bladder diary correlation represents the highest-volume diagnostic indication. Demand concentrates in outpatient clinics serving aging populations in Japan and Germany where prevalence rises with demographic transition.
- Pelvic Floor Disorders:Multi-compartment dysfunction assessment combining urodynamic and anorectal manometry protocols.
- Prostate Issues:Post-void residual and bladder outlet obstruction evaluation in male patients.
- Bladder Dysfunction:Neurogenic detrusor overactivity and underactivity assessment in spinal cord injury and multiple sclerosis populations.
Established procedural volume sits with Urinary Incontinence. Pelvic Floor Disorders represent the steepest expansion trajectory as multi-compartment diagnostic protocols gain reimbursement recognition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MedTech innovation corridors in Massachusetts and Minnesota concentrate cystometry platform development, while Japan's super-aged prefectures drive home-based telemetry adoption as institutional capacity contracts.
United States
Academic medical centers in Boston and Baltimore maintain the largest installed bases of multi-parameter diagnostic platforms for pre-surgical bladder assessment. FDA's Class II device controls and 510(k) review pathways shape commercialization timelines for wireless platform developers. Ambulatory surgery centers across Florida and Texas deploy compact uroflowmetry units to capture outpatient diagnostic volume outside hospital cost structures.
Germany
Integrated delivery networks in Bavaria and North Rhine-Westphalia extract extended warranty bundling and cross-facility standardization as contract conditions for cystometry system procurement. EU MDR's enhanced clinical evidence requirements for Class IIa diagnostic equipment accelerate hospital replacement cycles for aging installed bases. Medical device clusters around Tübingen and Erlangen anchor wireless telemetry development for ambulatory monitoring protocols.
Japan
Hokkaido and rural Honshu prefectures present concentrated demand for home-based urodynamic telemetry as institutional bed capacity contracts under super-aged demographic transition. PMDA's medical device review standards govern software-enabled diagnostic platform approvals. Tokyo and Osaka metropolitan areas concentrate electromyography sensor fabrication and pressure transducer miniaturization R&D.
United Kingdom
NHS procurement frameworks for diagnostic urology equipment favor multi-year sole-source agreements with extended training and calibration service bundling. MHRA's post-Brexit medical device regulations create parallel compliance pathways alongside retained EU MDR requirements. London and Manchester academic medical centers standardize wireless cystometry platforms across affiliated community hospital networks.
France
Hospital purchasing cooperatives in Île-de-France and Auvergne-Rhône-Alpes consolidate urodynamic equipment procurement through centralized bidding processes. ANSM's device vigilance requirements extend post-market surveillance obligations for active diagnostic equipment manufacturers. Lyon and Strasbourg urology departments drive adoption of MEMS-enabled pressure-sensitive microcatheters for dual-pressure synchronous measurement.
Urodynamic Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement concentration favoring established multi-parameter platform vendors while ambulatory clinics fragment toward compact single-use systems. The vendor base organizes into three strategic tiers: integrated urology portfolio holders defending installed base service revenue, wireless telemetry specialists capturing ambulatory replacement cycles, and disposable catheter fabricators exploiting single-use economics against reusable system maintenance. M&A activity targets telemetry software capabilities, while geographic expansion focuses on Japan's super-aged prefectures and Germany's MDR-driven replacement demand.
Among North American portfolio holders, Laborie and Boston Scientific Corporation exemplify the integrated urology equipment archetype, anchoring hospital network relationships through multi-year service contracts. Medtronic occupies a distinct position on the wireless telemetry vector, representing the shift toward patient-worn monitoring platforms that reduce catheter-associated infection risks. These three entities collectively illustrate how competitive positioning diverges between installed base defense and ambulatory market creation.
| Leading Market Players |
|---|
| Laborie |
| Boston Scientific Corporation |
| Verathon, Inc. |
| B. Braun Melsungen AG |
| Medtronic |
| Karl Storz |
| CooperSurgical Inc. |
| STorz Medical AG |
| Albyn Medical |
| Others |
Value Network & Pricing Analysis
Hospital purchasing cooperative consolidation across Germany and the United States is compressing vendor margins and forcing manufacturers to absorb extended warranty and calibration service costs into upfront equipment pricing. This procurement concentration is reshaping supply chain configurations as device firms seek captive component production to defend margin structures against bundled contract demands.
Pricing Analysis
Short lead-time premiums attach to wireless telemetry platforms as FDA 510(k) review congestion extends commercialization timelines for mid-tier manufacturers lacking predicate device strategies. Three-tier pricing structure across premium multi-parameter systems, standard cystometry platforms, and economy uroflowmetry units stratifies by measurement modality complexity and after-sales service bundling. Cost compression in economy tiers intensifies as ambulatory surgery centers in Florida and Texas prioritize disposable catheter economics over capital equipment investment. Clinics serving aging populations in Japan's super-aged prefectures exhibit highest price sensitivity, while academic medical centers in Boston and Baltimore demonstrate lowest sensitivity due to dedicated clinical engineering support and complex case referral volume.
Supply Chain Analysis
Japan's domestic-content requirements for medical device procurement in Hokkaido and rural Honshu regions are reshaping sourcing patterns for telemetry pod assembly and pressure transducer fabrication. Component manufacturing concentrates in Japan, Germany, and the United States, with electromyography sensor fabrication drawing from scarce platinum-iridium supplies anchored in South African and Russian refining operations. Single-source vulnerability runs through MEMS-enabled microcatheter foundries concentrated in Tokyo-Osaka metropolitan clusters. Distribution runs through hospital purchasing cooperatives and integrated delivery networks that extract multi-year sole-source agreements with cross-facility standardization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urodynamic devices sector is becoming a vertical-integration race as manufacturers pursue upstream control over pressure transducer miniaturization and downstream capture of ambulatory monitoring service revenue to offset hospital procurement consolidation pressure.
For Market Incumbents: Anticipate wireless telemetry commoditization by accelerating backward integration into MEMS pressure sensor foundries and securing exclusive supply agreements for platinum-iridium electrode fabrication. Defend installed base service revenue through extended calibration and cybersecurity update bundling as EU MDR post-market surveillance requirements extend clinical follow-up obligations. Hospital purchasing cooperative consolidation in Germany and the United States represents the primary margin compression threat requiring channel control investment. For New Entrants and Emerging Players: Enter via home-based telemetry deployment in Japan's contracting institutional bed markets, where PMDA software-enabled device pathways offer faster approval timelines than FDA 510(k) congestion for predicate-lacking manufacturers. Target ambulatory uroflowmetry in United States freestanding clinics seeking compact wireless units outside hospital cost structures. Reimbursement strategy alignment with CMS remote patient monitoring codes provides the critical go-to-market angle for direct-to-clinic device deployment without capital equipment sales cycles. For Investors and Strategic Acquirers: Re-rating potential sits with wireless telemetry specialists possessing FDA-cleared ambulatory platforms given CMS reimbursement expansion catalysts and hospital infection control protocol shifts. Long-term viability over the diagnostic instrumentation decentralization window favors firms with software-enabled device capabilities and cybersecurity documentation capacity under EU MDR Annex I. Acquisition target archetype: mid-scale device firms with ISO 13485 certification and strained quality management system documentation capacity facing MDR transition timelines. Signal to watch: hospital system partnership announcements for home-based monitoring pilot programs in super-aged prefectures.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements accelerate replacement cycles for aging cystometry installed bases in Bavaria and North Rhine-Westphalia. |
| Hospital System Partnership | Integrated delivery networks in the United States extract extended warranty bundling and cross-facility standardization as contract conditions. |
| Software Companion Development | Machine learning classification of detrusor pressure waveforms enables automated dysfunction pattern recognition without specialist interpretation. |
| Reimbursement Strategy | CMS remote patient monitoring codes covering ambulatory urodynamic data transmission create channel economics for direct-to-clinic deployment. |
| Backward Integration | Captive MEMS pressure transducer production defends margins against platinum-iridium electrode cost volatility and supply concentration. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract registries formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with urology department heads, biomedical engineering directors, GPO contracts managers, and ambulatory clinic operators combined with secondary validation across regulatory submission records. Bottom-up equipment installation tracking and top-down diagnostic procedure volume estimates provided triangulation for market value reconstruction.
Historical trendline analysis of cystometry system replacement cycles and wireless telemetry adoption curves informed projection framework construction across the analysis window. Segmentation modeling incorporated product type, connectivity architecture, end-user setting, and clinical indication dimensions with regional regulatory cluster differentiation. CAGRs derived from equipment procurement pipeline analysis and reimbursement code expansion trajectories, with uroflowmetry volume growth and home-based telemetry penetration serving as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA review timeline extension or platinum-iridium supply disruption scenarios. Forecasts reflect documented assumptions regarding MDR transition compliance timelines and CMS remote monitoring reimbursement stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Dermal Allograft Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
United States Respiratory Devices Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Prescription Goggles Market
Medical Devices
Catheter Systems Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Artificial Retina Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Canada Spinal Surgery Devices Market