
 Breast Biopsy Localization Wire Market | 2026-2036
Breast Biopsy Localization Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Biopsy Localization Wire Market Analytics
Aftermarket service revenue for wire localization systems is narrowing as manufacturers bundle placement devices with disposable wires under single-procedure contracts. Hologic leverages integrated mammography-to-biopsy platforms to control hospital purchasing decisions. Becton Dickinson and Company anchors its position through broad surgical needle portfolios that cross-sell localization products. Merit Medical Systems specializes in interventional radiology kits that incorporate wire placement into comprehensive breast biopsy workflows.
Breast biopsy localization wires are thin, implantable metallic or polymer filaments inserted percutaneously to mark non-palpable breast lesions for surgical excision, typically measuring 0.46-0.81 mm in diameter with hooked, coiled, or magnetic tips to prevent migration. The primary commercial purpose is enabling precise tissue removal while minimizing healthy tissue excision in image-guided breast surgery. Stainless steel hook wires still occupy the dominant volume position due to decades of clinical familiarity and lowest per-unit cost, though magnetic wire segments are attracting margin pools as facilities seek radiation-free alternatives to traditional wire localization. Diagnostic centers represent the fastest-growing end-user channel as ambulatory breast imaging networks expand same-day localization capacity.
FDA 510(k) clearance requirements govern wire device commercialization in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking access across European member states. ISO 13485 quality management certification shapes supplier qualification for original equipment manufacturer partnerships. Stakeholders must monitor reimbursement coding shifts for image-guided localization procedures, as bundled payment reforms could restructure whether hospitals or outpatient clinics capture procedure economics.
Market Dynamics
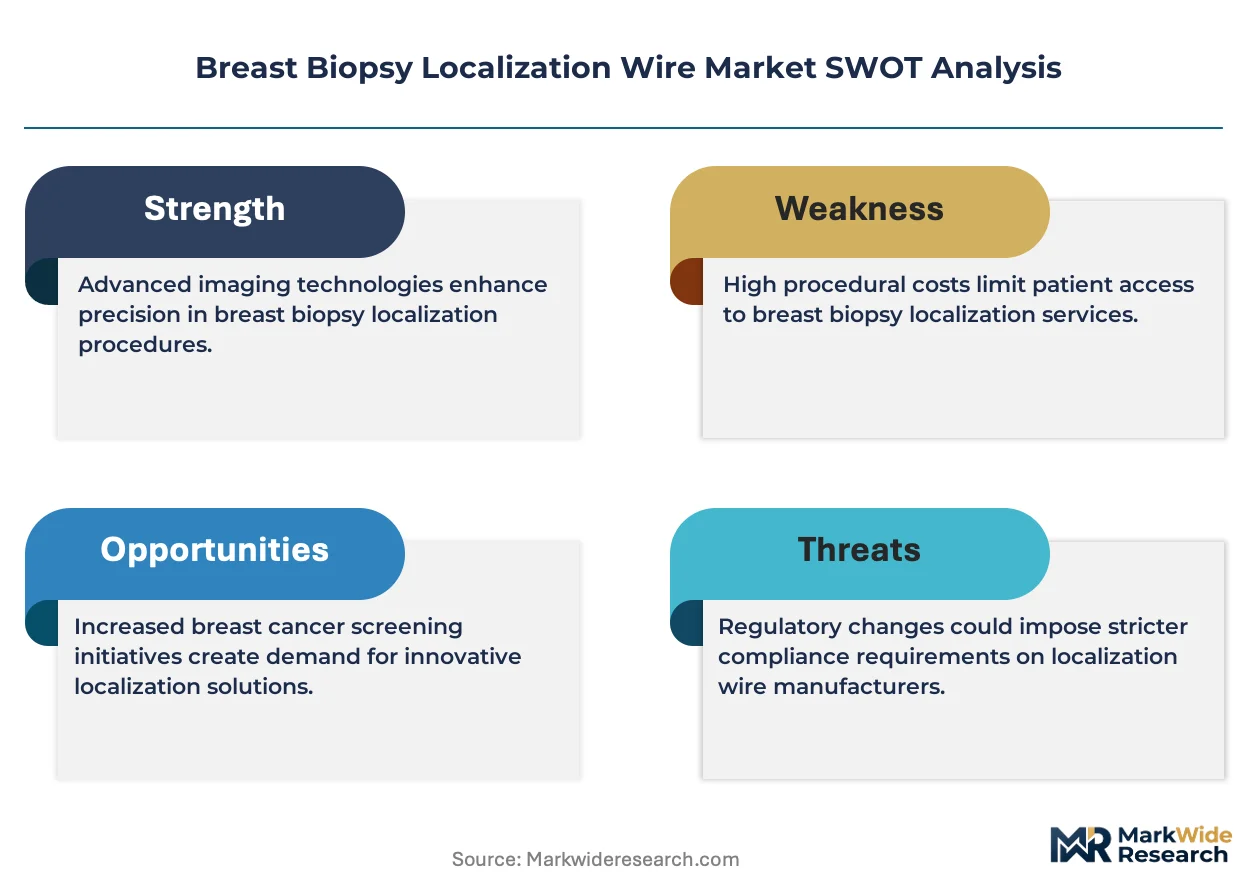
Hospital procurement consolidation is compressing vendor margins as integrated delivery networks negotiate bundled contracts spanning imaging systems, localization devices, and disposable wires under single-source agreements.
Growth Catalysts
- Dense breast tissue notification mandates:United States state laws requiring supplemental screening disclosures drive demand for precise localization in diagnostic workflows.
- Magnetic seed technology:Radiation-free alternatives to traditional wire localization attract facilities seeking to eliminate radioactive tracer handling protocols.
- Ambulatory surgical centers:Same-day breast biopsy capacity expansion creates localized demand for streamlined wire placement systems.
Market Restraints
- Nickel-titanium alloy cost volatility:Shape-memory wire raw material prices fluctuate with aerospace and medical device demand cycles.
- Single-source sterilization services:Gamma irradiation capacity concentrates in Midwest United States contract sterilizers, creating geographic supply vulnerability.
- FDA 510(k) predicate device requirements:Substantial equivalence demonstrations for novel tip geometries extend clearance timelines.
Strategic Opportunities
- India diagnostic imaging expansion:Tier-2 and Tier-3 city hospital breast screening programs remain underpenetrated for wire localization systems.
- Ultrasound-guided wire placement:Convergence of handheld ultrasound with electromagnetic tracking enables office-based localization without mammography suite access.
- EU MDR Article 120 transition:Legacy device certificate expiration deadlines create replacement demand for CE-marked next-generation products.
Industry Challenges
- Interventional radiology fellowship pipeline:Breast imaging subspecialty training program expansion lags behind procedure volume growth.
- ISO 13485 audit backlogs:Notified body capacity constraints delay quality management certification for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Biopsy Localization Wire Market |
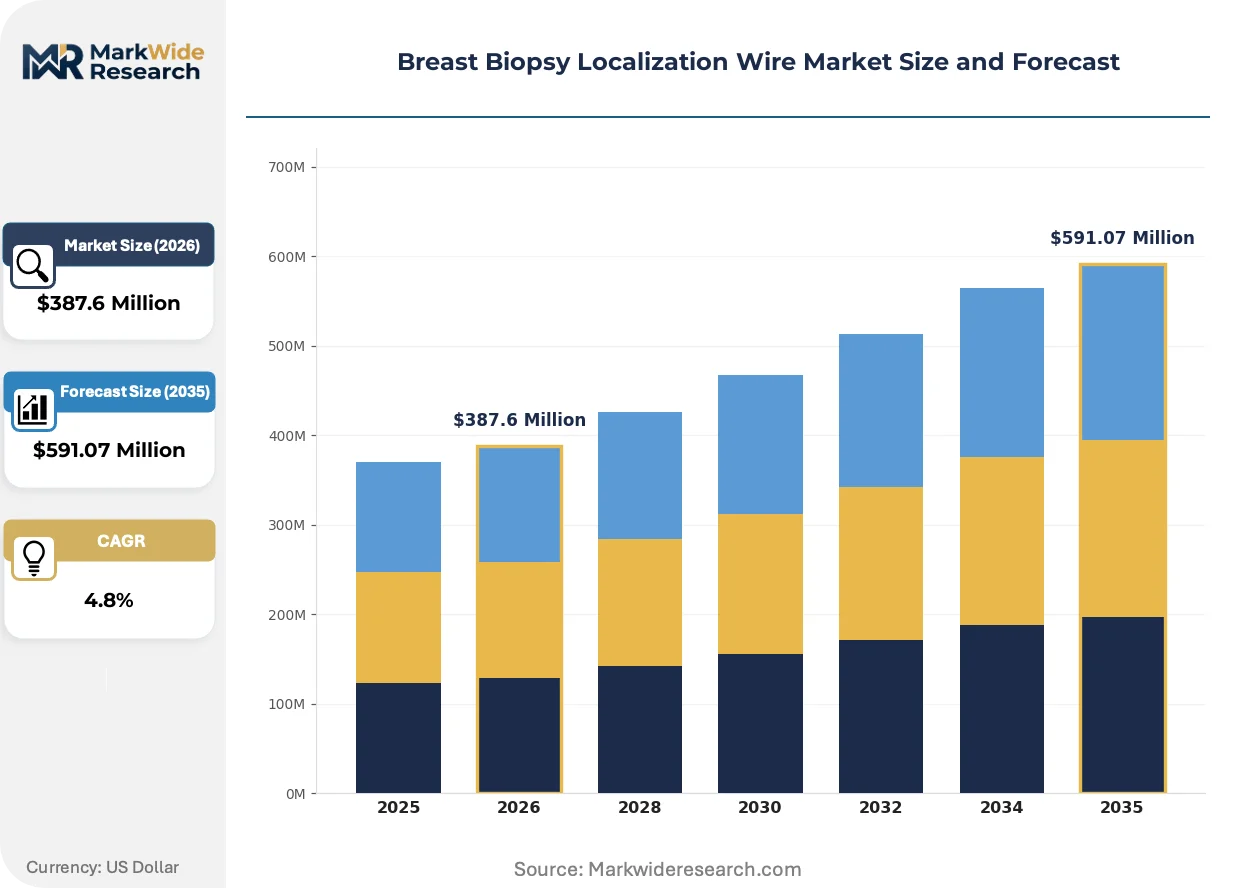
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
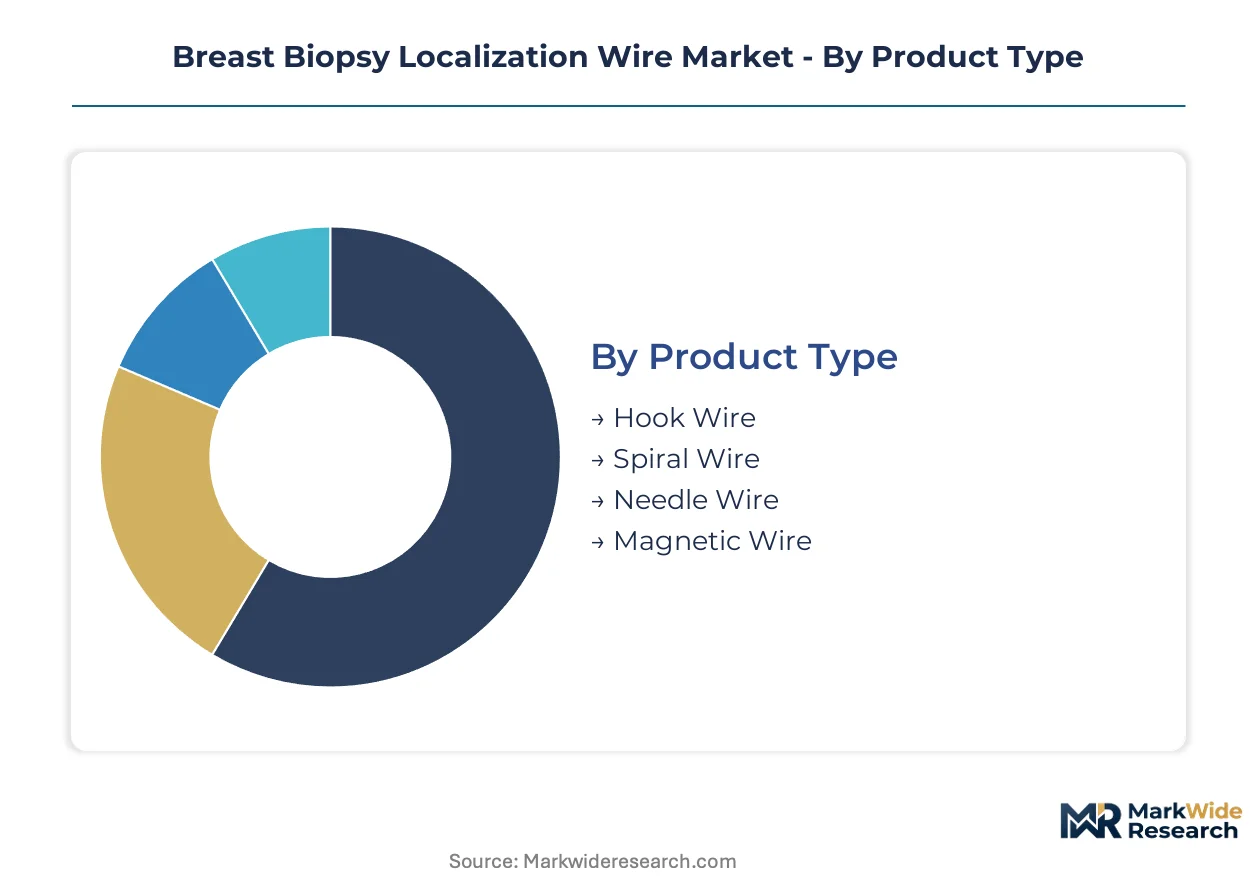
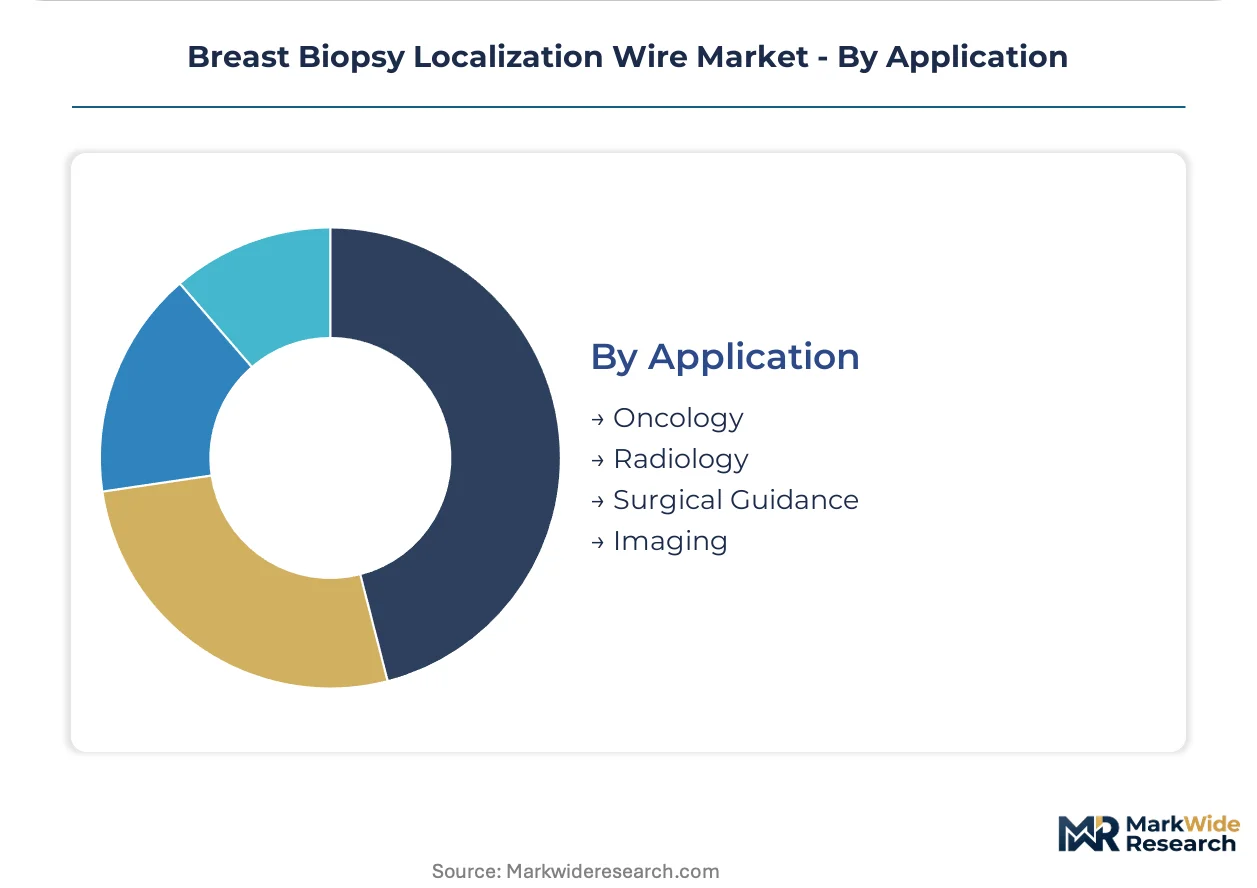
| Segmentation | Product Type: Hook Wire, Spiral Wire, Needle Wire, Magnetic Wire Material: Stainless Steel, Plastic, Titanium, Other Metals End User: Hospitals, Clinics, Diagnostic Centers, Surgical Facilities Application: Oncology, Radiology, Surgical Guidance, Imaging |
| Companies Covered | Hologic, Becton Dickinson and Company, Merit Medical Systems, Argon Medical Devices, Cook Medical, C R Bard, Leica Biosystems Nussloch GmbH, Ranfac, CP Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Biopsy Localization Wire Market Evolving Landscape
Wire localization technology is fragmenting into radiation-free, electromagnetic, and hybrid tracking modalities as facilities seek alternatives to traditional hook-wire systems. These shifts reshape equipment procurement criteria and service line economics.
Radioactive seed localization is hybridizing with electromagnetic detection platforms to eliminate gamma probe dependence. Academic medical centers in the United States are piloting dual-modality systems that combine magnetic seed placement with intraoperative wire guidance. This convergence is compressing the addressable market for pure-play radioactive tracer suppliers while expanding electromagnetic hardware revenue pools.
EU MDR recast requirements for implantable device Unique Device Identification mandate serialized wire tracking from manufacture to excision. German notified bodies are enforcing stricter biocompatibility testing for polymer-coated wires under ISO 10993-5 cytotoxicity protocols. Breast surgery departments across France, Italy, and Spain are restructuring supply chain documentation systems to comply with EUDAMED registration deadlines.
Same-day localization-to-surgery scheduling is displacing traditional multi-day wire placement protocols in United States ambulatory networks. Hospital outpatient departments are contracting directly with wire manufacturers to bypass distributor markups on high-volume disposable purchases. This channel compression is most visible in Texas, Florida, and California where freestanding breast centers capture rising shares of screening-detected lesion volumes.
Breast Biopsy Localization Wire Market Segmentation
Wire localization technology fragments across material compositions, tip geometries, and clinical settings. Procurement patterns diverge sharply between high-volume hospital systems and ambulatory networks seeking same-day throughput.
Product Type:
Mature hook-wire designs dominate procedure volumes while electromagnetic alternatives capture margin expansion in academic medical centers.
- Hook Wire:Stainless steel construction with distal barbs prevents migration during patient transport. United States hospital outpatient departments specify this format for bulk purchasing contracts under bundled payment structures.
- Magnetic Wire:Ferromagnetic core enables radiation-free detection via handheld probes. Diagnostic centers in dense breast tissue notification law states adopt this technology to eliminate radioactive tracer handling protocols.
- Spiral Wire:Coiled distal geometry distributes retention force across lesion margins.
- Needle Wire:Integrated cannula design suits ultrasound-guided placement workflows.
Hook Wire retains volume leadership; Magnetic Wire holds the steepest expansion curve.
Material:
Cost tiers separate commodity metals from specialized alloys with shape-memory properties.
- Stainless Steel:316L surgical grade dominates unit economics with established sterilization compatibility. Midwest United States contract sterilizers process gamma-irradiated stainless steel coils for nationwide distribution.
- Titanium:Nickel-titanium alloy delivers kink resistance and superelastic behavior. Aerospace demand cycles for nitinol create raw material price volatility affecting procurement planning.
- Plastic:Polymer-coated variants address nickel sensitivity concerns in European markets.
- Other Metals:Cobalt-chromium and platinum-iridium alloys serve niche magnetic resonance compatibility requirements.
Stainless Steel anchors procurement volumes; Titanium climbs the fastest on specialized procedure adoption.
End User:
Channel structure concentrates purchasing power while ambulatory expansion fragments demand.
- Hospitals:Integrated delivery networks negotiate single-source agreements spanning imaging systems and disposable wires. Texas and Florida health systems bypass distributor markups through direct manufacturer contracts.
- Diagnostic Centers:Freestanding breast imaging networks expand same-day localization capacity. California ambulatory networks capture rising shares of screening-detected lesion volumes.
- Clinics:Office-based practices adopt handheld ultrasound guidance for wire placement.
- Surgical Facilities:Ambulatory surgery centers streamline excision scheduling with morning placement protocols.
Hospitals command pricing leverage; Diagnostic Centers gain share fastest on network expansion.
Application:
Clinical workflow integration determines device specification requirements across service lines.
- Oncology:Breast surgery departments prioritize margin clearance precision in lesion excision. EU MDR Article 120 transition deadlines drive replacement demand for CE-marked devices in French and Italian hospitals.
- Radiology:Interventional radiology fellowship training gaps constrain procedure capacity expansion. ISO 13485 audit backlogs delay quality certification for contract manufacturers serving this channel.
- Surgical Guidance:Intraoperative wire tracking integrates with specimen radiography protocols.
- Imaging:Mammography suite scheduling constraints push placement toward ultrasound alternatives.
Oncology drives specification standards; Radiology expands most quickly on screening program growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals consume wire localization devices through bundled imaging contracts, while European facilities emphasize CE-marked polymer-coated alternatives; Indian diagnostic networks favor cost-optimized stainless steel hook wires for tier-2 city expansion.
United States
Dense breast tissue notification laws in Texas, Florida, and California drive supplemental screening volumes. FDA 510(k) clearance pathways govern predicate device requirements for novel tip geometries. Hospital outpatient departments in the Dallas-Fort Worth metroplex negotiate direct manufacturer contracts to bypass distributor markups on high-volume disposable purchases.
Germany
EU MDR Article 120 transition deadlines accelerate replacement demand for next-generation CE-marked devices. German notified bodies enforce ISO 10993-5 cytotoxicity protocols for polymer-coated wire variants. Breast surgery departments in Bavaria restructure supply chain documentation systems to comply with EUDAMED registration mandates.
France
Academic medical centers in Paris pilot dual-modality systems combining magnetic seed placement with intraoperative wire guidance. ANSM oversight aligns with EU MDR implantable device Unique Device Identification requirements. Lyon-based hospital networks expand same-day localization-to-surgery scheduling protocols.
India
Tier-2 and Tier-3 city hospital breast screening programs remain underpenetrated for wire localization systems. CDSCO medical device registration pathways shape import timelines for foreign manufacturers. Diagnostic imaging networks in Maharashtra and Gujarat expand ambulatory breast biopsy capacity with cost-optimized procurement.
Japan
PMDA premarket approval requirements govern wire device commercialization timelines. METI industrial policy supports domestic medical device manufacturing competitiveness. Tokyo and Osaka metropolitan hospital systems integrate wire localization into comprehensive breast cancer screening workflows.
Breast Biopsy Localization Wire Market Competitive Landscape
Capability concentration sits with integrated imaging-device manufacturers; scale advantage sits with diversified surgical needle suppliers. The market structures around three tiers: full-platform vendors controlling hospital purchasing decisions, broad surgical portfolio players cross-selling localization products, and interventional radiology kit specialists embedding wires into comprehensive workflows. Dominant competitive moves include backward integration into gamma sterilization services and single-source bundled contracts spanning imaging systems through disposable wires.
Among United States-based platform vendors, Hologic exemplifies the integrated imaging-to-biopsy archetype through mammography system control. Becton Dickinson and Company anchors the diversified surgical needle tier with cross-selling infrastructure. Merit Medical Systems occupies the interventional radiology specialist position with kit-based workflow integration. These three represent distinct competitive vectors rather than direct substitutability.
| Leading Market Players |
|---|
| Hologic |
| Becton Dickinson and Company |
| Merit Medical Systems |
| Argon Medical Devices |
| Cook Medical |
| C R Bard |
| Leica Biosystems Nussloch GmbH |
| Ranfac |
| CP Medical |
| Others |
Value Network & Pricing Analysis
Midwest United States gamma irradiation capacity concentration for contract sterilization services feeds directly into margin capture by sterilization providers rather than wire manufacturers or hospital purchasers. This geographic supply bottleneck enables sterilizers to command premium service rates that compress downstream device margins across the entire localization wire value chain.
Pricing Analysis
Long-term bundled contracts spanning imaging systems and disposable wires dominate hospital procurement, with single-source agreements replacing spot purchasing for high-volume accounts. Three-tier pricing structure across premium magnetic wire, standard stainless steel hook wire, and economy polymer-coated variants reflects certification grade differentiation and volume scale commitments. Cost compression in standard stainless steel segments is intensifying because integrated delivery networks negotiate direct manufacturer contracts to bypass distributor markups. Ambulatory diagnostic centers exhibit highest price sensitivity due to same-day throughput pressures, while academic medical centers show lowest sensitivity given magnetic seed technology adoption priorities.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as hospital procurement consolidation shifts working capital burden onto wire manufacturers and their component suppliers. Raw material sourcing draws from United States nitinol alloy producers, German precision wire drawing facilities, and Japanese polymer coating specialists for biocompatible surface treatments. Single-source vulnerability concentrates in Midwest gamma sterilization capacity, where three contract sterilizers process the majority of domestic device volumes. Distribution runs through specialized medical device distributors serving hospital networks, with direct manufacturer contracting bypassing traditional channels in Texas, Florida, and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology fragmentation across radiation-free electromagnetic and hybrid tracking modalities creates multiple viable competitive positions rather than winner-take-all consolidation. Ambulatory same-day localization expansion fragments demand sufficiently to support specialized entrants alongside integrated platform vendors.
For Market Incumbents: Insulate core hospital system relationships through backward integration into gamma sterilization services, capturing margin pools currently held by Midwest contract sterilizers. Deepen ISO 13485 quality management certification investments to accelerate contract manufacturer qualification timelines as notified body audit backlogs persist. Magnetic seed technology substitution threatens traditional hook-wire volumes; anchor switching costs through integrated mammography-to-biopsy platform control. For New Entrants and Emerging Players: Establish a beachhead in India Tier-2 and Tier-3 city diagnostic imaging networks, where breast screening program expansion outruns incumbent localization wire penetration. Target ultrasound-guided wire placement workflows for office-based practices seeking radiation-free alternatives without mammography suite capital investment. Pursue CDSCO registration pathways early to capture import timing advantages as Maharashtra and Gujarat ambulatory networks scale. For Investors and Strategic Acquirers: Capital is best deployed toward interventional radiology kit specialists with embedded wire localization workflows, given radiology fellowship pipeline constraints that limit procedure capacity expansion and protect incumbent revenue streams. Long-term viability hinges on electromagnetic tracking hardware revenue pools expanding faster than pure-play radioactive tracer markets contract. Watch FDA 510(k) clearance timeline compression for novel tip geometries as signal of regulatory pathway efficiency enabling faster competitive entry.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 120 deadlines force replacement demand for serialized device tracking compliance. |
| Hospital System Partnership | Direct contracting with Texas and Florida health systems bypasses distributor markups on disposable volumes. |
| Reimbursement Strategy | Bundled payment reform monitoring determines whether hospitals or outpatient clinics capture procedure economics. |
| Software Companion Development | Electromagnetic tracking platform integration enables radiation-free localization without gamma probe dependence. |
| FDA Submission | Premarket notification pathway efficiency for Class II devices shapes competitive entry timing against predicate requirements. |
Research Methodology
Initial hypotheses were tested against primary input from interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, hospital procurement contract filings, and EU MDR notified body conformity assessment records. Bottom-up demand modeling across end-user segments triangulated with top-down market sizing from device shipment data and imaging system installation bases.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning wire type, material composition, end-user channel, and application workflow integration. CAGRs were derived from procedure volume growth trajectories modulated by reimbursement stability and regulatory pathway efficiency. Forecast inputs incorporated dense breast tissue notification law expansion patterns and ambulatory surgical center capacity buildout rates.
Stress conditions across nickel-titanium alloy price volatility, gamma sterilization capacity constraints, and FDA clearance timeline variability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about screening program expansion and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Soft Contact Lenses Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Heel Incision Devices Market