
 Netherlands Respiratory Devices Market | 2026-2036
Netherlands Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Respiratory Devices Market Foresight
Market Context
Respiratory therapist workforce shortages in Dutch home care is bifurcating market growth between hospital-centric suppliers and portable device specialists. Koninklijke Philips N.V. leverages its integrated sleep and respiratory portfolio to dominate home CPAP distribution across the Netherlands. Drägerwerk AG anchors high-acuity ventilator placements in Dutch intensive care units through direct hospital contracting. ResMed Inc. differentiates via cloud-connected adherence platforms that sustain recurring revenue from Dutch sleep apnea patients.
Technical Definition and Structural Segments
Respiratory devices encompass mechanical and electromechanical systems designed to assist, monitor, or replace pulmonary function, typically operating at pressure ranges from 4-20 cm H₂O for positive airway support and flow rates adjustable to 60 L/min in emergency ventilation. These systems serve therapeutic, diagnostic, and life-support functions across acute, sub-acute, and domiciliary care environments. Inhalers and nebulizers retain the largest volume footprint within Dutch pharmacy and primary care channels, though margin pools concentrate in ventilators and CPAP devices where technical complexity and service contracts elevate profitability. Smart inhalers and wearable solutions represent the fastest-expanding technology tier, driven by Dutch reimbursement incentives for remote patient monitoring and pharmaceutical adherence tracking.
Regulatory Framework and Outlook
The Dutch healthcare regulator, operating under the EU Medical Devices Regulation (MDR) and coordinated with the Health and Youth Care Inspectorate (IGJ), enforces post-market surveillance and clinical evidence requirements that elevate barriers for non-compliant device entrants. CE marking under MDR Annex VIII classification rules governs market access for ventilators and active implantable respiratory accessories, while the Dutch Medicines Evaluation Board (CBG-MEB) intersects with combination products such as drug-device inhalers. Stakeholders must monitor evolving MDR transition timelines and IGJ enforcement priorities to calibrate product registration investments against Dutch market entry economics.
Market Dynamics
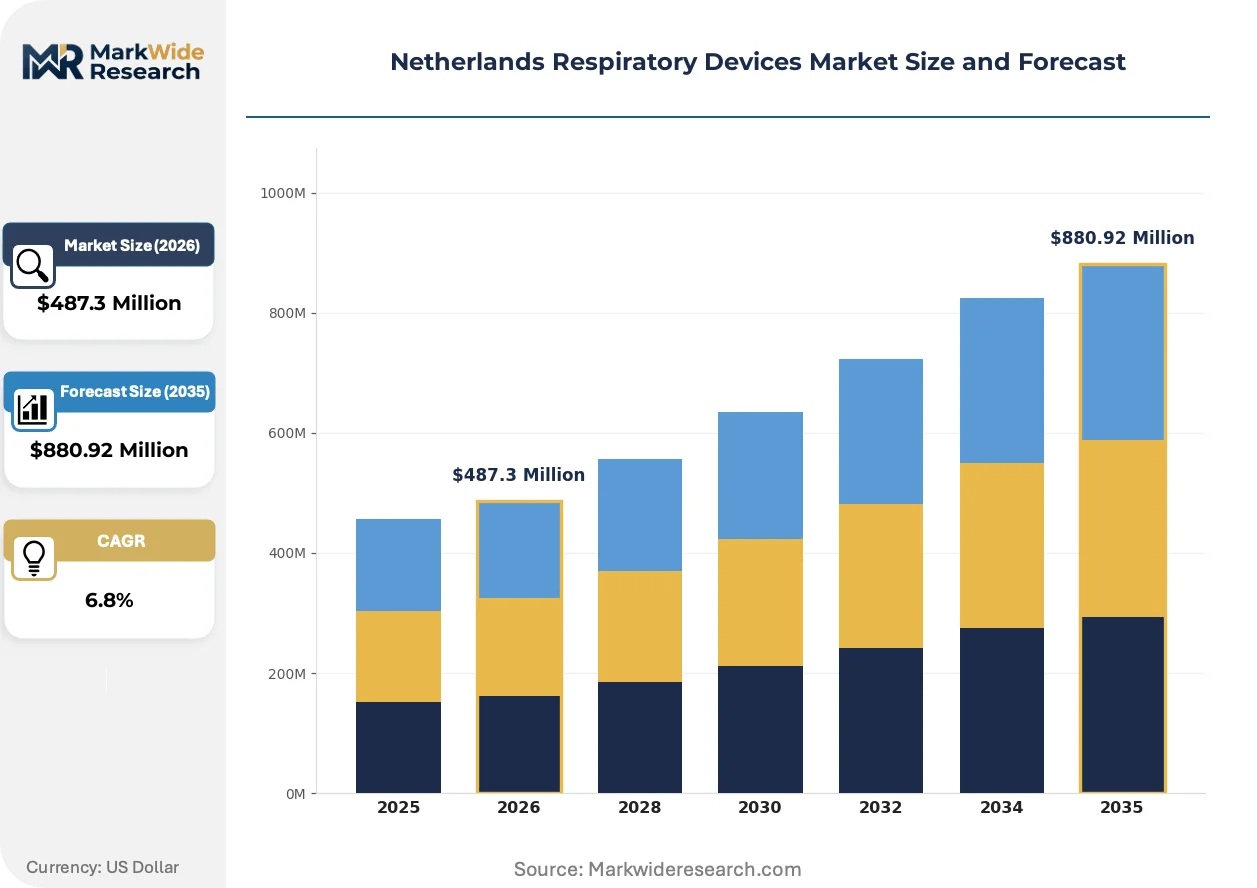
The Netherlands Respiratory Devices Market pivots on the MDR transition timeline, which is compressing product registration windows and forcing Dutch distributors to consolidate supplier relationships ahead of Annex VIII classification enforcement.
Growth Catalysts
- Remote patient monitoring reimbursement:Dutch health insurers now cover connected inhaler data transmission, accelerating pharmacy channel adoption of sensor-enabled devices.
- Randstad pulmonology density:Amsterdam-Rotterdam-The Hague corridor concentrates aging demographics with high COPD prevalence, creating concentrated demand pools for home ventilation.
- EU Green Deal medical device circularity:Sustainability mandates for device recyclability favor modular ventilator designs with replaceable components over disposable-heavy alternatives.
Market Restraints
- MDR clinical evidence requirements:The EU Medical Devices Regulation demands renewed clinical data for legacy ventilators, extending recertification timelines for Dutch importers.
- Semiconductor supply concentration:Flow sensor chip fabrication concentrates in East Asian foundries, exposing Dutch device assemblers to input volatility.
- Biologics substitution in severe asthma:Monoclonal antibody therapies reduce reliance on high-dose inhaled corticosteroids, compressing nebulizer utilization in tertiary centers.
Strategic Opportunities
- Underpenetrated Zeeland and Limburg provinces:Rural pulmonology deserts in southern Netherlands lack home care infrastructure, creating whitespace for mobile respiratory therapist networks.
- MDR transition service contracts:Technical file preparation and post-market surveillance outsourcing represents recurring revenue for Dutch regulatory consultancies.
- AI-integrated polysomnography:Machine learning diagnostic tools converge with home sleep testing, enabling direct-to-patient CPAP titration without laboratory infrastructure.
Industry Challenges
- Respiratory therapist workforce scarcity:Dutch vocational training programs produce insufficient qualified staff for expanding home care protocols.
- Legacy hospital IT integration:Cloud-connected CPAP platforms face interoperability friction with fragmented Dutch electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Respiratory Devices Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Ventilators, CPAP Devices Application: Asthma Management, COPD Treatment, Sleep Apnea Therapy, Emergency Care End User: Hospitals, Clinics, Home Care Settings, Long-Term Care Facilities Technology: Electronic Monitors, Smart Inhalers, Portable Devices, Wearable Solutions |
| Companies Covered | DeVilbiss Healthcare LLC, Drägerwerk AG, Fisher & Paykel Healthcare Ltd, GE Healthcare, Getinge AB, GlaxoSmithKline PLC, Koninklijke Philips N.V., ResMed Inc., Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Respiratory Devices Market Shifts & Advancements
Cloud-native device architectures are displacing standalone hardware as the default design paradigm, with Dutch reimbursement codes now explicitly favoring data-generating respiratory equipment over analog alternatives.
Mesh nebulizer technology is displacing traditional compressor-driven aerosol delivery in Dutch pediatric asthma management. Academic medical centers in Utrecht and Leiden adopt vibrating membrane platforms for precise particle sizing. This shift compresses the market for legacy jet nebulizers while elevating service contract value for precision cleaning and membrane replacement.
The EU Medical Devices Regulation tightens post-market surveillance for active implantable respiratory accessories, requiring Dutch notified bodies to expand clinical follow-up capacities. Ventilator manufacturers face expanded vigilance reporting obligations for software updates. High-acuity device segments absorb the heaviest compliance burden, with some Dutch hospitals deferring non-essential upgrades pending clarity on MDR transition timelines.
Dutch hospital procurement consortia consolidate purchasing power for ventilator fleets, shifting negotiations from device vendors to full-service respiratory management contracts. University Medical Center Utrecht and Erasmus MC anchor multi-year agreements bundling equipment, maintenance, and clinical training. This concentration pressures smaller Dutch regional hospitals to join purchasing cooperatives or accept standardized configurations.
Netherlands Respiratory Devices Market Segmentation
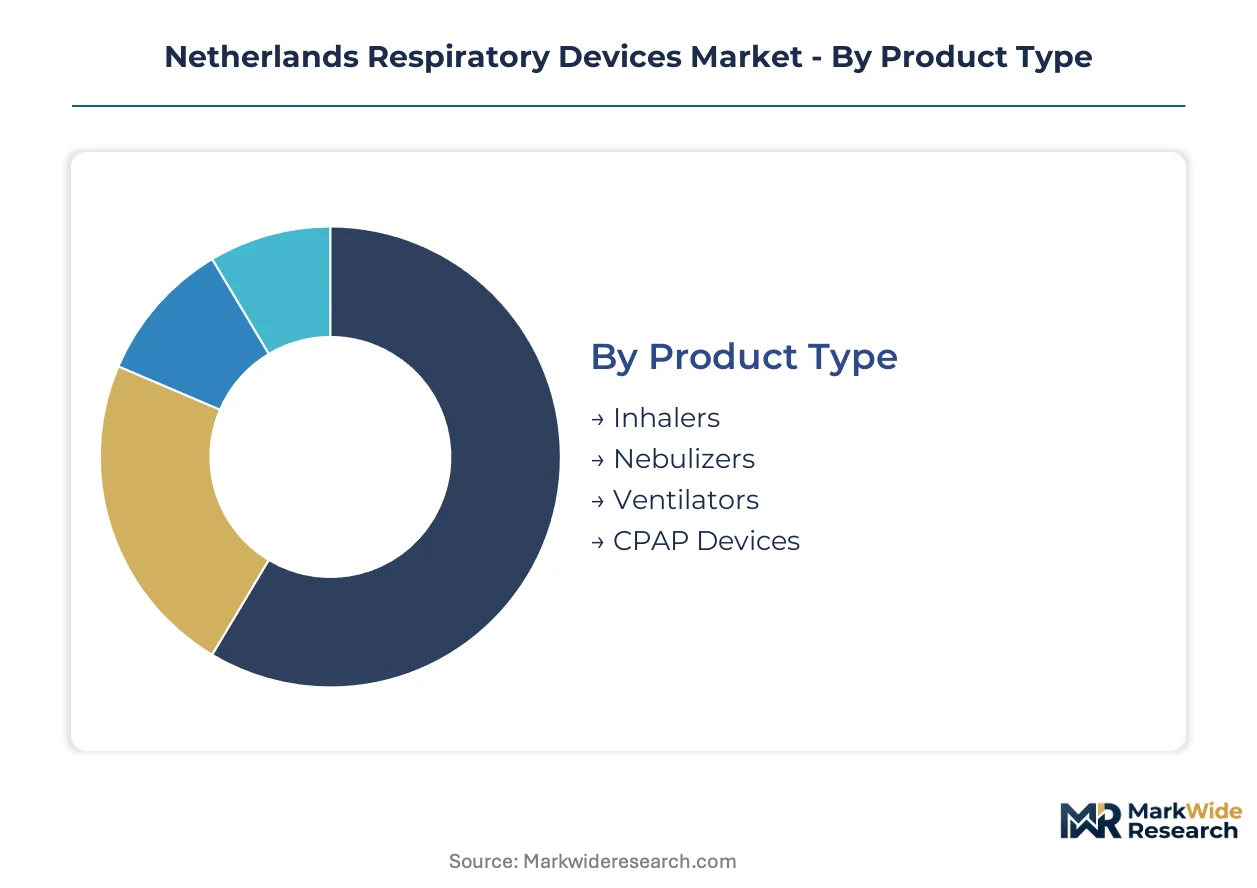
Segmentation reveals how Dutch reimbursement codes and MDR compliance costs concentrate profit pools across device categories. Understanding these structural divisions exposes where capital deployment yields sustainable returns versus commoditized volume plays.
Product Type:
Margin pools concentrate in ventilators and CPAP devices where technical complexity and service contracts elevate profitability above pharmacy-channel inhalers.
- Ventilators:High-acuity mechanical and electromechanical systems operate at pressure ranges from 4-20 cm H₂O with flow rates adjustable to 60 L/min for emergency ventilation. Dutch intensive care units at Erasmus MC and University Medical Center Utrecht anchor fleet purchasing through multi-year service contracts bundling equipment, maintenance, and clinical training. MDR Annex VIII classification rules impose renewed clinical evidence demands that extend recertification timelines.
- CPAP Devices:Continuous positive airway pressure systems for sleep apnea therapy now default to cloud-native architectures. Dutch health insurers explicitly favor data-generating equipment over analog alternatives, with remote patient monitoring reimbursement codes accelerating connected device adoption across Randstad metropolitan clusters.
- Inhalers:Drug-device combination products dominate Dutch pharmacy and primary care channels by volume. The Dutch Medicines Evaluation Board intersects with CBG-MEB oversight for these products.
- Nebulizers:Mesh technology displaces compressor-driven delivery in pediatric asthma management at Utrecht and Leiden academic centers.
Ventilators hold installed capacity. Smart inhalers are rotating up the share rankings.
Application:
Volume distribution tracks Dutch demographic clustering and pulmonology infrastructure density across provinces.
- Sleep Apnea Therapy:Machine learning diagnostic tools converge with home sleep testing, enabling direct-to-patient CPAP titration without laboratory infrastructure. Randstad aging demographics concentrate demand in Amsterdam-Rotterdam-The Hague corridor.
- COPD Treatment:Home care protocols expand as Dutch patients shift from institutional to domiciliary respiratory management. Rural pulmonology deserts in Zeeland and Limburg provinces create whitespace for mobile respiratory therapist networks.
- Asthma Management:Monoclonal antibody biologics reduce reliance on high-dose inhaled corticosteroids in tertiary centers.
- Emergency Care:High-acuity ventilator placements anchor through direct hospital contracting with intensive care units.
COPD treatment commands the largest addressable population base. Sleep apnea therapy is gaining share fastest.
End User:
Procurement authority concentrates in hospital consortia while growth vectors shift toward domiciliary channels.
- Home Care Settings:Dutch health insurers now cover connected inhaler data transmission, accelerating pharmacy channel adoption of sensor-enabled devices. Workforce shortages in respiratory therapy constrain expansion velocity.
- Hospitals:University Medical Center Utrecht and Erasmus MC anchor multi-year agreements bundling ventilator fleets, maintenance, and clinical training. Procurement consortia consolidate purchasing power across Dutch hospital networks.
- Clinics:Primary care channels handle inhaler and nebulizer volume distribution under pharmacy reimbursement frameworks.
- Long-Term Care Facilities:Aging demographics in Randstad clusters drive demand for portable ventilation support outside acute settings.
Hospitals retain capital equipment authority. Home care settings are climbing the fastest.
Technology:
Regulatory incentives under MDR and Dutch reimbursement codes favor data-generating architectures over standalone hardware.
- Smart Inhalers:Sensor-enabled devices with pharmaceutical adherence tracking qualify for remote patient monitoring reimbursement. Cloud-connected platforms sustain recurring revenue models.
- Wearable Solutions:The fastest-expanding technology tier combines respiratory monitoring with continuous data transmission. EU Green Deal circularity mandates favor modular designs with replaceable components.
- Portable Devices:Battery-powered systems enable domiciliary management across Dutch home care expansion protocols.
- Electronic Monitors:Flow sensor integration depends on East Asian semiconductor fabrication, exposing assemblers to input volatility.
Electronic monitors hold legacy installed base. Wearable solutions are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch provinces diverge sharply in respiratory device deployment, with metropolitan Randstad corridors favoring connected home-care platforms while southern and northern regions remain tethered to hospital-centric models due to workforce scarcity.
Randstad
Amsterdam-Rotterdam-The Hague corridor concentrates aging demographics with elevated COPD prevalence, driving demand for domiciliary ventilation and cloud-connected CPAP systems. Dutch health insurers explicitly favor data-generating equipment in this zone, accelerating reimbursement for remote patient monitoring. University Medical Center Utrecht and Erasmus MC anchor multi-year service contracts bundling ventilator fleets with clinical training.
Brabant
Eindhoven Region hosts Philips' integrated sleep and respiratory operations, creating localized supply chain density for home-care device distribution. The EU Medical Devices Regulation tightens post-market surveillance obligations here, with notified bodies expanding clinical follow-up capacities for active implantable accessories. Regional hospitals join procurement consortia to consolidate purchasing power against vendor concentration.
Eindhoven Region
High-tech manufacturing heritage supports precision nebulizer component fabrication, particularly vibrating membrane platforms for pediatric asthma management. Leiden academic medical centers adopt these systems for precise particle sizing. EU Green Deal circularity mandates favor modular ventilator designs with replaceable components over disposable-heavy alternatives in this industrial cluster.
Northern Netherlands
Groningen and Friesland provinces exhibit underpenetrated home care infrastructure relative to pulmonology demand, creating whitespace for mobile respiratory therapist networks. Workforce shortages in Dutch vocational training programs constrain expansion velocity here. Health and Youth Care Inspectorate enforcement priorities calibrate market entry economics for device distributors targeting rural coverage gaps.
Zeeland and Limburg
Rural pulmonology deserts in southern Netherlands lack home care protocols, preserving hospital-centric utilization patterns for emergency ventilation. Monoclonal antibody biologics reduce nebulizer utilization in tertiary centers, compressing device demand. MDR transition timelines delay non-essential upgrades as hospitals await clarity on recertification requirements.
Netherlands Respiratory Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling distribution infrastructure and service contract bundling while mid-scale players compete on portable device portability and pharmacy-channel volume. Three archetypes dominate: diversified health technology conglomerates with integrated sleep-respiratory portfolios; acute-care specialists anchoring high-acuity ventilator placements through direct hospital contracting; and cloud-native platform operators monetizing recurring adherence data revenue. Competitive moves concentrate on M&A to capture home-care distribution networks and strategic partnerships to secure semiconductor flow sensor supply.
Within the diversified conglomerate tier, Koninklijke Philips N.V. and GE Healthcare exemplify integrated leaders leveraging broad healthcare technology footprints to dominate procurement consortia negotiations. Drägerwerk AG occupies a position among acute-care specialists, anchoring high-acuity placements through direct relationships with Dutch intensive care units. ResMed Inc. represents the cloud-native archetype, sustaining recurring revenue models via connected adherence platforms. These three companies collectively illustrate how scale, specialization, and data architecture define competitive positioning across Dutch reimbursement and regulatory frameworks.
| Leading Market Players |
|---|
| DeVilbiss Healthcare LLC |
| Drägerwerk AG |
| Fisher & Paykel Healthcare Ltd |
| GE Healthcare |
| Getinge AB |
| GlaxoSmithKline PLC |
| Koninklijke Philips N.V. |
| ResMed Inc. |
| Medtronic |
| Others |
Supply & Pricing Matrix
EU Medical Devices Regulation Annex VIII classification gates both supplier qualification and price differentiation across Dutch respiratory device procurement. CE marking tiers separate premium ventilator vendors with full clinical evidence packages from economy-positioned competitors lacking post-market surveillance infrastructure, compressing margin pools at the lower tier while elevating service-contract value for compliant incumbents.
Pricing Analysis
Long-term service contracts dominate Dutch hospital procurement, with University Medical Center Utrecht and Erasmus MC anchoring multi-year agreements bundling equipment, maintenance, and clinical training. Price differentiation rests on MDR compliance tier and after-sales service depth, with fully-certified vendors commanding premiums over legacy importers facing recertification delays. Cost compression in the pharmacy-channel inhaler segment is intensifying because of sensor-enabled generic competition. Home care settings exhibit highest price sensitivity due to insurer reimbursement caps, while ICU ventilator buyers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor flow sensor chip fabrication for Dutch device assemblers, with East Asian foundries supplying pressure transducers and microcontroller units. Raw material dependencies span medical-grade polymers, precision-machined aluminum housings, and lithium-ion battery cells. Single-source vulnerability concentrates in semiconductor inputs, exposing assemblers to input volatility. Distribution runs through Philips-integrated direct channels for home CPAP, regional medical distributors for hospital ventilators, and pharmacy networks for inhaler volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dutch respiratory device penetration sits at early-cycle expansion, with remote patient monitoring reimbursement codes accelerating connected device adoption faster than workforce training pipelines can support.
For Market Incumbents: Secure MDR technical file completion ahead of Annex VIII enforcement deadlines to lock in hospital procurement consortium eligibility. Deepen backward integration into cloud platform infrastructure to defend against software-native entrants threatening recurring revenue models. Workforce scarcity in respiratory therapy constrains home care expansion velocity for all vendors. For New Entrants and Emerging Players: Lead with AI-integrated polysomnography tools targeting Zeeland and Limburg pulmonology deserts, where laboratory infrastructure gaps enable direct-to-patient CPAP titration without sleep center partnerships. Mobile respiratory therapist networks represent the most penetrable channel architecture. Reimbursement strategy alignment with Dutch health insurer data-transmission codes accelerates pharmacy channel access. For Investors and Strategic Acquirers: MDR transition timeline reshapes the acquisition landscape toward regulatory consultancies with recurring technical file preparation revenue and notified body relationships. Long-term viability favors targets with installed base migration pathways from legacy ventilators to cloud-native platforms. Watch IGJ enforcement priority shifts as the inflection signal for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Completion | CE marking under Annex VIII rules gates Dutch hospital procurement consortium access. |
| Cloud Platform Integration | Philips and ResMed architectures sustain recurring adherence revenue from Randstad sleep apnea patients. |
| Mobile Respiratory Therapist Networks | Zeeland and Limburg whitespace enables domiciliary coverage without fixed infrastructure investment. |
| AI Polysomnography Development | Machine learning diagnostic tools bypass laboratory bottlenecks in underpenetrated northern provinces. |
| Reimbursement Strategy Alignment | Dutch health insurer codes explicitly favor data-generating equipment over analog alternatives. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committees, GPO contracts managers, and respiratory therapists converged on the working assumptions underlying this analysis. Primary fieldwork with Dutch medical device distributors and IGJ regulatory specialists combined with secondary validation from EUDAMED device registrations, GPO contract databases, and CMS Medicare remote monitoring data. Bottom-up installed base estimates triangulated against top-down reimbursement code analysis across the analysis window.
Segmentation dimensions modeled include product type, application, end user, and technology tier across the projection horizon. CAGRs derived from regression analysis of historical adoption curves adjusted for MDR transition friction and workforce expansion constraints. Forecast inputs incorporated Dutch health insurer reimbursement schedule updates and pulmonology infrastructure density indices by province.
Forecasts assume regulatory continuity in EU MDR and Dutch IGJ enforcement regimes; material policy shifts would require re-modeling. Specific risks include semiconductor supply disruption, biologics substitution acceleration in severe asthma, and respiratory therapist training pipeline failures. Recalibration cycles align with material shifts in reimbursement codes and MDR transition clarity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Eye Examination Equipment Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Global Microcatheter Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
Global Otoscopes Market