
 Pannus Retraction Device Market | 2026-2036
Pannus Retraction Device Market Size, Share, and Industry Trends Forecast 2026-2036
Pannus Retraction Device Market Analytics
The EU Medical Device Regulation (MDR) is consolidating compliance requirements across European surgical device supply chains. Merit Medical Systems leverages its vertically integrated manufacturing footprint to sustain CE-marked product lines without third-party dependencies. Stetrix competes through specialized mechanical retraction portfolios purpose-built for ophthalmic microsurgery. Medtronic dominates hospital system procurement channels through bundled surgical platform contracts that incorporate pannus management accessories.
A pannus retraction device is a surgical instrument engineered to displace adipose abdominal tissue during procedures requiring unobstructed access to the operative field, typically constructed from medical-grade polymers or stainless steel with tension-adjustable locking mechanisms rated for sustained load bearing. The device serves primarily to eliminate manual retraction labor, reduce surgical site contamination risk, and standardize exposure geometry across variable patient anatomies. Single-use devices command the largest revenue share within product type segmentation, driven by infection control protocols and elimination of reprocessing validation costs. Electromechanical systems represent the fastest-expanding technology category, as surgeons seek programmable tension curves that reduce tissue trauma during extended procedures. Hospitals remain the dominant end-user channel, though ambulatory surgery centers are capturing disproportionate growth through streamlined procurement of disposable kits.
The FDA's Quality System Regulation and ISO 13485 framework govern device design controls and post-market surveillance obligations for manufacturers distributing in the United States. The EU MDR's enhanced clinical evidence requirements and Unique Device Identification mandates are extending time-to-market intervals and favoring incumbents with established notified body relationships. Japan's PMDA maintains distinct biocompatibility testing protocols that create incremental barriers for non-domestic entrants. Stakeholders must monitor evolving sterile processing guidelines at major hospital networks, as shifts toward disposable platforms versus reusable systems will determine capital allocation priorities across the supply base.
Market Dynamics
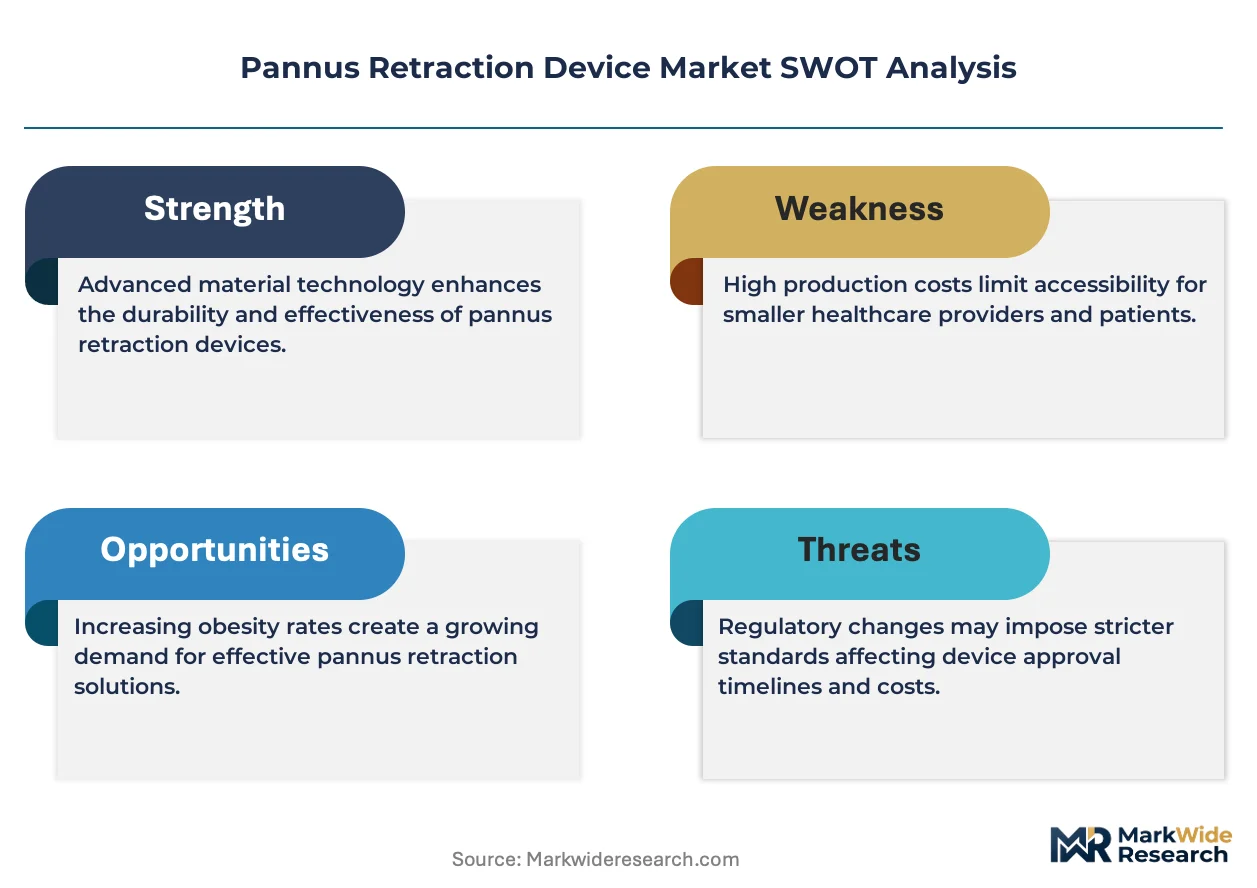
Single-use pannus retraction systems are displacing reusable stainless steel platforms as hospital infection control protocols harden and sterile processing costs escalate. This material transition is compressing capital equipment cycles while expanding recurring revenue pools for disposable manufacturers.
Growth Catalysts
- FDA Quality System Regulation:The agency's intensified scrutiny of reprocessing validation is accelerating hospital procurement of sterile single-use kits that eliminate sterilization documentation burdens.
- Bariatric surgery volume:Rising procedural counts in metabolic and weight-loss interventions are sustaining replacement demand for load-rated retraction systems across academic medical centers.
- Electromechanical tension control:Programmable force curves are reducing tissue trauma in extended ophthalmic procedures, expanding addressable procedure time windows.
Market Restraints
- Medical-grade polymer cost volatility:Specialized thermoplastic elastomer feedstock prices fluctuate with petrochemical indices, compressing gross margins on disposable platforms.
- EU MDR clinical evidence requirements:Extended notified body review timelines and enhanced biocompatibility testing protocols are delaying new product introductions by 18-24 months.
- Reusable system residual value:Stainless steel retractors with decades-long service life continue anchoring procurement in cost-constrained public hospital systems.
Strategic Opportunities
- Ambulatory surgery center expansion:Streamlined disposable kit procurement in outpatient settings is creating channel diversification beyond traditional hospital supply agreements.
- Japan PMDA pathway:Distinct biocompatibility testing protocols favor early entrants who establish domestic distributor relationships and localized technical files.
- Ophthalmic microsurgery convergence:Integration of pannus management with cataract and retinal platforms is opening bundled contract opportunities with integrated delivery networks.
Industry Challenges
- Notified body capacity scarcity:EU MDR implementation has concentrated certification reviews among fewer designated organizations, extending time-to-market for novel device iterations.
- Sterile processing workforce attrition:Hospital central supply departments face technician shortages that erode confidence in reusable system reprocessing quality, yet strain disposable budget allocations.
- Legacy equipment integration:Electromechanical retractors must interface with existing operating table rail systems and surgical boom architectures, constraining industrial design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pannus Retraction Device Market |
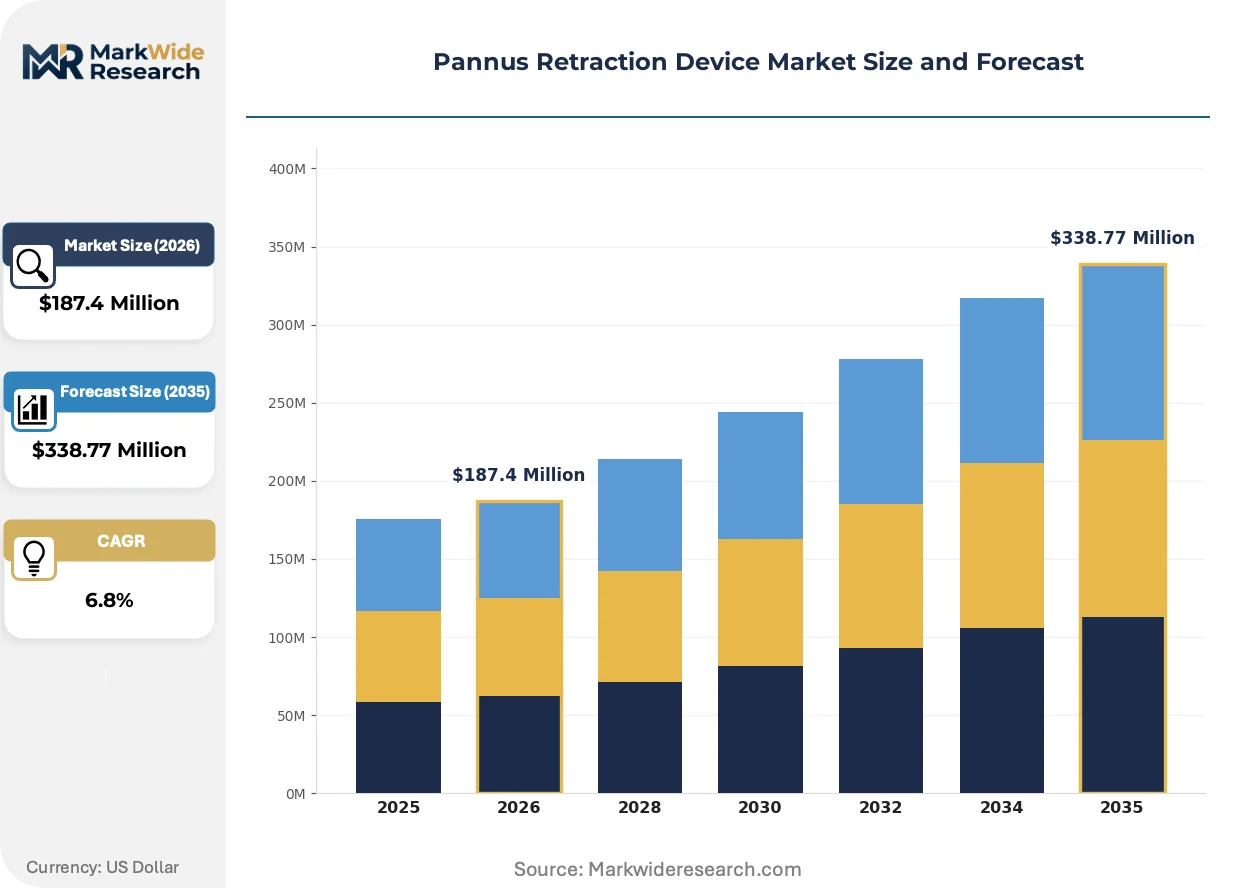
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Devices, Reusable Devices, Adjustable Systems, Fixed Systems Technology: Mechanical, Electromechanical, Laser-Based, Hybrid End User: Ophthalmic Clinics, Hospitals, Ambulatory Surgery Centers, Research Institutions Application: Eye Surgery, Cosmetic Procedures, Vision Restoration, Clinical Research |
| Companies Covered | Merit Medical Systems, Stetrix, Applied Medical Resources Corporation, Clinical Innovations, GSquared Medical, TZ Medical, Medtronic, Johnson & Johnson, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pannus Retraction Device Market Evolving Landscape
Active material science and regulatory harmonization efforts are compressing product development cycles while elevating performance benchmarks for tissue management systems. These forces are reshaping competitive positioning around sterile assurance and procedural efficiency.
Shape-memory polymer actuators are electrifying pannus retraction by replacing mechanical ratchets with thermally responsive elements that auto-adjust tension across patient respiratory cycles. Academic medical centers in the United States are piloting these systems in bariatric suites where sustained load duration exceeds four hours. The technology is electrifying competitive differentiation by eliminating manual readjustment labor and standardizing exposure geometry across variable adipose tissue distributions.
EU MDR Unique Device Identification mandates are forcing serialization infrastructure investments across European supply chains. Manufacturers must now maintain post-market surveillance databases traceable to individual device units, raising compliance costs disproportionately for mid-tier competitors. Single-use disposable lines face the steepest documentation burdens, driving consolidation toward vertically integrated producers with captive regulatory affairs capabilities.
Hospital procurement departments are unbundling after-sales service from capital equipment contracts, treating pannus retractors as consumable commodities rather than depreciated assets. Ambulatory surgery centers in the United States are leading this transition, negotiating direct distributor relationships that bypass manufacturer field service organizations. This behavioral shift is most visible in metropolitan markets where surgery center density supports consolidated purchasing cooperatives with sufficient volume to command price transparency.
Pannus Retraction Device Market Segmentation
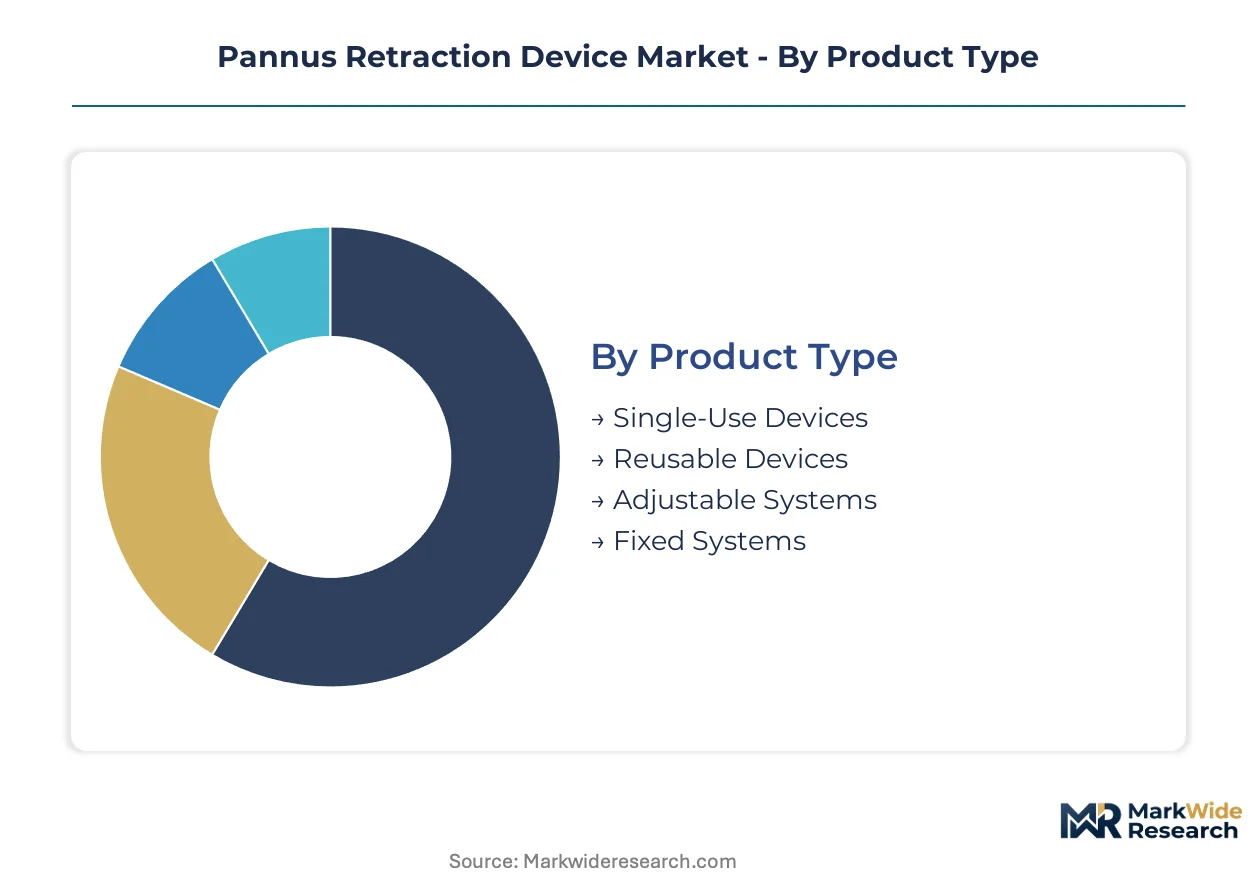
Segmentation in pannus retraction devices reveals how regulatory burden, procedural duration, and infection risk tolerance fragment procurement decisions across surgical settings. Each dimension carries distinct certification requirements and margin profiles that shape manufacturer portfolio strategy.
Product Type:
FDA's intensified scrutiny of reprocessing validation falls heaviest on reusable platforms, while single-use lines navigate sterility assurance documentation without sterilization cycle verification.
- Single-Use Devices:Constructed from medical-grade polymers with pre-sterilized packaging rated for immediate deployment. Demand concentrates in ambulatory surgery centers across the United States, where infection control protocols and elimination of reprocessing labor justify premium per-procedure costs.
- Reusable Devices:Fabricated from surgical stainless steel with tension-locking mechanisms designed for thousands of sterilization cycles. Procurement anchors in cost-constrained public hospital systems in Germany and France, where capital depreciation schedules and central supply infrastructure sustain long service-life economics.
- Adjustable Systems:Feature modular arm configurations adaptable to variable patient anatomies.
- Fixed Systems:Deploy rigid geometry optimized for standardized bariatric positioning protocols.
Leading the category by volume: Single-Use Devices. Growing fastest: Adjustable Systems.
Technology:
Cost tier stratification separates capital-intensive electromechanical platforms from disposable mechanical alternatives, with laser-based systems occupying a narrow premium niche in ophthalmic microsurgery.
- Mechanical:Ratchet-based tension systems requiring manual adjustment during procedures. Demand clusters in high-volume cataract centers in Japan, where PMDA biocompatibility testing favors established mechanical platforms with decades of clinical dossier accumulation.
- Electromechanical:Programmable force curves with sensor feedback enabling automated tension modulation. Academic medical centers in the United States pilot these systems for bariatric procedures exceeding four hours, where tissue trauma reduction justifies capital equipment investment.
- Laser-Based:Optical positioning guidance integrated with retraction arms for sub-millimeter precision.
- Hybrid:Combines mechanical reliability with electromechanical sensing in cost-optimized configurations.
Highest margin capture: Electromechanical. Steepest expansion trajectory: Hybrid configurations bridging cost and performance.
End User:
Customer type determines procurement channel structure, with hospitals negotiating bundled surgical platform contracts while ambulatory centers pursue streamlined disposable kit purchasing.
- Hospitals:Integrated delivery networks with centralized value analysis committees evaluating total cost of ownership. Procurement in the United States increasingly unbundles after-sales service, treating retraction devices as consumable commodities rather than depreciated capital assets.
- Ambulatory Surgery Centers:Outpatient facilities with streamlined supply chains and limited sterile processing capacity. Metropolitan clusters in Texas and Florida leverage purchasing cooperatives to command price transparency on disposable kits.
- Ophthalmic Clinics:Specialized retinal and cataract practices with procedure-specific retraction requirements.
- Research Institutions:Academic centers piloting shape-memory polymer actuators and novel tissue management protocols.
Dominant procurement volume: Hospitals. Disproportionate growth capture: Ambulatory Surgery Centers.
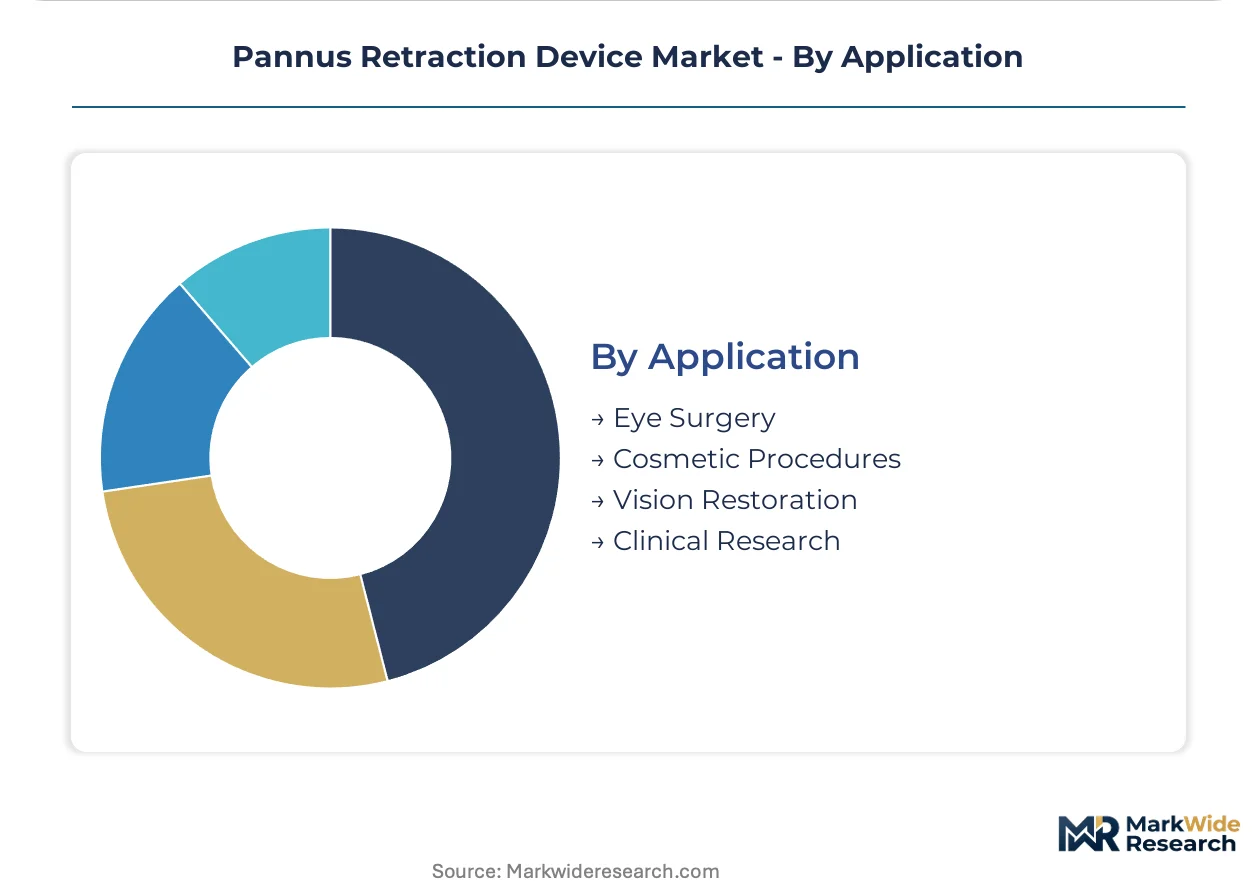
Application:
Procedure duration and tissue load requirements segment demand, with extended bariatric interventions requiring sustained load-bearing capacity versus brief ophthalmic exposures.
- Eye Surgery:Cataract extraction and retinal detachment repair demanding sub-millimeter positioning stability. Tension control precision drives electromechanical adoption in academic ophthalmology departments at Johns Hopkins and Bascom Palmer.
- Cosmetic Procedures:Abdominoplasty and body contouring with variable adipose tissue displacement requirements. Demand in South Korea's aesthetic surgery clusters favors adjustable systems accommodating diverse patient anthropometrics.
- Vision Restoration:Corneal transplantation and refractive procedures with specialized exposure geometry.
- Clinical Research:Investigational device trials and protocol development for novel retraction technologies.
Procedure volume leader: Eye Surgery. Technology upgrade intensity: Vision Restoration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in the United States and Germany while consumption spreads across surgical hubs in Japan and South Korea. This geographic split shapes regulatory compliance investments and distributor network strategies.
United States
Academic medical centers in Texas and Florida drive demand for electromechanical systems in bariatric suites exceeding four hours. FDA's intensified Quality System Regulation scrutiny of reprocessing validation accelerates hospital procurement of sterile single-use kits. Metropolitan surgery center clusters in Houston and Miami leverage purchasing cooperatives to command price transparency on disposable platforms.
Germany
Cost-constrained public hospital systems in Bavaria and North Rhine-Westphalia sustain procurement of reusable stainless steel retractors with decades-long service life. EU MDR's enhanced clinical evidence requirements and Unique Device Identification mandates extend time-to-market intervals for new product introductions. Industrial concentration around Stuttgart and Munich anchors vertically integrated manufacturing footprints serving CE-marked product lines.
Japan
PMDA maintains distinct biocompatibility testing protocols that create incremental barriers for non-domestic entrants in cataract and retinal surgery markets. High-volume ophthalmic centers in Tokyo and Osaka favor established mechanical platforms with accumulated clinical dossiers. Regulatory favoritism toward domestic distributors shapes localized technical file development strategies.
South Korea
Aesthetic surgery clusters in Seoul and Busan drive adjustable system demand for abdominoplasty and body contouring procedures with diverse patient anthropometrics. MFDS certification requirements align with international standards while permitting accelerated review for novel tissue management protocols. Metropolitan density supports direct procurement relationships bypassing traditional manufacturer field service organizations.
United Kingdom
Integrated delivery networks in London and Manchester evaluate total cost of ownership through centralized value analysis committees. NHS procurement frameworks increasingly unbundle after-sales service from capital equipment contracts. Research institutions in Cambridge and Oxford pilot shape-memory polymer actuators for extended-duration procedures.
Pannus Retraction Device Market Competitive Landscape
The competitive structure tilts toward diversified surgical platform conglomerates with bundled contract capabilities. Tier-one positions concentrate among manufacturers with captive regulatory affairs departments and established notified body relationships. Three strategic archetypes dominate: vertically integrated polymer processors, ophthalmic microsurgery specialists, and hospital supply channel consolidators. M&A activity targets mid-tier disposable manufacturers with EU MDR technical files in progress. Strategic partnerships between electromechanical developers and operating table OEMs address legacy equipment integration constraints.
Within the diversified medical technology tier, Merit Medical Systems and Medtronic exemplify scale-driven positioning through bundled surgical platform contracts. Stetrix occupies a specialist position purpose-built for ophthalmic microsurgery applications. Among capital equipment conglomerates, Stryker and Johnson & Johnson represent archetypal channel dominance through integrated delivery network procurement relationships. These named entities anchor industry-level commentary on competitive dynamics without asserting specific product-level or financial claims.
| Leading Market Players |
|---|
| Merit Medical Systems |
| Stetrix |
| Applied Medical Resources Corporation |
| Clinical Innovations |
| GSquared Medical |
| TZ Medical |
| Medtronic |
| Johnson & Johnson |
| Stryker |
| Others |
Value Network & Pricing Analysis
Ambulatory surgery center purchasing cooperatives in Texas and Florida command price transparency through consolidated volume, anchoring per-procedure disposable kit economics that squeeze manufacturer margins while accelerating single-use platform adoption.
Pricing Analysis
Margin tightening in electromechanical systems reflects polymer feedstock volatility and EU MDR compliance cost absorption. Three-tier pricing structure across premium electromechanical, standard single-use mechanical, and economy reusable stainless steel segments stratifies procurement. Cost-down pressure on disposable platforms intensifies as hospital networks unbundle after-sales service from capital contracts. Public hospital systems in Germany exhibit highest price sensitivity, while academic medical centers in the United States prioritize tissue trauma reduction over per-unit cost.
Supply Chain Analysis
Medical-grade thermoplastic elastomer supply rests on petrochemical processing clusters in the United States, Germany, and Japan with specialized compounding capabilities. Shape-memory polymer feedstock draws from academic research partnerships and limited commercial suppliers. Single-source vulnerability concentrates in sterilization packaging films. Distribution runs through GPO contracts and direct distributor relationships to hospital systems and surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical tension control systems are displacing mechanical ratchets in extended bariatric procedures, creating portfolio transition risk for stainless steel incumbent manufacturers.
For Market Incumbents: Hedge mechanical platform obsolescence by accelerating shape-memory polymer R&D partnerships and securing notified body pre-submission pathways for EU MDR technical files. Backward integration into medical-grade polymer compounding defends margin position against feedstock volatility. Channel control through bundled surgical platform contracts at integrated delivery networks remains the priority lever against unbundling procurement trends. For New Entrants and Emerging Players: Begin with ophthalmic microsurgery electromechanical systems at academic medical centers in the United States, where procedure duration and tissue trauma sensitivity justify premium positioning. Japan PMDA biocompatibility dossier gaps create white-space for domestic distributor partnerships. A software companion development strategy differentiates hardware commoditization pressures. For Investors and Strategic Acquirers: The window for entry favors mid-tier disposable manufacturers with EU MDR technical files in progress and established notified body relationships. Long-term viability hinges on sterile processing workforce attrition accelerating single-use adoption beyond current replacement cycles. Watch FDA Quality System Regulation enforcement intensity as the inflection signal for hospital procurement velocity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates sterile single-use kit market access ahead of reusable reprocessing scrutiny. |
| CE Marking Technical File Development | Secures EU MDR compliance for polymer actuator lines before notified body capacity constraints worsen. |
| Hospital System Partnership | Locks in ambulatory surgery center purchasing cooperatives with direct distributor relationships. |
| Software Companion Development | Enables programmable tension curve differentiation for electromechanical platforms at Johns Hopkins and Bascom Palmer. |
| Reimbursement Strategy | Aligns device coding with bariatric and ophthalmic procedure bundles in Medicare and commercial payer frameworks. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineering directors, GPO contracts managers, and sterile processing technicians underwrites the qualitative findings. Primary fieldwork combined with FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and CMS procedure volume data enables bottom-up and top-down triangulation.
Rate-of-change decomposition across the analysis window separates volume expansion from price-mix effects. Segmentation dimensions modeled include product type, technology tier, end-user channel, and application procedure duration. CAGRs derive from procedure volume trajectories, replacement cycle compression, and technology substitution elasticities. Inputs incorporate bariatric surgery growth rates and ophthalmic microsurgery platform integration timelines.
EU MDR implementation delays, polymer feedstock price spikes, and sterile processing workforce attrition are the dominant revision risks. Forecasts reflect documented assumptions about regulatory enforcement intensity and hospital capital budget allocation priorities. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Radiotherapy Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Medical Electronics Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Muscle Stimulator Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Male Artificial Urinary Sphincter Market