
 US Digital Therapeutics Market | 2026-2036
US Digital Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital Therapeutics Market Intelligence
FDA 510(k) and De Novo clearance pathways is redrawing competitive boundaries for market participants. Pear Therapeutics leverages its pioneer status in prescription digital therapeutics to sustain reimbursement relationships with major payers. Omada Health Inc. anchors employer-sponsored chronic disease programs with integrated coaching and remote monitoring capabilities. Teladoc Health extends its virtual care infrastructure to incorporate digital therapeutic modules alongside traditional telehealth consultations.
Digital therapeutics are evidence-based software interventions delivered to patients for preventing, managing, or treating medical conditions, requiring randomized controlled trial validation and regulatory authorization comparable to pharmaceutical products. The therapy area dimension shows diabetes and cardiology commanding established reimbursement codes while neurology applications build clinical evidence for broader coverage. Within product type, platform-based delivery captures enterprise health system contracts whereas standalone apps compete on direct-to-consumer subscription models.
FDA, CMS, and DEA frameworks collectively determine prescription status, reimbursement eligibility, and controlled-substance integration for digital therapeutic products. FDA's enforcement discretion policy distinguishes regulated medical device software from wellness applications, directly shaping which developers can access clinical revenue streams. Stakeholders must monitor evolving state-level telehealth prescribing rules and pharmacy benefit manager formulary decisions that will determine commercial scalability beyond initial regulatory clearance.
Market Dynamics
FDA's enforcement discretion policy for software-as-medical-device creates a bifurcated market where cleared prescription digital therapeutics access reimbursement while wellness apps compete on direct subscription revenue.
Growth Catalysts
- CMS reimbursement codes:Established billing pathways for remote patient monitoring enable health systems to integrate digital therapeutics into chronic care management workflows without operational friction.
- Diabetes prevalence concentration:California, Massachusetts, and New York health systems drive enterprise contracting for glucose management platforms as accountable care organizations seek alternatives to pharmaceutical escalation.
- Telehealth prescribing rules:State-level permanent extensions of pandemic-era remote prescribing authority expand addressable patient populations beyond traditional clinic-based distribution.
Market Restraints
- Clinical validation costs:Randomized controlled trial requirements comparable to pharmaceutical development create capital barriers exceeding fifty million dollars per therapeutic indication.
- Payer concentration risk:Pharmacy benefit manager formulary decisions at CVS Caremark, Express Scripts, and OptumRx determine commercial scalability irrespective of FDA clearance status.
- Physician workflow friction:Electronic health record integration complexity limits adoption in fee-for-service systems where documentation burden exceeds perceived clinical benefit.
Strategic Opportunities
- Neurology evidence accumulation:Post-traumatic stress disorder and substance use disorder applications build reimbursement precedent through VA health system pilot programs.
- DEA controlled-substance integration:Digital therapeutics paired with medication-assisted treatment for opioid use disorder access specialized reimbursement under substance use disorder carve-outs.
- Employer-sponsored channels:Self-insured corporations bypass payer intermediaries to contract directly for integrated coaching and remote monitoring capabilities.
Industry Challenges
- Behavioral health specialist scarcity:Licensed clinical social worker and psychologist shortages constrain the human coaching components required for chronic disease platform efficacy.
- HIPAA compliance architecture:Real-time biometric data transmission from patient devices to cloud platforms demands continuous security investment as attack surfaces expand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital Therapeutics Market |
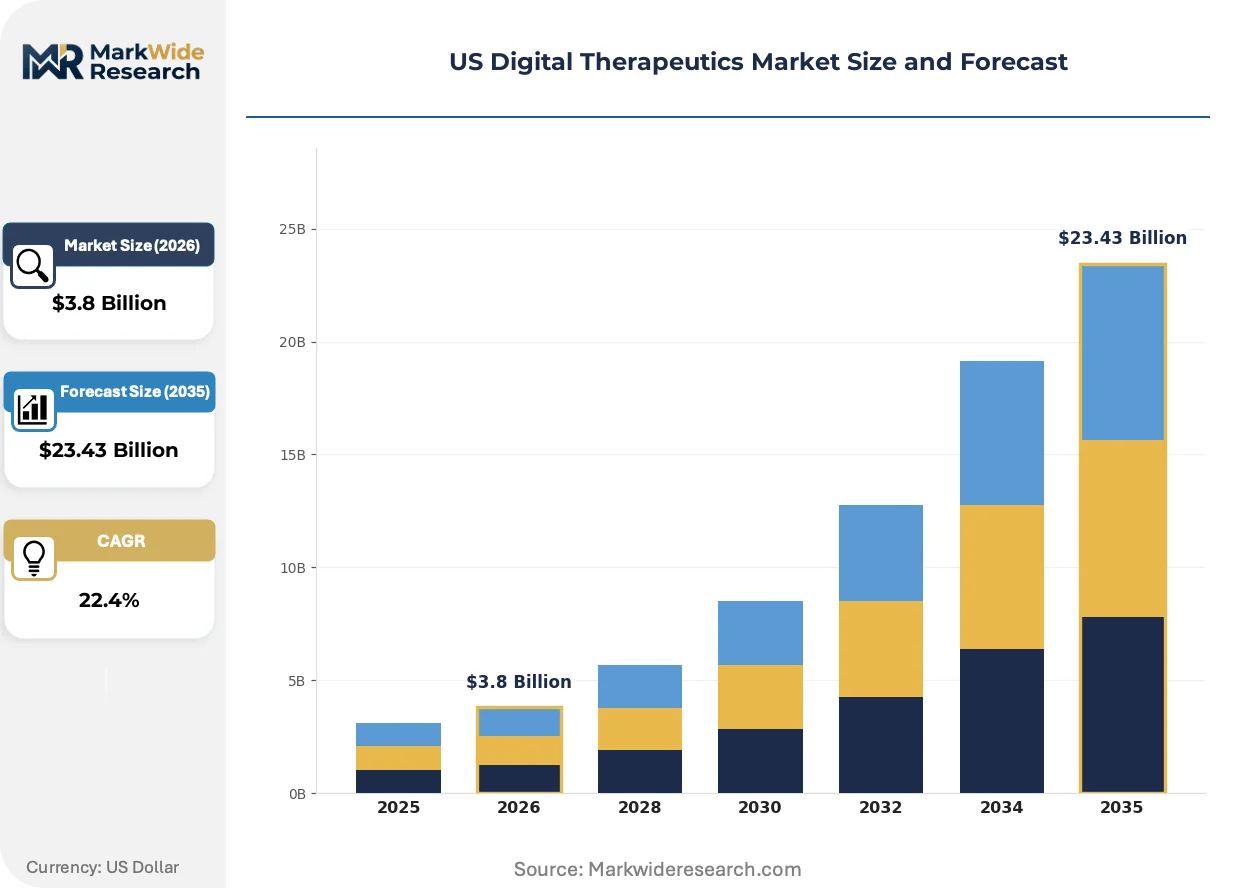
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.43 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apps, Wearables, Platforms, Software Therapy Area: Neurology, Psychiatry, Cardiology, Diabetes End User: Pediatric, Adult, Geriatric, Healthcare Providers Delivery Mode: Remote Monitoring, Self-Management, In-Person, Online |
| Companies Covered | Omada Health Inc., Pear Therapeutics, Teladoc Health, 2Morrow Inc., Welldoc, Click Therapeutics, Noom, Akili, Better Therapeutics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital Therapeutics Market Strategic Shifts & Innovations
Sensor-embedded wearable hardware and adaptive algorithm architectures are compressing development cycles while FDA's software precertification pilot reshapes validation requirements for iterative product updates.
Continuous glucose monitoring integration is miniaturizing the data capture infrastructure required for diabetes digital therapeutics. Health systems in Texas and Florida are deploying combined hardware-software bundles that eliminate separate device procurement processes. The technology is miniaturizing patient onboarding from multi-week clinical protocols to same-day smartphone activation.
FDA's De Novo pathway for novel device types establishes predicate-clearance frameworks that subsequent entrants leverage for streamlined 510(k) submissions. The industrial consequence accelerates competitive entry in established therapeutic categories while concentrating pioneer advantages in neurology and respiratory indications. Cardiology applications face compressed exclusivity windows as follow-on filings reference initial clearance decisions.
Self-insured employers are unbundling traditional disease management contracts to procure digital therapeutic modules through standalone subscription agreements. Benefits consultants at Mercer and Willis Towers Watson are displacing legacy health plan intermediaries with direct vendor curation services. This restructuring is most visible in Fortune 500 manufacturing and technology sectors seeking measurable return-on-investment metrics for wellness program spending.
US Digital Therapeutics Market Segmentation
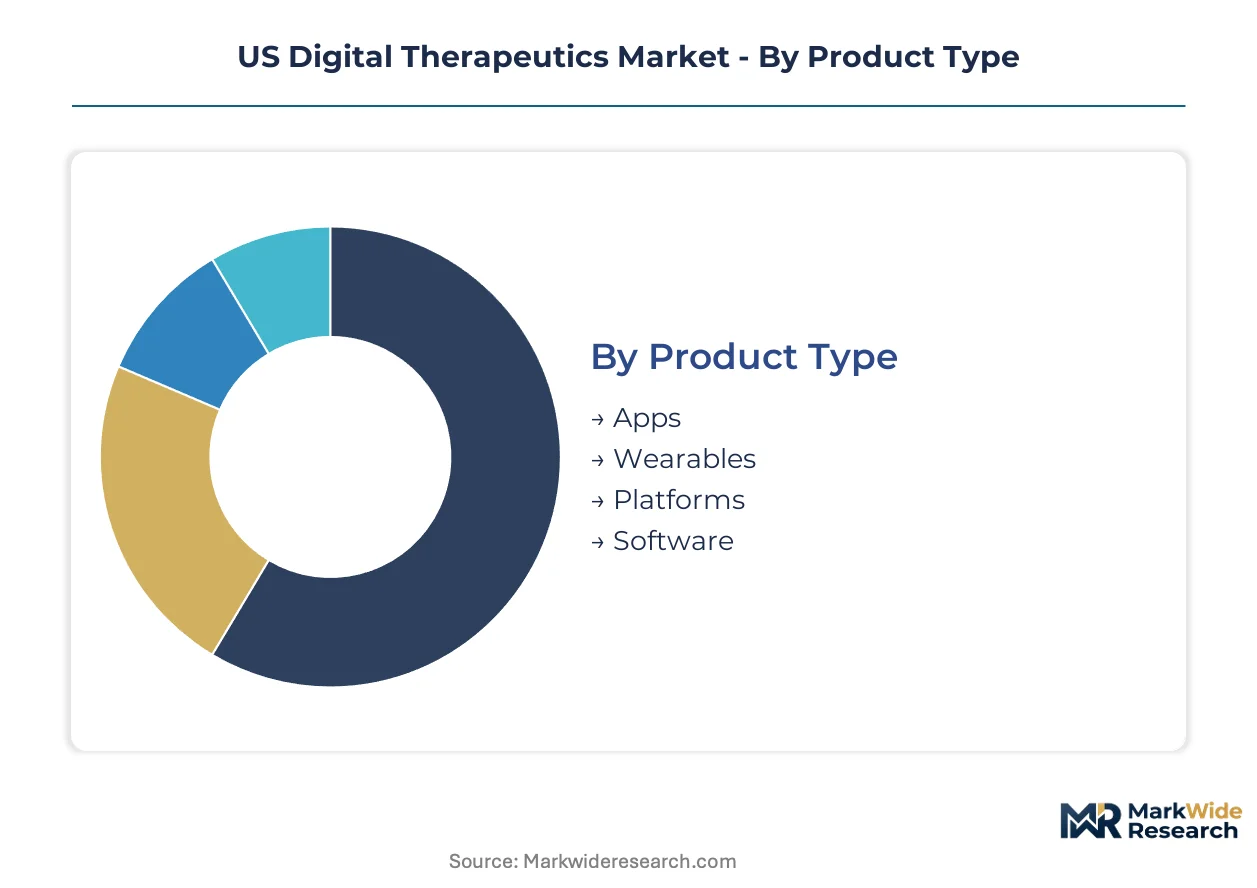
Segmentation in the US digital therapeutics market determines reimbursement pathways, regulatory requirements, and go-to-market strategy. Product architecture and therapy area selection dictate whether developers pursue FDA 510(k) clearance or direct-to-consumer distribution.
Product Type:
Platform-based offerings face the strongest substitution pressure from standalone apps that bypass enterprise procurement cycles.
- Platforms:Integrated software ecosystems combine patient-facing interfaces with clinician dashboards and EHR connectivity. California and Massachusetts health systems contract for platform deployments that bundle remote monitoring with care coordination services.
- Apps:Smartphone-delivered interventions operate on direct-to-consumer subscription models outside FDA enforcement discretion boundaries. CVS Caremark formulary decisions rarely cover app-only products lacking clinical trial validation comparable to pharmaceutical standards.
- Wearables:Sensor-embedded hardware captures biometric data streams for algorithm-driven therapeutic adjustments.
- Software:Cloud-based therapeutic engines process patient inputs to generate personalized intervention protocols.
Platforms retain volume leadership; apps hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates diabetes and cardiology applications with established CMS reimbursement codes from neurology indications still building clinical evidence.
- Diabetes:Continuous glucose monitoring integration enables real-time insulin dosing recommendations validated in randomized controlled trials. New York health systems deploy diabetes platforms as alternatives to pharmaceutical escalation within accountable care organization contracts.
- Cardiology:Heart failure and hypertension modules access remote patient monitoring billing codes that offset deployment costs for hospital systems. FDA 510(k) predicates in cardiology compress exclusivity windows as follow-on entrants reference initial clearance decisions.
- Neurology:Post-traumatic stress disorder and substance use disorder applications accumulate evidence through VA health system pilot programs.
- Psychiatry:Depression and anxiety interventions compete with traditional behavioral health services in employer-sponsored benefit designs.
Diabetes commands the deepest reimbursement integration; neurology is climbing the fastest toward coverage parity.
End User:
Application maturity varies sharply across patient demographics, with geriatric populations presenting the highest onboarding friction due to technology literacy gaps.
- Healthcare Providers:Hospital systems and physician practices require EHR-integrated workflows that minimize documentation burden. Texas medical centers prioritize platforms with Epic and Cerner compatibility to sustain fee-for-service productivity metrics.
- Adult:Working-age patients access digital therapeutics through employer-sponsored channels that bypass traditional payer intermediaries. Fortune 500 self-insured corporations contract directly with vendors for integrated coaching and biometric monitoring capabilities.
- Pediatric:Adolescent-focused interventions address attention-deficit disorders and behavioral health conditions.
- Geriatric:Senior-facing platforms require simplified interfaces and caregiver proxy access to achieve adherence thresholds.
Healthcare providers drive enterprise contract value; adult populations deliver the broadest addressable base.
Delivery Mode:
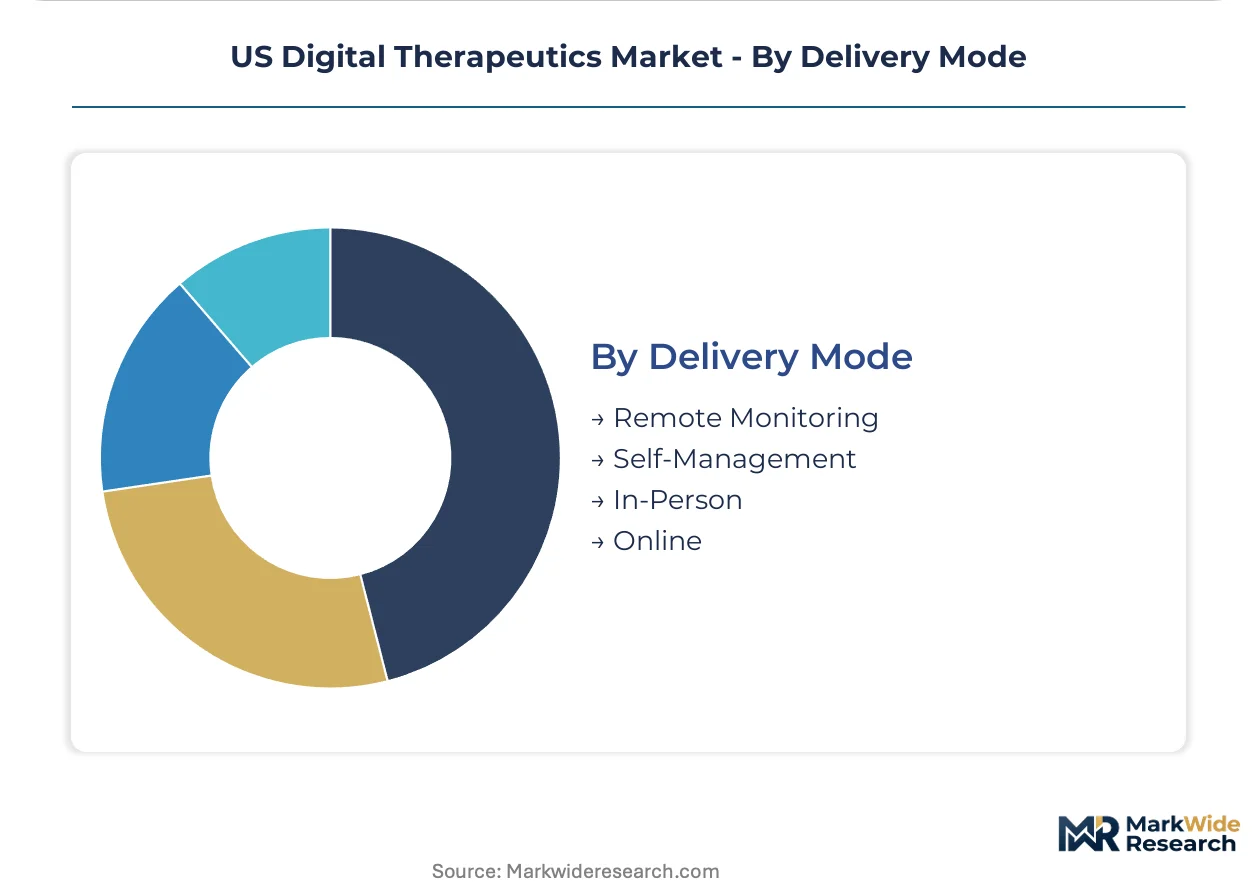
Geographic concentration of telehealth prescribing authority creates uneven access patterns across state regulatory environments.
- Remote Monitoring:Biometric data transmission to cloud platforms enables asynchronous clinician oversight with established CMS billing pathways. Florida health systems deploy combined hardware-software bundles that eliminate separate device procurement processes.
- Self-Management:Patient-directed interventions without real-time clinician involvement operate on wellness-app regulatory frameworks outside FDA medical device jurisdiction.
- In-Person:Clinic-based digital therapeutic administration supports controlled-substance integration for medication-assisted treatment protocols.
- Online:Synchronous video-delivered therapeutic sessions blend telehealth consultation with software-based intervention modules.
Remote monitoring captures the highest reimbursement rates; self-management is gaining share fastest through direct subscription channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and self-insured employers concentrate purchasing power in coastal states with established accountable care organization infrastructure and progressive telehealth prescribing frameworks.
California
Stanford Health Care and Kaiser Permanente deploy diabetes platforms as alternatives to pharmaceutical escalation within value-based contracts. FDA 510(k) clearance holders access Medi-Cal reimbursement pathways for remote patient monitoring. The San Francisco Bay Area anchors venture capital flows into prescription digital therapeutic startups seeking De Novo pathway validation.
Massachusetts
Mass General Brigham and Beth Israel Lahey Health contract for integrated coaching platforms that bundle biometric monitoring with care coordination services. Massachusetts Health Policy Commission mandates digital health cost-effectiveness reviews for state employee benefit designs. The Cambridge-Boston corridor concentrates clinical trial infrastructure for neurology applications building PTSD and substance use disorder evidence.
New York
NewYork-Presbyterian and Mount Sinai Health System integrate cardiology modules with Epic EHR workflows to capture remote patient monitoring billing codes. New York State Department of Financial Services regulates pharmacy benefit manager formulary transparency for digital therapeutic coverage decisions. The New York City metro area drives employer-sponsored contracting among Fortune 500 financial services and media corporations.
Texas
Houston Methodist and Baylor Scott & White Health prioritize platform compatibility with Cerner and Epic systems to sustain fee-for-service productivity metrics. Texas Medical Board permanent telehealth prescribing rules expand addressable populations for asynchronous clinician oversight models. The Dallas-Fort Worth metroplex concentrates self-insured employer procurement from manufacturing and energy sector benefits managers.
Florida
AdventHealth and Baptist Health South Florida deploy combined hardware-software bundles that eliminate separate continuous glucose monitoring device procurement processes. Florida Agency for Health Care Administration Medicaid managed care contracts incorporate digital therapeutic adherence metrics into quality incentive calculations. The Miami-Dade health system cluster pilots geriatric-facing platforms with simplified interfaces and caregiver proxy access.
US Digital Therapeutics Market Key Industry Players
Player mix skews toward venture-backed health technology specialists with FDA clearance experience and legacy telehealth platforms extending into therapeutic modules. Market structure concentrates around prescription digital therapeutic pioneers with established payer relationships and employer wellness vendors with direct contracting capabilities. Strategic archetypes include FDA 510(k) clearance specialists, integrated coaching platform operators, and virtual care infrastructure extenders. Dominant competitive moves encompass strategic partnerships with pharmacy benefit managers and portfolio diversification into adjacent remote monitoring categories.
Within the FDA clearance specialist tier, Pear Therapeutics and Welldoc occupy positions as early movers in prescription digital therapeutic authorization pathways. Among integrated coaching platform operators, Omada Health Inc. exemplifies the employer-sponsored chronic disease management archetype. Teladoc Health represents the virtual care infrastructure extension model, incorporating therapeutic modules alongside traditional telehealth consultation services.
| Leading Market Players |
|---|
| Omada Health Inc. |
| Pear Therapeutics |
| Teladoc Health |
| 2Morrow Inc. |
| Welldoc |
| Click Therapeutics |
| Noom |
| Akili |
| Better Therapeutics |
| Others |
Cost & Logistics Intelligence
FDA 510(k) and De Novo clearance pathways gate both supply qualification and price differentiation simultaneously, separating prescription digital therapeutics with reimbursement access from direct-to-consumer wellness applications competing on subscription revenue alone. This regulatory bifurcation concentrates pricing power among cleared developers while forcing uncertified entrants toward low-margin consumer channels.
Pricing Analysis
Cost-plus contracts with CMS reimbursement code indexation anchor enterprise pricing for platform-based offerings, while direct-to-consumer apps compete on monthly subscription tiers without billing pathway support. Price differentiation rests on FDA clearance tier and EHR integration depth, with Epic-compatible platforms commanding premium positioning against standalone smartphone interventions. Pricing pressure stems from pharmacy benefit manager formulary consolidation at CVS Caremark, Express Scripts, and OptumRx, which narrows covered indications irrespective of regulatory status. Self-insured employers show least price sensitivity through direct contracting, whereas individual consumers in app marketplaces exhibit highest elasticity to subscription costs.
Supply Chain Analysis
Cloud infrastructure concentration in AWS, Microsoft Azure, and Google Cloud Platform creates a chokepoint for algorithm hosting and real-time biometric data processing at enterprise scale. Raw material dependencies center on sensor-embedded wearable hardware from Asian manufacturing clusters, specialized encryption modules for HIPAA compliance, and continuous glucose monitoring device components. Single-source vulnerability runs through concentrated cloud service providers, where outage or pricing restructuring would cascade across deployed therapeutic platforms. Distribution feeds from direct health system procurement cycles and employer benefits consultant channels, bypassing traditional pharmaceutical wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prescription digital therapeutics represent high-growth disruption against pharmaceutical chronic disease management, accelerated by FDA software precertification pilots compressing validation timelines for iterative algorithm updates.
For Market Incumbents: Secure reimbursement code expansion through CMS remote patient monitoring pathway lobbying, while defending platform position against standalone app substitution via EHR integration depth at Epic and Cerner. Threat concentration sits with pharmacy benefit manager formulary exclusion; vertical integration into employer direct contracting offsets payer intermediary risk. For New Entrants and Emerging Players: Lead with neurology evidence accumulation in PTSD and substance use disorder, where VA health system pilot programs offer penetrable reimbursement precedent ahead of commercial payer coverage. White-space concentration in Texas and Florida health systems deploying combined hardware-software bundles for diabetes management. Go-to-market angle: simplified onboarding protocols compressing patient activation from multi-week clinical protocols to same-day smartphone deployment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across randomized controlled trial requirements, where validation costs exceeding fifty million dollars per indication filter venture-scale entrants toward platform consolidation. Long-term viability favors FDA 510(k) clearance holders with established payer relationships over direct-to-consumer subscription models facing churn saturation. Acquisition target archetype: integrated coaching platforms with biometric monitoring capabilities and Fortune 500 employer contracts. Signal to watch: DEA controlled-substance integration approvals for medication-assisted treatment pairings, which unlock specialized reimbursement carve-outs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Pathway Submission | Establishes predicate-clearance frameworks that subsequent entrants leverage for streamlined 510(k) submissions in cardiology. |
| Hospital System Partnership | California and Massachusetts health systems contract for platform deployments bundling remote monitoring with care coordination. |
| Reimbursement Strategy | CMS remote patient monitoring billing codes offset deployment costs for hospital systems in New York and Texas. |
| Software Companion Development | Continuous glucose monitoring integration miniaturizes data capture infrastructure for diabetes platform activation. |
| Strategic Partnership | Benefits consultants at Mercer and Willis Towers Watson displace legacy health plan intermediaries with direct vendor curation. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and De Novo submission databases, CMS reimbursement code filings, and hospital procurement contract records. Primary inputs drew from regulatory affairs specialists at prescription digital therapeutic developers, formulary directors at pharmacy benefit managers, and biomedical engineers integrating platforms with Epic and Cerner EHR systems. Secondary validation incorporated ClinicalTrials.gov registration data, SEC filings from publicly traded virtual care platforms, and GPO contract databases tracking health system purchasing patterns. Bottom-up therapeutic indication sizing triangulated against top-down market aggregation across product type and therapy area segments.
Segmentation dimensions modeled span product architecture, therapy area, end user demographic, and delivery mode across the projection horizon. Analytical framework derived CAGRs through indication-level revenue build-ups validated against payer coverage expansion trajectories and health system deployment timelines. Forecast inputs incorporated state-level telehealth prescribing rule permanence, FDA software precertification pilot expansion scope, and employer-sponsored benefit design unbundling velocity.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement code stability and progressive telehealth prescribing authority would require recalibration. Forecasts reflect assumptions regarding clinical trial success rates, pharmacy benefit manager formulary inclusion timelines, and EHR integration adoption curves. Revision becomes warranted when FDA enforcement discretion policy shifts materially alter the regulated medical device software boundary.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Global Metaverse in Healthcare Market
Digital Health Solutions
GCC E-Health Market
Digital Health Solutions
Telepsychiatry Software Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Long Term Care Software Market