
 AI Health and Fitness Products Market | 2026-2036
AI Health and Fitness Products Market Size, Share, and Industry Trends Forecast 2026-2036
AI Health and Fitness Products Market Insights
Subscription-based leasing models for smart fitness hardware is reconfiguring capital deployment across the competitive landscape. Peloton Interactive leverages asset-light financing partnerships to reduce consumer entry barriers. Apple sustains premium positioning through vertical integration of its wearable ecosystem. Samsung Electronics anchors manufacturing scale across multiple device categories simultaneously.
AI health and fitness products encompass sensor-embedded hardware and algorithm-driven software that process biometric data through machine learning pipelines to generate personalized workout, recovery, and nutritional recommendations. These systems typically integrate accelerometers, photoplethysmography sensors, and gyroscopes sampling at 100–500 Hz to capture physiological signals for real-time coaching feedback. Wearable devices and smart equipment capture the dominant share of current revenue, while virtual trainers represent the fastest-expanding margin pool due to minimal incremental delivery cost per user. Machine learning and predictive analytics segments attract disproportionate R&D investment because algorithmic differentiation directly determines subscription retention rates.
The FDA software-as-medical-device framework and EU MDR classification rules determine whether AI fitness applications require clinical validation, directly shaping product development timelines and market access costs. GDPR in Europe and HIPAA in the United States impose strict constraints on biometric data storage and cross-border transfer, forcing architecture decisions that affect feature sets. Stakeholders must monitor whether regulators extend medical-grade certification requirements to stress management and sleep monitoring applications, as this boundary shift would fundamentally alter competitive economics.
Market Dynamics
The AI Health and Fitness Products Market faces a structural inflection where FDA software-as-medical-device classification pressure is compressing development timelines while simultaneously raising barriers to entry for algorithmic health claims.
Growth Catalysts
- Corporate wellness procurement:Enterprise HR departments now mandate AI-enabled fitness platforms for workforce health management, creating institutional demand anchors that stabilize subscription revenue pools.
- Photoplethysmography sensor cost curves:Component economics for optical heart-rate monitoring have collapsed manufacturing thresholds for biometric wearables, enabling price accessibility at mass-market scale.
- China's dual carbon goals:National energy efficiency mandates accelerate domestic production of low-power AI inference chips for edge-deployed fitness devices.
Market Restraints
- GDPR biometric data friction:Cross-border transfer restrictions on physiological signals force European operators into costly regional data center buildouts that fragment architecture economics.
- Accelerometer supply concentration:MEMS motion sensor fabrication clusters in Taiwan create single-point vulnerability for wearable hardware pipelines.
- Clinical validation burden:EU MDR classification rules impose documentation requirements on sleep monitoring algorithms that extend time-to-market by 18-24 months for algorithm-centric entrants.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing attract contract assembly investment that can serve price-sensitive South Asian demand segments.
- Generative AI workout synthesis:Large language model integration with motion capture libraries enables hyper-personalized virtual coaching at marginal cost approaching zero.
- Japan's METI healthy aging mandate:National policy targets for senior fitness technology adoption create subsidized procurement channels for fall-detection and mobility monitoring systems.
Industry Challenges
- Machine learning operations talent scarcity:Edge model optimization for 100-500 Hz sensor pipelines requires specialized firmware engineering capabilities concentrated in semiconductor hubs.
- Interoperability certification delays:Fragmented health data exchange standards between hospital EHR systems and consumer fitness platforms stall enterprise partnership timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Health and Fitness Products Market |
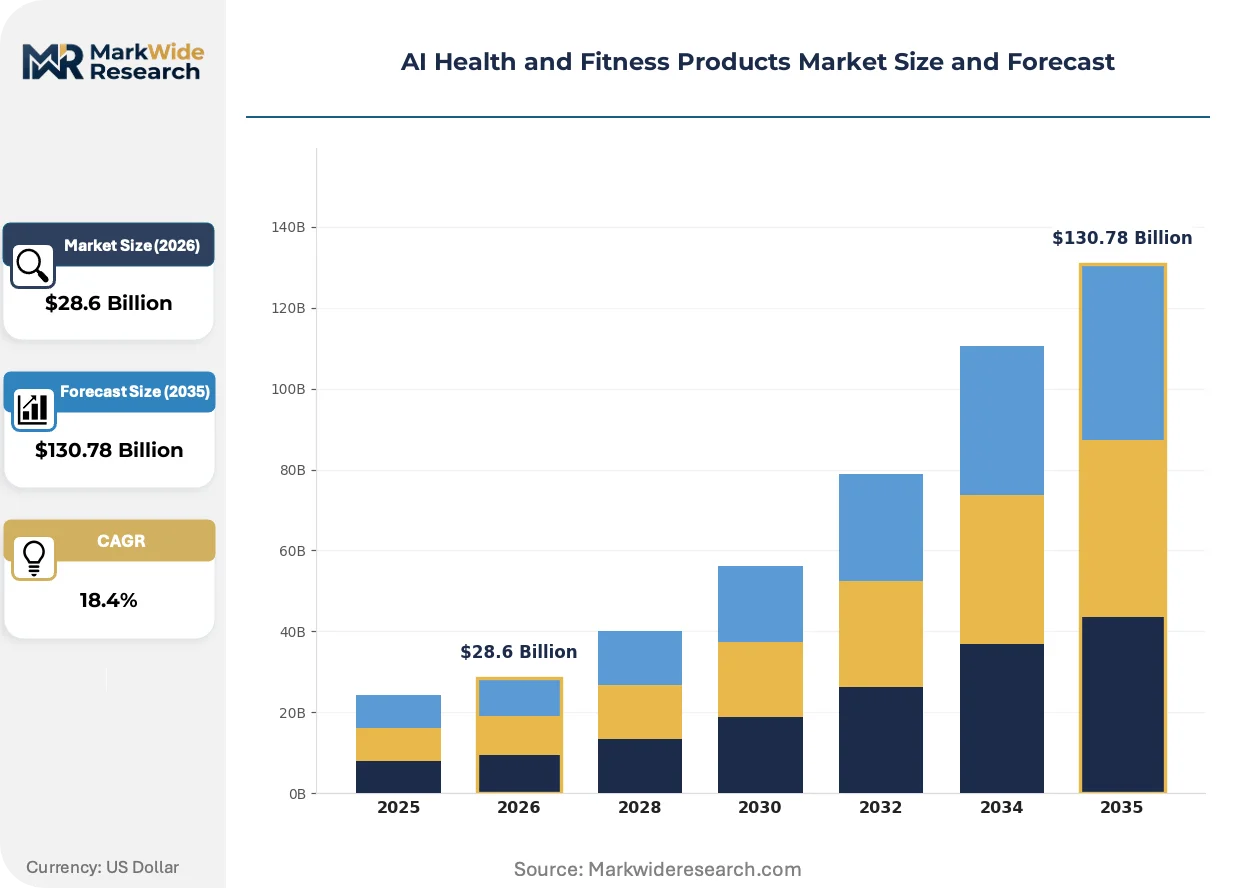
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Smart Equipment, Virtual Trainers, Personal Health Monitors Technology: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics, Voice Recognition Application: Physical Activity Tracking, Nutritional Guidance, Sleep Monitoring, Stress Management, Rehabilitation Support End User: Fitness Enthusiasts, Senior Wellness, Corporate Wellness Programs, Rehabilitation Centers, Individual Consumers |
| Companies Covered | Apple, Google, Samsung Electronics, Garmin, Xiaomi, Fitbit, Peloton Interactive, Technogym, Whoop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Health and Fitness Products Market Trends and Innovations
Algorithmic personalization is migrating from cloud-centric inference to on-device processing, compressing latency for real-time coaching feedback while complicating model update distribution architectures across fragmented hardware ecosystems.
Photoplethysmography signal processing is migrating from heart-rate estimation to continuous blood pressure approximation, enabling hypertension screening in consumer-grade wearables. Cardiology clinics in Germany and the United States now pilot prescription-grade validation protocols for these optical biomarkers. The structural consequence is a blurring boundary between wellness accessories and diagnostic tools that triggers FDA premarket notification requirements.
The EU AI Act's risk classification framework now captures fitness applications making physiological predictions, forcing algorithmic transparency documentation that European developers must embed from initial training pipeline design. High-risk system designations apply to stress management tools claiming clinical correlation. French and Dutch regulators have issued early guidance demanding explainability for workout recommendations affecting vulnerable populations.
Employer-sponsored hardware leasing is displacing direct consumer purchase for premium connected fitness equipment, with corporate benefit administrators negotiating fleet pricing that locks in multi-year platform commitments. This procurement consolidation concentrates buyer power in North American enterprise channels while squeezing retail margin structures for direct-to-consumer brands. Wellness program administrators in California and Texas now specify API integration requirements with existing HR information systems as table stakes for vendor selection.
AI Health and Fitness Products Market Segmentation
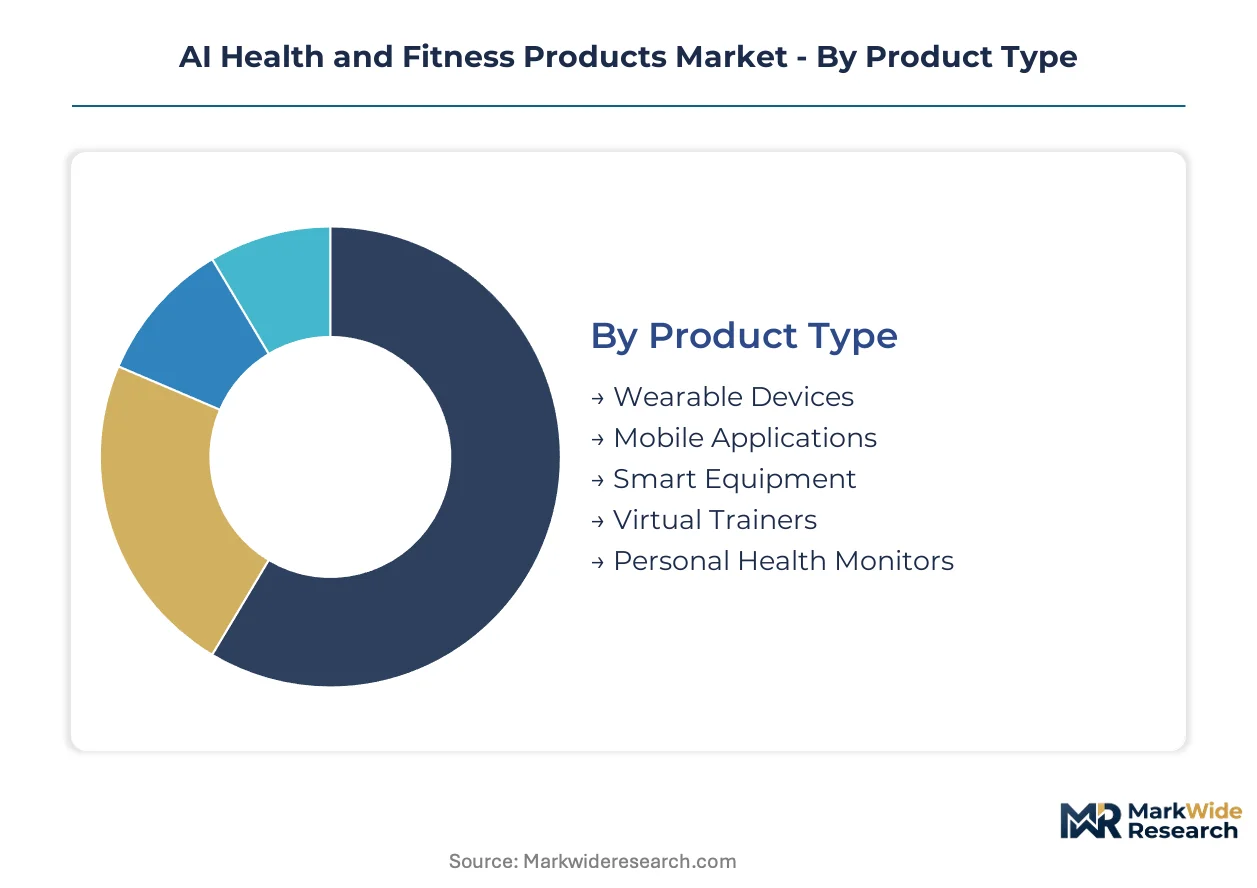
Segmentation in AI health and fitness products determines which technical architectures justify premium pricing versus mass-market penetration. Hardware-software integration depth varies dramatically across product categories, creating distinct margin profiles and renewal economics for vendors.
Product Type:
After-sales service intensity varies sharply across hardware categories, with sensor calibration needs and firmware update cycles creating divergent customer lifetime value profiles.
- Wearable Devices:Sensor-embedded wristbands, rings, and chest straps integrate photoplethysmography and accelerometer arrays sampling biometric signals at 100–500 Hz. Enterprise procurement in Germany and the United States concentrates demand for clinical-grade validation protocols that extend replacement cycles.
- Virtual Trainers:Algorithm-driven coaching platforms deliver personalized workout synthesis through large language model integration with motion capture libraries. Marginal delivery cost approaching zero attracts disproportionate venture investment in San Francisco and London.
- Smart Equipment:Connected treadmills, rowers, and strength training machines embed force sensors and computer vision for form correction.
- Mobile Applications:Smartphone-based fitness platforms leverage onboard accelerometers and GPS for activity tracking without dedicated hardware.
- Personal Health Monitors:Standalone devices for blood pressure, glucose, and body composition measurement target chronic condition management.
By volume, Wearable Devices leads. By growth pace, Virtual Trainers is ahead.
Technology:
Cost tier separation in AI health and fitness products tracks directly against R&D intensity and patent portfolio depth, with frontier algorithms commanding sustained pricing premiums.
- Machine Learning:Supervised and reinforcement learning pipelines process longitudinal biometric datasets to generate predictive health insights. FDA software-as-medical-device classification pressure in the United States compresses development timelines for algorithmic health claims.
- Computer Vision:Optical motion capture systems analyze exercise form through camera feeds, enabling real-time corrective feedback without wearable sensors. Rehabilitation centers in Japan and Australia pilot prescription-grade implementations for post-surgical recovery protocols.
- Predictive Analytics:Statistical models forecast injury risk and performance plateaus from training load patterns.
- Natural Language Processing:Conversational interfaces enable voice-controlled workout logging and nutritional queries.
- Voice Recognition:Speaker identification and emotional tone analysis support hands-free coaching interactions.
By volume, Machine Learning leads. By margin expansion, Computer Vision is gaining share fastest.
Application:
Application maturity in AI health and fitness products correlates with regulatory clarity, with diagnostic-adjacent functions facing steeper validation burdens than lifestyle-oriented features.
- Physical Activity Tracking:Step counting, calorie estimation, and workout classification represent the most penetrated use case, with commodity algorithms now standard across price tiers. Corporate wellness programs in Texas and California mandate API integration with HR information systems as baseline procurement requirements.
- Sleep Monitoring:Polysomnography approximation through accelerometer and heart rate variability analysis is migrating from wellness accessory to clinical screening tool. EU MDR classification rules impose documentation requirements that extend time-to-market by 18–24 months for algorithm-centric entrants.
- Nutritional Guidance:Meal logging and macronutrient optimization through computer vision and database matching.
- Stress Management:HRV-guided breathing exercises and cortisol pattern inference from biometric signals.
- Rehabilitation Support:Post-injury exercise progression and range-of-motion monitoring for physical therapy adherence.
By volume, Physical Activity Tracking leads. By regulatory pressure intensity, Sleep Monitoring is climbing the fastest.
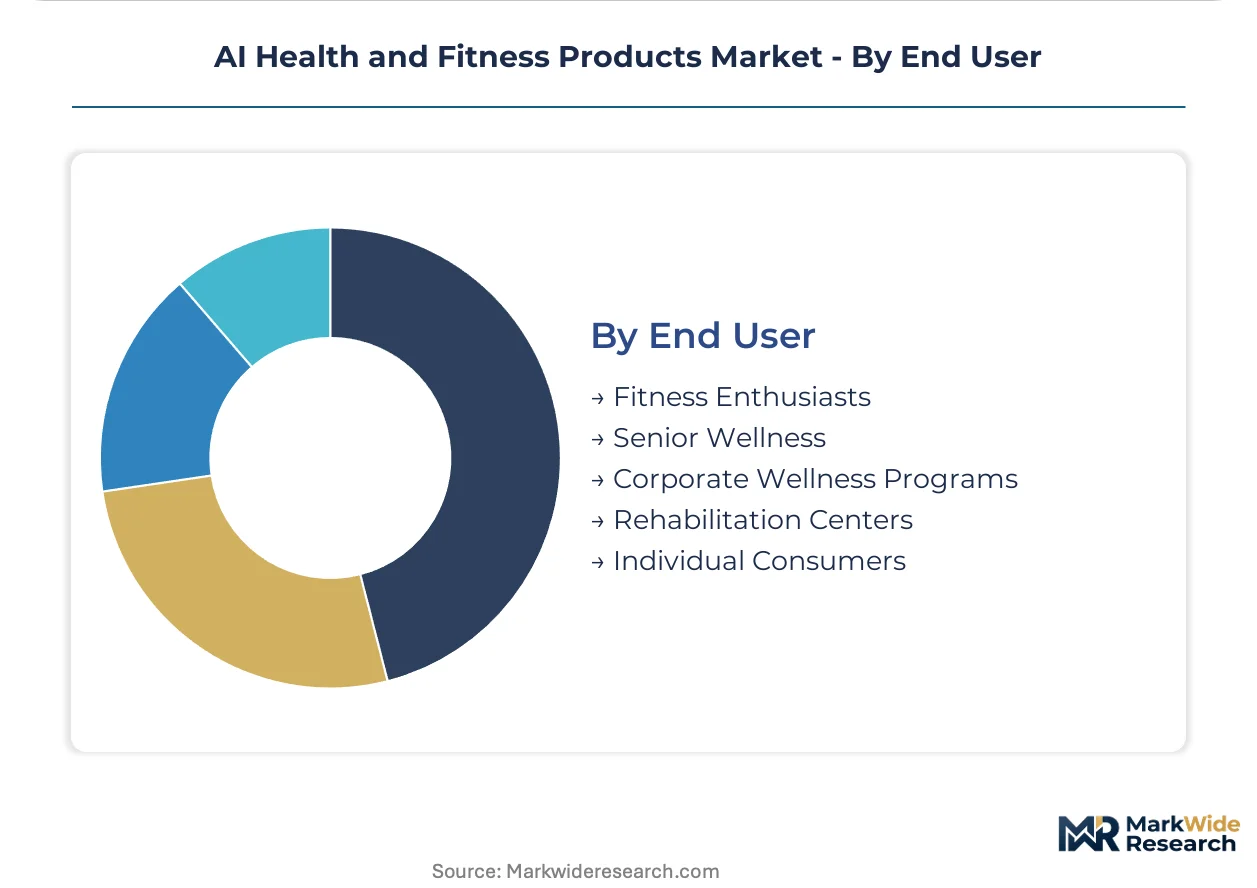
End User:
Customer type segmentation in AI health and fitness products reveals divergent procurement modalities, with institutional buyers consolidating vendor relationships while individual consumers fragment across subscription and hardware purchase models.
- Corporate Wellness Programs:Employer-sponsored platforms aggregate workforce health data for insurance premium negotiations and productivity metrics. Fleet pricing negotiations by benefit administrators in North America concentrate buyer power and lock in multi-year platform commitments.
- Fitness Enthusiasts:Self-directed consumers pursuing performance optimization through advanced training analytics and competitive benchmarking. Community features and social proof mechanisms drive retention in this segment across London, Sydney, and New York metropolitan areas.
- Senior Wellness:Fall detection, medication adherence, and mobility monitoring for aging populations.
- Rehabilitation Centers:Clinical settings requiring HIPAA-compliant data handling and EHR integration.
- Individual Consumers:Mass-market users seeking basic activity tracking and generalized health guidance.
By volume, Fitness Enthusiasts leads. By contract value stability, Corporate Wellness Programs is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness program administrators in the United States concentrate procurement authority for AI-enabled fitness platforms, while consumer demand clusters around Shenzhen and Seoul for wearable hardware with embedded biometric sensors.
United States
FDA software-as-medical-device classification pressure compresses development timelines for algorithmic health claims, forcing San Francisco and Boston developers into accelerated clinical validation protocols. HIPAA constraints on biometric data storage reshape cloud architecture decisions for fitness platforms serving enterprise clients. Austin and Denver host emerging clusters of virtual training startups leveraging generative AI for workout synthesis.
China
Xiaomi and Huawei anchor mass-market adoption of sensor-embedded wearables through domestic supply chain integration spanning Shenzhen and Dongguan manufacturing corridors. National dual carbon goals accelerate production of low-power AI inference chips for edge-deployed fitness devices. Shanghai and Beijing concentrate R&D investment for predictive analytics algorithms processing longitudinal biometric datasets.
Germany
EU MDR classification rules impose documentation requirements on sleep monitoring algorithms that extend time-to-market for Berlin and Munich developers. GDPR biometric data friction forces costly regional data center buildouts that fragment architecture economics for cross-border fitness platforms. Cardiology clinics in Hamburg pilot prescription-grade validation protocols for photoplethysmography-derived optical biomarkers.
Japan
METI healthy aging mandates create subsidized procurement channels for fall-detection and mobility monitoring systems targeting senior populations in Tokyo and Osaka. Rehabilitation centers in Nagoya pilot prescription-grade computer vision implementations for post-surgical recovery protocols. Domestic semiconductor fabrication in Kyushu supplies MEMS motion sensors for wearable hardware pipelines.
India
Production-linked incentives for electronics manufacturing attract contract assembly investment serving price-sensitive demand across Maharashtra and Karnataka. Bengaluru hosts emerging clusters of machine learning operations talent optimizing edge models for 100-500 Hz sensor pipelines. Delhi-NCR concentrates corporate wellness procurement for AI-enabled fitness platforms among IT services employers.
AI Health and Fitness Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware, software, and integrated platform tiers. The market structure fragments between vertically integrated technology conglomerates, pure-play wearable specialists, and subscription-based fitness content platforms. Three strategic archetypes dominate: ecosystem-anchored device manufacturers, algorithm-centric virtual coaching providers, and enterprise-facing wellness platform operators. M&A activity concentrates on sensor technology acquisitions and generative AI startup absorption, while strategic partnerships proliferate between hardware OEMs and cloud infrastructure providers.
Among ecosystem-anchored device manufacturers, Apple exemplifies premium positioning through captive hardware-software integration, Samsung Electronics occupies a position spanning multiple device categories simultaneously, and Xiaomi anchors mass-market penetration through supply chain cost optimization. These three players represent divergent approaches to biometric sensor deployment, algorithm development, and distribution channel control across consumer and enterprise segments.
| Leading Market Players |
|---|
| Apple |
| Samsung Electronics |
| Garmin |
| Xiaomi |
| Fitbit |
| Peloton Interactive |
| Technogym |
| Whoop |
| Others |
Pricing and Supply Chain Analysis
The Shenzhen-Dongguan manufacturing corridor governs freight economics for MEMS sensor shipments, compressing landed costs for wearable OEMs while amplifying price differentiation between clinical-grade and consumer-tier fitness devices across North American and European distribution channels.
Pricing Analysis
Cost-plus contracts with MEMS component suppliers index to Taiwan semiconductor foundry pricing, embedding volatility into wearable device margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated algorithms from wellness-tier alternatives, with certification investment acting as the primary price escalator. Pricing pressure stems from photoplethysmography sensor commoditization in Shenzhen. Corporate wellness programs exhibit lowest price sensitivity due to fleet procurement scale, while individual consumers in India and Southeast Asia drive volume at economy tiers.
Supply Chain Analysis
Supplier-financing facilities from Taiwan-based MEMS foundries extend 90-day payment terms that ease working capital constraints for mid-tier wearable OEMs. Component sourcing concentrates in Taiwan, South Korea, and China, with accelerometer and gyroscope fabrication anchored in Hsinchu and Seoul. Raw material dependencies span silicon wafers, rare-earth magnets for haptic motors, and lithium-polymer cells. Single-source vulnerability in Taiwan MEMS fabrication threatens hardware pipelines. Distribution runs through enterprise procurement channels for corporate wellness, direct-to-consumer e-commerce for fitness enthusiasts, and medical device distributors for rehabilitation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat arena where FDA software-as-medical-device classification creates regulatory entrenchment, erecting switching costs that cement incumbent positions across algorithm-centric product tiers.
For Market Incumbents: Insulate algorithmic differentiation through accelerated FDA 510(k) pathway investment, preempting entrant access to clinical-validation tier pricing. Deepen backward integration into photoplethysmography sensor design to capture component margin compression. Threat: generative AI virtual coaching startups eroding subscription retention through zero-marginal-cost workout synthesis. For New Entrants and Emerging Players: India's PLI-subsidized electronics manufacturing zones represent the most penetrable entry point for price-sensitive wearable hardware targeting South Asian corporate wellness procurement. Japan's METI-subsidized senior fitness technology channels offer algorithm licensing opportunities without hardware investment. Go-to-market: API-first integration with existing HR information systems bypasses direct consumer acquisition costs. For Investors and Strategic Acquirers: Edge AI optimization specialists with firmware engineering capabilities for 100-500 Hz sensor pipelines command scarcity premiums in acquisition markets. Long-term viability hinges on regulatory boundary shifts extending medical-grade certification to stress management applications. Signal to watch: EU AI Act enforcement actions against algorithmic transparency violations in Dutch and French fitness platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Clinical validation unlocks premium pricing tiers and enterprise procurement eligibility. |
| Generative AI Virtual Coaching Integration | Large language model deployment collapses marginal delivery cost for personalized workout synthesis. |
| MEMS Sensor Backward Integration | In-house accelerometer design captures component economics and secures supply continuity. |
| Corporate Wellness Platform Partnership | HR system API integration locks multi-year subscription commitments through fleet pricing. |
| EU MDR Certification Pathway | CE marking for sleep monitoring algorithms enables market access across German and French clinical channels. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers at wearable device OEMs, regulatory affairs specialists navigating FDA software-as-medical-device pathways, corporate wellness procurement managers at North American employers, and machine learning operations engineers optimizing edge inference models. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, SEC filings of publicly traded fitness platform operators, and customs trade data for MEMS sensor imports. Bottom-up demand modeling triangulated against top-down market sizing across hardware shipment volumes and subscription revenue pools.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, technology stack, application function, and end-user procurement modality. CAGRs derived from longitudinal biometric data monetization trends and corporate wellness program penetration curves. Industry-specific forecast inputs incorporated photoplethysmography sensor cost curve trajectories and EU AI Act risk classification enforcement timelines.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or cross-border data transfer regulatory stringency would shift the trajectory. Forecasts embed assumptions regarding FDA classification boundary stability and MEMS fabrication capacity expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Behavioral Mental Health Care Software Market
Digital Health Solutions
Digiceuticals Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Cardiovascular Digital Solutions Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Prescribed Health Apps Market