
 Pharmacovigilance (PV) and Drug Safety Software Market | 2026-2036
Pharmacovigilance (PV) and Drug Safety Software Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacovigilance (PV) and Drug Safety Software Market Insights
Biotech firms is rebalancing the end-user mix as smaller innovators outsource pharmacovigilance workflows to specialized vendors rather than building in-house capabilities. Oracle Corporation leverages its enterprise database heritage to anchor multi-tenant safety platforms across top-tier pharmaceutical accounts. IQVIA sustains competitive density through real-world data integration that bridges clinical and post-market surveillance workflows. Veeva Systems Inc. differentiates via cloud-native architecture purpose-built for life sciences compliance requirements.
Pharmacovigilance and drug safety software encompasses adverse event capture, signal detection algorithms, risk-benefit assessment workflows, and regulatory submission modules designed to monitor drug safety across pre-approval and post-market phases. These systems process structured and unstructured data from clinical trials, spontaneous reports, literature sources, and electronic health records to identify potential safety signals before they trigger regulatory action. Adverse event reporting maintains the largest installed base among product type segments, though signal detection commands premium pricing due to its reliance on artificial intelligence and natural language processing. Cloud-based deployment is gaining share fastest as sponsors seek elastic infrastructure for periodic regulatory submissions and periodic safety update reports. Contract research organizations represent a concentrated growth pocket within end users, driven by sponsor preferences for outsourced safety surveillance during late-phase trials.
The FDA, EMA, and ICH E2B guidelines collectively shape software functionality requirements through mandatory data exchange standards and periodic safety reporting timelines. FDA Sentinel Initiative mandates active surveillance capabilities that force platform upgrades among holders of approved drug applications. EMA's Good Pharmacovigilance Practices and evolving signal management guidance create recurring compliance-driven replacement cycles across European operations. Stakeholders must weigh interoperability investments against regulator-specific submission formats as pharmacovigilance data flows expand across multinational trial networks.
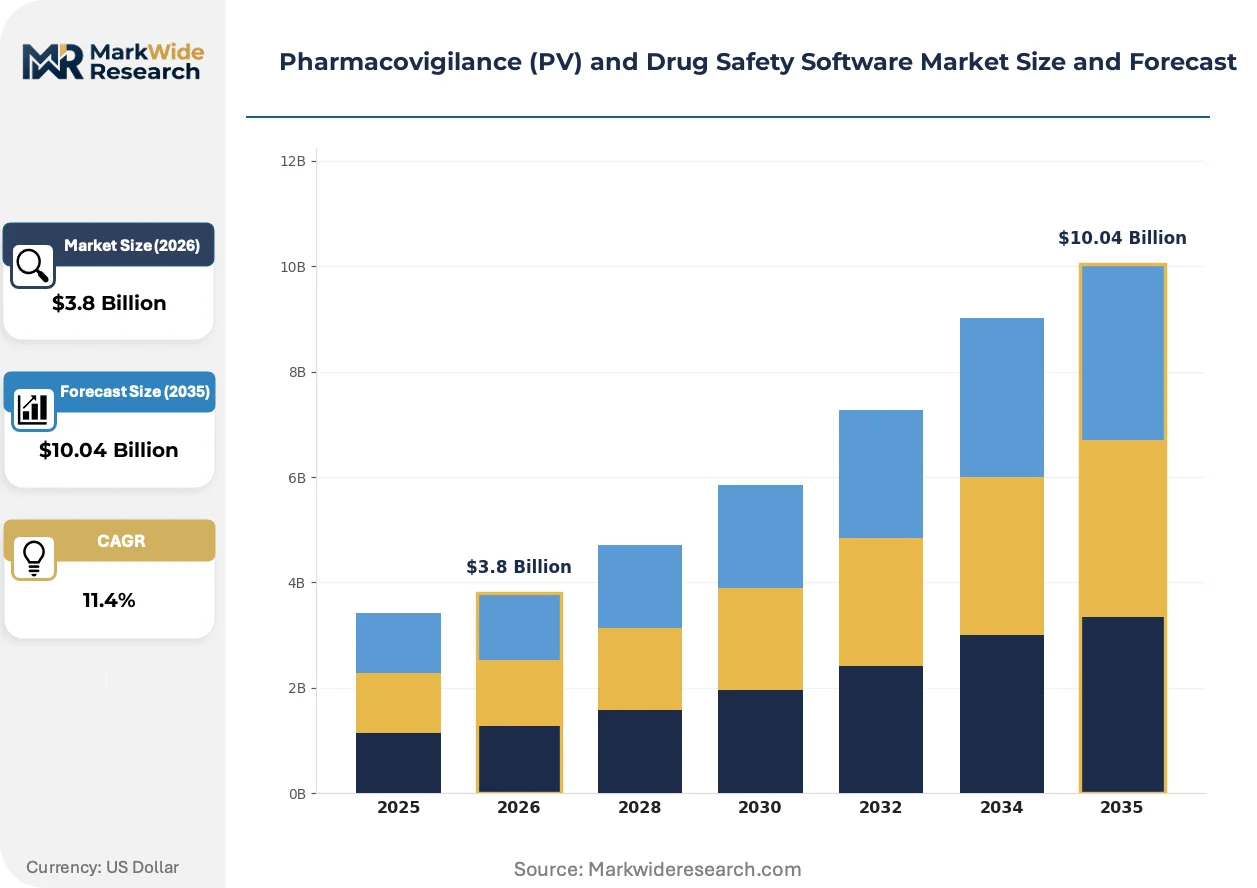
Market Dynamics
Cloud-native architectures are compressing deployment timelines for adverse event platforms as sponsors abandon legacy on-premise installations that cannot scale for periodic regulatory submissions.
Growth Catalysts
- EMA Signal Management Guidance:The European Medicines Agency's evolving mandates for proactive signal detection are forcing platform upgrades across European operations.
- Contract Research Organizations:Sponsor preferences for outsourced safety surveillance during late-phase trials are concentrating demand among specialized service providers.
- Natural Language Processing:AI-powered extraction of safety signals from unstructured literature and social media sources is expanding data ingestion capabilities beyond traditional reporting channels.
Market Restraints
- Data Fragmentation:Heterogeneous electronic health record formats across hospital systems create interoperability barriers that inflate integration costs.
- Specialized Talent Scarcity:The shallow pool of professionals combining pharmacovigilance expertise with data science competencies constrains implementation velocity.
- Validation Burden:FDA 21 CFR Part 11 compliance requirements for electronic records impose lengthy qualification timelines that delay go-live dates.
Strategic Opportunities
- Real-World Evidence Convergence:Integration of clinical trial data with post-market surveillance streams is unifying safety and efficacy workflows for lifecycle management.
- Asia-Pacific Regulatory Maturation:Japan's PMDA and South Korea's MFDS are adopting ICH E2B standards that open procurement opportunities for standardized platforms.
- Biologic Therapies:Complex immunogenicity profiles of cell and gene therapies require novel signal detection algorithms that incumbent vendors have not optimized.
Industry Challenges
- Legacy System Entrenchment:Decades-old safety databases at established pharmaceutical firms resist migration to modern architectures despite functional limitations.
- Multinational Submission Complexity:Divergent regional formatting requirements for periodic safety update reports force redundant workflow configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacovigilance (PV) and Drug Safety Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Trial Management, Adverse Event Reporting, Risk Management, Signal Detection End User: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Regulatory Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Application: Post-Market Surveillance, Risk Assessment, Data Analysis, Compliance Monitoring |
| Companies Covered | Oracle Corporation, ArisGlobal LLC, Veeva Systems Inc., IQVIA, Ennov Solutions Inc., Extedo GmbH, AB Cube, Paraxel International Corporation, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacovigilance (PV) and Drug Safety Software Market Trends and Innovations
Artificial intelligence is compressing signal detection cycles from months to weeks while regulatory mandates for active surveillance are rewriting platform specifications across major jurisdictions.
Federated learning architectures are unifying safety data analysis across institutional boundaries without centralizing protected health information. Large pharmaceutical sponsors in the United States and European Union are piloting these networks to satisfy FDA Sentinel Initiative and EMA data sharing expectations. This approach is unifying previously siloed adverse event repositories while preserving patient privacy constraints that would otherwise block multi-source signal validation.
The FDA's Sentinel Initiative mandates active surveillance capabilities that force platform upgrades among holders of approved drug applications. Industrial consequence includes mandatory investment in distributed query infrastructure that can interrogate electronic health record networks in near-real-time. Small and mid-sized sponsors lacking internal IT resources are responding through vendor-managed service arrangements that bundle software licensing with operational support.
Biotech innovators are abandoning capital-intensive in-house safety operations in favor of subscription-based vendor platforms. This behavior shift concentrates purchasing power among contract research organizations that aggregate demand across multiple sponsor accounts. The phenomenon is most visible in Boston and San Francisco R&D clusters where venture-backed firms prioritize speed-to-market over operational self-sufficiency.
Pharmacovigilance (PV) and Drug Safety Software Market Segmentation
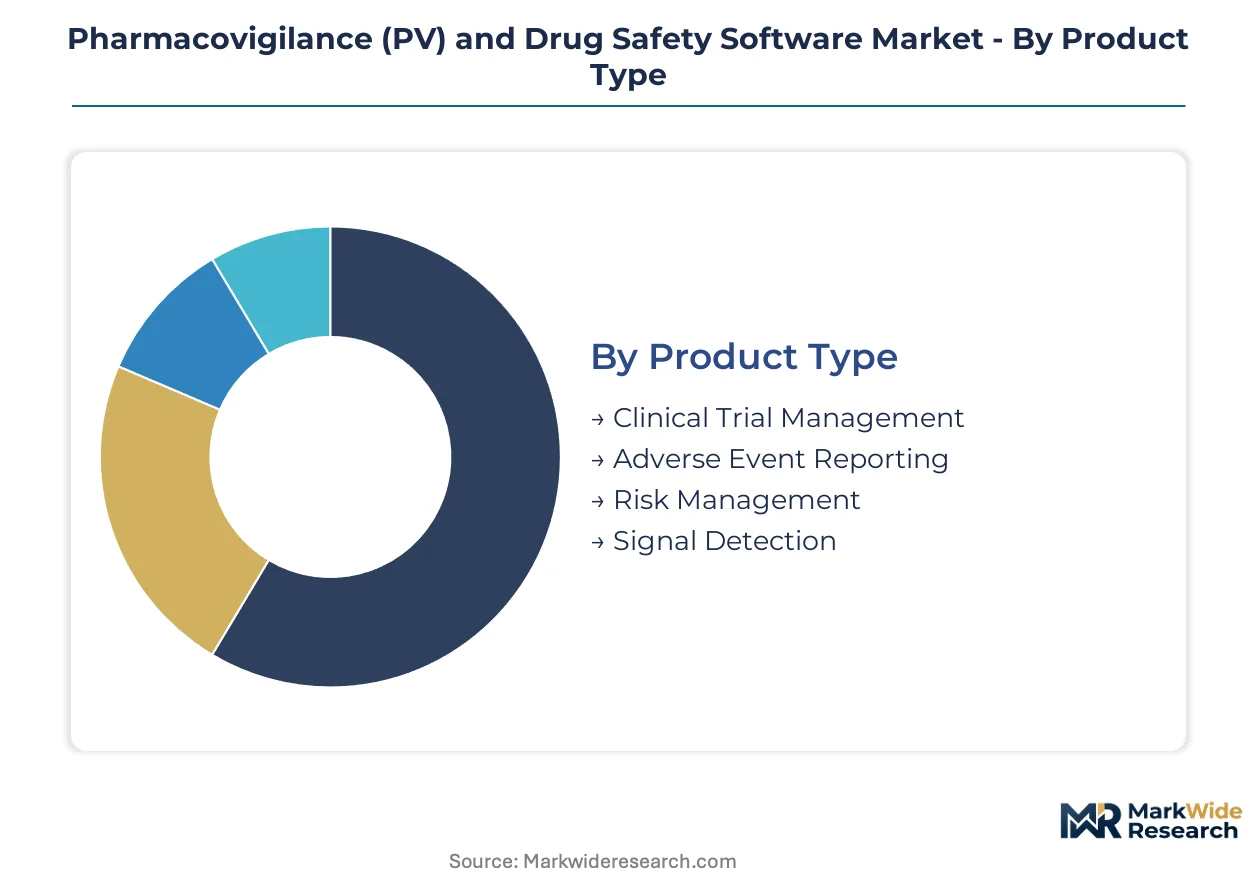
Pharmacovigilance software procurement patterns diverge sharply across organizational scale and regulatory maturity. Segmentation reveals how enterprise pharmaceutical buyers prioritize integration depth while emerging biotech sponsors favor modular, subscription-based deployments.
Product Type:
Standalone adverse event platforms dominate biotech procurement cycles, whereas signal detection modules increasingly embed within broader clinical data ecosystems.
- Adverse Event Reporting:Core intake workflows process structured case reports from clinical sites, spontaneous submissions, and regulatory portals. Demand concentrates among contract research organizations managing multi-sponsor safety operations under FDA 21 CFR Part 11 and EMA Good Pharmacovigilance Practices mandates.
- Signal Detection:Algorithmic surveillance engines apply statistical disproportionality analysis and natural language processing to identify safety patterns across disparate data streams. Pharmaceutical companies in the United States and Germany drive premium procurement for AI-augmented capabilities that compress detection cycles.
- Clinical Trial Management:Integrated safety-efficacy data repositories unify pre-approval and post-market pharmacovigilance workflows.
- Risk Management:Risk-benefit assessment modules automate periodic safety update report generation and regulatory submission packaging.
Adverse Event Reporting leads volumes today; Signal Detection is gaining share fastest.
End User:
Customer archetypes span capital-rich enterprises with captive IT infrastructure to venture-backed innovators outsourcing entire safety functions.
- Contract Research Organizations:Specialized service providers aggregate pharmacovigilance demand across sponsor portfolios, achieving economies of scale in case processing and regulatory submission. CROs in Boston and Basel clusters are consolidating safety platform procurement through multi-tenant vendor arrangements.
- Biotech Firms:Smaller innovators lack internal safety infrastructure and rely on vendor-managed platforms for adverse event intake and signal monitoring. These sponsors prioritize speed-to-market over operational self-sufficiency, particularly in San Francisco and Cambridge R&D corridors.
- Pharmaceutical Companies:Established manufacturers maintain legacy safety databases requiring gradual cloud migration.
- Regulatory Agencies:Government bodies deploy surveillance infrastructure for active monitoring mandates like FDA Sentinel.
Pharmaceutical Companies anchor current procurement value; Biotech Firms show the steepest expansion trajectory.
Deployment:
Architecture choices reflect tension between elastic scalability requirements and validation burden constraints.
- Cloud-Based:Multi-tenant SaaS platforms eliminate capital expenditure for periodic regulatory submission spikes and enable rapid scaling for safety update report cycles. Sponsors in the United States and United Kingdom are abandoning on-premise installations that cannot accommodate FDA Sentinel distributed query requirements.
- Hybrid:Split architectures retain sensitive case data on-premise while leveraging cloud analytics for signal detection workloads. European pharmaceutical operations favor this model to reconcile EMA data residency expectations with computational scalability needs.
- On-Premises:Legacy installations persist at established manufacturers with decades-old safety database investments.
- Mobile:Field-accessible case intake applications support clinical site reporters and traveling safety physicians.
On-Premises retains the largest installed base; Cloud-Based deployment is climbing the fastest.
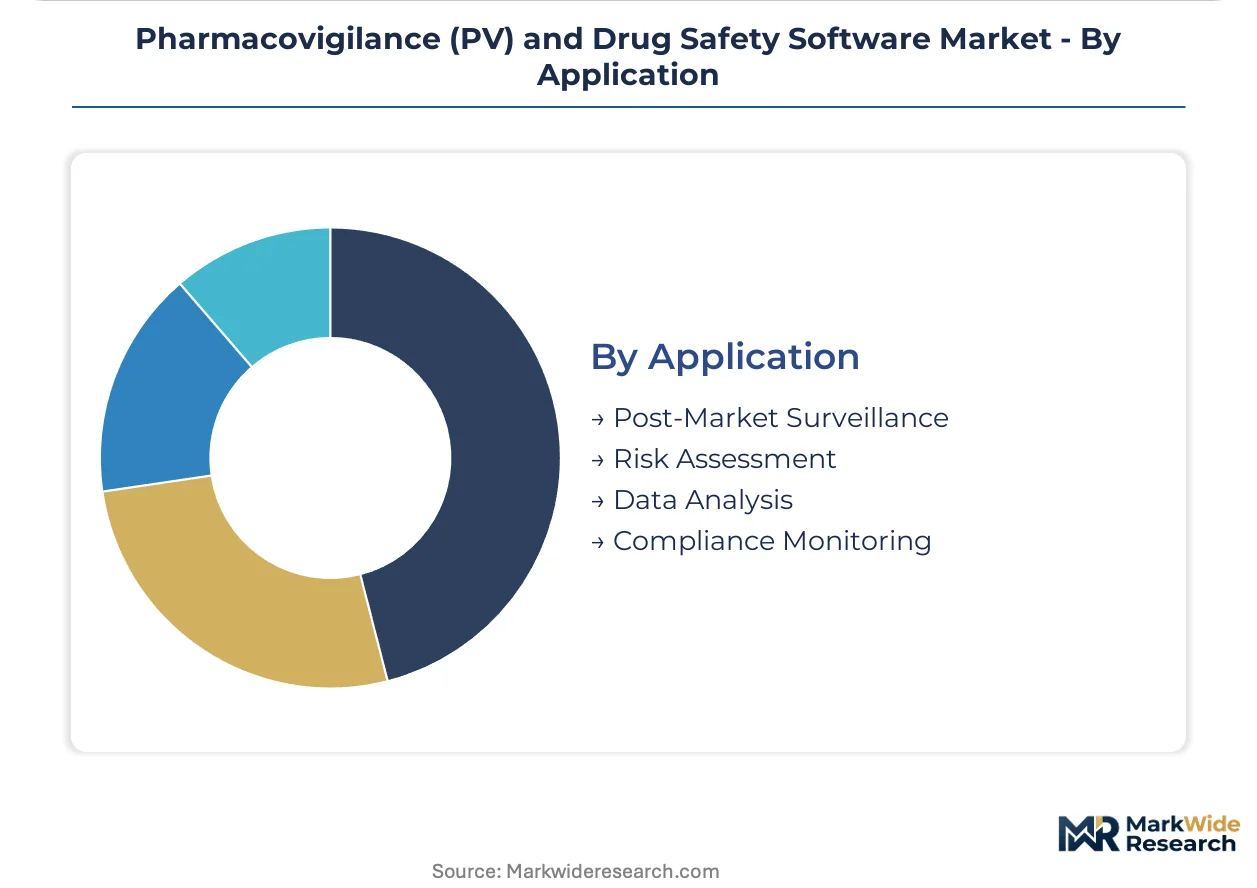
Application:
Functional use cases trace the drug lifecycle from pre-approval risk assessment through post-market active surveillance.
- Post-Market Surveillance:Continuous safety monitoring of approved therapies through spontaneous reporting systems, literature surveillance, and electronic health record network queries. FDA Sentinel Initiative mandates are forcing platform upgrades among holders of approved drug applications in the United States.
- Risk Assessment:Systematic evaluation of risk-benefit profiles for regulatory submissions and label updates. EMA signal management guidance is accelerating procurement for integrated risk assessment workflows across European operations.
- Data Analysis:Statistical and machine learning methods applied to safety signal identification and validation.
- Compliance Monitoring:Automated tracking of regulatory submission deadlines and periodic safety reporting obligations.
Post-Market Surveillance dominates current procurement; Risk Assessment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor concentrates the highest density of pharmacovigilance software procurement in North America. Venture-backed firms in this cluster outsource safety operations to cloud-native platforms rather than building captive infrastructure. Regulatory mandates from the FDA, EMA, and Japan's PMDA are reshaping procurement patterns across major pharmaceutical markets.
United States
FDA Sentinel Initiative mandates are forcing platform upgrades among holders of approved drug applications. The distributed query infrastructure requirement is accelerating abandonment of legacy on-premise installations. Boston and San Francisco R&D clusters show the steepest cloud migration velocity as biotech sponsors prioritize speed-to-market.
Germany
EMA Good Pharmacovigilance Practices and evolving signal management guidance create recurring compliance-driven replacement cycles. Baden-Württemberg pharmaceutical operations favor hybrid architectures to reconcile data residency expectations with computational scalability. Stuttgart-based manufacturers are consolidating procurement through multi-tenant vendor arrangements.
Japan
PMDA adoption of ICH E2B standards is opening procurement opportunities for standardized platforms. Tokyo and Osaka pharmaceutical sponsors are migrating from legacy safety databases to cloud-native architectures. The Kanto region shows concentrated demand for AI-augmented signal detection capabilities.
United Kingdom
Post-Brexit regulatory divergence from EMA frameworks is creating dual compliance requirements for multinational sponsors. London and Cambridge life sciences clusters are investing in platforms supporting both UK MHRA and EMA submission formats. Thames Valley operations show preference for subscription-based vendor-managed services.
India
CDSCO alignment with ICH E2B standards is accelerating platform standardization among contract research organizations. Hyderabad and Bangalore CRO clusters are aggregating pharmacovigilance demand across sponsor portfolios. These service providers achieve economies of scale in case processing and regulatory submission workflows.
Pharmacovigilance (PV) and Drug Safety Software Market Competitive Landscape
Platform consolidation dominates the current landscape as enterprise software vendors absorb specialized safety functionality. The vendor base stratifies across three tiers: database-anchored incumbents, cloud-native specialists, and CRO-integrated service platforms. Strategic archetypes include enterprise database heritage players, real-world data integrators, and compliance-focused SaaS architects. M&A activity and cloud migration partnerships represent the dominant competitive moves reshaping market structure.
Within the enterprise infrastructure tier, Oracle Corporation and IQVIA occupy positions reflecting database heritage and clinical data integration respectively. Veeva Systems Inc. exemplifies the cloud-native compliance architecture archetype purpose-built for life sciences requirements. These three anchors represent divergent strategic bets on how pharmacovigilance workflows will converge with broader clinical and commercial data ecosystems.
| Leading Market Players |
|---|
| Oracle Corporation |
| ArisGlobal LLC |
| Veeva Systems Inc. |
| IQVIA |
| Ennov Solutions Inc. |
| Extedo GmbH |
| AB Cube |
| Paraxel International Corporation |
| Accenture |
| Others |
Pricing and Supply Chain Analysis
Cloud-native SaaS migration is simultaneously collapsing deployment cost structures and concentrating procurement leverage among multi-tenant platform vendors serving biotech clusters in Boston and San Francisco. This technology shift rewards elastic infrastructure providers while penalizing legacy on-premise installations that cannot scale for FDA Sentinel distributed query mandates.
Pricing Analysis
Input-cost pass-through from AI compute infrastructure and NLP model licensing flows directly into signal detection module pricing, compressing margins for vendors lacking cloud scale. Subscription tiers stratify across adverse event intake volume, signal detection algorithm sophistication, and regulatory submission automation depth. Pricing pressure stems from sponsor consolidation around CRO-managed service bundles that aggregate demand across multiple accounts. Biotech firms exhibit highest price sensitivity due to venture-funded runway constraints, while top-20 pharmaceutical manufacturers prioritize integration depth over unit cost.
Supply Chain Analysis
Freight cost exposure remains minimal for software delivery, though data residency requirements create geographic supply chain complexity for cloud infrastructure provisioning. Platform engineering talent concentrates in the United States, India, and Germany, with Hyderabad and Bangalore CRO clusters feeding case processing capacity. Raw material dependencies center on GPU compute access, proprietary safety databases, and ICH E2B-compliant data exchange protocols. Single-source vulnerability sits with hyperscaler cloud infrastructure for FDA Sentinel-compliant distributed query networks. Distribution runs through direct enterprise sales for pharmaceutical accounts and CRO channel partnerships for biotech sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where sponsor procurement is shifting toward premium specifications for AI-augmented signal detection and real-world evidence integration. Regulatory mandates for active surveillance are elevating minimum viable platform capabilities beyond what economy-tier vendors can deliver.
For Market Incumbents: To counter cloud-native specialists displacing legacy database installations, Oracle and IQVIA should deepen backward integration into real-world data assets and accelerate multi-tenant architecture deployment for CRO channel capture. Certification investment in FDA 21 CFR Part 11 and EMA Good Pharmacovigilance Practices compliance automation anchors retention of pharmaceutical accounts facing audit intensity. For New Entrants and Emerging Players: Mid-sized biotech sponsors in the United Kingdom and Japan represent the most penetrable buyer archetype, as post-Brexit dual compliance requirements and PMDA ICH E2B standardization create demand for modular, subscription-based platforms. A direct-to-sponsor SaaS model bypassing CRO intermediaries captures procurement autonomy among venture-backed firms prioritizing speed-to-market. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-architecture vendors with established European data residency capabilities and underexploited AI engineering teams. Long-term viability across the analysis window hinges on convergence between clinical trial and post-market surveillance data streams. Watch FDA Sentinel Initiative expansion beyond its current therapeutic scope as the inflection signal for platform upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies adverse event intake with signal detection workflows for EMA compliance automation. |
| Acquisition of Specialist Firm | Adds NLP capabilities for literature and social media safety signal extraction. |
| Geographic Expansion | Establishes cloud infrastructure in Japan to capture PMDA ICH E2B procurement opportunities. |
| Strategic Partnership | Links CRO safety operations with real-world evidence data networks for lifecycle management. |
| Product Launch | Introduces federated learning architectures satisfying FDA Sentinel privacy-preserving mandates. |
Research Methodology
Bottom-up biotech firm and pharmaceutical company modeling reconciled against top-down CRO and regulatory agency tracking forms the analytical core of this study. Primary interviews with drug safety officers, regulatory affairs directors, CRO procurement leads, and cloud platform engineers were validated against secondary sources including FDA Sentinel Initiative documentation, EMA Good Pharmacovigilance Practices guidance, ICH E2B technical specifications, and clinical trial registry filings. Triangulation between sponsor-reported software procurement patterns and vendor-disclosed platform deployment metrics anchors volume estimates.
Input-output matrices map adverse event case volume, signal detection query complexity, and regulatory submission frequency against platform licensing tiers and professional services attach rates across the projection horizon. Segmentation dimensions include deployment architecture, organization scale, therapeutic focus, regulatory jurisdiction cluster, and integration depth with clinical data ecosystems. CAGRs derive from fitted adoption curves for cloud migration and AI-augmented capabilities, calibrated against FDA and EMA mandate implementation timelines. Forecast inputs incorporate CRO consolidation velocity and biotech venture funding cycle patterns.
Inputs from regulatory filing databases and CRO financial disclosures were available through the study window; gaps in privately held biotech firm software expenditure introduce uncertainty bands around sponsor segment sizing. Forecasts reflect assumptions regarding EMA signal management guidance enforcement consistency and FDA Sentinel distributed query infrastructure rollout pace. Stakeholders should weight assumptions against their own operating context and regulatory inspection history.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market