
 Econsent in Healthcare Market | 2026-2036
Econsent in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Econsent in Healthcare Market Analytics
Platform licensing revenue is reshaping margin distribution between traditional software vendors and trial service providers. Veeva Systems leverages its cloud-native architecture to anchor enterprise-scale deployments across multinational pharmaceutical sponsors. Florence Healthcare competes on site-centric workflow design, sustaining deep penetration among academic medical centers and mid-size research sites.
Electronic consent (eConsent) encompasses digital capture, presentation, and documentation of informed consent documentation through interactive multimedia interfaces, incorporating signature authentication, version control, and audit trail generation to satisfy regulatory evidentiary standards. Its primary purpose centers on replacing paper-based consent processes with traceable, accessible, and patient-comprehensible workflows that reduce protocol deviations and enhance regulatory inspection readiness. Cloud-based deployment leads among delivery models, capturing the bulk of new implementations as sponsors prioritize remote trial enablement and elastic infrastructure scaling. Mobile applications represent the fastest-growing product type, reflecting patient preference for smartphone-native engagement and bring-your-own-device flexibility in decentralized trial settings.
The US FDA, EMA, and HIPAA collectively govern eConsent validity, data integrity, and patient privacy protections across jurisdictions, with FDA guidance on electronic records and signatures establishing baseline technical expectations for submissions. GDPR and the EU AI Act introduce additional layers of cross-border data governance and algorithmic transparency for AI-enabled consent comprehension tools. Stakeholders must monitor evolving interoperability mandates between eConsent platforms and electronic health record systems as regulators tighten audit expectations for consent version lineage and patient withdrawal tracking.
Market Dynamics
Decentralized clinical trial architectures are compressing consent timelines from weeks to days, forcing sponsors to abandon paper workflows in favor of cloud-native platforms that integrate directly with electronic health record systems and remote monitoring infrastructure.
Growth Catalysts
- FDA Electronic Records Guidance:The agency's technical specifications for 21 CFR Part 11 compliance provide regulatory certainty that accelerates sponsor investment in validated eConsent platforms.
- Patient Smartphone Penetration:Bring-your-own-device flexibility in decentralized trials eliminates hardware provisioning costs while expanding recruitment reach into rural and underserved populations.
- Protocol Deviation Reduction:Automated version control and real-time audit trails compress inspection preparation timelines and reduce findings during regulatory audits.
Market Restraints
- HIPAA Technical Safeguards:Encryption and access control requirements for protected health information impose infrastructure costs that disadvantage smaller research sites with limited IT budgets.
- EHR Interoperability Fragmentation:Proprietary data exchange protocols between consent platforms and hospital information systems force expensive custom integration work at each deployment.
- Cybersecurity Insurance Escalation:Rising premiums for clinical trial data breach coverage are being passed through to platform licensing fees, compressing margins for mid-size contract research organizations.
Strategic Opportunities
- EU AI Act Algorithmic Transparency:Machine learning-based consent comprehension tools face new explainability requirements that create first-mover advantage for vendors with interpretable model architectures.
- India CDSCO Digital Trial Pathways:The regulator's emerging framework for remote consent in domestic trials opens penetration opportunity for platforms with multilingual interface capabilities.
- Synthetic Control Arm Integration:Convergence of eConsent with real-world data platforms enables single-arm trial designs that reduce patient burden and accelerate regulatory submissions.
Industry Challenges
- Clinical Informatics Talent Scarcity:Shortage of professionals who bridge regulatory science, data engineering, and patient experience design is extending implementation timelines for complex multi-site deployments.
- Consent Withdrawal Workflow Complexity:Real-time propagation of patient withdrawal decisions across interconnected trial systems remains technically immature, creating compliance exposure during inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Econsent in Healthcare Market |
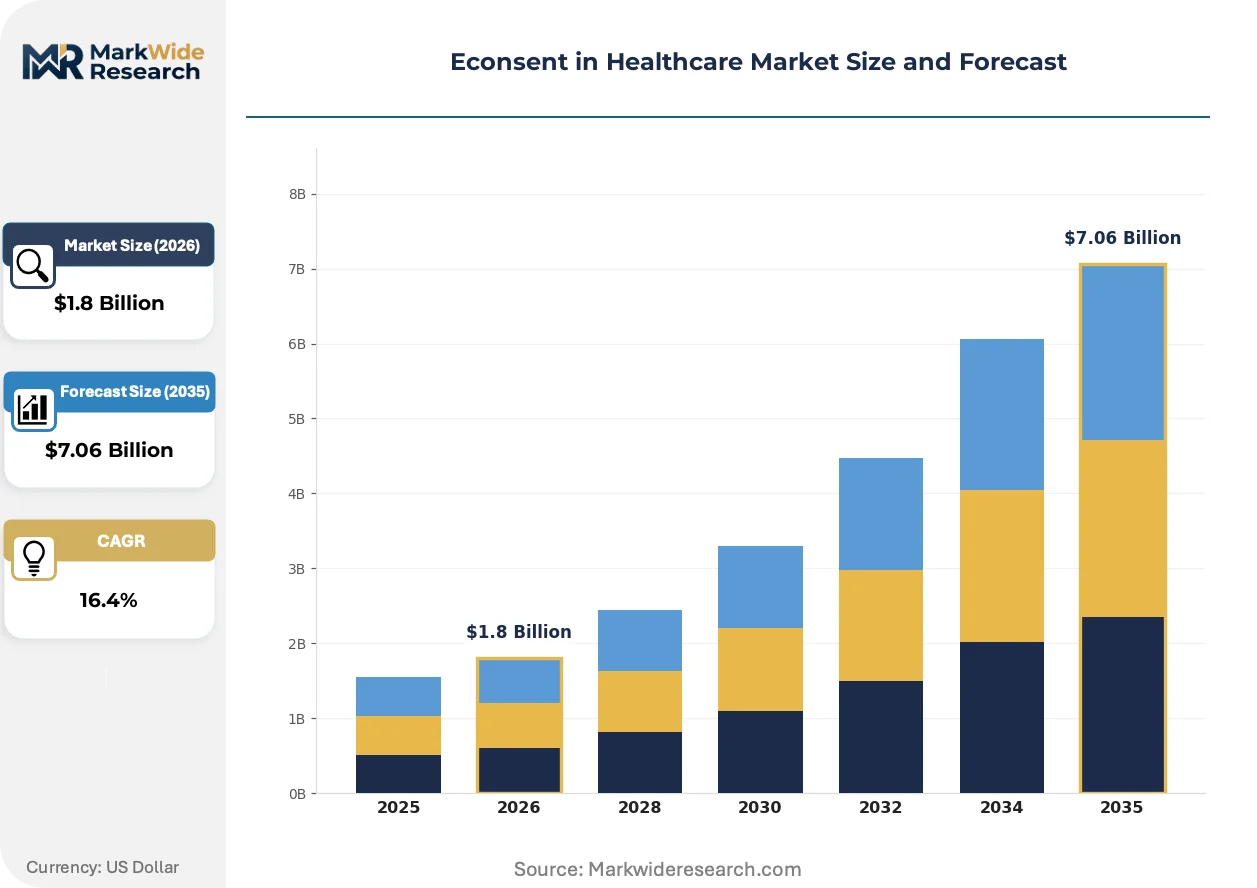
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Web Portals, Integrated Platforms, Standalone Solutions End User: Clinics, Hospitals, Research Institutions, Patients Deployment: Cloud-Based, On-Premise, Hybrid Solutions, SaaS Offers Integration Level: API Integration, Standalone Use, EHR Integration, Limited Connectivity |
| Companies Covered | Veeva Systems, Florence Healthcare, Signant Health, Advarra, IQVIA, Medidata, Clinical ink, Castor, Interlace Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Econsent in Healthcare Market Evolving Landscape
Interactive multimedia interfaces are replacing static PDF documents, embedding video explanations and comprehension quizzes that adapt to patient health literacy levels while generating granular engagement analytics for regulatory defense.
Virtual reality consent modules are virtualizing the informed consent conversation for surgical and interventional trials, allowing patients to experience procedural risks through immersive simulation before enrollment. Academic medical centers in Germany and the Netherlands are piloting these deployments for orthopedic and cardiovascular device studies. The technology is virtualizing the traditional physician-patient dialogue, compressing the time required for comprehension verification while generating standardized documentation that satisfies FDA evidentiary requirements.
EMA's updated guidance on electronic informed consent in multinational trials is harmonizing technical validation requirements across member states, reducing the duplication of platform qualification work that previously fragmented European deployments. Sponsors operating across Germany, France, and Italy now face unified expectations for signature authentication and audit trail retention. Small and mid-size biotechnology companies are responding by consolidating European trial management under single eConsent platform instances rather than maintaining country-specific configurations.
Site procurement patterns are fragmenting as academic research organizations demand modular pricing that unbundles platform licensing from professional services, while pharmaceutical sponsors prefer enterprise subscriptions that include unlimited site onboarding and 24-hour support coverage. Contract research organizations in the United States are responding with hybrid commercial models that separate core platform access from implementation consulting. This bifurcation is most visible in oncology trials, where large academic networks negotiate site-specific terms while sponsor-backed studies standardize on bundled arrangements.
Econsent in Healthcare Market Segmentation
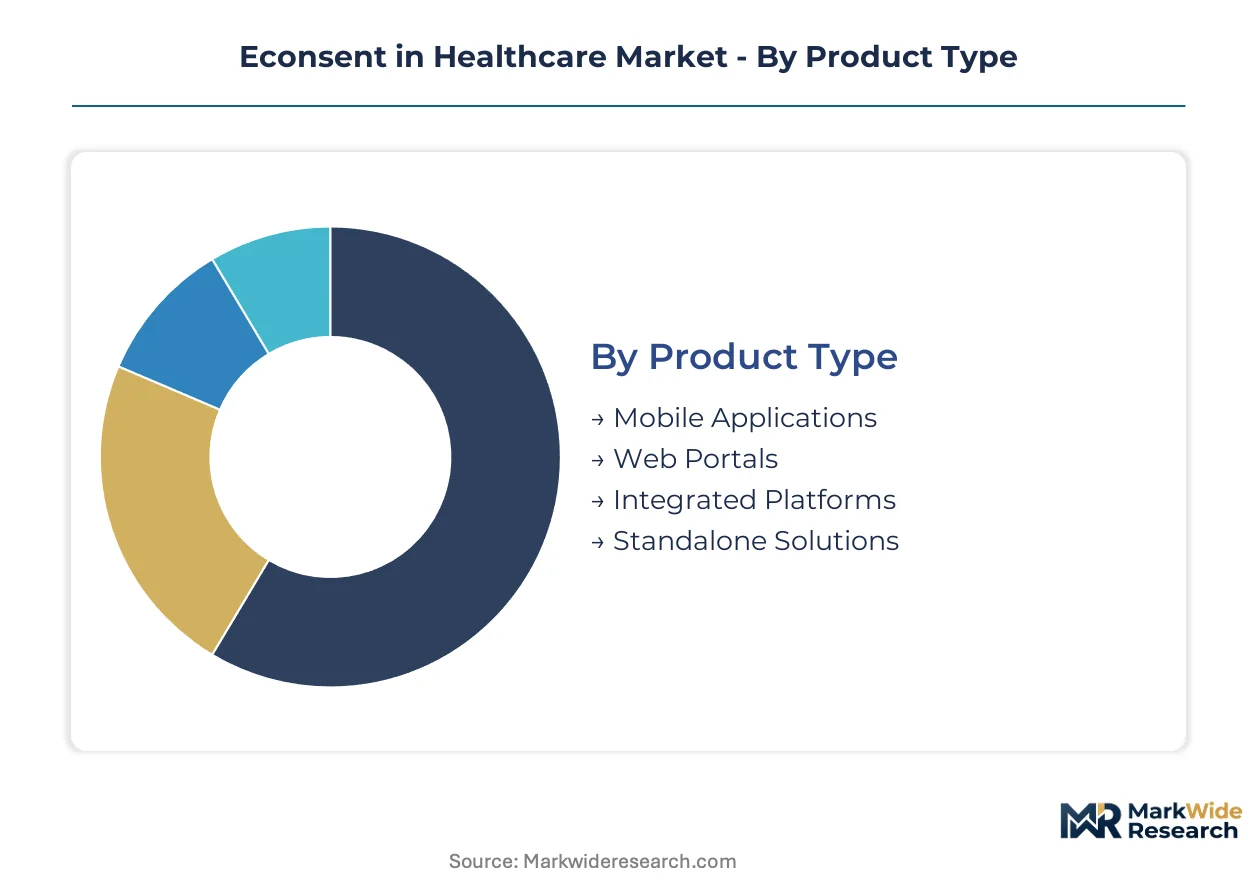
eConsent platforms fragment across four structural dimensions that determine procurement patterns and margin capture. Deployment architecture and integration depth shape implementation timelines, while product format and end-user type dictate pricing elasticity and renewal rates.
Product Type:
Cycle times vary dramatically by interface complexity, with lightweight mobile deployments refreshing every 18-24 months versus enterprise platforms on 5-7 year amortization schedules.
- Mobile Applications:Native iOS and Android interfaces leverage smartphone biometric authentication and push notification capabilities for real-time consent status updates. Demand concentrates among decentralized trial sponsors targeting rural patient populations in the United States and Western Europe, driven by bring-your-own-device policies that eliminate hardware provisioning overhead.
- Integrated Platforms:Unified consent-to-data-capture systems embed eSignature, multimedia education, and EHR synchronization within single vendor stacks. Academic medical centers in Germany and the Netherlands prioritize these deployments for multi-site orthopedic and cardiovascular device studies requiring procedural visualization modules.
- Web Portals:Browser-based interfaces accessible across device types without app store distribution dependencies.
- Standalone Solutions:Single-function consent modules deployed without adjacent trial management capabilities.
Integrated platforms dominate installed base. Mobile applications are where expansion concentrates.
End User:
Procurement authority and budget scale create tiered pricing elasticity, with pharmaceutical sponsors absorbing premium platform fees while patient-facing deployments demand freemium conversion models.
- Research Institutions:University-affiliated clinical trial units and academic medical centers operating under federal funding constraints. Principal investigators at Stanford, Mayo Clinic, and Charité Berlin negotiate modular licensing that unbundles platform access from professional services.
- Hospitals:Integrated delivery networks and community hospital systems managing investigator-initiated trials alongside sponsored research portfolios.
- Clinics:Independent specialty practices and site management organizations with limited IT infrastructure budgets.
- Patients:Direct-to-patient deployment models in decentralized trials where consent interfaces bypass institutional procurement entirely.
Research institutions anchor platform revenue. Patients represent the steepest expansion trajectory as decentralized trial architectures displace site-centric models.
Deployment:
Margin profiles diverge by infrastructure ownership, with cloud-native subscriptions generating recurring revenue streams against capital-intensive on-premise installations with heavy professional services attachment.
- Cloud-Based:Multi-tenant SaaS architectures hosted on AWS, Azure, or Google Cloud with elastic scaling for seasonal enrollment surges. Pharmaceutical sponsors in the United States prioritize these deployments for global trial portfolios requiring 24-hour support coverage and unlimited site onboarding.
- SaaS Offers:Single-tenant managed instances with dedicated infrastructure isolation for HIPAA technical safeguard compliance.
- Hybrid Solutions:Split architectures retaining sensitive consent records on-premise while leveraging cloud analytics layers.
- On-Premise:Self-hosted installations within institutional data centers with full infrastructure control.
Cloud-based deployments capture the majority of new implementations. SaaS offers are climbing fastest among mid-size biotechnology companies consolidating European trial management.
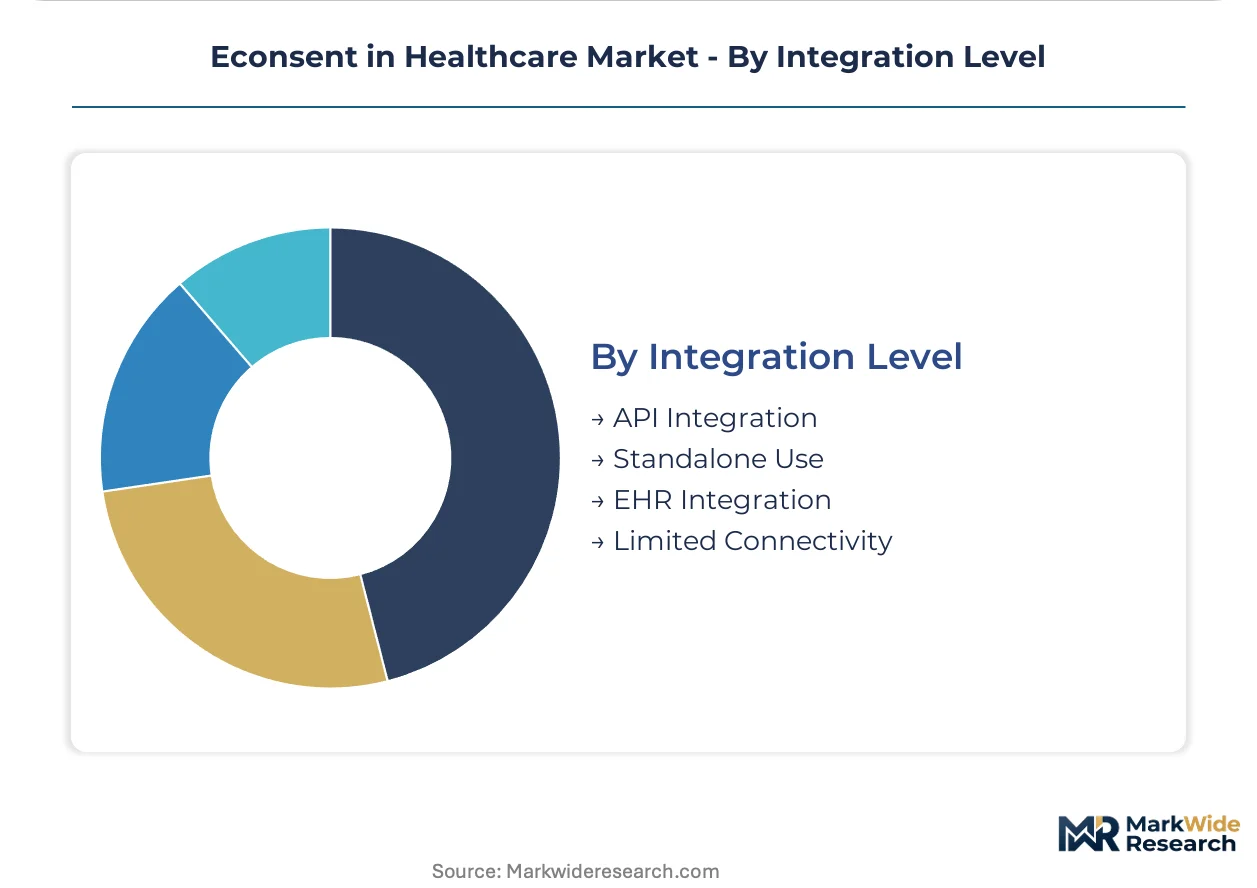
Integration Level:
Technical maturity and regulatory validation requirements stretch implementation timelines, with deep EHR integration demanding 12-18 month deployment cycles versus standalone deployments operational within weeks.
- EHR Integration:Bidirectional data exchange with Epic, Cerner, and MEDITECH systems enabling automatic population of consent status into patient records. FDA inspection readiness depends on audit trail lineage propagating across interconnected systems without manual reconciliation.
- API Integration:RESTful and FHIR-based connectivity enabling custom workflow orchestration between consent platforms and adjacent trial systems.
- Standalone Use:Self-contained consent modules operating without external system dependencies.
- Limited Connectivity:Basic export functionality requiring manual data transfer to downstream systems.
EHR integration dominates enterprise procurement requirements. API integration is gaining share fastest as contract research organizations respond to site demands for modular interoperability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States sponsors deploy eConsent primarily for decentralized trial enablement, while German operators emphasize EHR-integrated workflows for multi-site academic studies. This consumption-mix differential shapes platform procurement priorities across major markets.
United States
FDA guidance on 21 CFR Part 11 compliance drives enterprise investment in validated cloud-native platforms. HIPAA technical safeguard requirements for encryption and access control impose infrastructure costs that disadvantage smaller research sites. The Boston-Cambridge biotech corridor anchors adoption, with Massachusetts General Hospital and Dana-Farber Cancer Institute piloting VR consent modules for surgical trials.
Germany
Academic medical centers in Berlin and Heidelberg prioritize integrated platforms with procedural visualization capabilities for orthopedic and cardiovascular device studies. EMA harmonization of electronic consent validation requirements across member states reduces platform qualification duplication. The Charité Berlin network negotiates modular licensing terms that unbundle platform access from professional services.
United Kingdom
NHS Digital interoperability mandates accelerate EHR integration demand among London-based research institutions. GDPR cross-border data governance requirements complicate multinational trial consent workflows for UK-registered sponsors. The Oxford-Cambridge-London golden triangle concentrates deployment activity, with Oxford University Hospitals leading implementation of mobile-first consent for rural patient recruitment.
Netherlands
Academic centers in Amsterdam and Utrecht pilot virtual reality consent modules for interventional device trials under EMA-aligned regulatory frameworks. Dutch data protection authority guidance on algorithmic transparency shapes vendor selection for AI-enabled comprehension tools. The Leiden Bio Science Park hosts concentrated platform validation activity for European multinational studies.
India
CDSCO emerging frameworks for remote consent in domestic trials create penetration opportunity for platforms with multilingual interface capabilities. Contract research organizations in Hyderabad and Bangalore absorb cloud-based deployments to serve multinational sponsor portfolios. The Hyderabad life sciences cluster sees accelerating adoption as domestic biotechnology companies consolidate trial management under single platform instances.
Econsent in Healthcare Market Competitive Landscape
Capability concentration sits with cloud-native specialists; scale advantage sits with diversified clinical technology conglomerates. The vendor base stratifies across three tiers: enterprise platform providers with EHR integration depth, site-centric workflow specialists, and modular point-solution vendors. Dominant competitive moves include strategic partnerships with academic medical center networks and geographic expansion into emerging regulatory markets.
Within the enterprise tier, Veeva Systems and Medidata occupy positions as anchors for multinational pharmaceutical sponsor deployments. Florence Healthcare exemplifies the site-centric specialist archetype with concentrated penetration among academic medical centers. IQVIA represents the diversified conglomerate model, leveraging adjacent clinical services capabilities to bundle consent platform access within broader trial management relationships.
| Leading Market Players |
|---|
| Veeva Systems |
| Florence Healthcare |
| Signant Health |
| Advarra |
| IQVIA |
| Medidata |
| Clinical ink |
| Castor |
| Interlace Health |
| Others |
Value Network & Pricing Analysis
The Boston-Cambridge biotech corridor anchors cloud infrastructure capacity for eConsent platforms, with AWS and Azure data center proximity reducing latency costs that otherwise compress margins for decentralized trial deployments. This geographic concentration of cloud compute resources shapes downstream pricing power for platform vendors serving pharmaceutical sponsors.
Pricing Analysis
Long-term enterprise subscriptions dominate contract structures, with pharmaceutical sponsors locking in five-to-seven-year terms that bundle unlimited site onboarding and 24-hour support coverage. Three-tier pricing structure across premium, standard, and economy levels separates EHR-integrated deployments from standalone modules and mobile-only access. Cost compression in the mid-market tier is intensifying because contract research organizations face cybersecurity insurance premium pass-throughs. Academic medical centers exhibit highest price sensitivity due to federal funding constraints, while multinational sponsors absorb premium fees for compliance validation.
Supply Chain Analysis
Upstream feedstock for eConsent platforms centers on cloud infrastructure services, biometric authentication APIs, and FHIR-compliant interoperability modules sourced from the United States, Ireland, and Singapore. AWS GovCloud and Azure Government instances draw from domestic data center capacity to satisfy HIPAA technical safeguard requirements. Single-source vulnerability concentrates in proprietary EHR integration protocols for Epic and Cerner systems. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and channel partners serving academic medical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent bridging regulatory science, data engineering, and patient experience design remains chronically scarce, extending implementation timelines and inflating professional services costs for complex multi-site deployments. This capability gap defines competitive advantage in platform selection.
For Market Incumbents: Insulate enterprise relationships by deepening EHR integration partnerships with Epic and Cerner while accelerating AI-enabled comprehension tools that preempt EU AI Act compliance requirements. Vertical integration into professional services capabilities counters margin pressure from modular pricing demands by academic medical centers. Cloud-native architecture investments reinforce switching costs against site-centric workflow specialists. For New Entrants and Emerging Players: Establish a beachhead in India CDSCO digital trial pathways by prioritizing multilingual interface capabilities for domestic biotechnology sponsors consolidating trial management. White-space opportunity concentrates in mid-size contract research organizations seeking SaaS deployments with dedicated infrastructure isolation for HIPAA compliance. Go-to-market leverage rests on API-first architectures that respond to site demands for modular interoperability without custom integration work. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified clinical technology conglomerates seeking to rationalize non-core consent platform assets amid portfolio consolidation. Long-term viability favors vendors with interpretable machine learning architectures positioned for EU AI Act algorithmic transparency mandates. Signal to watch: CDSCO framework finalization for remote consent in domestic Indian trials as inflection indicator for geographic expansion returns.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep EHR connectivity with Epic and Cerner satisfies FDA inspection readiness requirements. |
| Regulatory Approval Pathway | EU AI Act compliance for algorithmic transparency creates first-mover positioning in Europe. |
| Geographic Expansion | India CDSCO framework penetration captures multilingual domestic trial growth. |
| Strategic Partnership | Academic medical center network alliances secure site-centric workflow dominance. |
| Product Launch | Virtual reality consent modules differentiate surgical and interventional trial offerings. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at pharmaceutical sponsors, clinical informatics directors at academic medical centers, platform engineers at cloud-native vendors, and procurement managers at contract research organizations and refined through secondary validation against FDA 21 CFR Part 11 guidance documents, EMA electronic consent validation frameworks, ClinicalTrials.gov registry data, and hospital procurement database trends. Bottom-up deployment estimates across product type, end user, and integration level segments were triangulated with top-down market sizing from cloud infrastructure spending disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning deployment architecture, product format, end-user type, and integration complexity. CAGRs were derived from elasticity modeling of sponsor technology budgets and site adoption curves. Industry-specific forecast inputs included decentralized trial penetration rates and EHR interoperability mandate timelines.
Macroeconomic conditions sit as an overlay; deviation in biotechnology venture funding cycles and cloud infrastructure pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory guidance stability and patient smartphone penetration trends. Cross-checking against hyperscaler healthcare vertical revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Occupational Therapy Software Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
Digital Health Tracking Apps Market