
 Digital Twins in Healthcare Market | 2026-2036
Digital Twins in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Twins in Healthcare Market Insights
The capital-intensity gap between cloud-native entrants and legacy device manufacturers is collapsing as platform economics favor scalable AI infrastructure over proprietary hardware stacks. Microsoft Corporation leverages its Azure cloud ecosystem to anchor hospital system deployments across North American and European networks. Siemens Healthineers sustains deep clinical integration through its imaging-to-simulation workflow, competing on regulatory pedigree rather than software velocity. Dassault Systèmes specializes in biomechanical modeling, dominating pharmaceutical research contracts with its Living Heart Project consortium.
Digital twins in healthcare are computational replicas of physiological systems, organs, or patient-specific anatomies that integrate real-time sensor data, medical imaging, and predictive algorithms to simulate biological behavior under varying clinical conditions. These systems employ finite element analysis, agent-based modeling, and machine learning inference to forecast disease progression, optimize therapeutic interventions, and reduce surgical risk. Cloud-based delivery mode now leads deployment preferences as hospitals seek elastic compute for intermittent simulation workloads without capital-intensive server farms. Predictive analytics applications are capturing the fastest expansion within the application dimension, driven by pharmaceutical companies deploying virtual patient cohorts to compress clinical trial timelines. AI technology within the technology stack sits at the center of margin concentration, since proprietary neural architectures for organ modeling create switching costs that standard simulation software cannot replicate.
FDA software-as-medical-device frameworks, EU MDR conformity requirements for AI-enabled diagnostics, and HIPAA security rule provisions collectively shape product development roadmaps and market access timelines for vendors seeking multi-territory deployment. EMA guidance on synthetic control arms in regulatory submissions is directly stimulating demand from European pharmaceutical sponsors building virtual patient populations for trial augmentation. Stakeholders must monitor evolving reimbursement pathways for digital twin-assisted procedures, as payer acceptance will determine whether hospital capital budgets or operational IT spending becomes the dominant procurement channel.
Market Dynamics
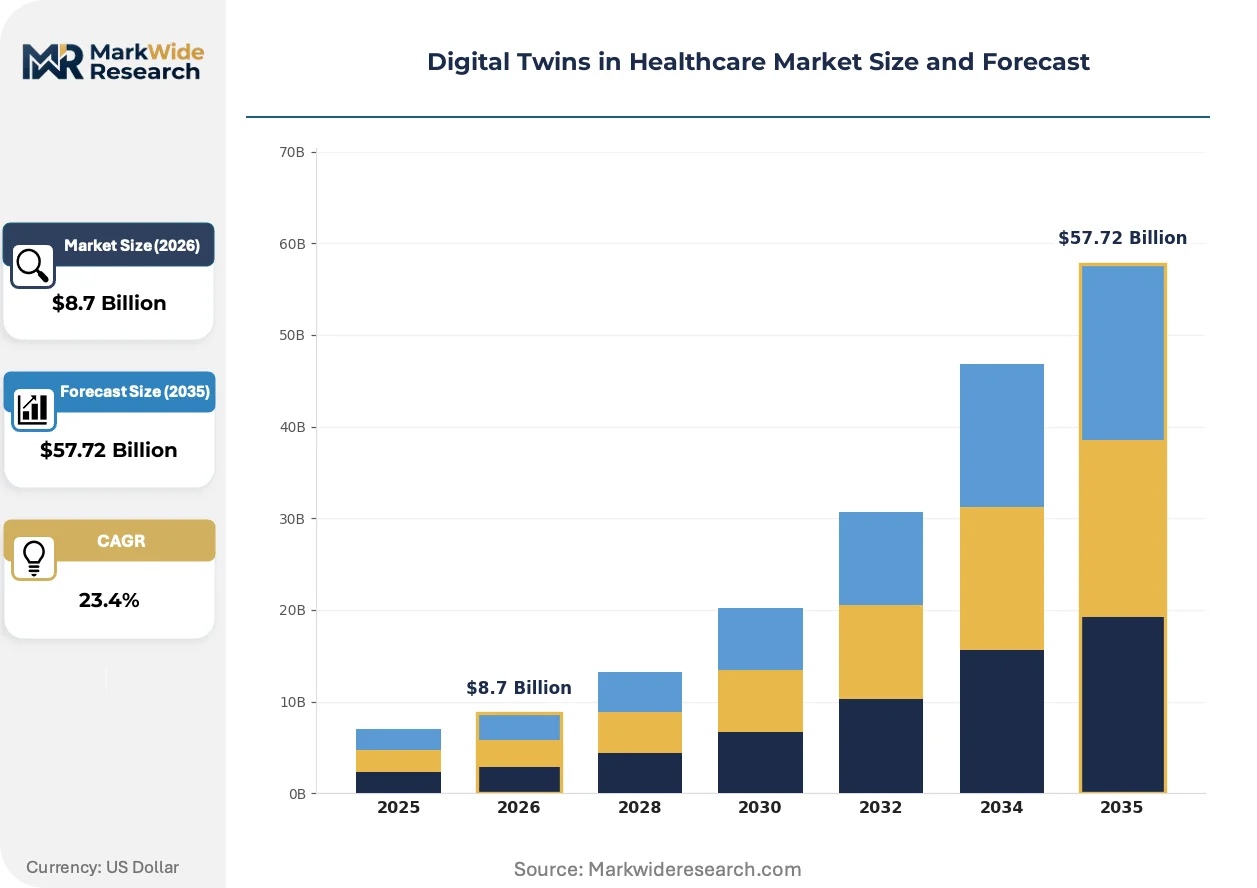
Platform economics are collapsing the capital-intensity gap between cloud-native entrants and legacy device manufacturers, favoring scalable AI infrastructure over proprietary hardware stacks in hospital system procurement decisions.
Growth Catalysts
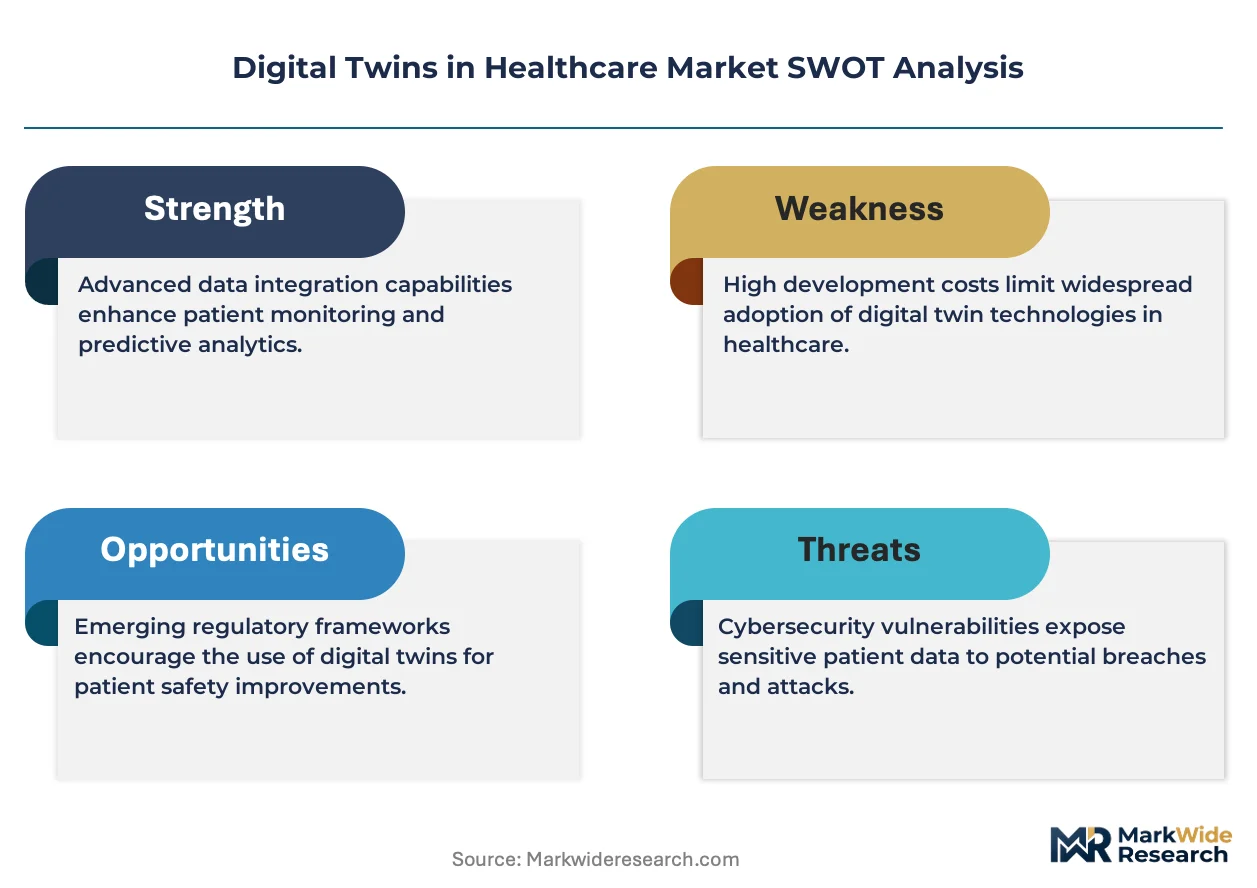
- FDA software-as-medical-device frameworks:The FDA's evolving guidance on AI-enabled medical devices accelerates validation requirements for clinical decision support tools, creating compliance-driven demand for integrated simulation platforms.
- EMA synthetic control arm guidance:European pharmaceutical sponsors are building virtual patient populations to augment regulatory submissions, directly stimulating demand for virtual trial infrastructure.
- Cloud-based delivery mode preference:Hospital systems seek elastic compute for intermittent simulation workloads without capital-intensive server farms, favoring vendors with mature cloud orchestration capabilities.
Market Restraints
- HIPAA security rule provisions:Multi-territory deployment requires complex data governance architectures that extend product development timelines and inflate compliance costs for cross-border patient data flows.
- Proprietary neural architecture switching costs:AI technology concentration creates vendor lock-in effects that hospital procurement committees resist, slowing enterprise-wide platform consolidation.
- EU MDR conformity requirements:AI-enabled diagnostic modules face extended certification cycles that compress software release velocity relative to unregulated health IT applications.
Strategic Opportunities
- Underpenetrated German hospital networks:Siemens Healthineers and university hospital consortia are building organ-specific simulation platforms, creating anchor demand for biomechanical modeling partnerships.
- Pharmaceutical virtual patient cohorts:Predictive analytics applications are capturing expansion within trial design, compressing clinical timelines through synthetic population deployment.
- Reimbursement pathway evolution:Payer acceptance of digital twin-assisted procedures will determine whether hospital capital budgets or operational IT spending becomes the dominant procurement channel.
Industry Challenges
- Finite element analysis talent scarcity:The intersection of biomedical engineering and computational physics requires specialized expertise that academic pipelines are not producing at sufficient scale.
- Legacy imaging system integration:PACS and EMR interoperability demands create implementation friction that extends deployment timelines and inflates professional services requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Twins in Healthcare Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $57.72 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AI, Machine Learning, Simulation Software, Cloud Computing End User: Hospitals, Clinics, Research Institutes, Pharmaceutical Companies Application: Patient Monitoring, Predictive Analytics, Surgical Planning, Personalized Medicine Delivery Mode: On-Premises, Cloud-Based, Hybrid, Software as a Service |
| Companies Covered | Microsoft Corporation, Siemens Healthineers AG, Oracle Corporation, Dassault Systèmes, GE Healthcare, IBM, Koninklijke Philips N.V., Twin Health, Unlearn AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Twins in Healthcare Market Trends and Innovations
Agent-based modeling combined with real-time sensor fusion is actively reshaping how physiological systems are simulated, compressing the gap between predictive accuracy and clinical deployment velocity.
Cloud-native finite element analysis is supplanting on-premise simulation clusters in hospital IT architectures. Academic medical centers in the United States and Germany are migrating organ-specific workloads to elastic infrastructure. This shift is enabling smaller community hospitals to access surgical planning capabilities previously restricted to tier-one research institutions.
EU MDR conformity requirements for AI-enabled diagnostics are mandating post-market surveillance mechanisms that software vendors must architect into product roadmaps. The regulation forces continuous validation pipelines rather than point-in-time certification. European pharmaceutical sponsors building virtual patient populations are investing most heavily in audit-ready simulation traceability.
Hospital procurement committees are unbundling after-sales service from perpetual software licenses, favoring consumption-based pricing tied to simulation runtime or patient case volume. This compresses upfront capital requirements while shifting vendor revenue recognition patterns. The model is most visible in North American health system deployments where operating budget flexibility exceeds capital allocation authority.
Digital Twins in Healthcare Market Segmentation
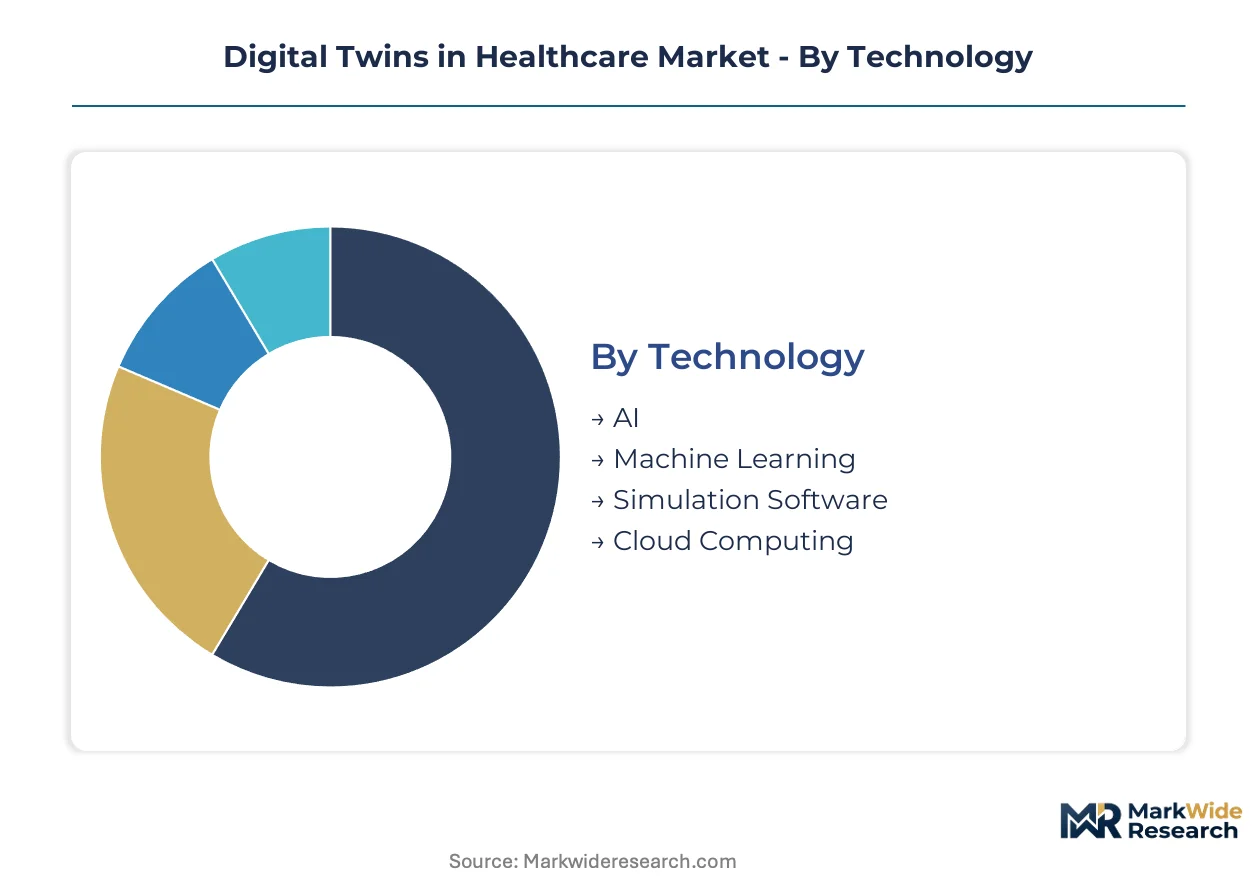
Segmentation in digital twins healthcare reveals distinct procurement patterns across technology stacks, end-user workflows, and delivery architectures. Each dimension carries unique margin profiles and regulatory compliance burdens that shape vendor go-to-market strategies.
Technology:
AI and machine learning modules flow through enterprise software licensing channels, while simulation platforms and cloud infrastructure increasingly route through consumption-based subscription models.
- AI:Neural architectures for organ modeling create proprietary switching costs that hospital procurement committees resist. Siemens Healthineers and Microsoft Azure anchor hospital system deployments across Germany and the United States with integrated inference pipelines.
- Machine Learning:Predictive algorithms for disease progression forecasting compress clinical trial timelines for pharmaceutical sponsors. EMA synthetic control arm guidance directly stimulates demand from European research consortia building virtual patient populations.
- Simulation Software:Finite element analysis tools for biomechanical modeling dominate pharmaceutical research contracts.
- Cloud Computing:Elastic compute infrastructure enables intermittent simulation workloads without capital-intensive server farms.
AI dominates installed base through embedded clinical decision support. Machine learning is where expansion concentrates for trial augmentation applications.
End User:
Cost tier stratification separates capital-budget hospital deployments from operational-budget research institute subscriptions, with pharmaceutical companies commanding premium pricing for regulatory-grade simulation traceability.
- Hospitals:Tier-one academic medical centers in the United States and Germany migrate organ-specific workloads to cloud-native finite element analysis. Community hospitals access surgical planning capabilities previously restricted to research institutions through elastic infrastructure.
- Pharmaceutical Companies:Virtual patient cohort deployment compresses clinical trial timelines. FDA software-as-medical-device frameworks accelerate validation requirements for integrated simulation platforms used in regulatory submissions.
- Research Institutes:University hospital networks build organ-specific simulation platforms with biomechanical modeling partnerships.
- Clinics:Smaller facilities lag in adoption due to PACS and EMR interoperability friction.
Hospitals anchor procurement volume through enterprise licensing. Pharmaceutical companies represent the steepest expansion trajectory as synthetic trial infrastructure demand accelerates.
Application:
Volume concentration clusters around predictive analytics for pharmaceutical sponsors, while surgical planning generates premium per-case pricing from hospital capital budgets.
- Predictive Analytics:Virtual patient populations enable trial augmentation with synthetic control arms. European pharmaceutical sponsors invest heavily in audit-ready simulation traceability to satisfy EU MDR post-market surveillance requirements.
- Surgical Planning:Patient-specific anatomical modeling reduces operative risk through pre-procedure simulation. United States hospital systems expand virtual patient modeling capabilities for complex interventions.
- Patient Monitoring:Real-time sensor fusion with agent-based modeling reshapes physiological system simulation.
- Personalized Medicine:Therapeutic optimization through individual patient replicas remains nascent but climbing.
Predictive analytics dominates revenue concentration through pharmaceutical contracts. Surgical planning is where hospital procurement committees unbundle perpetual licenses in favor of consumption-based pricing.
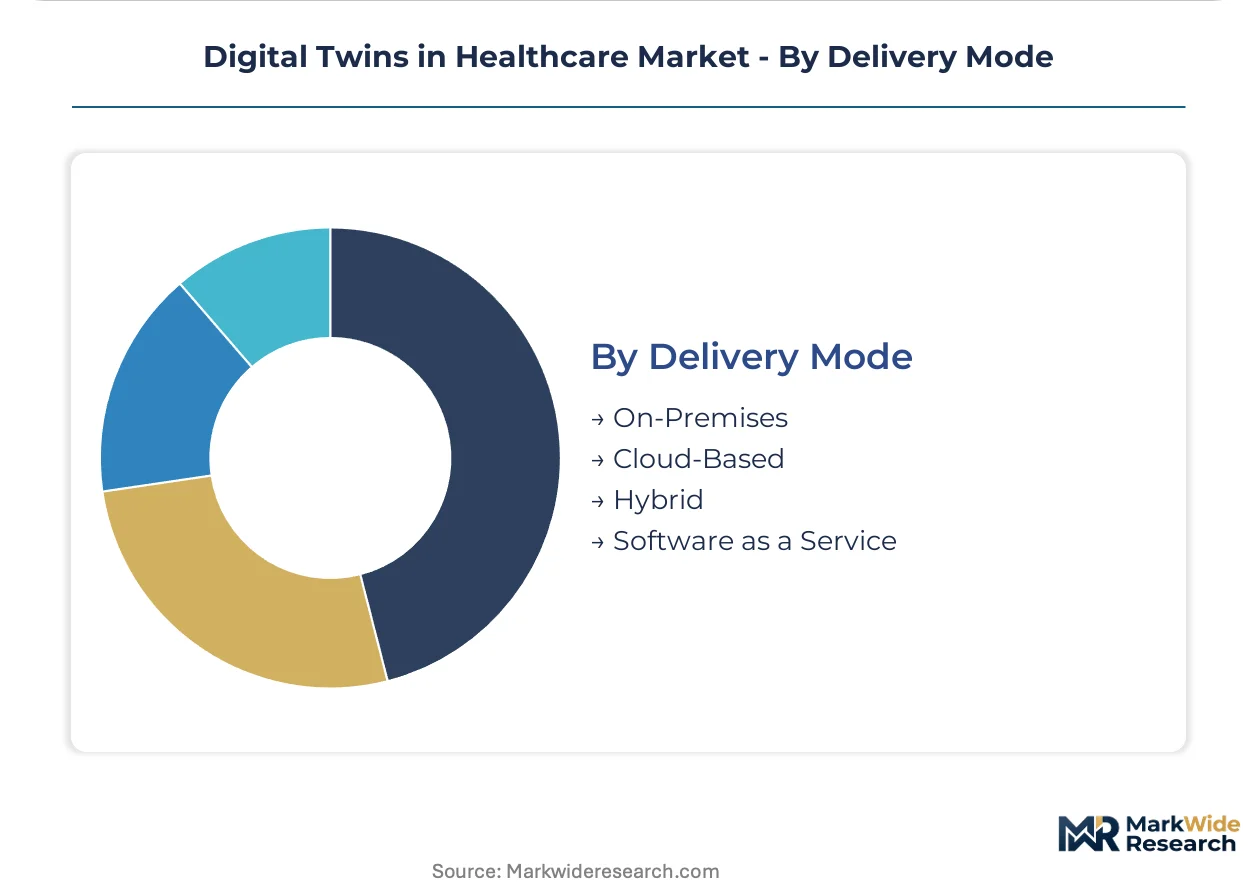
Delivery Mode:
Customer type determines deployment architecture, with research-intensive end-users favoring hybrid models that preserve on-premise data sovereignty while bursting to cloud for compute-intensive simulations.
- Cloud-Based:Elastic infrastructure enables smaller institutions to access capabilities previously restricted to tier-one research centers. Hospital procurement committees favor consumption-based pricing tied to simulation runtime or patient case volume.
- Software as a Service:Subscription models compress upfront capital requirements while shifting vendor revenue recognition patterns. North American health system deployments show operating budget flexibility exceeding capital allocation authority.
- Hybrid:Mixed architectures satisfy HIPAA security rule provisions for cross-border patient data flows.
- On-Premises:Legacy installations persist in facilities with strict data residency requirements.
Cloud-based delivery dominates new procurement preference. Software as a service is where pricing model innovation concentrates as vendors respond to hospital budget constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany demonstrate the lowest price elasticity, accepting premium licensing for regulatory-grade simulation traceability, while community health systems in India and Southeast Asia prioritize consumption-based cloud models that minimize upfront capital outlays.
United States
Academic medical centers in Boston and Stanford drive surgical planning adoption through NIH-funded research consortia. FDA software-as-medical-device frameworks accelerate validation pipelines for clinical decision support tools. The Cleveland Clinic and Mayo Clinic anchor organ-specific simulation development for cardiac and neurological interventions.
Germany
Siemens Healthineers and university hospital networks in Munich and Heidelberg build biomechanical modeling platforms for regulatory submissions. EU MDR conformity requirements mandate post-market surveillance mechanisms with continuous validation pipelines. The Rhine-Main cluster concentrates pharmaceutical sponsors investing in audit-ready virtual patient populations.
United Kingdom
NHS England's digital transformation programs fund cloud-native finite element analysis for tier-one teaching hospitals. MHRA alignment with FDA guidance on AI-enabled devices streamlines multi-territory product registrations. The Cambridge-Oxford-London triangle anchors pharmaceutical research contracts for synthetic control arm deployment.
China
NMPA regulatory pathways for AI diagnostics stimulate domestic software validation capabilities in Shanghai and Beijing. Hospital groups in the Yangtze River Delta pilot patient-specific anatomical modeling for orthopedic surgery. Government-backed health technology funds prioritize elastic compute infrastructure over proprietary hardware procurement.
Japan
PMDA consultation procedures for software-as-medical-device products compress time-to-market for simulation platforms. METI industrial policy supports digital twin integration in medical device manufacturing supply chains. The Kansai region's medical device cluster partners with academic medical centers in Osaka for surgical planning validation studies.
Digital Twins in Healthcare Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cloud-native entrants capturing elastic compute contracts while legacy device manufacturers defend installed-base relationships through imaging-to-simulation workflow integration. The market structure separates into three strategic tiers: hyperscale cloud platforms with hospital system anchoring capabilities, medical technology incumbents with regulatory pedigree, and specialized biomechanical modeling firms with pharmaceutical research concentration. Dominant competitive moves include strategic partnerships between cloud infrastructure providers and academic medical centers, plus portfolio diversification into consumption-based pricing models that shift revenue recognition from perpetual licenses to runtime-based subscriptions.
Among the technology-provider tier, Microsoft Corporation and Oracle Corporation anchor enterprise software licensing channels with cloud orchestration capabilities that hospital procurement committees favor for intermittent simulation workloads. Siemens Healthineers AG occupies a distinct position bridging imaging hardware and simulation software through regulatory-compliant workflow integration. Dassault Systèmes exemplifies the specialized modeling archetype, anchoring pharmaceutical research contracts through consortium-based biomechanical platforms. These three player types represent the competitive fault lines: cloud scale versus clinical integration depth versus research-specialized simulation accuracy.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Siemens Healthineers AG |
| Oracle Corporation |
| Dassault Systèmes |
| GE Healthcare |
| IBM |
| Koninklijke Philips N.V. |
| Twin Health |
| Unlearn AI |
| Others |
Pricing and Supply Chain Analysis
FDA software-as-medical-device frameworks gate both supplier qualification and price differentiation, forcing vendors to embed continuous validation costs into subscription tiers while hospital procurement committees unbundle perpetual licenses in favor of consumption-based models. This regulatory threshold simultaneously filters out undercapitalized entrants and segments pricing power between regulatory-grade simulation platforms and unvalidated health IT tools.
Pricing Analysis
After-sales service revenue from extended validation contracts and continuous compliance monitoring drives lifetime value for established vendors. Consumption-based pricing tied to simulation runtime or patient case volume now dominates hospital procurement, compressing upfront capital requirements while shifting vendor revenue recognition patterns. Price differentiation stems from FDA regulatory pedigree and cloud orchestration maturity, with tier-one academic medical centers showing lowest price sensitivity for audit-ready traceability while community hospitals prioritize elastic infrastructure with minimal fixed costs. Cost compression in mid-tier simulation software is intensifying because cloud-native entrants are collapsing the capital-intensity gap through scalable AI infrastructure.
Supply Chain Analysis
Inventory lead times for specialized GPU clusters and biomedical engineering talent extend deployment timelines for organ-specific simulation platforms. Software development concentrates in the United States, Germany, and China, with cloud infrastructure provisioning anchored in hyperscale data centers across North America and Western Europe. The supply chain draws from finite element analysis expertise, medical imaging hardware, and proprietary neural architectures, with single-source vulnerability concentrated in specialized computational physics talent pools. Distribution runs through enterprise software licensing channels for AI modules and subscription-based orchestration for cloud infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA guidance on AI-enabled medical devices creates a high-growth disruption window as validation requirements accelerate software-as-medical-device frameworks and compress time-to-market for compliant platforms.
For Market Incumbents: Compound regulatory pedigree advantages by deepening imaging-to-simulation workflow integration and securing continuous validation pipeline contracts with tier-one academic medical centers. Defend against cloud-native entrants through backward integration into proprietary neural architectures for organ modeling that create switching costs hospital procurement committees cannot easily replicate. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for AI-enabled diagnostics offer the most penetrable entry point for virtual patient cohort platforms targeting pharmaceutical sponsors. White-space concentration sits in community hospital networks seeking surgical planning capabilities through elastic cloud infrastructure without capital-intensive server farms. Go-to-market traction requires consumption-based pricing models that align with hospital operating budget flexibility. For Investors and Strategic Acquirers: EMA synthetic control arm guidance reshapes the acquisition landscape by elevating virtual trial infrastructure to regulatory-critical status across European pharmaceutical sponsors. Long-term viability favors specialized biomechanical modeling firms with pharmaceutical research concentration and audit-ready simulation traceability. The signal to monitor is payer reimbursement pathway evolution for digital twin-assisted procedures, which will determine whether hospital capital budgets or operational IT spending becomes the dominant procurement channel.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates validation pipelines for clinical decision support tools across hospital system deployments. |
| CE Marking Pathway for AI Diagnostics | Unlocks European market access through EU MDR conformity for post-market surveillance mechanisms. |
| Hospital System Partnership | Anchors enterprise licensing through imaging-to-simulation workflow integration with academic medical centers. |
| Software Companion Development | Enables consumption-based pricing models tied to simulation runtime or patient case volume. |
| Reimbursement Strategy | Determines procurement channel dominance between hospital capital budgets and operational IT spending. |
Research Methodology
Cross-validation between primary interviews with hospital procurement committees, biomedical engineers, and pharmaceutical regulatory affairs leads and secondary sources including FDA filings, EMA submissions, and hospital procurement databases anchors the qualitative findings. Bottom-up triangulation incorporates GPO contracts and CMS Medicare data for demand-side validation, while top-down analysis draws from hyperscaler capex disclosures and clinical trial registry entries. This dual approach ensures segmentation integrity across technology stacks, end-user workflows, and delivery architectures.
Sensitivity analysis frames the analytical approach across the projection horizon, with CAGRs derived from modeled interactions between AI technology penetration, cloud infrastructure adoption curves, and regulatory compliance timelines. Segmentation dimensions include technology modality, end-user cost tier, application workflow, and regional regulatory cluster. Forecast inputs incorporate pharmaceutical sponsor investment patterns in virtual patient populations and hospital capital budget allocation shifts toward operational IT spending.
Underlying assumptions cover continuous validation pipeline maturation and payer reimbursement pathway evolution, with deviation risk concentrated in FDA guidance timeline adjustments and EU MDR certification cycle extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
Global Patient Engagement Solution Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Mobile Tablets in Healthcare Market