
 Telepsychiatry Software Market | 2026-2036
Telepsychiatry Software Market Size, Share, and Industry Trends Forecast 2026-2036
Telepsychiatry Software Market Insights
Direct-to-consumer digital channels is narrowing as telehealth providers consolidate around employer and payer contracts. Teladoc Health leverages its hybrid care model to anchor enterprise accounts across multiple states. Amwell sustains competitive positioning through payer partnerships that embed its platform into existing benefit structures. Doxy.me specializes in lightweight, browser-first delivery that dominates small private practices with minimal IT overhead.
Telepsychiatry software encompasses secure video conferencing, clinical documentation, e-prescribing, and patient scheduling systems purpose-built for remote mental health delivery, typically requiring end-to-end encryption and HIPAA-compliant data architecture to protect sensitive psychiatric records. The application dimension shows behavioral health and substance abuse management outpacing traditional psychiatric segments as integrated care models expand reimbursement for comorbidity treatment. Cloud-based solutions lead the delivery mode category by margin pool, though hybrid models are gaining fastest among health systems seeking workflow continuity between virtual and in-person encounters.
FDA oversight of clinical decision support tools, DEA regulations on controlled substance prescribing via telemedicine, and state-level telehealth parity laws collectively shape platform design and market access requirements across the United States. CMS reimbursement rules determine whether providers can bill for remote psychiatric sessions at rates comparable to in-office visits, directly influencing software procurement cycles. Stakeholders must monitor how the DEA finalizes post-public health emergency prescribing flexibilities, as this single regulatory pivot will either expand or constrict the addressable market for platforms serving patients with severe mental illness requiring medication management.
Market Dynamics
DEA prescribing rule uncertainty is compressing platform development cycles as vendors race to architect compliance frameworks before controlled substance flexibilities expire. This regulatory overhang forces simultaneous investment in multiple technical pathways.
Growth Catalysts
- CMS Reimbursement Parity:Medicare payment equivalence between virtual and in-person psychiatric visits sustains provider revenue models and software procurement budgets across United States health systems.
- Behavioral Health Integration:Value-based care contracts embedding mental health into primary care workflows expand addressable seats for telepsychiatry platforms serving comorbid populations.
- Rural Hospital Closures:Workforce evacuation from non-urban counties accelerates remote care mandates, forcing community health centers toward browser-based psychiatric delivery systems.
Market Restraints
- DEA Registration Complexity:Separate controlled substance prescribing credentials for each state create compliance cost escalators for multi-state platform deployments.
- Cloud Infrastructure Concentration:AWS, Microsoft Azure, and Google Cloud dominate HIPAA-eligible hosting, creating vendor lock-in risk and pricing power asymmetry for independent software vendors.
- Reimbursement Rate Compression:Commercial payers in certain states enforce site-of-service differentials that undercut parity laws and constrain provider willingness to invest in dedicated telepsychiatry tools.
Strategic Opportunities
- Substance Use Disorder Expansion:Medication-assisted treatment for opioid use disorder represents an underpenetrated application where DEA flexibilities temporarily lower regulatory barriers to entry.
- AI-Assisted Documentation:Convergence of ambient clinical intelligence with psychiatric note templates promises to compress documentation burden and extend clinician daily capacity.
- Correctional Health Penetration:State prison systems and county jails present a channel innovation opportunity where remote psychiatric evaluation addresses severe specialist shortages.
Industry Challenges
- Cross-State Licensure Bottlenecks:Interstate Medical Licensure Compact adoption remains uneven, forcing platforms to maintain complex credential verification workflows that delay provider onboarding.
- EHR Integration Friction:Legacy psychiatric record systems from vendors like Cerner and Epic require costly custom API development to achieve seamless virtual visit documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telepsychiatry Software Market |
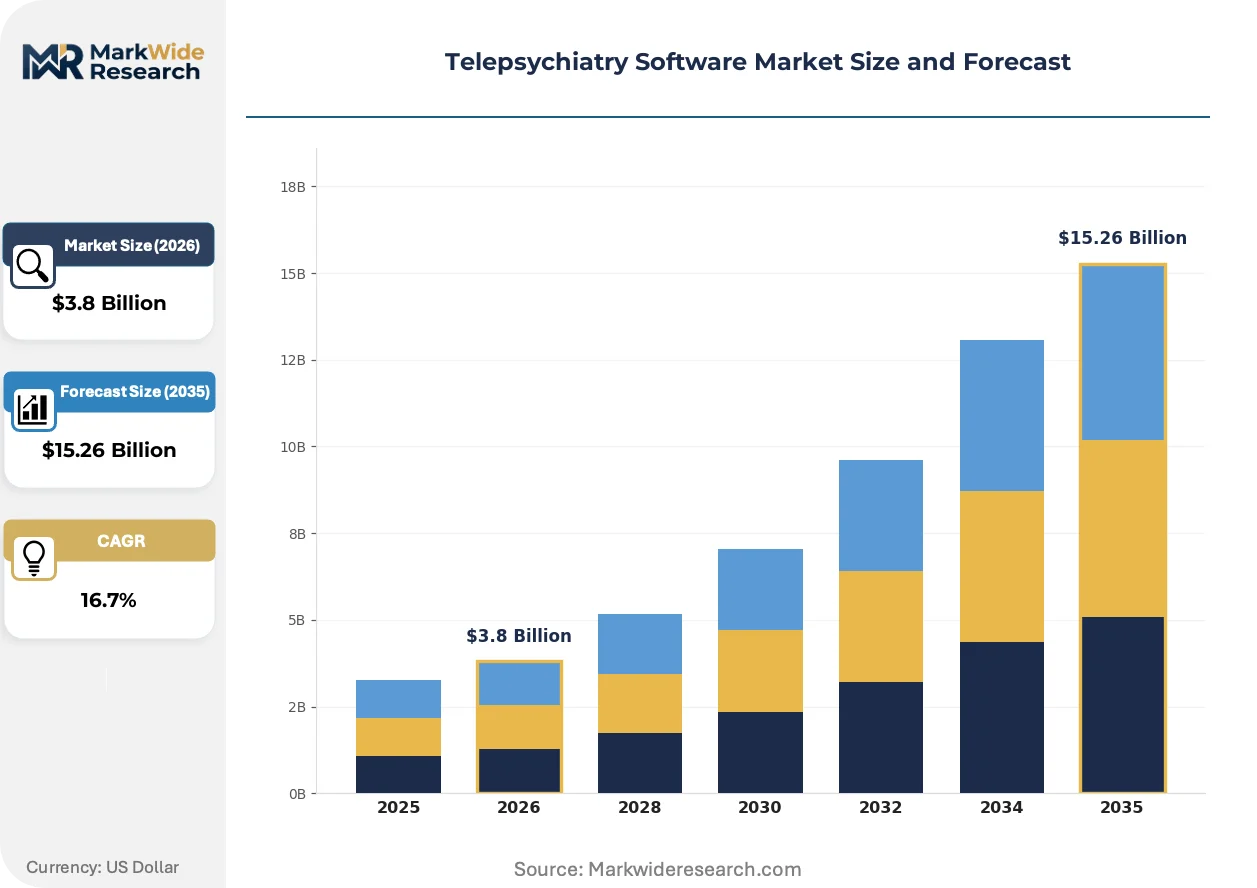
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-demand Services, Subscription Services, Hybrid Models, Licensed Software Delivery Mode: Web-based Platforms, Mobile Applications, Cloud-based Solutions, Desktop Applications End User: Clinics, Hospitals, Private Practices, Telehealth Providers Application: Adult Psychiatry, Pediatric Psychiatry, Behavioral Health, Substance Abuse Management |
| Companies Covered | Teladoc Health, Amwell, BetterHelp, Cerebral, Included Health, Doxy.me, Doctor On Demand, PlushCare, HealthTap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telepsychiatry Software Market Trends and Innovations
Platform architecture is pivoting toward ambient intelligence and automated clinical documentation as psychiatric workforce constraints intensify. Vendors are embedding AI layers that reduce administrative burden rather than merely replicating video connectivity.
Browser-native WebRTC infrastructure is collapsing the distinction between lightweight consumer-grade tools and enterprise telehealth platforms. Small private practices now access encryption and workflow features previously reserved for health system contracts. This compression erodes the traditional segmentation between Doxy.me's minimal-overhead model and Amwell's payer-embedded deployments. The technical barrier to enterprise-grade psychiatric delivery has fallen below five hundred dollars monthly.
DEA telemedicine prescribing rules are reshaping platform compliance roadmaps as the agency weighs permanent flexibilities against return to in-person examination requirements. Controlled substance prescribing represents thirty percent of psychiatric medication volume, making this regulatory pivot existential for platforms serving severe mental illness populations. Vendors are architecting dual-track systems that accommodate either regulatory outcome without core platform reconstruction.
Employer-sponsored mental health benefits are consolidating purchasing power around integrated employee assistance programs that bundle telepsychiatry with coaching and crisis support. This channel rotation displaces direct-to-consumer marketing as the primary patient acquisition pathway. Large self-insured employers in Texas and California now mandate platform participation through their benefits administrators, compressing independent provider choice.
Telepsychiatry Software Market Segmentation
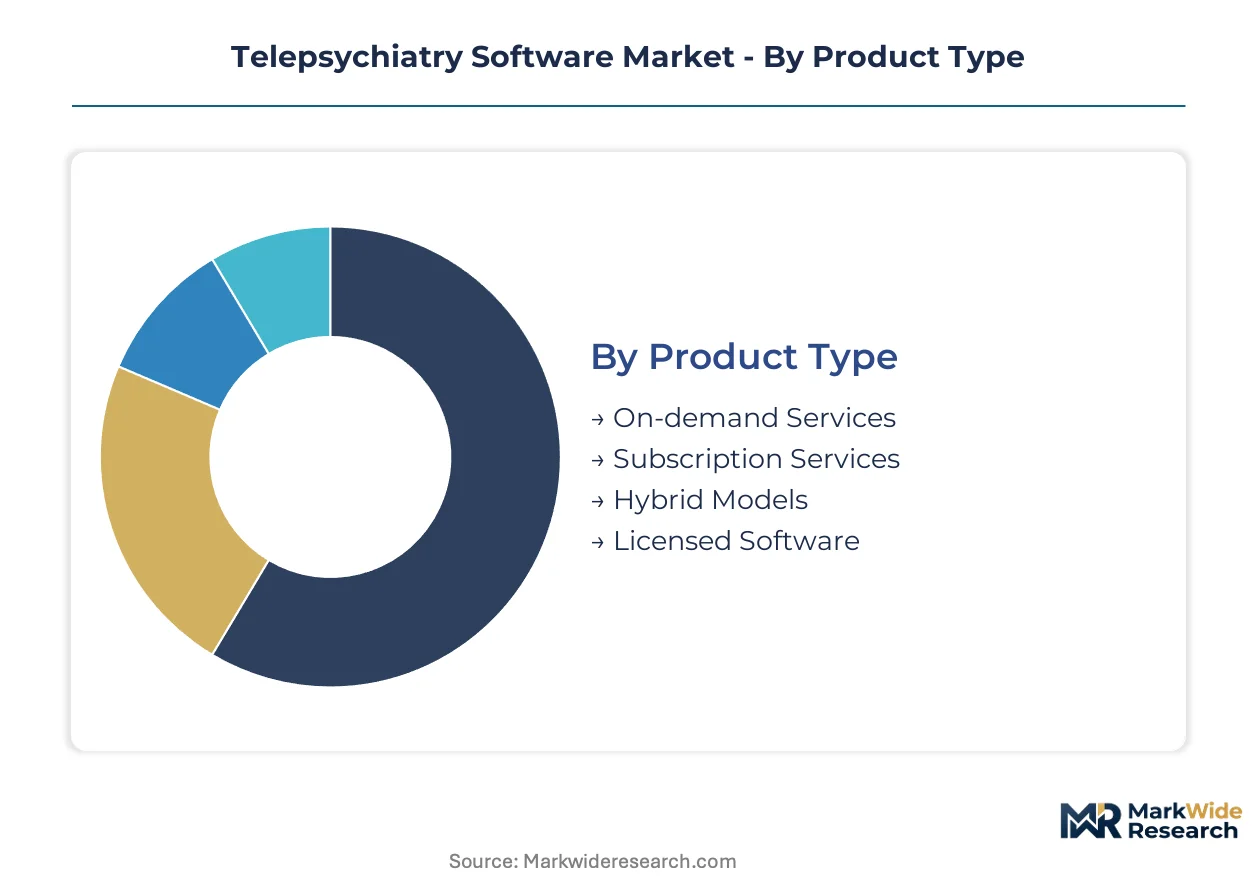
Telepsychiatry software segmentation reveals how procurement patterns split between capital-intensive health system deployments and lightweight independent practice solutions. Vendor product strategy must align with these divergent technical requirements and budget cycles.
Product Type:
Use-case spectrum spans episodic crisis intervention through longitudinal medication management, with payment models adapting to clinical relationship duration.
- On-demand Services:Pay-per-consultation platforms deliver immediate psychiatric assessment for urgent stabilization without subscription overhead. Crisis response teams in hospital emergency departments and employer assistance programs drive procurement for same-day access.
- Subscription Services:Recurring revenue models bundle unlimited visits, care coordination tools, and outcome analytics for sustained therapeutic relationships. Large telehealth providers and integrated health systems favor this structure for predictable budgeting across multi-month treatment protocols.
- Hybrid Models:Blended fee structures combine base platform access with per-encounter surcharges for specialized services.
- Licensed Software:Perpetual license purchases with maintenance contracts appeal to institutional IT departments seeking asset ownership.
The dominant share belongs to Subscription Services, while Hybrid Models is closing the gap fastest.
Delivery Mode:
Technical architecture choices concentrate around infrastructure ownership tradeoffs and endpoint accessibility requirements.
- Cloud-based Solutions:Multi-tenant SaaS architectures eliminate server maintenance burden while ensuring automatic security patching and HIPAA-compliant data residency. Health systems undergoing EHR consolidation prioritize these deployments for interoperability with Epic and Cerner environments.
- Web-based Platforms:Browser-native WebRTC implementations remove app store friction and device compatibility constraints. Rural community health centers and correctional facilities select this modality for lowest-barrier patient access across shared workstation environments.
- Mobile Applications:Native iOS and Android clients support asynchronous messaging and push notification adherence reminders.
- Desktop Applications:Installed software persists in high-security environments requiring local data processing.
Cloud-based Solutions commands procurement volume leadership, though Web-based Platforms expands most quickly among budget-constrained providers.
End User:
Customer type segmentation maps to organizational scale, regulatory exposure, and integration complexity tolerance.
- Telehealth Providers:Pure-play virtual care organizations require white-label customization, multi-state licensure workflows, and payer-agnostic billing engines. Teladoc Health and Amwell anchor this segment with enterprise-grade compliance frameworks.
- Hospitals:Acute care systems demand seamless EHR integration, inpatient-to-outpatient care transitions, and 24/7 coverage guarantees for emergency psychiatric consultation.
- Clinics:Federally qualified health centers and community mental health agencies prioritize Medicaid billing automation and sliding-fee scale management.
- Private Practices:Solo and small-group psychiatrists select minimal-overhead solutions with browser-first delivery and self-service onboarding.
Telehealth Providers holds the dominant position, while Hospitals shows steepest expansion trajectory as health systems embed virtual psychiatry into primary care networks.
Application:
Clinical specialty segmentation tracks reimbursement policy divergence and workforce availability gaps across patient populations.
- Behavioral Health:Integrated care platforms addressing anxiety, depression, and trauma-related disorders within primary care workflows. Value-based contracts in California and Texas health systems accelerate deployment for comorbidity management.
- Substance Abuse Management:Medication-assisted treatment coordination for opioid and alcohol use disorders, where DEA prescribing flexibilities temporarily expand telemedicine eligibility. State Medicaid programs in rural counties drive procurement for buprenorphine initiation and monitoring.
- Adult Psychiatry:General psychiatric medication management and psychotherapy for patients over 18.
- Pediatric Psychiatry:Developmental assessment and family-centered intervention for children and adolescents.
Behavioral Health retains the dominant share, while Substance Abuse Management climbs fastest as regulatory flexibilities open new reimbursement pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate Highway System and fiber-optic backbone density anchor North American telepsychiatry infrastructure, while undersea cable landing stations in Western Europe and Asia-Pacific cloud regions enable cross-border data flows for remote mental health delivery.
United States
Rural hospital closures in Appalachia and the Great Plains drive procurement of browser-based psychiatric platforms. CMS reimbursement parity policies sustain provider revenue models across Medicare Advantage networks. The Dallas-Fort Worth metroplex hosts multiple telehealth operations centers serving multi-state provider networks.
Germany
Digital Health Act (DVG) reimbursement pathways for video consultations expand addressable seats for psychiatric platforms. BfArM fast-track approval processes accelerate market entry for clinical decision support modules. Berlin's health tech cluster concentrates vendor development activity for EU market localization.
United Kingdom
NHS Long Term Plan commitments to mental health workforce expansion create procurement pull for remote consultation tools. MHRA guidance on software as medical device classification shapes platform compliance architecture. London's NHS trusts pilot integrated telepsychiatry within primary care networks across the capital.
India
Telemedicine Practice Guidelines issued by the national medical commission legitimize cross-state psychiatric consultations. NITI Aayog's digital health mission funds rural connectivity infrastructure for remote care delivery. Bengaluru's health tech ecosystem hosts platform development for domestic and export markets.
Canada
Provincial telehealth reimbursement frameworks in Ontario and British Columbia sustain provider adoption of virtual psychiatric tools. Health Canada oversight of medical device software influences platform security architecture design. Toronto's hospital networks anchor multi-province telepsychiatry service delivery models.
Telepsychiatry Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying encryption modules, EHR connectors, and ambient documentation engines. The vendor base stratifies between enterprise-grade health system deployments and lightweight independent practice solutions. Three archetypes dominate: payer-embedded platforms, browser-native minimalists, and hybrid care orchestrators. Consolidation pressure intensifies as enterprise contracts demand end-to-end workflow integration, while strategic partnerships between telehealth vendors and EHR incumbents reshape competitive boundaries.
Within the payer-embedded tier, Teladoc Health and Amwell occupy positions anchoring enterprise accounts across multiple states. Doxy.me exemplifies the browser-native minimalist archetype, serving small private practices with reduced IT overhead requirements. These three entities collectively represent the strategic positioning spectrum—from capital-intensive health system integration to frictionless independent provider onboarding—that defines current competitive dynamics.
| Leading Market Players |
|---|
| Teladoc Health |
| Amwell |
| BetterHelp |
| Cerebral |
| Included Health |
| Doxy.me |
| Doctor On Demand |
| PlushCare |
| HealthTap |
| Others |
Pricing and Supply Chain Analysis
Bengaluru's health tech cluster concentrates platform development capacity for telepsychiatry software, with its engineering density creating downstream pricing leverage for SaaS vendors serving cost-sensitive rural health systems. This geographic concentration of technical talent shapes how subscription tiers compress toward browser-native delivery models.
Pricing Analysis
Volume-discount tiering structures separate enterprise health system deployments from independent practice subscriptions, with per-seat pricing stratifying across premium EHR-integrated tiers, standard cloud-hosted offerings, and economy browser-first solutions. Price differentiation hinges on HIPAA certification grade and customization depth for legacy system integration. Cost compression in the economy tier is intensifying because WebRTC infrastructure commoditizes encryption features previously reserved for premium contracts. Federally qualified health centers exhibit highest price sensitivity, while large telehealth providers demonstrate lowest due to bundled care coordination requirements.
Supply Chain Analysis
Contract manufacturing concentration for telepsychiatry infrastructure rests on AWS, Microsoft Azure, and Google Cloud as the dominant HIPAA-eligible hosting providers. Geographic supply concentration centers on the United States, Ireland, and Singapore for data residency compliance. Raw material dependencies include encryption module libraries, WebRTC protocol stacks, and API middleware for EHR connectivity. Single-source vulnerability in cloud infrastructure creates systemic risk for multi-tenant platform continuity. Distribution runs through direct enterprise sales teams for health systems and self-service web portals for independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telepsychiatry software fragmentation creates entry niches as DEA prescribing rule uncertainty splinters platform compliance architectures and rural workforce shortages fragment buyer procurement priorities.
For Market Incumbents: Build regulatory compliance moats by architecting dual-track systems accommodating both permanent DEA flexibilities and restored in-person examination requirements. Defensive consolidation should prioritize backward integration into ambient clinical intelligence engines to compress documentation burden. Threat substitution from AI-native documentation entrants demands capacity addition in Bengaluru and Berlin development clusters. For New Entrants and Emerging Players: Pursue correctional health and substance use disorder segments where specialist shortages and temporary DEA flexibilities lower competitive barriers. The most penetrable geography clusters in rural Appalachian and Great Plains counties facing hospital closures. Go-to-market execution should anchor on browser-native WebRTC delivery with Medicaid billing automation for community health centers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because CMS reimbursement parity and DEA prescribing rules determine platform viability more than technical differentiation. Acquisition targets should concentrate on ambient documentation specialists with psychiatric note templates. The signal to watch is final DEA rulemaking on controlled substance telemedicine flexibilities as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamless Epic and Cerner EHR embedding secures health system procurement contracts. |
| Strategic Partnership | Payer-embedded deployments through Medicare Advantage networks lock recurring revenue streams. |
| Acquisition of Specialist Firm | Ambient clinical intelligence engines extend clinician daily capacity for workforce-constrained systems. |
| Geographic Expansion | Multi-state licensure workflows unlock rural community health center procurement pipelines. |
| Reimbursement Strategy | Medicaid billing automation captures federally qualified health center subscription volume. |
Research Methodology
Operator-level perspectives from telehealth platform executives, psychiatric practice administrators, hospital IT procurement officers, and CMS reimbursement policy specialists anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, DEA registration databases, CMS Medicare cost reports, and state telehealth parity legislation trackers. Bottom-up deployment counts across delivery modes and end-user segments triangulated against top-down market sizing from payer contract disclosures and health system capital expenditure patterns.
Scenario-bracketing framed projections across the analysis window, modeling demand trajectories under alternative DEA regulatory outcomes. Segmentation dimensions spanned product type, delivery mode, end-user organization scale, application specialty, and regional reimbursement framework. CAGRs derived from logistic diffusion curves fitted to telehealth adoption benchmarks and workforce shortage severity indices. Forecast inputs incorporated rural hospital closure rates and Medicare Advantage telepsychiatry penetration assumptions.
Sensitivities concentrate around DEA final rule timing, CMS parity policy durability, and cloud infrastructure pricing volatility. Forecasts reflect assumptions on regulatory stability and reimbursement continuity without guarantee of policy persistence. Quarterly review of DEA rulemaking dockets, CMS physician fee schedule updates, and state telehealth mandate legislation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Behavioral Mental Health Care Software Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Care Coordination Software Market